
 Gas Holders Market | 2026-2036
Gas Holders Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Holders Market Foresight
Composite materials is decoupling gas holder construction from traditional steel-intensive fabrication, cutting capital costs and extending corrosion resistance in biogas and wastewater treatment environments. Linde plc leverages its industrial gas infrastructure footprint to anchor large-scale storage project deployments across European utility networks. Chart Industries, Inc. specializes in cryogenic and gas handling systems, competing aggressively in membrane gas holder technology for bioenergy applications. Wartsila operates across the biogas value chain, extending its energy storage engineering capabilities into biogas upgrading and containment solutions.
A gas holder is a sealed vessel engineered to store gaseous fuels at low pressure, typically constructed with steel plates, reinforced membranes, or composite shells rated for specific pressure thresholds and chemical resistance against hydrogen sulfide and moisture. Its primary industrial purpose is to buffer supply-demand imbalances in gas distribution networks and to contain biogas, landfill gas, or synthetic methane for subsequent treatment or grid injection. Membrane gas holders represent the fastest-growing product category, displacing hydraulic and spiral designs in new bioenergy plants due to lower foundation requirements and modular scalability. Among end users, biogas facilities and waste management firms command expanding capital allocation, while energy producers and gas distributors sustain the installed base of steel and concrete holders through retrofit cycles.
The EPA enforces methane emission standards under the Clean Air Act that compel landfill and wastewater operators to upgrade or replace leaking legacy containment, directly stimulating membrane gas holder procurement in the United States. EMA and national regulators across Europe enforce ATEX directives and F-Gas Regulation compliance for gas storage near populated areas, shaping material specifications and safety system designs. Stakeholders must monitor evolving biomethane injection standards and carbon intensity scoring mechanisms, as these frameworks will determine which storage technologies qualify for renewable energy certificates and green gas subsidies.
Market Dynamics
Membrane-based gas holder systems are compressing project timelines and foundation costs for biogas operators, displacing hydraulic and spiral steel designs that dominated municipal storage for decades. This material transition is redistributing competitive advantage toward composite fabrication specialists and away from traditional steel tank contractors.
Growth Catalysts
- EU Green Deal methane rules:Tightening emission thresholds under the EU Green Deal are compelling German and UK landfill operators to replace leaking legacy steel holders with sealed membrane systems.
- Biogas upgrading infrastructure:Renewable natural gas injection standards in India and Germany are mandating intermediate storage capacity between anaerobic digesters and grid connection points.
- Composite shell fabrication:Glass-reinforced polymer manufacturing is cutting gas holder weight by half, enabling rooftop and constrained-site installations previously impossible with steel construction.
Market Restraints
- Specialized membrane supply concentration:High-performance ethylene-propylene-diene monomer sheeting for biogas containment relies on a narrow base of European and Japanese chemical suppliers.
- Steel price volatility:Carbon steel plate costs for remaining hydraulic holder installations fluctuate with scrap metal and energy input prices, compressing margins for conventional fabricators.
- Concrete foundation requirements:Spiral-guided steel holders still demand extensive civil works that extend project payback periods beyond membrane alternatives.
Strategic Opportunities
- Indian municipal biogas expansion:Urban wastewater treatment plants in Maharashtra and Gujarat lack adequate gas containment for captured methane, creating first-mover openings for membrane system suppliers.
- Power-to-gas storage integration:Synthetic methane produced from electrolytic hydrogen requires flexible, low-pressure buffer storage that membrane holders provide at scale.
- Renewable natural gas incentive programs:California's LCFS and EU biomethane certificates reward carbon-negative gas production, directly subsidizing storage infrastructure at anaerobic digestion facilities.
Industry Challenges
- Membrane welding technician scarcity:Certified installers for large-diameter ethylene-propylene-diene monomer seams are concentrated in Germany and the Netherlands, creating project bottlenecks elsewhere.
- ATEX compliance documentation:European biogas operators face extended certification timelines for explosion protection documentation under ATEX directives, delaying commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Holders Market |
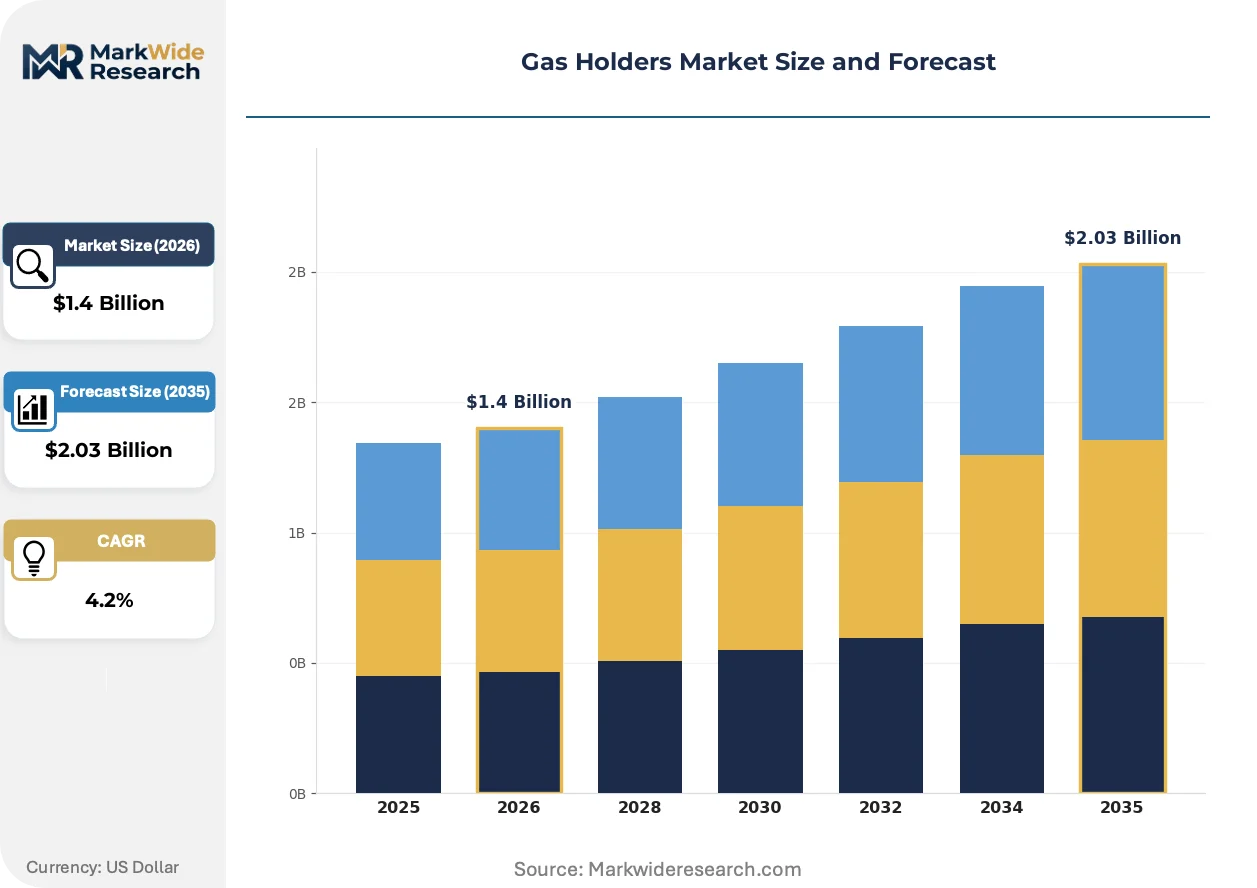
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Gas Holders, Spiral Gas Holders, Telescopic Gas Holders, Rectangular Gas Holders, Membrane Gas Holders Application: Municipal Gas Storage, Industrial Gas Storage, Bioenergy Plants, Landfill Gas Containment, Wastewater Treatment End User: Energy Producers, Gas Distributors, Utility Operators, Waste Management Firms, Biogas Facilities Technology: Steel Fabrication, Fabric Reinforced Membranes, Concrete Construction, Composite Materials, Automated Valve Systems |
| Companies Covered | Wartsila, Linde plc, Xebec Adsorption Inc., Chart Industries, Inc., Hitachi Zosen Corporation, Air Liquide, Air Products and Chemicals, Inc., Messer Group, Taiyo Nippon Sanso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Holders Market Shifts & Advancements
Active material science development is collapsing the performance gap between flexible membrane systems and rigid steel containment, while regulatory pressure on methane leaks accelerates replacement cycles. These forces are converging to reshape procurement criteria and supplier rankings across municipal and industrial gas storage.
Glass-reinforced thermoplastic composite shells are unifying corrosion resistance and structural rigidity in a single fabrication step, eliminating the separate coating and welding sequences required for steel holders. Wastewater treatment operators in Germany and the United Kingdom are specifying these systems for hydrogen sulfide-rich biogas environments. This unification of material functions is compressing supplier qualification timelines and enabling smaller fabricators to compete with established tank contractors.
The EPA's Clean Air Act methane emission standards are forcing US landfill operators to upgrade or replace legacy containment infrastructure that fails leak detection thresholds. Industrial consequence includes accelerated procurement of membrane-based replacement systems that seal more completely than aging hydraulic holders. California and Texas landfill gas capture facilities are responding with compressed project schedules to meet compliance deadlines.
Biogas plant operators are consolidating procurement decisions under specialized EPC contractors rather than fragmenting purchases across civil, mechanical, and electrical vendors. This concentration is displacing direct equipment sales from holder manufacturers to turnkey project integrators. The shift is most visible in German agricultural biogas clusters, where farmer cooperatives now contract complete storage-to-grid solutions rather than specifying components separately.
Gas Holders Market Segmentation
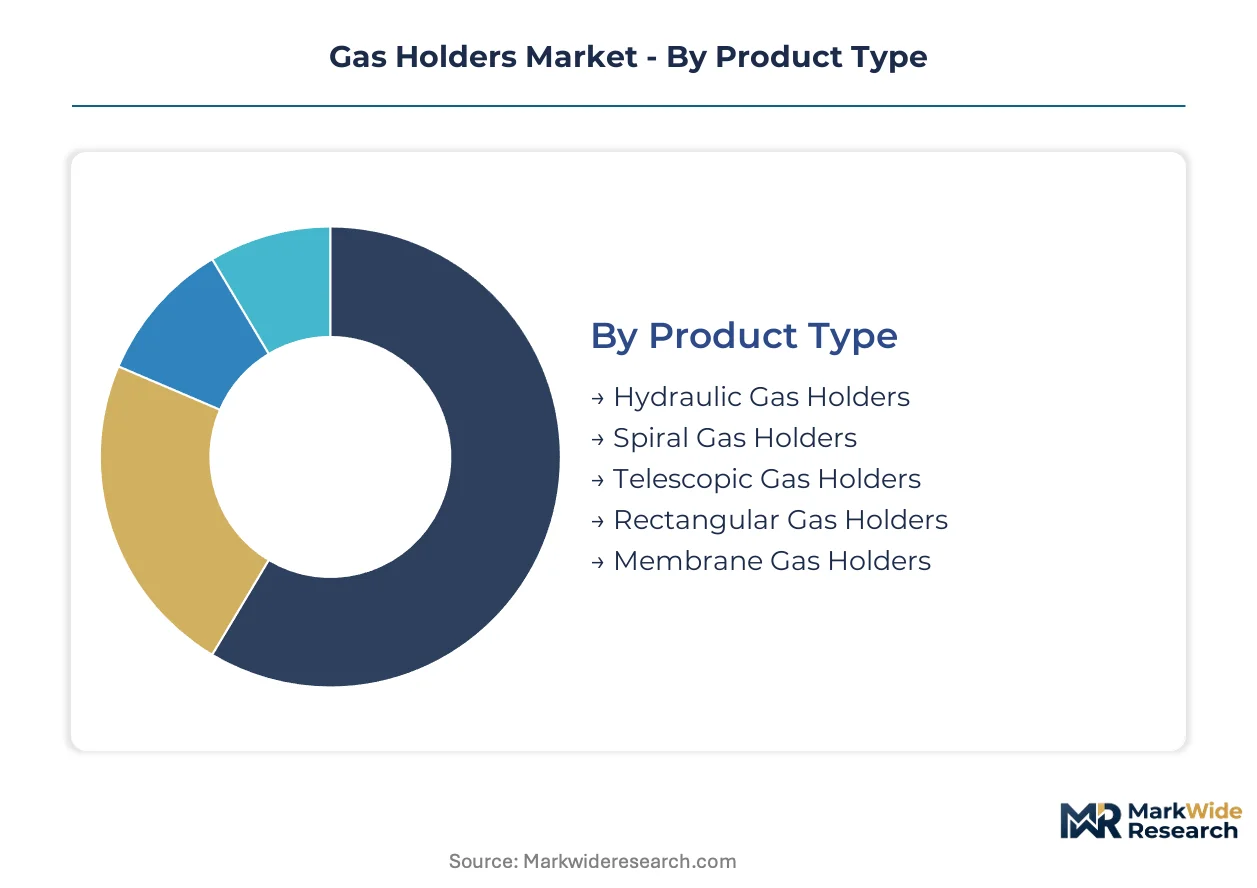
Gas holder procurement varies sharply by containment pressure, chemical exposure, and foundation constraints. Technology-material combinations determine project economics across municipal utilities, industrial sites, and bioenergy clusters. Segment boundaries are blurring as membrane systems displace steel in applications once dominated by hydraulic designs.
Product Type:
Membrane systems command premium pricing while hydraulic and spiral designs retain volume share in legacy municipal fleets.
- Membrane Gas Holders:Flexible ethylene-propylene-diene monomer sheeting tensioned over concrete bases eliminates corrosion-prone steel components. German biogas upgrading facilities and UK landfill operators specify these for hydrogen sulfide-rich environments under tightening EU Green Deal methane rules. Modular assembly cuts site construction time by half versus welded alternatives.
- Hydraulic Gas Holders:Sealed piston systems using water seals maintain pressure equilibrium across variable demand cycles. Indian municipal gas distribution networks in Maharashtra and Gujarat continue specifying these for grid-buffer applications where membrane durability remains unproven at scale.
- Spiral Gas Holders:Interlocking steel strip construction allows vertical expansion without additional footprint.
- Telescopic Gas Holders:Nested cylindrical sections provide staged capacity adjustment for fluctuating industrial demand.
- Rectangular Gas Holders:Welded plate designs optimize site geometry in dense urban European utility yards.
Today's leader: Hydraulic Gas Holders. Tomorrow's challenger: Membrane Gas Holders.
Application:
Bioenergy and landfill containment concentrate procurement growth while municipal storage sustains replacement revenue.
- Bioenergy Plants:Anaerobic digestion facilities require intermediate buffer storage between biogas production and upgrading-to-grid injection. India's renewable natural gas incentive programs in Gujarat and Maharashtra are accelerating membrane holder deployment at agricultural and food-waste digesters. Pressure ratings must accommodate variable methane-carbon dioxide ratios.
- Landfill Gas Containment:Leachate and methane capture systems demand corrosion-resistant containment under EPA Clean Air Act enforcement. California and Texas operators face compressed replacement schedules for leaking legacy steel infrastructure. Membrane systems seal more completely than aging hydraulic holders in high-moisture environments.
- Wastewater Treatment:Activated sludge digesters produce biogas requiring immediate containment to prevent methane venting.
- Municipal Gas Storage:Urban distribution networks buffer peak demand through low-pressure holder farms.
- Industrial Gas Storage:Steel fabrication and chemical plants maintain captive gas reserves for process continuity.
Bioenergy Plants capture the steepest expansion trajectory as renewable natural gas certificates subsidize storage infrastructure.
End User:
Specialized biogas operators consolidate procurement decisions while traditional utilities fragment purchases across engineering disciplines.
- Biogas Facilities:Farmer cooperatives and industrial digesters now contract turnkey storage-to-grid solutions rather than specifying components separately. German agricultural clusters exemplify this consolidation under specialized EPC contractors. Membrane system modularity aligns with distributed generation scale.
- Waste Management Firms:Landfill operators integrate gas capture with power generation or renewable natural gas upgrading. US EPA methane emission standards compel infrastructure upgrades at facilities failing leak detection thresholds. Procurement prioritizes sealed membrane containment over steel refurbishment.
- Energy Producers:Power generators maintain buffer storage for synthetic methane from power-to-gas electrolysis.
- Gas Distributors:Municipal utilities sustain installed base of steel holders through selective retrofit cycles.
- Utility Operators:Grid balancing services require flexible low-pressure storage for demand smoothing.
Biogas Facilities and Waste Management Firms are gaining procurement influence fastest as regulatory pressure concentrates on methane containment.
Technology:
Composite fabrication is decoupling construction from steel-intensive supply chains while membrane welding expertise concentrates geographically.
- Composite Materials:Glass-reinforced thermoplastic shells unify corrosion resistance and structural rigidity in single fabrication steps. Wastewater treatment operators in Germany and the United Kingdom specify these for hydrogen sulfide-rich environments. Elimination of separate coating and welding sequences compresses supplier qualification timelines.
- Fabric Reinforced Membranes:Ethylene-propylene-diene monomer sheeting with polyester reinforcement delivers chemical resistance at reduced weight. European and Japanese chemical suppliers dominate high-performance membrane feedstock. Certified welding technicians concentrate in Germany and the Netherlands, creating installation bottlenecks elsewhere.
- Steel Fabrication:Carbon steel plate construction retains cost advantage in large-diameter hydraulic applications.
- Concrete Construction:Spiral holder foundations and membrane base slabs require extensive civil works.
- Automated Valve Systems:Pressure regulation and safety venting integrate with holder control architecture.
Composite Materials are climbing the fastest as corrosion resistance and foundation flexibility reshape procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biogas upgrading clusters anchor the regional gas holder demand map, with membrane system procurement accelerating under EU Green Deal methane enforcement. Regulatory pressure and renewable natural gas incentive programs are redistributing capital allocation across municipal and industrial storage infrastructure.
United States
Landfill gas capture facilities in California and Texas face compressed replacement schedules for leaking steel infrastructure under EPA Clean Air Act enforcement. The EPA's methane emission standards compel operators toward sealed membrane containment systems. Industrial procurement concentrates in municipal waste management clusters seeking renewable natural gas certification pathways.
Germany
Agricultural biogas cooperatives in Bavaria and Lower Saxony now contract turnkey storage-to-grid solutions rather than fragmenting purchases across vendors. EU Green Deal methane rules under the EU Green Deal tighten emission thresholds for existing steel holder fleets. Farmer cooperatives in northern German agricultural clusters exemplify procurement consolidation under specialized EPC contractors.
India
Urban wastewater treatment plants in Maharashtra and Gujarat lack adequate gas containment for captured methane, creating first-mover openings for membrane system suppliers. Central Electricity Authority guidelines and state-level renewable natural gas programs in Gujarat accelerate digester infrastructure deployment. Food-waste and agricultural digester clusters in western Indian states drive capital allocation toward modular storage solutions.
United Kingdom
Landfill operators across England and Scotland replace aging hydraulic holders with membrane systems to meet Environment Agency methane containment requirements. The UK's biomethane injection standards mandate intermediate storage capacity between production and grid connection. Industrial biogas upgrading facilities in the Midlands and northern England concentrate procurement of corrosion-resistant composite containment.
Japan
Wastewater treatment authorities in the Kanto and Kansai regions specify glass-reinforced thermoplastic shells for hydrogen sulfide-rich digester gas environments. METI-supported biogas utilization programs accelerate municipal infrastructure investment. Industrial gas handling specialists in the Nagoya and Osaka manufacturing belts integrate membrane storage into combined heat and power installations.
Gas Holders Market Competitive Landscape
Global majors compete with regional champions across technology-material combinations, with composite fabrication specialists gaining ground against traditional steel tank contractors. The vendor base organizes around three strategic archetypes: industrial gas infrastructure conglomerates extending into storage project deployment, cryogenic and gas handling specialists competing in membrane technology, and composite material fabricators decoupling from steel-intensive supply chains. Dominant competitive moves include backward integration into membrane feedstock production and geographic expansion through specialized EPC partnerships.
Within the industrial gas infrastructure tier, Linde plc and Air Liquide occupy positions anchored by large-scale project deployment capabilities across European utility networks. Chart Industries, Inc. exemplifies the cryogenic and gas handling specialist archetype, with membrane gas holder technology representation in bioenergy applications. Wartsila sits within the energy storage engineering segment, extending capabilities from power generation into biogas upgrading and containment solutions. These three companies illustrate the competitive positioning spectrum without exhausting the active participant base.
| Leading Market Players |
|---|
| Wartsila |
| Linde plc |
| Xebec Adsorption Inc. |
| Chart Industries, Inc. |
| Hitachi Zosen Corporation |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer Group |
| Taiyo Nippon Sanso Corporation |
| Others |
Supply & Pricing Matrix
EU Green Deal methane emission thresholds gate both qualified membrane supply and premium-tier pricing access for gas holder systems, compressing margins for fabricators lacking certified EPDM welding capabilities while elevating pricing power for composite specialists meeting ATEX compliance documentation requirements.
Pricing Analysis
Input-cost pass-through from ethylene-propylene-diene monomer sheeting and carbon steel plate volatility shapes contract structures across membrane and hydraulic systems respectively. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates ATEX-documented composite shells from conventional steel fabrications. Cost compression in standard membrane tiers is intensifying because European and Japanese chemical suppliers concentrate high-performance EPDM feedstock. Municipal utilities in India exhibit highest price sensitivity due to constrained capital budgets, while German agricultural cooperatives demonstrate lowest sensitivity given renewable natural gas certificate revenue streams.
Supply Chain Analysis
Certified membrane welding technician scarcity in Germany and the Netherlands constrains manufacturing throughput for large-diameter EPDM systems. Supply concentration rests on German composite fabricators, Japanese chemical suppliers, and Indian steel plate contractors for respective technology tiers. Raw material dependencies include glass-reinforced polymer feedstock, ethylene-propylene-diene monomer sheeting, and carbon steel plate. Single-source vulnerability from narrow European and Japanese EPDM supplier bases creates project bottlenecks. Distribution runs through specialized EPC contractors consolidating turnkey storage-to-grid procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Clean Air Act methane enforcement and EU Green Deal emission thresholds continuously refresh replacement demand cycles.
For Market Incumbents: Hedge membrane feedstock exposure through backward integration into EPDM sheeting production or captive supply agreements with Japanese chemical suppliers. Defend position against emerging composite fabricators by accelerating ATEX compliance documentation capabilities to compress certification timelines for European biogas operators. For New Entrants and Emerging Players: Capture first-mover positioning in Indian municipal wastewater treatment plants across Maharashtra and Gujarat where gas containment infrastructure remains underdeveloped. Target membrane system deployment through specialized EPC partnerships rather than direct equipment sales channels. For Investors and Strategic Acquirers: Roll-up economics work for regional composite fabrication specialists because membrane welding technician scarcity concentrates qualified supply in Germany and the Netherlands. Monitor biomethane injection standard revisions across EU member states as the signal indicating which storage technologies qualify for renewable energy certificates and green gas subsidies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Feedstock | Secures membrane supply for biogas containment projects under EU Green Deal timelines. |
| ATEX Certification Investment | Accelerates commissioning schedules for German and UK landfill gas capture facilities. |
| Specialized EPC Partnership Expansion | Aligns with procurement consolidation trends among German agricultural biogas cooperatives. |
| Composite Shell Manufacturing Scale-Up | Captures displacement of steel-intensive fabrication in hydrogen sulfide-rich environments. |
| Indian Municipal Market Entry | Addresses gas containment gaps in Maharashtra and Gujarat wastewater treatment infrastructure. |
Research Methodology
Multiple input streams — primary interviews with biogas facility operators, EPC contractor technical directors, and membrane system welding technicians; secondary validation through EPA enforcement databases, EU ETS transaction records, and Indian Central Electricity Authority guidelines; plus customs data on EPDM sheeting imports — were reconciled through bottom-up project pipeline analysis and top-down regulatory impact modeling.
Data-stream reconciliation across the analysis window applied capacity-based modeling for hydraulic and spiral steel holders alongside unit economics frameworks for membrane and composite systems. Segmentation dimensions included product type, application category, end-user archetype, and technology-material combination. CAGRs were derived from installed base replacement cycles intersecting with regulatory compliance deadlines. Forecast inputs incorporated biomethane certificate pricing trajectories and methane emission detection threshold revisions.
Underlying measurement precision varies by segment; membrane gas holder deployments in Germany and the United Kingdom carry tighter precision than emerging market municipal projects. Forecasts reflect assumptions regarding regulatory enforcement consistency and feedstock supply continuity. Material deviation in EPA inspection frequency or EU Green Deal implementation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Card Market
Others
Subtilisin Market
Others
Bio-Based Leather Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Augmented Reality in Energy and Utilities Market
Others
Global Compact Wheel Loaders Market
Others
Managed Testing Services Market
Others
Trusted Platform Module (TPM) Market
Others
India Foundry Market
Others
Digital Transformation of Maritime Freight Market
Others
Magnetic Stripe Readers Market
Others
Smart Doorbell Market
Others
Global Laser Defense Eyewear Market
Others
Rotary Evaporators Market
Others
Smart Home Technologies Market
Others
Air Purification Systems Market