
 Asia-Pacific Feed Vitamins Market | 2026-2036
Asia-Pacific Feed Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Vitamins Market Outlook
Aftermarket technical service revenue is reconfiguring margin pools away from commodity vitamin sales toward formulation consulting and on-farm nutritional auditing. BASF SE leverages its Ludwigshafen-derived vitamin A and E synthesis expertise to anchor premium pricing in Southeast Asian aquaculture channels. DSM-Firmenich sustains R&D intensity across carotenoid and B-vitamin portfolios, while Kemin Industries Inc. specializes in microencapsulation delivery systems that protect vitamin stability in tropical feed milling conditions.
Feed vitamins comprise organic micronutrient compounds—fat-soluble A, D, E, K and water-soluble B-complex and C—typically dosed at 50–500 grams per metric ton of compound feed to prevent deficiency disorders and optimize metabolic performance in livestock. Industrial production proceeds via chemical synthesis, fermentation, or extraction, with stability-enhancing coatings applied to withstand pelleting temperatures exceeding 80°C. The amino acids segment dominates volume throughput due to lysine and methionine fortification in poultry and swine rations, while the enzymes category registers the fastest structural expansion as phytase and non-starch polysaccharide enzymes reduce antinutritional factors in soybean- and cassava-based diets. Aquaculture end-use commands superior margins versus ruminant applications, reflecting the complexity of species-specific vitamin requirements for shrimp and high-value marine fish.
China's SAMR enforces GB standards for feed additive labeling and maximum inclusion rates, while India's BIS mandates premix quality certification for imported vitamin concentrates. The EU Green Deal's deforestation-free supply chain requirements, applied to Southeast Asian palm kernel and soybean meal inputs, indirectly shape vitamin sourcing decisions for export-oriented livestock operations. Stakeholders must monitor regulatory divergence between national feed safety regimes and align premix formulation capabilities with evolving species-specific nutritional guidelines.
Market Dynamics
Precision-formulated vitamin premixes are displacing commodity vitamin sales across Southeast Asian aquaculture and poultry corridors, as integrators demand species-specific nutritional auditing and feed conversion optimization services bundled with micronutrient supply.
Growth Catalysts
- Vietnam's Mekong Delta aquaculture intensification:Shrimp and pangasius farmers require stabilized vitamin C and E formulations to combat oxidative stress in high-density ponds.
- China's GB 7300 feed additive standards:Mandatory labeling and maximum inclusion rates for imported premixes are forcing quality upgrades that favor certified suppliers.
- Microencapsulation technology:Heat-stable coating systems protect vitamin bioactivity through pelleting temperatures exceeding 80°C in tropical feed mills.
Market Restraints
- Retinol and tocopherol precursor volatility:Chemical synthesis feedstocks for vitamins A and E fluctuate with petrochemical and palm derivative markets.
- Import concentration risk:European and Chinese vitamin manufacturers control 70% of Southeast Asian premix supply, creating single-source vulnerability.
- Species-specific formulation complexity:Shrimp vitamin requirements differ materially from poultry, preventing scale economies in multi-species feed mills.
Strategic Opportunities
- Indonesia's Central Java poultry corridor:Contract farming expansion creates demand for on-farm nutritional auditing services bundled with premix supply.
- EU Green Deal deforestation-free mandates:Export-oriented livestock operations require traceable vitamin sourcing aligned with sustainable soybean and palm kernel supply chains.
- Fermentation-derived vitamin K2 and B12:Microbial production platforms reduce dependency on petrochemical synthesis for niche aquaculture applications.
Industry Challenges
- Formulation chemist scarcity:Tropical stability expertise and species-specific nutrition knowledge concentrate in European and Chinese R&D centers.
- Dual certification timelines:India's BIS premix quality certification and China's SAMR registration create 18-24 month market entry delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Vitamins Market |
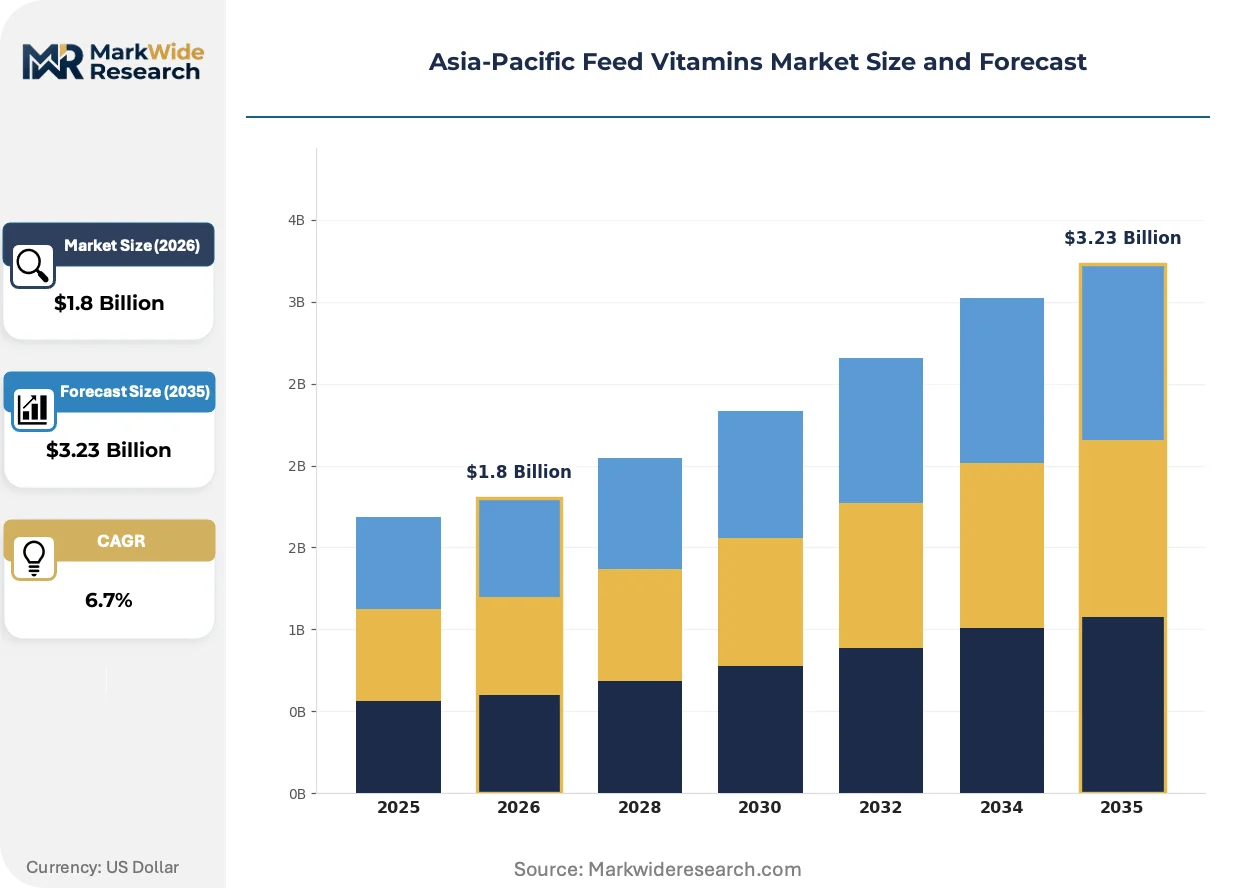
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Minerals, Enzymes End User: Poultry, Swine, Aquaculture, Ruminants Form: Powder, Liquid, Granular, Tablets Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Adisseo, BASF SE, Cargill Inc., DSM-Firmenich, Lonza Group Ltd., Archer Daniels Midland Co., Evonik Industries, Kemin Industries Inc., Chr. Hansen, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Vitamins Market Strategic Shifts
Digital nutrition platforms and precision dosing systems are compressing the gap between laboratory formulation and on-farm vitamin delivery, while regulatory divergence between national feed safety regimes forces premix suppliers to maintain multiple compliance architectures.
NIR spectroscopy coupled with cloud-based formulation software is digitizing real-time vitamin premix quality verification in Vietnamese and Indonesian feed mills. Large poultry integrators deploy these systems to detect vitamin degradation before pelleting. The technology is digitizing supplier accountability, shifting liability from feed mill operators to premix manufacturers for bioactivity guarantees.
China's SAMR enforcement of GB 7300 labeling standards and India's BIS premix certification mandates are fragmenting regulatory compliance costs across the Asia-Pacific region. Importers must maintain separate documentation trails and reformulation capabilities for each national market. Aquaculture-exporting operations face the strictest scrutiny, as EU and Japanese import requirements cascade down to vitamin sourcing decisions.
Integrator procurement teams are unbundling commodity vitamin purchases from technical service contracts, creating separate RFP streams for premix supply versus on-farm nutritional auditing. Thai and Vietnamese poultry conglomerates pioneered this split, pressuring premix suppliers to demonstrate formulation expertise independent of volume discounts. The shift is most visible in Mekong Delta shrimp operations, where disease outbreak recovery depends on rapid vitamin protocol adjustments rather than static premix specifications.
Asia-Pacific Feed Vitamins Market Segmentation
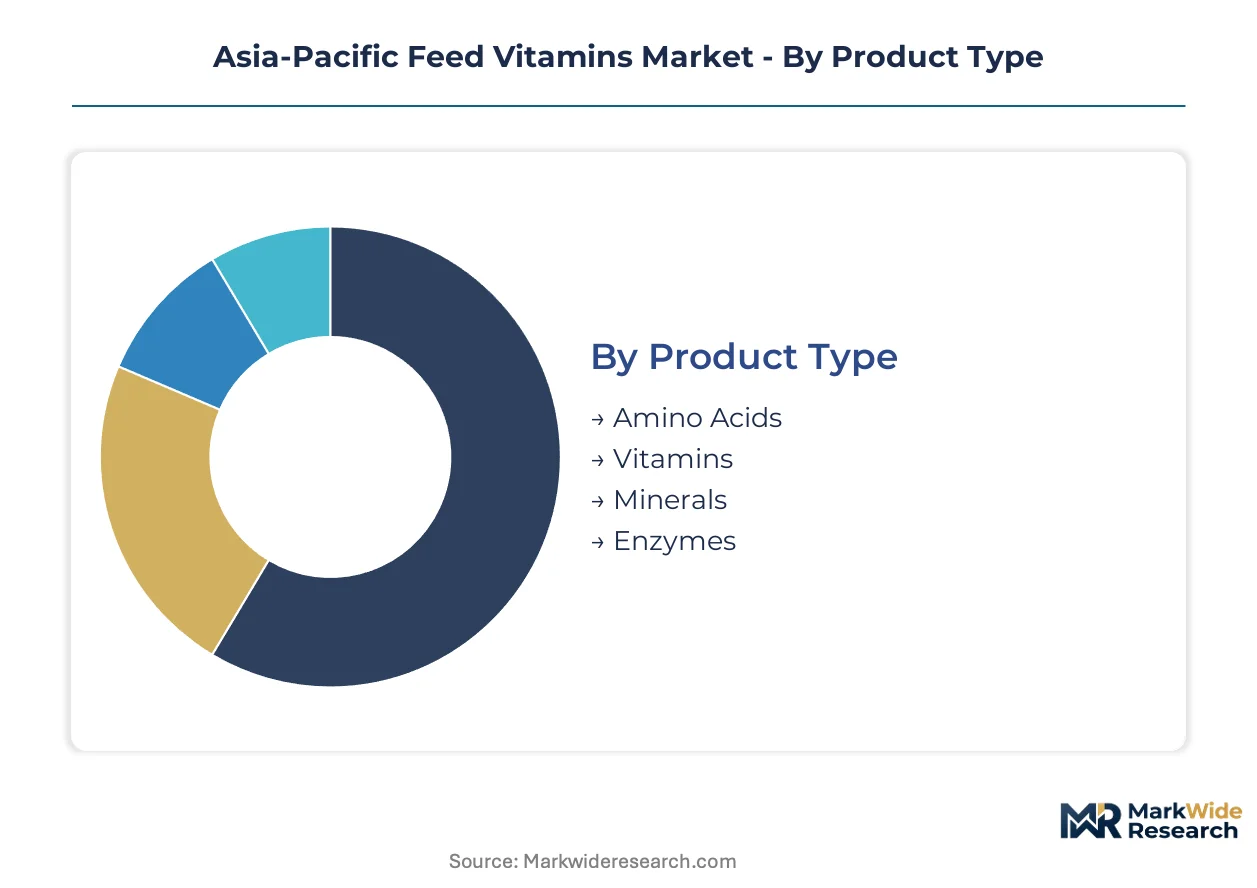
Segmentation in the Asia-Pacific feed vitamins market reveals how micronutrient suppliers align formulation capabilities with species-specific metabolic requirements and tropical supply chain constraints. Each dimension—product chemistry, livestock category, physical form, and channel structure—creates distinct margin pools and technical service demands across Southeast Asian aquaculture belts and Chinese poultry corridors.
Product Type:
Use-case spectrum spans from bulk amino acid fortification to precision vitamin premixes requiring stability engineering for tropical pelleting conditions.
- Amino Acids:Lysine and methionine dominate volume throughput in poultry and swine rations, with Chinese compound feed mills consuming the largest regional share for protein optimization in high-density broiler operations. Demand concentrates in Vietnam's Mekong Delta and Indonesia's Central Java, where integrators prioritize feed conversion ratio improvements over micronutrient complexity.
- Vitamins:Fat-soluble A, D, E, K and water-soluble B-complex formulations require microencapsulation coatings to withstand pelleting temperatures exceeding 80°C in tropical feed mills. Aquaculture applications in Vietnam and Thailand command superior margins due to species-specific requirements for shrimp vitamin C and E supplementation in oxidative stress management.
- Minerals:Trace element premixes support bone development and enzymatic function across ruminant and monogastric species, with India's BIS certification mandates creating quality thresholds for imported concentrates.
- Enzymes:Phytase and non-starch polysaccharide enzymes reduce antinutritional factors in soybean- and cassava-based diets, expanding most quickly as Southeast Asian feed formulators seek digestibility improvements in alternative protein sources.
The dominant share belongs to amino acids, while enzymes are closing the gap fastest.
End User:
Customer type stratification follows the intensity of farming operations and the technical sophistication of nutritional auditing requirements.
- Poultry:Broiler and layer operations in Indonesia's Central Java corridor and Thailand's contract farming networks drive standardized premix demand with bundled technical service contracts. China's GB 7300 labeling standards force quality upgrades among integrators sourcing imported vitamin concentrates.
- Aquaculture:Shrimp and pangasius farmers in Vietnam's Mekong Delta require stabilized vitamin formulations for high-density pond systems, with disease outbreak recovery protocols demanding rapid nutritional adjustments rather than static specifications.
- Swine:Sow and grower-finisher operations in China and Vietnam consume B-vitamin fortification for metabolic performance, though margin pressure from African swine fever recovery limits premium premix adoption.
- Ruminants:Dairy and beef cattle applications in Australia and New Zealand exhibit lower micronutrient intensity compared to monogastric species, with pasture-based systems reducing dependence on precision-formulated supplementation.
Poultry maintains volume leadership, though aquaculture generates the steepest expansion trajectory in value terms.
Form:
Physical format selection hinges on feed mill equipment, tropical storage stability, and species-specific dosing precision requirements.
- Powder:Standard premix format for integration into compound feed, dominating Vietnamese and Indonesian feed mill procurement for cost efficiency in high-volume poultry rations.
- Liquid:Post-pelleting application systems protect heat-sensitive vitamins, gaining traction in Thai aquaculture feed mills where vitamin C stability is critical for shrimp diets.
- Granular:Coated granules improve flowability and reduce dust in tropical milling environments, with Chinese manufacturers prioritizing this format for SAMR-compliant export premixes.
- Tablets:Compressed forms serve niche ruminant mineral supplementation and on-farm top-dressing applications, limited by dosing precision constraints in automated feed systems.
Powder commands the installed base, while liquid formats are gaining share fastest in aquaculture channels.
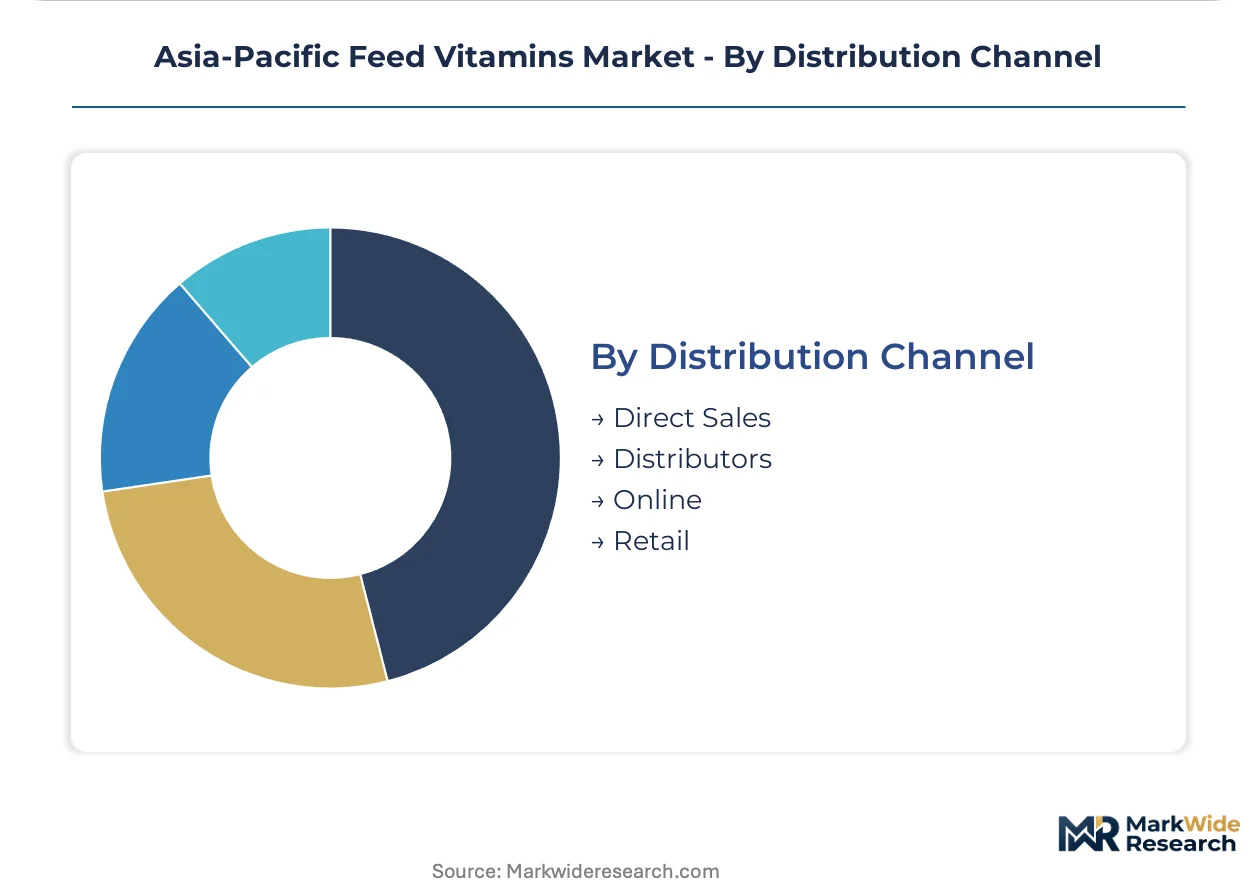
Distribution Channel:
Channel structure reflects the unbundling of commodity supply from technical service relationships across Southeast Asian integrator procurement teams.
- Direct Sales:Large poultry conglomerates in Thailand and Vietnam source premixes through dedicated supply agreements, separating volume purchasing from on-farm nutritional auditing contracts.
- Distributors:Regional premix distributors maintain inventory positions for mid-tier feed mills, with India's BIS certification requirements filtering supplier eligibility.
- Online:Digital procurement platforms emerge for standardized vitamin specifications, though complex aquaculture formulations remain relationship-driven.
- Retail:Farm supply stores serve smallholder livestock operations with pre-packaged vitamin supplements, concentrated in Indonesia's outer island poultry farming communities.
Direct sales anchor the largest volume flow, while distributor networks are expanding most quickly to serve mid-market feed mill consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia-Pacific feed vitamins landscape. Vietnamese aquaculture operators absorb premium formulations for disease recovery, while Indonesian poultry integrators drive hard volume discounts on standardized premixes.
China
SAMR enforcement of GB 7300 labeling standards compels quality upgrades among compound feed manufacturers sourcing imported vitamin concentrates. The Yangtze River Delta hosts the densest concentration of premix formulators, where Ludwigshafen-derived synthesis expertise anchors premium positioning in aquaculture channels. Domestic fermentation platforms for vitamin K2 and B12 are reducing import dependency for niche applications.
Vietnam
Shrimp and pangasius farmers in the Mekong Delta require stabilized vitamin C and E formulations to manage oxidative stress in high-density pond systems. The Ministry of Agriculture and Rural Development aligns feed safety protocols with export market requirements for EU and Japanese destinations. Can Tho and An Giang provinces concentrate the most intensive premix technical service relationships.
Indonesia
Central Java's poultry corridor drives contract farming expansion with bundled nutritional auditing demands separate from commodity vitamin procurement. BIS-equivalent feed additive registration creates compliance friction for European premix suppliers. Surabaya feed mill clusters are adopting microencapsulation coatings to protect bioactivity through tropical pelleting conditions.
India
FSSAI-aligned feed safety protocols and BIS premix quality certification filter eligible suppliers for imported vitamin concentrates. Poultry integrators in Haryana and Telangana prioritize feed conversion ratio improvements through precision-formulated B-vitamin fortification. The 18-24 month dual certification timeline disadvantages new market entrants against established European and Chinese suppliers.
Thailand
Large poultry conglomerates pioneered unbundled procurement streams, separating volume purchasing from on-farm nutritional auditing contracts. Bangkok-based feed mill networks deploy NIR spectroscopy systems for real-time premix quality verification before pelleting. Aquaculture export operations face cascading EU Green Deal deforestation-free requirements down to vitamin sourcing decisions.
Asia-Pacific Feed Vitamins Market Competitive Environment
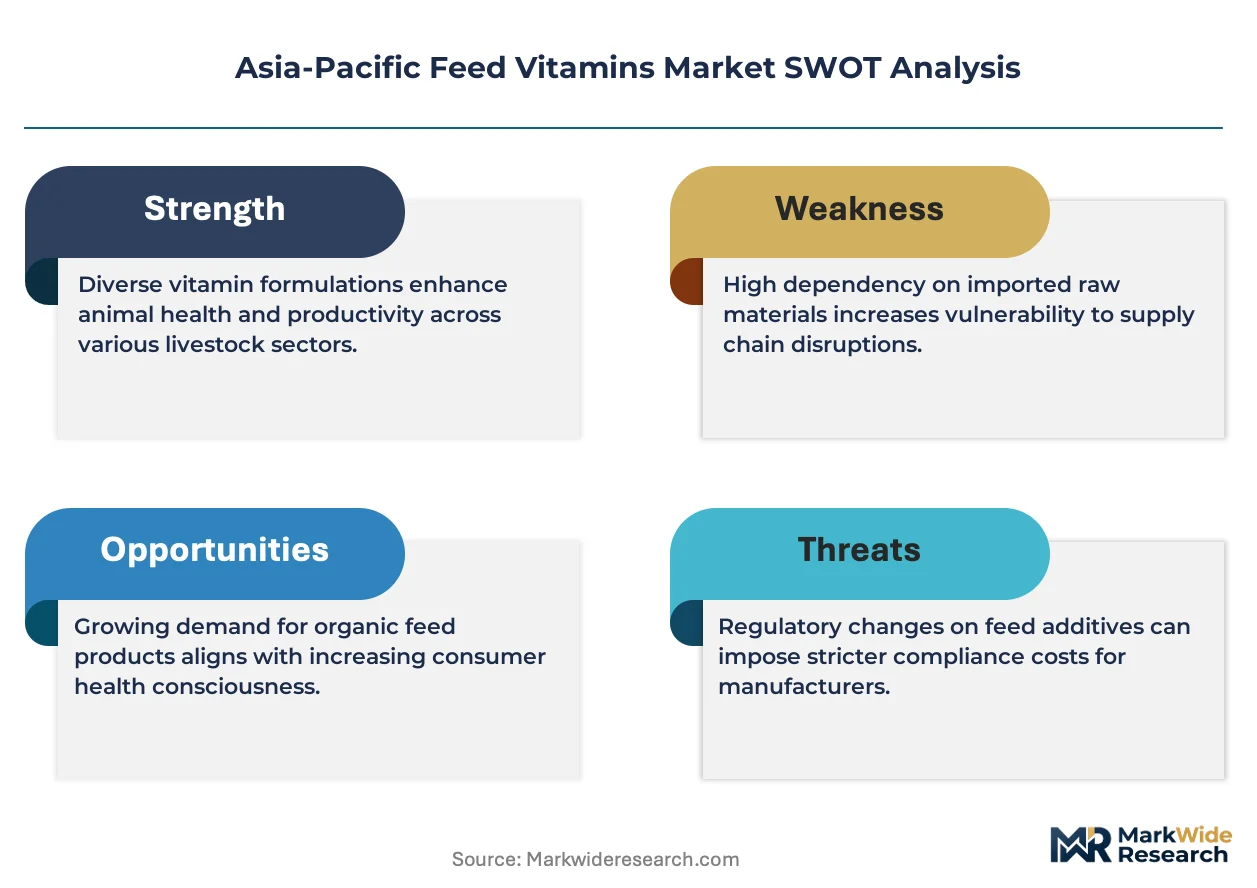
Integrated chemical conglomerates and specialized nutrition companies split the Asia-Pacific feed vitamins market along capability lines. European and Chinese manufacturers control approximately seventy percent of regional premix supply, creating concentrated sourcing dependencies for Southeast Asian integrators. Three archetypes dominate: synthesis-led chemical majors with backward integration into petrochemical feedstocks, fermentation specialists leveraging microbial production platforms, and application-technology firms focused on tropical stability engineering. Competitive moves center on microencapsulation R&D partnerships and on-farm technical service expansion.
Within the synthesis-led tier, BASF SE and DSM-Firmenich exemplify divergent strategic positioning around Ludwigshafen-derived vitamin A and E production versus carotenoid and B-vitamin portfolio breadth. Kemin Industries Inc. occupies a distinct position among stability-technology specialists, with microencapsulation delivery systems addressing tropical feed milling conditions. Adisseo represents the fermentation-platform archetype, with microbial production capabilities reducing dependency on petrochemical synthesis pathways. These three anchors illustrate how technical service bundling and geographic proximity to Southeast Asian aquaculture clusters determine competitive viability.
| Leading Market Players |
|---|
| Adisseo |
| BASF SE |
| Cargill Inc. |
| DSM-Firmenich |
| Lonza Group Ltd. |
| Archer Daniels Midland Co. |
| Evonik Industries |
| Kemin Industries Inc. |
| Chr. Hansen |
| Others |
Value Chain & Pricing Dynamics
Ludwigshafen's vitamin A and E synthesis complexes anchor European supply capacity, with their output fluctuations transmitting directly into Southeast Asian premix pricing power during petrochemical feedstock volatility cycles. Chinese fermentation platforms for vitamin K2 and B12 compete on cost, compressing margins for synthesis-dependent suppliers when microbial production scales.
Pricing Analysis
On-farm nutritional auditing contracts now generate higher lifetime value than commodity vitamin transactions, with Thai poultry integrators unbundling these services into separate RFP streams. Three-tier pricing structure across certified-premium, standard-grade, and economy premix levels reflects China's GB 7300 compliance costs versus Indonesian volume discounts. Pricing pressure stems from African swine fever recovery limiting premium B-vitamin adoption in Vietnamese sow operations. Aquaculture operators in Vietnam's Mekong Delta exhibit lowest price sensitivity, absorbing stabilized vitamin C premiums for oxidative stress management, while Indonesian Central Java broiler integrators drive hardest volume negotiations.
Supply Chain Analysis
Petrochemical-derived retinol precursors and palm-based tocopherol feedstocks concentrate upstream vulnerability in European and Malaysian oleochemical complexes. BASF's Ludwigshafen operations and DSM-Firmenich's Swiss carotenoid facilities anchor 70% of Southeast Asian premix supply alongside Chinese fermentation platforms. Single-source concentration risk intensifies when India's BIS certification timelines delay alternative supplier qualification. Distribution runs through direct sales agreements with Thai and Vietnamese poultry conglomerates, supplemented by regional distributors serving mid-tier Indonesian feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in post-African swine fever cyclical recovery, with Chinese sow herd rebuilding driving B-vitamin demand normalization across the projection horizon.
For Market Incumbents: Build tropical stability expertise moats through microencapsulation R&D partnerships with Vietnamese aquaculture clusters. Defend against Chinese fermentation platforms by securing backward integration into palm-derived tocopherol feedstocks. Expand on-farm nutritional auditing capacity in Indonesia's Central Java corridor before contract farming consolidation completes.
For New Entrants and Emerging Players: India's 18-24 month BIS-SAMR dual certification lag offers white-space entry for fermentation-derived vitamin K2 specialists targeting shrimp export operations. Penetrate liquid vitamin post-pelleting systems in Thai aquaculture mills where heat-sensitive vitamin C stability commands premium positioning. Deploy digital nutrition platforms as Trojan horse for premix supply relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because divergence between China's GB standards, India's BIS mandates, and EU Green Deal traceability requirements fragments compliance architectures. Target acquisition candidates with multi-jurisdictional certification capabilities and captive tropical stability engineering. Monitor Indian poultry integrator consolidation rates as inflection signal for B-vitamin fortification intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation R&D Partnership | Kemin Industries' heat-stable coatings protect bioactivity through 80°C pelleting in Vietnamese mills. |
| Dual Certification Investment | Simultaneous BIS and SAMR registration cuts 18-24 month market entry delays for Indian-Chinese corridor access. |
| Fermentation Platform Expansion | Microbial vitamin K2 and B12 production reduces petrochemical synthesis dependency for aquaculture niches. |
| Digital Nutrition Platform Launch | NIR spectroscopy systems shift liability to premix manufacturers for real-time bioactivity verification. |
| On-Farm Technical Service Buildout | Unbundled nutritional auditing contracts separate from commodity premix sales in Thai integrator procurement. |
Study Parameters
A standing panel of feed mill procurement managers, poultry integrator nutrition directors, aquaculture farm operators, and regulatory affairs specialists provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with Vietnamese Mekong Delta shrimp farmers and Indonesian Central Java contract farming coordinators, validated against secondary sources including China's SAMR GB 7300 filings, India's BIS premix certification registries, and EU Green Deal deforestation-free supply chain disclosures. Bottom-up premix volume estimates from Vietnamese and Indonesian feed mill clusters triangulated against top-down compound feed production data.
Scenario bracketing around African swine fever recovery trajectories and Chinese sow herd rebuilding informed projection ranges across the modeling period. Segmentation dimensions modeled included vitamin chemistry type, livestock species category, physical form factor, and distribution channel structure, with additional granularity on tropical stability requirements versus temperate-zone specifications. CAGRs derived from trend extrapolation of premix intensity per metric ton of compound feed, cross-referenced against aquaculture export volume forecasts and poultry integrator expansion plans.
Practitioners should monitor Chinese SAMR enforcement intensity and Indian BIS certification backlog durations for early signals of supply constraint or regulatory arbitrage opportunities. Cross-checking against FAO aquaculture production statistics and national feed industry association volume disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market