
 Middle-East E-Bike Market | 2026-2036
Middle-East E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East E-Bike Market Foresight
Chinese battery pack suppliers is broadening lithium-ion cell availability across Gulf Cooperation Council assembly plants. Giant Manufacturing Co. Ltd. leverages its integrated motor-drive systems to anchor premium commuter lines in Dubai and Abu Dhabi. Trek Bicycle Corporation competes through specialty retail partnerships that control service networks in Riyadh and Jeddah. Specialized Bicycle Components differentiates via high-torque 750W powertrains designed for desert heat cycling.
An e-bike combines a rechargeable electric motor with pedal-assist or throttle-drive propulsion, typically housing lithium-ion cells within a weather-sealed downtube frame and regulating output through a controller rated between 250W and 1000W. The primary commercial purpose is to extend rider range and reduce physical exertion in high-temperature urban environments where traditional cycling faces climate barriers. Commuter and folding product types dominate unit volume as Gulf cities expand metro feeder networks and employers subsidize last-mile employee transport. Lithium-ion battery configurations command the replacement and upgrade margin pool due to energy density requirements in ambient temperatures exceeding 40 degrees Celsius.
The UAE's Ministry of Energy and Infrastructure and Saudi Arabia's SASO standards body govern e-bike import certification, motor power limits, and battery safety testing protocols that determine market access eligibility. Dubai's Roads and Transport Authority has introduced dedicated cycling lane mandates and parking integration rules that directly shape fleet procurement specifications for delivery operators. Stakeholders must monitor how Saudi Vision 2030 transport privatization timelines and Abu Dhabi municipal micromobility permits redefine channel economics for distributors and direct-to-consumer platforms.
Market Dynamics
Last-mile delivery fleet electrification in Gulf Cooperation Council cities is compressing procurement cycles and forcing distributors to reconfigure service networks around high-utilization commercial operators rather than retail consumers.
Growth Catalysts
- Vision 2030 Transport Privatization:Saudi Arabia's mandate to diversify mobility services is opening state-protected routes to private e-bike fleet operators, accelerating B2B procurement timelines.
- Metro Feeder Integration:Dubai's Roads and Transport Authority cycling lane mandates are embedding e-bike parking into station design specifications, creating captive demand corridors.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements are extending range thresholds beyond 80 kilometers in 40-degree ambient conditions, removing climate barriers to adoption.
Market Restraints
- Import Certification Friction:UAE Ministry of Energy and Infrastructure battery safety testing protocols add 8-12 week clearance timelines that strain just-in-time fleet deployment schedules.
- Desert Thermal Degradation:Lithium-ion cells suffer accelerated capacity fade in ambient temperatures exceeding 45 degrees Celsius, forcing premature replacement cycles.
- Chinese Motor-Drive Concentration:Gulf assembly plants depend on single-source integrated systems from East Asian suppliers, creating vulnerability to shipping disruptions through the Strait of Hormuz.
Strategic Opportunities
- Abu Dhabi Micromobility Permits:Municipal licensing frameworks for shared e-bike fleets are creating regulated channel access previously blocked by public transport monopolies.
- Battery Swapping Infrastructure:Commercial delivery operators are piloting exchange networks that eliminate charging downtime and shift capital expenditure from fleets to infrastructure providers.
- Employer Subsidy Programs:Corporate mobility benefits covering e-bike lease payments are penetrating professional services sectors in Riyadh and Jeddah as recruitment differentiators.
Industry Challenges
- Thermal Management Engineering Talent:Battery pack design expertise for extreme-climate cycling applications remains concentrated in East Asian and European labor markets, forcing Gulf distributors to import technical support.
- SASO Standards Harmonization:Saudi Arabia's standards body maintains divergent motor power limits and connector specifications from UAE certification requirements, fragmenting regional product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East E-Bike Market |
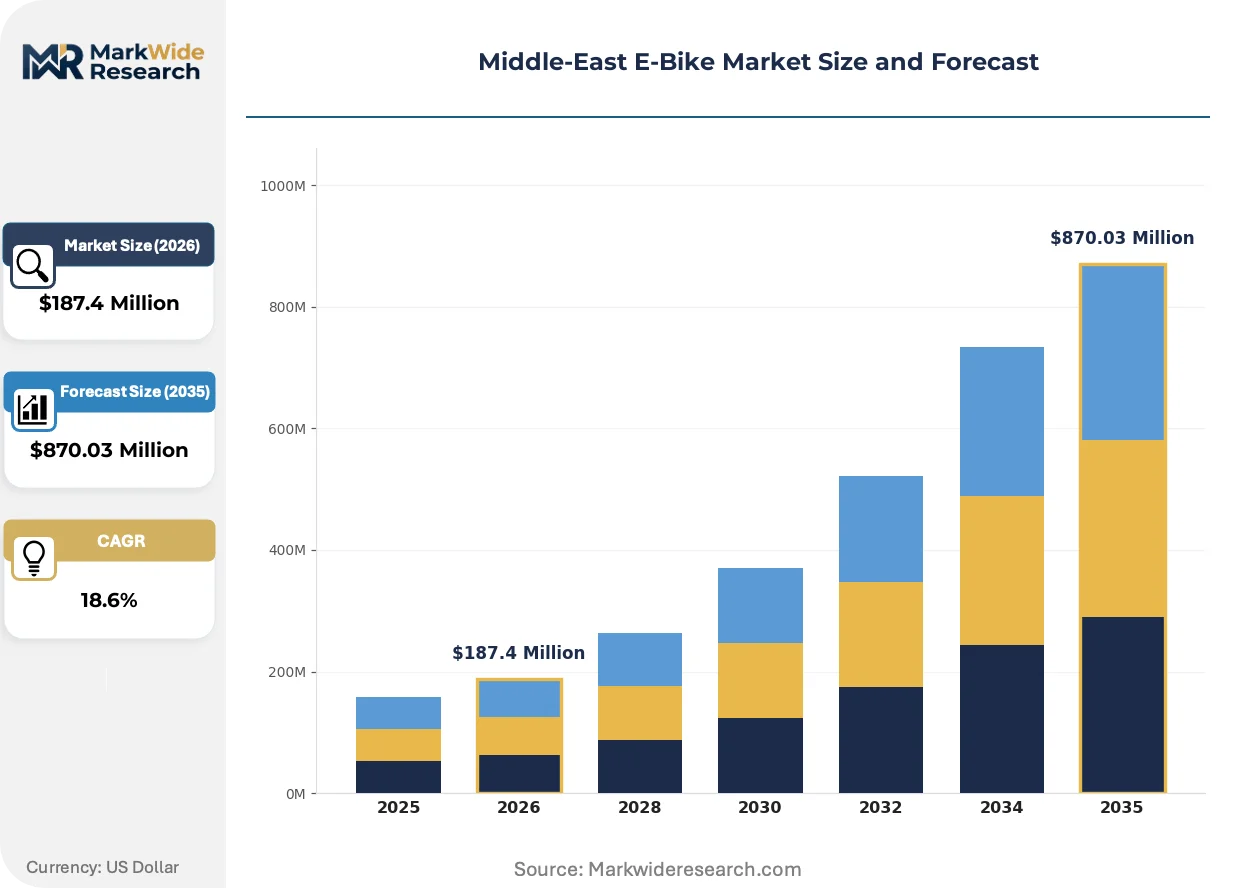
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain, Road, Commuter, Folding Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Lithium Polymer Power Rating: 250W, 500W, 750W, 1000W Sales Channel: Online Retail, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Giant Manufacturing Co. Ltd., Trek Bicycle Corporation, Mercedes-Benz, Accell Group, Riese & Müller, TIER Mobility AG, myStromer AG, Specialized Bicycle Components, Propella, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East E-Bike Market Shifts & Advancements
Smart connectivity modules and thermal management systems are becoming standard equipment as commercial fleet operators demand real-time diagnostics and predictive maintenance capabilities in harsh desert operating conditions.
Regenerative braking hardware is converging with advanced battery management systems to recapture kinetic energy during stop-start urban delivery routes. Fleet operators in Dubai and Riyadh are retrofitting existing pedal-assist vehicles with these packages to extend daily range without increasing battery mass. This convergence is compressing total cost of ownership calculations and accelerating replacement cycles for legacy mechanical braking platforms.
Saudi Vision 2030 sustainability mandates are binding state procurement to electric two-wheeler minimums for municipal service contracts. The industrial consequence is a guaranteed offtake floor that de-risks distributor inventory positions and attracts component suppliers to establish local assembly presence. Commercial fleet segments are responding by front-loading procurement to secure allocation before capacity constraints emerge.
Employers are unbundling mobility benefits from traditional company car schemes and redirecting allowances toward e-bike lease subscriptions. Corporate HR departments in Abu Dhabi and Jeddah are displacing cash allowances with vehicle-as-a-service contracts that bundle maintenance and insurance. This shift is most visible in technology and financial services verticals where parking scarcity and congestion charges have eroded automobile utility.
Middle-East E-Bike Market Segmentation
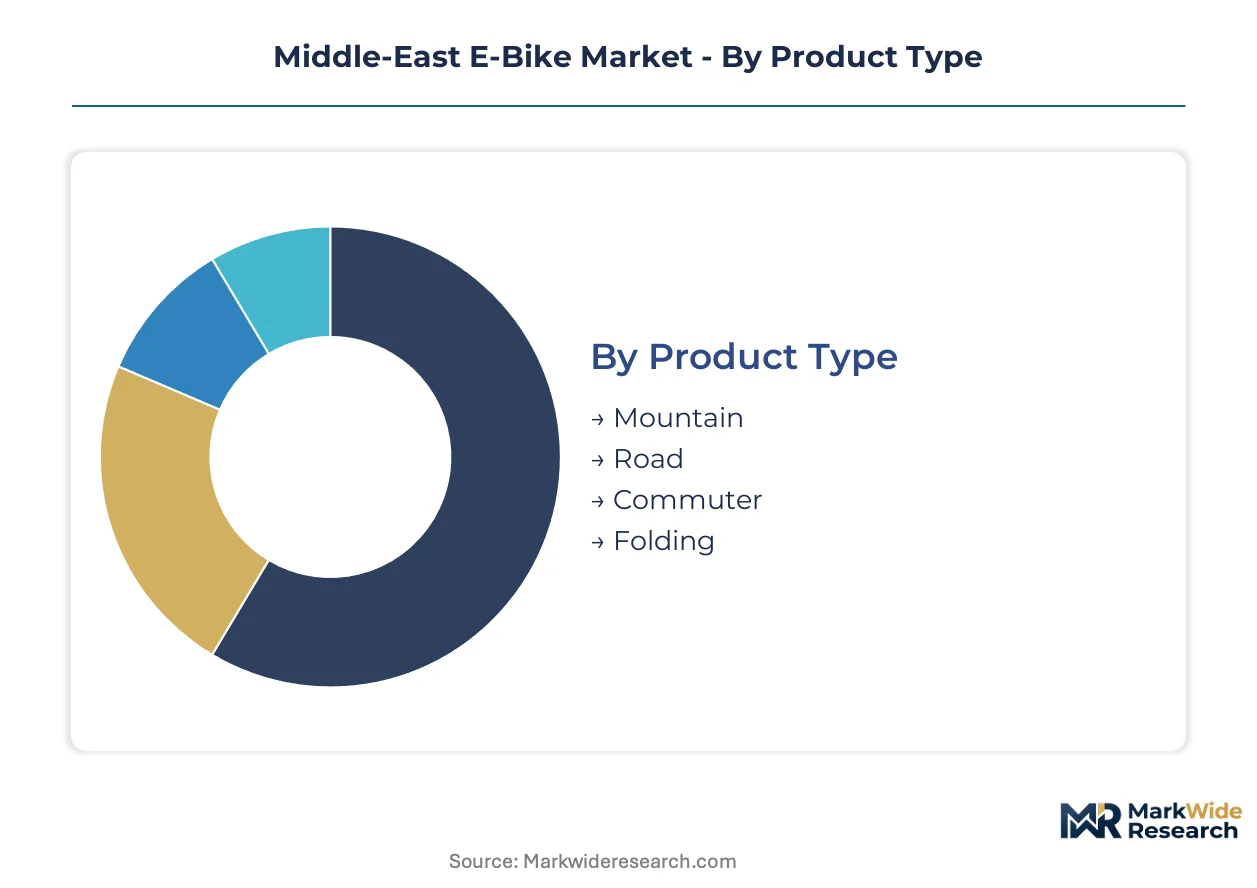
Segment boundaries in the Middle-East e-bike market trace directly to regulatory thresholds and climate adaptation requirements. SASO and UAE Ministry of Energy certification protocols create divergent compliance burdens across product configurations, reshaping distributor portfolios and procurement specifications.
Product Type:
Certification requirements from SASO and the UAE Ministry of Energy and Infrastructure apply differentially across product categories, with mountain and road variants facing stricter frame integrity testing for desert terrain use.
- Commuter:Step-through aluminum frames with integrated downtube batteries dominate fleet procurement in Dubai and Riyadh. Dubai's Roads and Transport Authority cycling lane mandates are embedding dedicated parking infrastructure at metro stations, creating captive demand corridors for daily urban transit.
- Folding:Hinge-reinforced frames with quick-release battery packs address space constraints in high-rise residential towers. Saudi Vision 2030 employer subsidy programs are penetrating professional services sectors in Jeddah as recruitment differentiators for last-mile employee transport.
- Mountain:Suspension-equipped frames with enhanced thermal shielding for battery compartments.
- Road:Lightweight carbon-fiber builds with aerodynamic profiles for recreational cycling clusters in Abu Dhabi.
Commuter sits at the top of the volume ranking, with Folding climbing the fastest.
Battery Type:
Cost tier stratification separates premium energy density configurations from budget alternatives, with replacement cycle economics determining total ownership calculations in extreme-climate operating conditions.
- Lithium-Ion:NMC cell chemistry delivers energy density exceeding 250 Wh/kg, extending range thresholds beyond 80 kilometers in 40-degree ambient conditions. Commercial delivery operators in Riyadh are piloting swapping networks that eliminate charging downtime and shift capital expenditure from fleets to infrastructure providers.
- Lithium Polymer:Pouch-cell configurations enable custom form factors for frame integration in premium commuter lines. Abu Dhabi municipal micromobility permits are creating regulated channel access for shared fleet operators previously blocked by public transport monopolies.
- Lead Acid:Entry-level price points for price-sensitive consumer segments in secondary Gulf cities.
- Nickel-Metal Hydride:Legacy installations in early-generation fleet vehicles awaiting replacement cycles.
Lithium-Ion captures the dominant revenue share, while Lithium Polymer gains share fastest among new fleet procurements.
Power Rating:
Application intensity separates commercial fleet specifications from consumer-grade alternatives, with torque requirements and thermal load profiles determining motor-drive system selection.
- 750W:High-torque configurations designed for desert heat cycling with enhanced controller thermal management. Specialized Bicycle Components anchors premium positioning through powertrains rated for sustained output in ambient temperatures exceeding 45 degrees Celsius.
- 500W:Mid-range specification balancing acceleration response with battery conservation for mixed urban terrain. Giant Manufacturing leverages integrated motor-drive systems to anchor commuter lines across Dubai and Abu Dhabi retail networks.
- 250W:Entry-level pedal-assist for flat urban corridors and regulatory compliance in restricted zones.
- 1000W:Heavy-load cargo configurations for commercial delivery fleets operating in hilly terrain.
750W leads commercial fleet specifications, with 500W expanding most quickly in employer subsidy programs.
Sales Channel:
Customer type fragmentation separates high-touch service requirements from transactional procurement patterns, with after-sales support capabilities determining channel viability in extreme-climate operating environments.
- Specialty Stores:Trek Bicycle Corporation competes through controlled service networks in Riyadh and Jeddah, with technician training programs addressing thermal management engineering talent scarcity. Battery pack design expertise for extreme-climate applications remains concentrated in East Asian and European labor markets.
- Distributors:B2B procurement consolidation around last-mile delivery fleets is compressing sales cycles and forcing inventory reconfiguration toward high-utilization commercial operators. Import certification friction from UAE battery safety testing protocols adds 8-12 week clearance timelines that strain just-in-time deployment schedules.
- Online Retail:Direct-to-consumer platforms penetrating price-sensitive segments with limited service requirements.
- Supermarkets:Mass-market impulse purchases for entry-level commuter specifications.
Distributors command the dominant transaction value, with Specialty Stores deepening margin capture through service attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's fleet electrification mandates are outpacing UAE infrastructure buildout, while smaller Gulf states are importing regulatory frameworks rather than developing indigenous certification regimes.
United Arab Emirates
Dubai's last-mile delivery operators and Abu Dhabi's municipal micromobility permits are driving commercial procurement. MOHAP battery safety protocols and RTA cycling lane mandates shape fleet specifications. Dubai anchors the GCC's densest charging and parking infrastructure network.
Saudi Arabia
Vision 2030 transport privatization is opening state-protected routes to private fleet operators. SASO motor power limits and connector specifications diverge from UAE requirements, fragmenting regional product portfolios. Riyadh and Jeddah concentrate employer subsidy program adoption.
Qatar
World Cup legacy infrastructure and Doha Metro feeder integration are creating captive demand corridors. The country's national standards body is adopting GCC harmonized certification to accelerate import clearance. Lusail City hosts pilot battery swapping networks for commercial operators.
Kuwait
Congestion pricing discussions and urban heat island mitigation policies are shifting municipal procurement toward electric two-wheelers. The central transport authority is studying Dubai's RTA cycling lane specifications for adaptation. Kuwait City delivery fleets are trialing thermal-shielded battery configurations.
Israel
Tech sector employer mobility benefits and Tel Aviv metro expansion are displacing automobile allowances with e-bike leases. The Ministry of Transport maintains distinct motor power classifications from GCC regimes. Tel Aviv and Haifa host the region's most mature shared micromobility permit frameworks.
Middle-East E-Bike Market Competitive Landscape
Taiwanese producers anchor the integrated motor-drive tier; European specialists hold premium positioning through thermal engineering capabilities. Market structure concentrates around three strategic archetypes: vertically integrated Asian manufacturers controlling component supply, European engineering houses commanding service-attachment premiums, and GCC-based distributors consolidating fleet procurement relationships. Competitive moves center on backward integration into battery pack assembly and geographic expansion through distributor acquisition.
Among Taiwan-based fabricators, Giant Manufacturing Co. Ltd. exemplifies scale-driven motor-drive integration. Trek Bicycle Corporation and Specialized Bicycle Components occupy positions within the premium engineering tier, representing divergent approaches to extreme-climate product development. These three anchors illustrate the market's fundamental segmentation between component control and application-specific thermal management expertise.
| Leading Market Players |
|---|
| Giant Manufacturing Co. Ltd. |
| Trek Bicycle Corporation |
| Mercedes-Benz |
| Accell Group |
| Riese & Müller |
| TIER Mobility AG |
| myStromer AG |
| Specialized Bicycle Components |
| Propella |
| Others |
Supply & Pricing Matrix
Lithium-ion cell chemistry advances are compressing cost structures across Gulf assembly operations while simultaneously concentrating procurement leverage among Chinese battery pack suppliers. This dual shift tightens margins for distributors even as it expands addressable demand for thermal-managed configurations in Saudi and UAE fleet deployments.
Pricing Analysis
Capacity additions in Chinese NMC cell production are reshaping price floors for Middle-East e-bike battery configurations. Three-tier pricing structure across premium thermal-shielded, standard commuter, and economy lead-acid tiers separates fleet operators from retail consumers. Cost compression in the standard tier is intensifying because SASO and UAE certification divergence forces duplicate testing runs. Last-mile delivery fleets show the lowest price sensitivity due to total-cost-of-ownership calculations, while individual commuters in secondary Gulf cities remain highly price-sensitive.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese, South Korean, and Japanese specialty chemical producers with limited alternative sourcing. Motor-drive systems, controller electronics, and thermal management hardware feed from East Asian component clusters. Single-source vulnerability through the Strait of Hormuz creates exposure to shipping disruptions that could idle Gulf assembly plants. Distribution runs through Dubai-based distributors consolidating B2B fleet procurement and Jeddah specialty retailers controlling service attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle-East e-bike market entry functions as a regulatory-arbitrage play: SASO motor power limits diverge from UAE requirements, creating portfolio fragmentation costs that favor local assembly over pure import strategies.
For Market Incumbents: Anchor service network density in Riyadh and Jeddah to defend against emerging direct-to-consumer platforms. SASO standards harmonization pressure threatens product portfolio complexity; backward integration into battery pack assembly reduces exposure to Chinese supplier concentration. Thermal management engineering talent scarcity in the GCC forces either technical training investments or European partnership structures. For New Entrants and Emerging Players: Battery swapping infrastructure technology offers a wedge against incumbent fleet relationships currently tethered to charging-downtime economics. Kuwait congestion pricing discussions and employer subsidy penetration in Jeddah represent the most penetrable white-space corridors. A distributor-acquisition go-to-market angle bypasses the 8-12 week UAE import certification friction that strains just-in-time deployment. For Investors and Strategic Acquirers: Roll-up economics work for Dubai-based distributors with established fleet procurement relationships because Vision 2030 privatization mandates guarantee offtake floors that de-risk inventory positions. Acquisition targets should show thermal-management service capabilities and SASO certification expertise. Battery chemistry announcements from Chinese suppliers warrant ongoing watch as inflection indicators for replacement cycle economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Infrastructure Deployment | Eliminates charging downtime for Riyadh commercial fleets and shifts capital expenditure to infrastructure providers. |
| Thermal Management R&D Partnership | Addresses 45-degree Celsius capacity fade through European engineering house collaboration on NMC cell configurations. |
| SASO Certification Pre-Investment | Reduces 8-12 week clearance timelines that strain just-in-time fleet deployment schedules in Saudi Arabia. |
| Distributor Acquisition in UAE Corridor | Captures Dubai RTA cycling lane mandates embedding dedicated parking infrastructure at metro stations. |
| Employer Subsidy Program Integration | Penetrates Jeddah professional services verticals displacing automobile allowances with bundled lease contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged fleet operations managers at Dubai and Riyadh delivery companies, procurement leads at GCC-based distributors, thermal engineering specialists at European component suppliers, and regulatory affairs officers navigating SASO and UAE Ministry of Energy certification protocols. Secondary validation drew from customs import records, SASO technical standards publications, RTA infrastructure planning documents, and Vision 2030 transport privatization timelines. Bottom-up fleet deployment tracking and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the projection horizon to documented procurement cycles and infrastructure buildout phases. Segmentation modeling spanned product type, battery chemistry tier, power rating band, and sales channel structure alongside climate-adaptation requirement intensity. CAGRs derived from fitted trend extrapolation cross-checked against fleet electrification mandate schedules and employer subsidy program adoption curves. Lithium-ion energy density improvement trajectories and thermal degradation replacement cycle frequencies fed directly into forecast mechanics.
The model holds under sustained Vision 2030 privatization timelines and stable Strait of Hormuz logistics; deviation in battery chemistry cost curves or GCC regulatory harmonization would shift distributor margin structures. Forecasts reflect documented assumptions about employer subsidy penetration rates and metro feeder integration completion. Certification timeline extensions and Chinese supplier concentration risks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Golf Cart Battery Market