
 Global Electric Cars Market | 2026-2036
Global Electric Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Cars Market Foresight
China's gigafactory corridor is reshaping cost curves across the electric vehicle value chain. Tesla leverages its integrated battery-cell architecture to sustain margin advantages in premium segments. BYD anchors its position through in-house production of lithium iron phosphate cells and semiconductor components. Volkswagen Group competes by extending its MEB platform across multiple brands and price tiers.
Electric cars are road vehicles propelled by one or more electric motors drawing energy from rechargeable battery packs, with energy density typically measured in watt-hours per kilogram and thermal management systems governing cell longevity. Their primary purpose is to displace internal combustion engines for passenger and light commercial transport while eliminating tailpipe emissions. Battery Electric Vehicles occupy the dominant share of unit volume as cell costs decline and charging infrastructure proliferates. Plug-in Hybrid Electric Vehicles retain structural importance in markets where range anxiety persists and grid reliability remains uneven. Solid-state battery chemistry represents the fastest-growing technology segment as manufacturers pursue higher energy density and reduced fire risk.
The US EPA tailpipe standards, the EU Green Deal vehicle CO2 targets, and China's MIIT new energy vehicle mandates collectively mandate electrification timelines that manufacturers cannot defer. These frameworks shape demand by restricting internal combustion sales, subsidizing battery purchases, and penalizing fleet-average emissions. Stakeholders must monitor regulatory phase-out calendars and subsidy taper schedules to calibrate capacity investments against policy-driven demand cliffs.
Market Dynamics
The solid-state battery transition is compressing charging infrastructure requirements while extending vehicle range, forcing manufacturers to reconfigure cell chemistry roadmaps and thermal management architectures ahead of 2030 regulatory deadlines.
Growth Catalysts
- EU Green Deal vehicle CO2 targets:The framework mandates fleet-average emissions reductions that manufacturers cannot achieve without battery electric vehicle volume expansion. OEMs accelerate platform electrification to avoid penalties.
- Last-mile delivery electrification:Fleet operators in logistics and urban freight deploy battery electric vans and light trucks to comply with municipal zero-emission zones. This segment absorbs mid-size battery pack output.
- Lithium iron phosphate chemistry:Cell producers in China scale LFP production for cost-sensitive vehicle tiers. The chemistry reduces nickel and cobalt dependency while improving cycle life for commercial applications.
Market Restraints
- Critical mineral supply concentration:Cobalt and lithium processing capacity concentrates in the Democratic Republic of Congo and Chile. Geopolitical disruption or export restrictions would constrain cell manufacturing output.
- Charging infrastructure deployment lag:Grid interconnection queues and utility upgrade timelines delay fast-charging hub commissioning. Range anxiety persists in multi-unit residential areas without dedicated parking.
- Cell cost floor:Raw material volatility and energy-intensive cathode production prevent further battery pack cost declines. Price parity with internal combustion engines remains elusive in entry vehicle segments.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives attract battery and electric vehicle assembly investment. Domestic manufacturing capacity addresses import dependency while serving South Asian demand.
- Vehicle-to-grid integration:Bidirectional charging hardware enables electric cars to function as distributed storage assets. Utilities in Germany and California pilot aggregated fleet participation in frequency regulation markets.
- Solid-state electrolyte commercialization:Toyota and Samsung SDI advance sulfide-based cell architectures. Higher energy density enables extended-range platforms without pack weight penalties.
Industry Challenges
- Battery thermal runaway mitigation:Cell manufacturers must validate propagation prevention across module and pack architectures. Regulatory bodies in China and the United States tighten testing protocols for passenger safety certification.
- Power electronics talent scarcity:Semiconductor design and packaging expertise for inverter and onboard charger production concentrates in Taiwan and South Korea. OEMs compete for engineering capacity to develop 800-volt architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Cars Market |
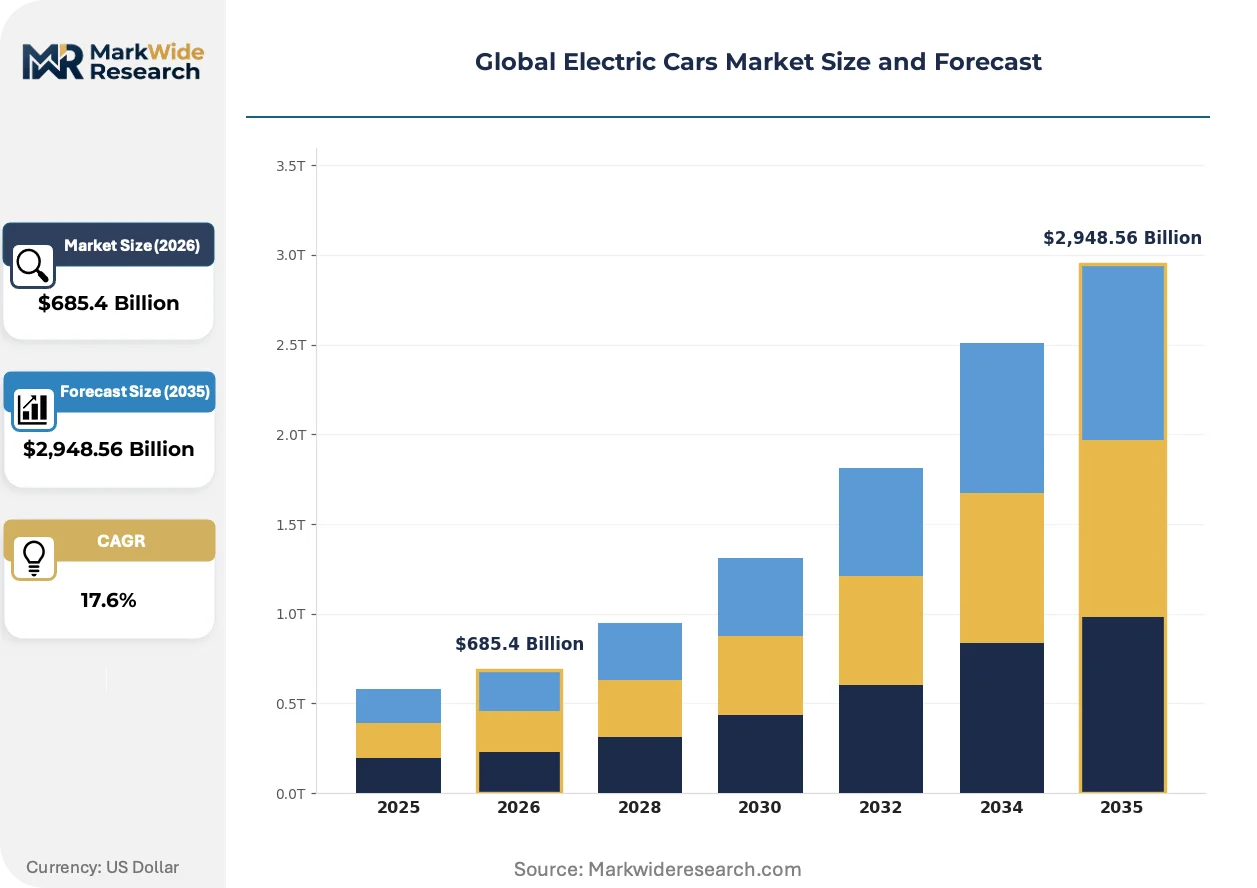
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $2,948.56 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Extended Range Electric Vehicles Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead Acid, Lithium Polymer Application: Personal Transport, Ride-Hailing Services, Car Sharing, Delivery Services, Government Fleets End User: Individual Consumers, Corporate Fleets, Leasing Companies, Rental Agencies |
| Companies Covered | Tesla, BYD, Geely Holdings, General Motors, Ford, Volkswagen Group, Toyota, Hyundai-Kia, Rivian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Cars Market Shifts & Advancements
Battery chemistry roadmaps, charging infrastructure topology, and software-defined vehicle architectures are converging to reshape how electric cars are engineered, sold, and operated across passenger and commercial segments.
Solid-state battery technology is migrating from laboratory validation to pilot production lines. Sulfide and oxide electrolyte formulations promise energy density exceeding 400 watt-hours per kilogram. Premium passenger vehicle segments adopt these cells first to justify cost premiums through range extension. The technology is migrating from niche aerospace applications toward mainstream automotive platforms.
The US EPA tailpipe standards and California's Advanced Clean Cars II regulation mandate zero-emission vehicle sales percentages that escalate through 2035. Manufacturers cannot comply through plug-in hybrid volumes alone. Battery electric vehicle production quotas force platform consolidation and supplier contract restructuring. The United States market responds with dedicated electric truck and SUV architectures.
Fleet procurement is consolidating around total cost of ownership models rather than sticker price. Logistics operators calculate energy, maintenance, and residual value differentials across battery electric and internal combustion alternatives. Leasing structures and battery-as-a-service contracts displace traditional ownership in European commercial vehicle channels. Germany and the Netherlands exhibit the fastest contract restructuring.
Global Electric Cars Market Segmentation
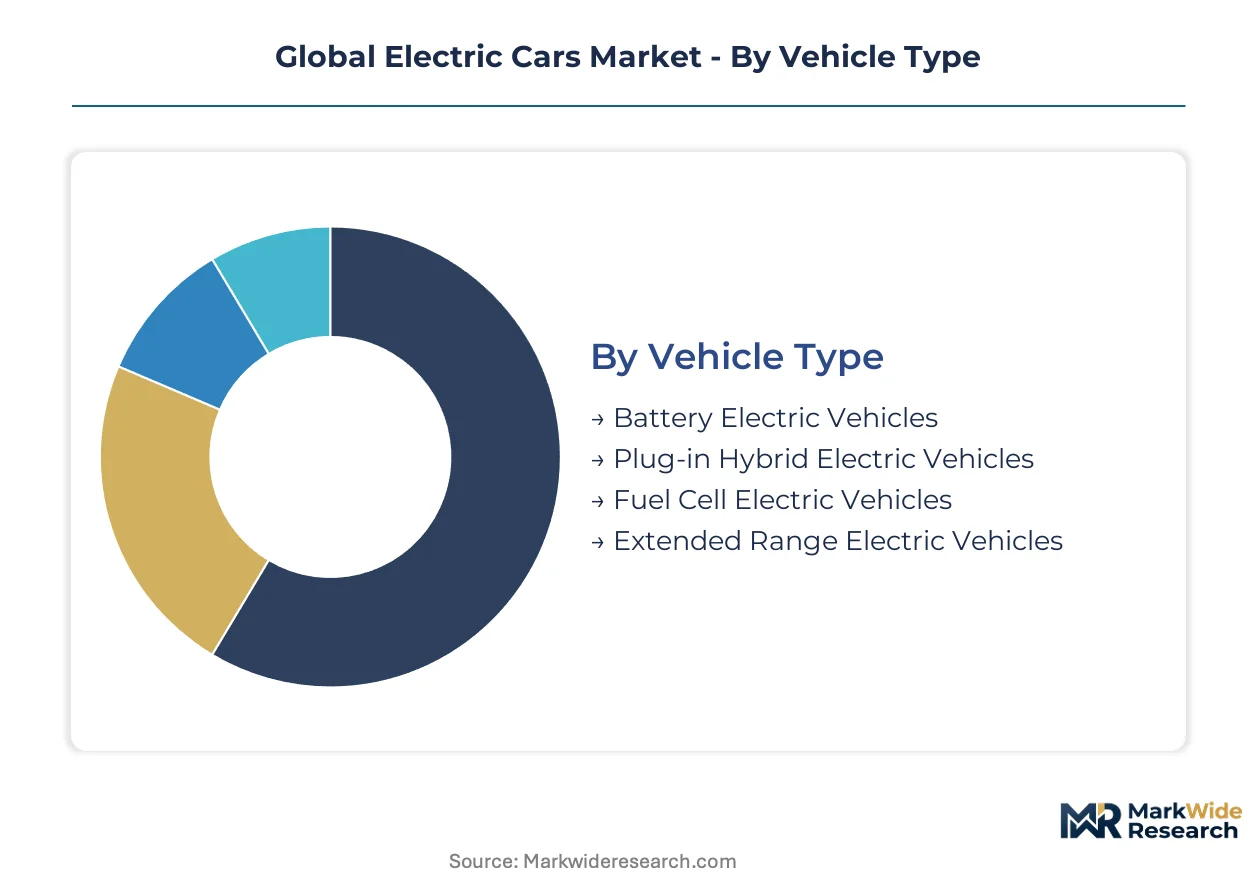
Segmentation reveals how electrification pathways diverge across use cases and powertrain architectures. Battery chemistry choices and fleet procurement models determine margin structures and supplier relationships for manufacturers.
Vehicle Type:
Product cycles stretch from eighteen months for mass-market battery platforms to seven-year horizons for fuel cell architectures still awaiting infrastructure maturation.
- Battery Electric Vehicles:Pure electric powertrains with lithium-ion or solid-state cell packs deliver zero tailpipe emissions. Demand concentrates in China, Germany, and California where MIIT, EU Green Deal, and EPA regulations mandate phase-outs of combustion engines. Cell cost declines and charging infrastructure density sustain volume leadership.
- Plug-in Hybrid Electric Vehicles:Dual powertrain systems combining electric motors with range-extending combustion engines address residual range anxiety. Corporate fleets in the United States and European urban centers deploy PHEVs where charging infrastructure remains uneven. Regulatory treatment under EPA and EU CO2 frameworks preserves structural importance through the mid-decade transition.
- Fuel Cell Electric Vehicles:Hydrogen fuel cell stacks generate electricity onboard for extended-range commercial transport. Japan's METI hydrogen roadmap and South Korean cluster investments anchor early adoption in heavy-duty segments.
- Extended Range Electric Vehicles:Series-hybrid architectures with combustion engines functioning solely as generators. Premium passenger segments in China and the United States adopt E-REV configurations for luxury positioning without range compromise.
Battery Electric Vehicles anchor the volume base while Solid-State variants within BEV architectures gain share at the steepest rate as Toyota and Samsung SDI accelerate pilot production.
Battery Technology:
Cost tiers separate premium energy density applications from commoditized commercial vehicle packs.
- Lithium-Ion:Nickel-cobalt-manganese and lithium iron phosphate chemistries dominate current production. LFP variants from BYD and CATL capture cost-sensitive vehicle tiers in China. Raw material volatility in Congolese cobalt and Chilean lithium concentrates supply risk.
- Solid-State:Sulfide and oxide electrolyte formulations exceed 400 watt-hours per kilogram energy density. Toyota's pilot lines and Samsung SDI manufacturing investments target premium passenger segments first. Thermal stability eliminates propagation risks that constrain conventional pack architectures.
- Nickel-Metal Hydride:Mature chemistry retained in select hybrid applications where cycling durability outweighs energy density requirements. Toyota's Prius platform sustains residual demand.
- Lead Acid:Auxiliary power applications and low-speed electric vehicles in emerging markets. India's PLI scheme for automotive excludes lead chemistry from incentive eligibility.
- Lithium Polymer:Pouch cell formats enabling flexible pack geometries for performance-oriented platforms. Limited automotive adoption due to cost premiums relative to cylindrical and prismatic alternatives.
Lithium-Ion configurations retain volume dominance while Solid-State chemistries climb the fastest as manufacturers reconfigure roadmaps ahead of 2030 regulatory deadlines.
Application:
Customer procurement cycles compress from multi-year fleet tenders to individual consumer purchases with minimal negotiation leverage.
- Personal Transport:Individual ownership models across passenger car and light SUV segments. China's tier-one cities and Germany's metropolitan corridors drive replacement demand as combustion bans approach.
- Ride-Hailing Services:High-utilization platforms requiring rapid-charging compatibility and durability validation. Uber and Didi deployment mandates in California and Beijing accelerate specific model certification.
- Car Sharing:Station-based and free-floating fleets optimizing for trip frequency over range. Amsterdam and Paris municipal contracts specify compact BEV architectures with bidirectional charging capability.
- Delivery Services:Last-mile logistics operators in Amazon, DHL, and regional postal services electrify van and light truck segments. EU Green Deal vehicle CO2 targets and municipal zero-emission zones compel procurement timelines.
- Government Fleets:Federal, state, and municipal procurement with domestic content requirements. United States General Services Administration and China's state-owned enterprise purchasing directives shape supplier qualification.
Personal Transport sustains the installed base while Delivery Services expands most quickly as logistics operators restructure total cost of ownership models.
End User:
Volume concentration shifts from fragmented retail channels toward consolidated fleet procurement with standardized specifications.
- Individual Consumers:Retail purchasers sensitive to sticker price, charging access, and residual value uncertainty. Multi-unit residential dwellers in European and North American cities face infrastructure deployment lags.
- Corporate Fleets:Commercial operators calculating total cost of ownership across energy, maintenance, and depreciation. Germany and Netherlands leasing structures displace traditional ownership in European channels.
- Leasing Companies:Financial intermediaries managing residual value risk and remarketing pathways. Battery state-of-health certification standards from China's MIIT and US NHTSA influence contract pricing.
- Rental Agencies:Short-term mobility providers with high turnover utilization models. Hertz and Enterprise fleet electrification in the United States and Europe drives specific fast-charging infrastructure partnerships.
Individual Consumers anchor volume contribution while Corporate Fleets gains share at the steepest rate as procurement consolidates around operational cost metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys battery electric vehicles for mass-market personal transport, while Germany and the United States concentrate procurement around corporate fleet channels and premium passenger segments. Regulatory frameworks and infrastructure maturity create distinct consumption patterns across major automotive markets.
China
MIIT new energy vehicle mandates and municipal license plate restrictions in Beijing and Shanghai accelerate battery electric vehicle replacement cycles. The dual carbon goals framework imposes manufacturer electrification quotas that tighten annually through 2035. Shenzhen and Shanghai anchor the Yangtze River Delta and Pearl River Delta manufacturing clusters where CATL and BYD operate integrated gigafactory corridors.
Germany
Corporate fleet operators in Munich and Stuttgart restructure total cost of ownership models around battery electric vans and executive sedans. The EU Green Deal vehicle CO2 targets enforce fleet-average emissions reductions that manufacturers cannot defer. Bavaria and Baden-Württemberg concentrate Volkswagen Group and BMW engineering centers alongside North Rhine-Westphalia charging infrastructure deployment.
United States
EPA tailpipe standards and California's Advanced Clean Cars II regulation mandate zero-emission vehicle sales percentages that escalate through 2035. The Inflation Reduction Act domestic content provisions reshape supplier qualification for federal fleet procurement. Michigan and Texas anchor battery assembly investments while California's Los Angeles Basin and San Francisco Bay Area drive consumer uptake.
South Korea
Hyundai-Kia and Samsung SDI accelerate solid-state battery pilot production targeting premium export markets. METI hydrogen roadmap coordination influences fuel cell commercial vehicle development for heavy-duty segments. The Seoul Capital Area and Busan-Ulsan industrial corridor concentrate cell manufacturing and vehicle assembly capacity.
India
Maharashtra and Gujarat absorb PLI scheme for automotive incentives attracting battery and electric vehicle assembly investment. Delhi-NCR municipal zero-emission zones compel last-mile delivery fleet electrification for logistics operators. The country's national automotive regulator tightens safety certification protocols for lithium-ion pack architectures.
Global Electric Cars Market Competitive Landscape
Capability concentration sits with integrated battery-cell architects; scale advantage sits with platform-sharing conglomerates. The vendor base organizes around three tiers: vertically integrated specialists controlling semiconductor and cell production, multi-brand OEMs leveraging shared modular architectures, and pure-play electric entrants targeting fleet channels. Dominant competitive moves include backward integration into cathode materials and strategic partnerships for charging network access.
Within the integrated specialist tier, Tesla and BYD occupy positions defined by captive battery supply chains and in-house semiconductor design. Volkswagen Group exemplifies the multi-brand platform strategy, extending modular electric drive matrix architectures across price tiers. Among pure-play entrants, Rivian anchors the commercial fleet vector with dedicated last-mile delivery configurations. Toyota represents the solid-state transition archetype, advancing sulfide electrolyte pilot lines ahead of 2030 regulatory deadlines.
| Leading Market Players |
|---|
| Tesla |
| BYD |
| Geely Holdings |
| General Motors |
| Ford |
| Volkswagen Group |
| Toyota |
| Hyundai-Kia |
| Rivian |
| Others |
Supply & Pricing Matrix
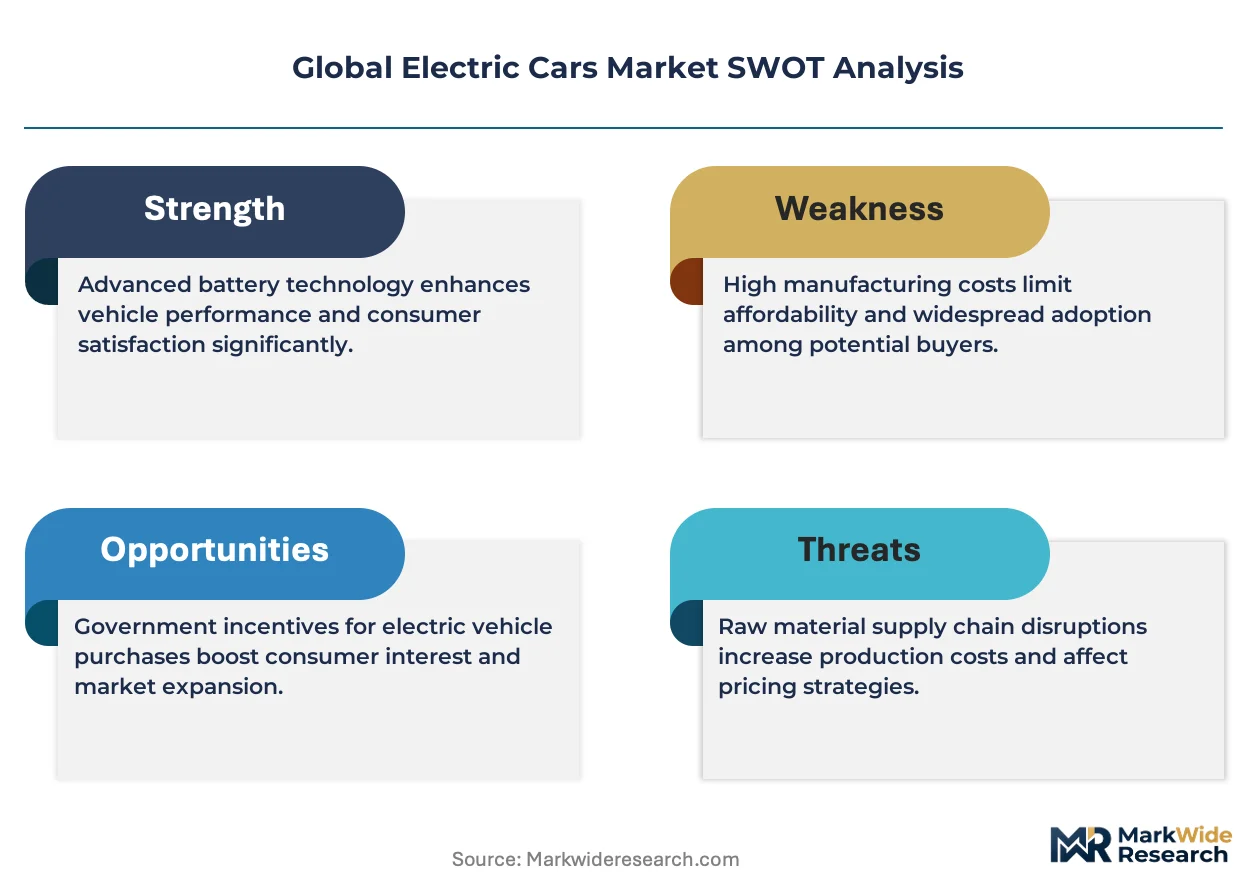
Overcapacity in China's gigafactory corridor is compressing cell pricing and forcing cathode producers to absorb margin erosion, while undercapacity in European fast-charging component assembly is inflating delivery premiums. Utilization differentials between these regions reshape how OEMs negotiate long-term offtake terms versus spot market exposure.
Pricing Analysis
Long-term offtake contracts dominate lithium-ion procurement, with CATL and BYD locking in volume commitments from Volkswagen Group and Tesla through multi-year cathode supply agreements. Price differentiation hinges on nickel content grade and MIIT safety certification tier, with NCM811 cells commanding premiums over LFP alternatives. Cost compression in entry vehicle segments is intensifying because BYD's in-house semiconductor production eliminates inverter markup. Fleet operators exhibit the highest price sensitivity, while premium passenger buyers absorb solid-state cell premiums for range extension.
Supply Chain Analysis
Contract manufacturing concentration sits with CATL, BYD, and Samsung SDI, which collectively hold pilot and mass-production capacity for cylindrical, prismatic, and pouch cell formats. Geographic supply concentration centers on China, South Korea, and Japan, with cathode active material processing anchored in Fujian and Hunan provinces. Raw material dependencies draw from Chilean lithium brine, Congolese cobalt hydroxide, and Indonesian nickel matte. Single-source vulnerability in sulfide electrolyte precursors threatens solid-state roadmaps. Distribution runs through OEM captive plants for integrated specialists and Tier 1 module assembly for platform-sharing conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards firms controlling scarce assets in power electronics design and solid-state electrolyte formulation, while punishing those dependent on commoditized cell assembly. Semiconductor packaging expertise for 800-volt architectures represents the critical capability gap separating viable competitors from margin-squeezed assemblers.
For Market Incumbents: Harden thermal management validation protocols ahead of tightened NHTSA and MIIT propagation testing standards. Secure captive cathode supply through equity stakes in Indonesian nickel processing or Chilean lithium offtake. Vertical integration into power electronics packaging mitigates Taiwan and South Korea talent scarcity. For New Entrants and Emerging Players: Establish a beachhead in India's last-mile delivery segment before PLI scheme incentives attract incumbent manufacturing footprints. Target municipal zero-emission zone compliance contracts in Delhi-NCR and European logistics corridors. Battery-as-a-service financing structures bypass residual value risk that blocks traditional fleet procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state pilot production lines, favoring early-stage equipment suppliers over cell manufacturers. Long-term viability hinges on differentiation in energy density and thermal stability rather than scale economics alone. Acquisition targets should exhibit sulfide electrolyte IP or 800-volt inverter design capacity. Quarterly review of MIIT subsidy taper schedules and EPA enforcement discretion is advised to detect demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL's long-term contracts with BMW secure NCM811 allocation for Munich-assembled executive sedans. |
| Platform Standardization | Volkswagen Group extends MEB architecture across Skoda, Seat, and Audi variants to amortize R&D. |
| Software-Defined Vehicle Investment | Tesla's over-the-air update capability sustains recurring revenue streams beyond initial vehicle sale. |
| Charging Infrastructure Partnership | Ionity's highway fast-charging network enables Mercedes-Benz premium positioning through exclusive access tiers. |
| Geographic Manufacturing Footprint | Tesla's Texas and Berlin gigafactories satisfy IRA domestic content provisions for federal fleet eligibility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OEM production filings, MIIT new energy vehicle registration databases, and IHS Markit vehicle assembly data. Interviews with Tier 1 supplier procurement directors, OEM platform engineers, cathode plant operations managers, and dealership fleet sales heads inform demand-side validation. Bottom-up cell production estimates triangulate against top-down regulatory mandate trajectories from EPA, EU Green Deal, and MIIT frameworks.
Forecast inputs include vehicle class segmentation across passenger, light commercial, and heavy-duty architectures; propulsion architecture splits between BEV, PHEV, and FCEV; and regional production cluster capacity utilization. CAGRs derive from regression against historical MIIT quota achievement rates and EU CO2 fleet compliance pathways. Solid-state commercialization timelines and charging infrastructure deployment velocity constitute industry-specific forecast inputs across the projection horizon.
Sensitivities concentrate around Congolese cobalt export restrictions, Chilean lithium royalty policy shifts, and EPA enforcement discretion on tailpipe standards. Forecasts reflect assumptions regarding cell cost decline trajectories and subsidy taper schedules without guaranteed realization. Quarterly review of CATL and BYD capacity utilization disclosures, plus NHTSA thermal runaway testing protocol updates, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Used EV Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market