
 Electric Vehicle NVH Material Market | 2026-2036
Electric Vehicle NVH Material Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle NVH Material Market Insights
The EU Green Deal is expanding the addressable market for bio-based and recycled-content NVH materials as automakers face binding carbon-footprint disclosure rules. BASF SE leverages its polyurethane chemistry portfolio to supply lightweight foam systems for battery pack encapsulation. Covestro AG anchors European supply through its polycarbonate-based acoustic composites, while Sumitomo Riko Company Limited dominates Asian OEM relationships with its rubber vibration-isolation expertise.
Electric Vehicle NVH Material encompasses engineered substrates—typically polymer foams, elastomeric composites, and constrained-layer viscoelastic sheets between 2-10 mm thickness—that attenuate structure-borne and airborne noise in battery-electric powertrains lacking internal-combustion masking frequencies. These materials must maintain acoustic performance across temperature cycles from -40°C to 120°C while adding minimal mass to range-sensitive vehicle architectures. Foams and composites capture the dominant share of material-type value as OEMs prioritize weight reduction over legacy mass-loaded vinyl solutions. Active Noise Control technology is gaining fastest penetration in premium platforms, though Passive Noise Control and vibration damping still absorb the majority of segment investment due to lower system cost and proven durability.
EPA noise emission standards and the EU F-Gas Regulation shape product development by restricting certain blowing agents in foam production and mandating end-of-life recyclability. China's MIIT publishes GB standards for passenger car interior noise that directly specify material test methods, creating compliance gateways for foreign suppliers. Stakeholders must monitor how REACH chemical restrictions and evolving battery-safety standards from NHTSA redefine permissible flame-retardant chemistries in cabin-facing acoustic layers.
Market Dynamics
Multi-layer acoustic packages are displacing legacy single-material NVH solutions as premium EV platforms pursue cabin silence targets below 35 decibels at highway speeds.
Growth Catalysts
- EU Green Deal carbon-footprint disclosure rules:Automakers must document cradle-to-grave emissions, creating procurement mandates for bio-based polyurethane foams and recycled-content elastomers in acoustic subsystems.
- Battery pack encapsulation demand:Cell-to-pack architectures require thermally stable NVH materials that simultaneously dampen road noise and manage thermal runaway propagation across temperature cycles.
- Shanghai and Shenzhen production clusters:BYD, NIO, and Xpeng are localizing NVH supply chains for export-grade vehicles, generating pull-through demand for regional foam and rubber damping system suppliers.
Market Restraints
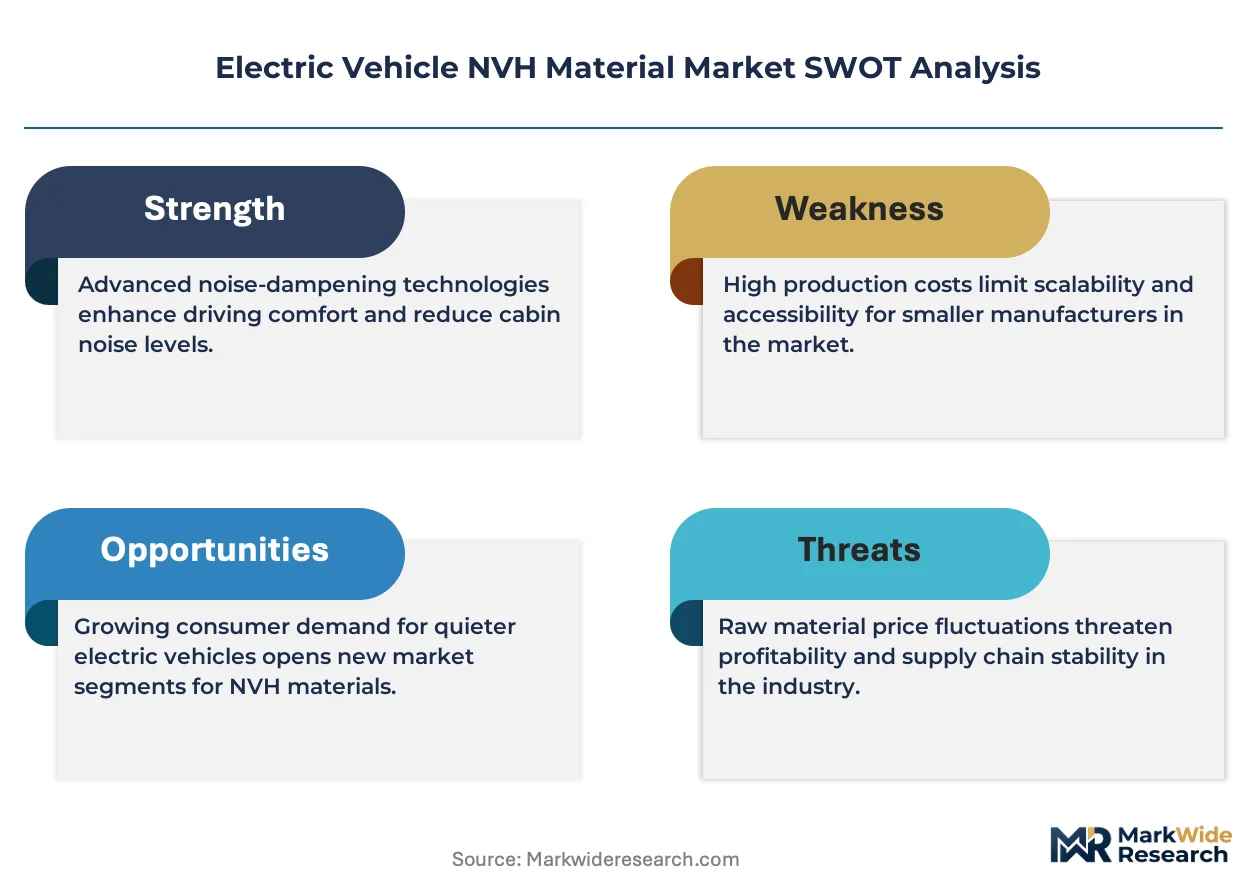
- Petrochemical feedstock volatility:Polyurethane precursor costs fluctuate with crude oil and natural gas benchmarks, compressing margins for foam converters serving price-sensitive mass-market EV programs.
- Constrained-layer viscoelastic supply concentration:Asian specialty chemical producers control 70% of high-performance adhesive formulations, creating single-source risk for European tier-1 acoustic module assemblers.
- REACH chemical restriction complexity:Evolving flame-retardant bans and SVHC candidate list updates force continuous reformulation of cabin-facing acoustic layers, extending qualification timelines by 12-18 months.
Strategic Opportunities
- India PLI scheme for advanced chemistry cell manufacturing:Domestic battery production scale-up creates virgin demand for localized NVH material supply, currently served entirely through imports.
- Active-passive hybrid noise control convergence:Integration of microphone-array-based cancellation with tuned-mass dampers opens premium tier pricing for suppliers with mechatronics capabilities.
- Direct-to-OEM digital procurement platforms:B2B marketplaces for engineered materials are compressing distributor layers, enabling compounders to capture margin previously allocated to regional stockists.
Industry Challenges
- Battery-safety standard harmonization:NHTSA thermal propagation test protocols and UN 38.3 shipping classifications impose conflicting material performance requirements, forcing parallel qualification tracks for single products.
- Acoustic engineer talent scarcity:OEMs and tier-1s compete for simulation specialists capable of multi-physics modeling (vibro-acoustic-thermal) across frequency ranges up to 8 kHz.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle NVH Material Market |
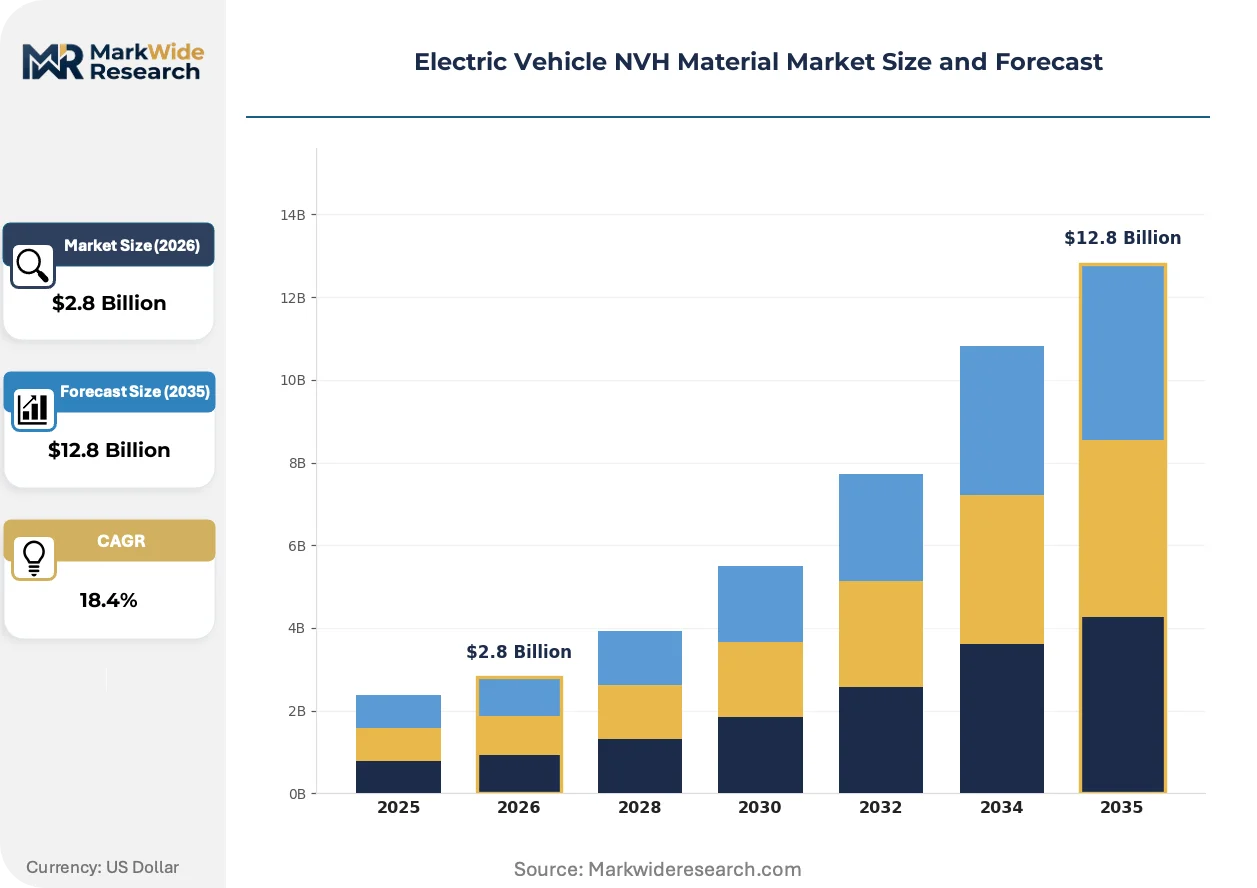
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Foams, Composites, Rubber, Mass Loaded Vinyl Technology: Active Noise Control, Passive Noise Control, Vibration Damping, Sound Absorption Application: Interior Noise Reduction, Exterior Noise Management, HVAC Noise Control, Structural Damping End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | 3M Company, BASF SE, Dow Inc., Covestro AG, Huntsman Corporation, Sumitomo Riko Company Limited, ElringKlinger AG, Autoneum, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle NVH Material Market Trends and Innovations
Material science advances are compressing the performance gap between lightweight foams and legacy mass-loaded barriers, enabling EV platforms to maintain acoustic targets without range penalty.
Aerogel-infused polyurethane foam is absorbing high-frequency tire noise while adding under 15% mass versus conventional melamine systems. Tesla and Mercedes-Benz specification teams have accelerated validation cycles for these materials from 24 months to 14 months. The technology is absorbing share from multi-layer asphaltic barriers in underbody applications where thermal insulation co-benefits justify premium pricing.
REACH SVHC candidate list expansion is forcing reformulation of halogenated flame retardants in cabin-facing acoustic layers. ECHA 2024-2025 consultations on organophosphate esters have triggered pre-emptive substitution programs across German and French supply bases. Foam compounders with non-halogenated phosphorus-nitrogen chemistry portfolios are capturing specification wins ahead of formal restriction dates.
Cellular vehicle architecture is compressing NVH material specification cycles from platform-based to program-based decisions. Chinese OEMs now release acoustic target cascades 8 months before traditional European timelines, forcing tier-1s to pre-position modular foam kits without finalized geometry data. This pattern is most visible in NIO and Xpeng development programs where battery-swap compatibility demands rapid iteration of pack-surrounding acoustic packages.
Electric Vehicle NVH Material Market Segmentation
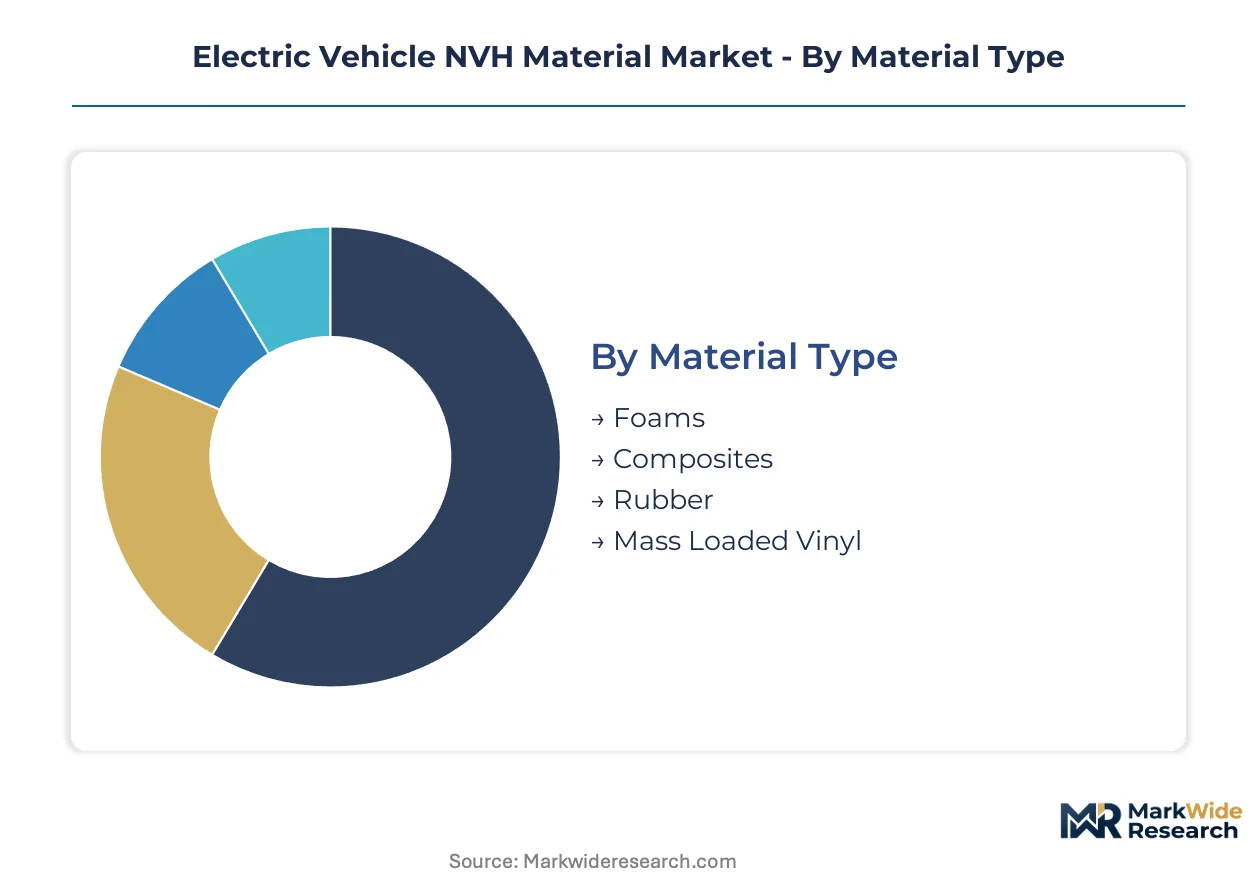
NVH material selection in electric vehicles hinges on balancing acoustic performance against mass penalties that directly erode range. Segmentation reveals how OEMs prioritize weight reduction in premium platforms while cost-constrained programs retain legacy solutions.
Material Type:
Polymer chemistry sophistication separates mass-market commodity supply from engineered formulations commanding specification premiums.
- Foams:Open-cell and closed-cell polyurethane systems dominate battery pack encapsulation and cabin liner applications. Shanghai and Shenzhen production clusters source localized foam supply for BYD, NIO, and Xpeng export programs, with thermally stable formulations now mandatory for cell-to-pack architectures.
- Composites:Polycarbonate-based acoustic laminates and fiber-reinforced layers deliver multi-frequency attenuation in floor pan and wheel arch applications. European OEMs specify these materials to meet EU Green Deal carbon-footprint disclosure rules, driving procurement mandates for recycled-content substrates.
- Rubber:EPDM and butyl compounds isolate powertrain mounts and suspension bushings.
- Mass Loaded Vinyl:Dense polymer sheets persist in budget EV platforms where range sensitivity is lower.
Gaining share fastest: Foams. Retaining volume leadership: Composites.
Technology:
Hardware-software integration intensity distinguishes premium tier supply from passive material-only offerings.
- Passive Noise Control:Multi-layer acoustic packages using constrained-layer viscoelastic sheets and tuned-mass dampers absorb structure-borne energy across the 50-500 Hz range. Tesla and Mercedes-Benz specification teams validate these systems for cabin silence targets below 35 decibels at highway speeds.
- Active Noise Control:Microphone-array-based cancellation algorithms paired with electromechanical actuators target low-frequency powertrain whine. Premium platforms from BMW and Mercedes-Benz accelerate adoption despite 40-60% system cost premiums over passive alternatives.
- Vibration Damping:Elastomeric isolators and hydraulic mounts attenuate road-induced oscillations.
- Sound Absorption:Porous materials dissipate airborne noise in headliner and pillar trim applications.
Commanding current investment majority: Passive Noise Control. Expanding most quickly: Active Noise Control.
Application:
Thermal-acoustic co-engineering requirements concentrate demand in battery-adjacent zones.
- Interior Noise Reduction:Headliner, carpet, and dashboard acoustic treatments target speech intelligibility and occupant comfort metrics. Chinese GB standards from MIIT specify interior noise test methods, creating compliance gateways for foreign suppliers seeking access to BYD and NIO supply chains.
- Exterior Noise Management:Underbody shields and wheel arch liners address tire roar and wind noise. Aerogel-infused polyurethane foam is displacing multi-layer asphaltic barriers here, with Tesla validation cycles compressing from 24 months to 14 months.
- HVAC Noise Control:Duct liners and blower housing treatments manage climate system tonal noise.
- Structural Damping:Body-in-white reinforcements reduce panel boom and drumming.
Generating highest material intensity per vehicle: Interior Noise Reduction. Fastest specification cycle compression: Exterior Noise Management.
End User:
Procurement authority concentration determines margin capture and technical dialogue access.
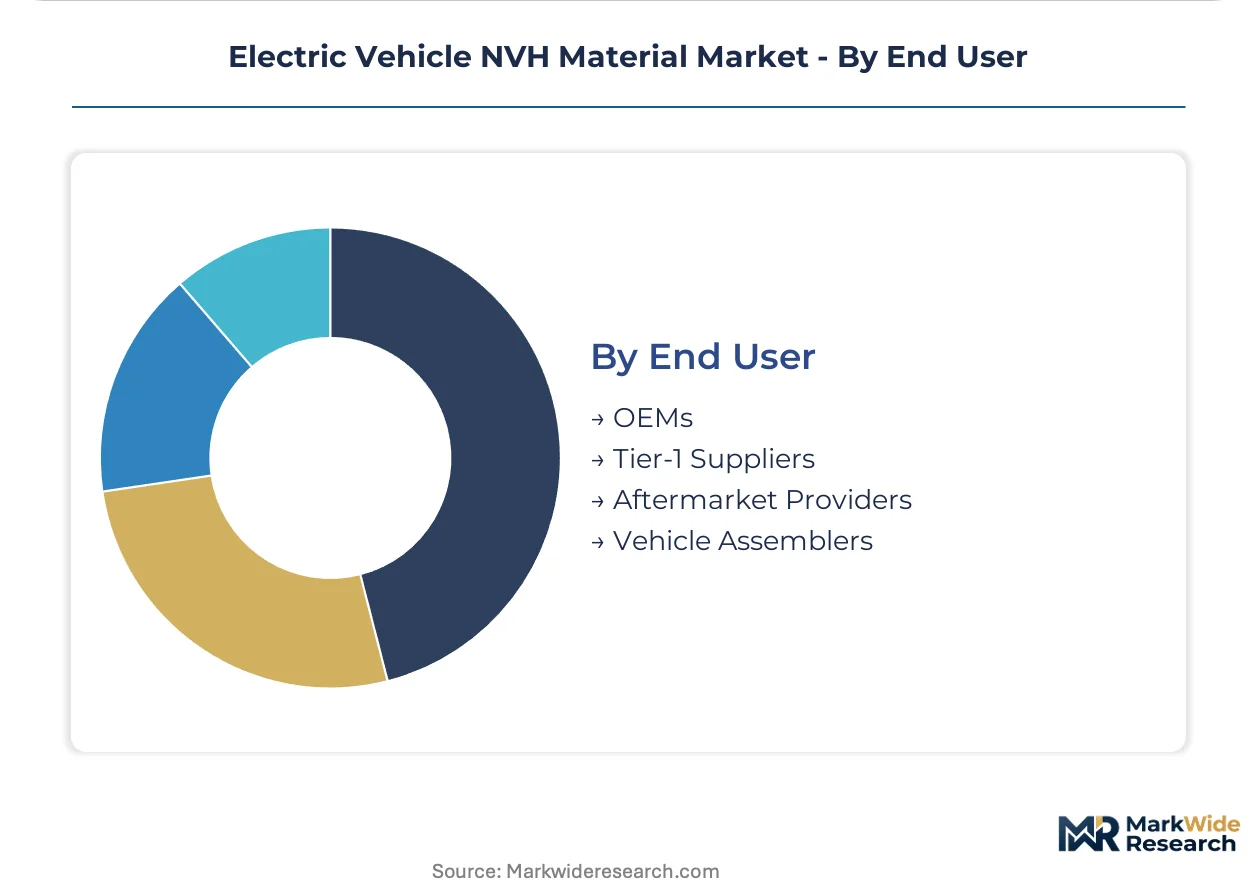
- OEMs:Tesla, BMW, and Mercedes-Benz acoustic engineering teams specify material chemistries directly, bypassing tier-1 converters for critical battery pack and cabin subsystems. Direct-to-OEM digital procurement platforms are compressing distributor layers, enabling compounders to capture margin previously allocated to regional stockists.
- Tier-1 Suppliers:Faurecia, Autoneum, and Adient assemble modular acoustic kits for programs where OEMs delegate subsystem integration. These suppliers face margin compression from petrochemical feedstock volatility in polyurethane precursor markets.
- Aftermarket Providers:Independent installers and e-commerce channels serve vehicle modification and repair demand.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities execute build-to-print specifications.
Holding specification authority: OEMs. Facing procurement channel disruption: Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of EV NVH materials consumed worldwide, yet Germany and the United States absorb disproportionate specification authority through their premium OEM engineering centers. This production-consumption divide shapes trade flows and technology licensing patterns across the industry.
China
Shanghai and Shenzhen production clusters supply localized foam and rubber damping systems for BYD, NIO, and Xpeng export programs. MIIT GB standards for passenger car interior noise specify material test methods, creating compliance gateways for foreign suppliers. Yangtze River Delta chemical parks concentrate polyurethane precursor manufacturing for battery pack encapsulation foams.
Germany
EU Green Deal carbon-footprint disclosure rules mandate cradle-to-grave emissions documentation, driving procurement of bio-based polyurethane foams and recycled-content elastomers. ECHA REACH consultations on organophosphate esters trigger pre-emptive flame-retardant substitution programs. Bavaria and Baden-Württemberg host acoustic engineering centers for BMW and Mercedes-Benz specification teams.
United States
EPA tailpipe noise standards tighten permissible decibel thresholds for electric powertrains, forcing material upgrades across domestic EV platforms. NHTSA thermal propagation test protocols impose battery-safety requirements that redefine permissible chemistries in cabin-facing acoustic layers. Michigan and California concentrate OEM acoustic engineering talent and tier-1 converter operations.
Japan
METI industrial policy supports advanced material development for next-generation EV platforms. JIS standards provide reference frameworks for acoustic performance testing adopted across Asian supply chains. Kansai region chemical producers, including Sumitomo Riko, maintain rubber vibration-isolation expertise serving regional OEM relationships.
India
PLI scheme incentives for advanced chemistry cell manufacturing create virgin demand for localized NVH material supply currently served through imports. BIS adoption of international test standards accelerates qualification pathways for foreign compounders. Tamil Nadu and Gujarat automotive corridors attract acoustic module assembly investments from global tier-1s.
Electric Vehicle NVH Material Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with polyurethane and elastomer portfolios. Three to five multinational material science groups capture premium specification slots through direct OEM relationships, while regional foam converters serve mass-market programs through tier-1 distributors. Strategic archetypes include integrated chemical producers with captive precursor supply, specialized acoustic module assemblers, and automotive-focused rubber compounders. Capacity expansion and backward integration into blowing-agent chemistry represent dominant competitive moves.
Among diversified chemical producers, BASF SE, Covestro AG, and Dow Inc. occupy positions defined by polymer chemistry breadth and geographic manufacturing footprints. BASF SE leverages polyurethane formulation expertise across European and Asian production networks. Covestro AG anchors supply relationships through polycarbonate-based material portfolios. Dow Inc. represents scale-driven supply capability with integrated petrochemical feedstock access. These conglomerates contrast with specialized players like Sumitomo Riko Company Limited, which sits within the rubber vibration-isolation segment through elastomeric expertise, and 3M Company, which exemplifies technology-differentiated positioning through adhesive and acoustic laminate portfolios. Tier-1 module assemblers including Autoneum and ElringKlinger AG face margin pressure from feedstock volatility while defending specification influence through integrated design-and-build capabilities.
| Leading Market Players |
|---|
| 3M Company |
| BASF SE |
| Dow Inc. |
| Covestro AG |
| Huntsman Corporation |
| Sumitomo Riko Company Limited |
| ElringKlinger AG |
| Autoneum |
| Exxon Mobil Corporation |
| Others |
Pricing and Supply Chain Analysis
Premium EV platform procurement teams from Tesla, BMW, and Mercedes-Benz command specification authority that compresses tier-1 converter margins while enabling compounders to capture value through direct digital channels. This buyer concentration creates asymmetric pricing power where acoustic performance guarantees override pure cost competition in battery-adjacent applications.
Pricing Analysis
Margin tightening in mass-market EV programs reflects petrochemical feedstock volatility in polyurethane precursor markets. Three-tier pricing structure across premium, standard, and economy levels separates aerogel-infused foam systems from conventional melamine and mass-loaded vinyl alternatives. Cost-down pressure on tier-1 converters accelerates because OEMs delegate subsystem integration to capture design efficiencies. Government fleet buyers exhibit highest price sensitivity; luxury platform engineering teams demonstrate least.
Supply Chain Analysis
Polyurethane blowing-agent chemistry rests on German, Chinese, and Japanese specialty chemical producers controlling formulation IP. Raw material dependencies include MDI precursors, polycarbonate resins, and EPDM rubber compounds. Single-source vulnerability concentrates in high-performance adhesive formulations where Asian producers hold 70% share. Distribution runs through tier-1 acoustic module assemblers serving OEM platform engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock volatility and REACH chemical restriction complexity are forcing consolidation among foam converters lacking backward integration into precursor supply. Surviving players will capture specification slots through direct OEM relationships and non-halogenated chemistry portfolios.
For Market Incumbents: Cement specification influence by pre-positioning modular foam kits ahead of Chinese OEM release cycles. Deepen upstream control over blowing-agent chemistry to defend margin position against petrochemical volatility. Invest in non-halogenated phosphorus-nitrogen portfolios ahead of formal ECHA restriction dates.
For New Entrants and Emerging Players: Capture white-space in India's PLI-driven advanced chemistry cell manufacturing corridor, currently import-dependent for NVH supply. Target aftermarket acoustic retrofit demand from independent installers and e-commerce channels. Lead with B2B marketplace positioning to bypass entrenched distributor layers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized acoustic module assemblers with integrated design-and-build capabilities in European regulatory jurisdictions. Long-term viability hinges on qualification timelines compressing from 24 months toward 14 months. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for substitution program acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Captive MDI supply insulates BASF and Covestro from crude oil benchmark volatility. |
| Direct-to-OEM Digital Procurement Platform | B2B marketplaces enable compounders to disintermediate regional foam distributors. |
| Non-Halogenated Flame Retardant Portfolio | ECHA organophosphate consultations trigger pre-emptive specification wins ahead of bans. |
| Modular Foam Kit Pre-Positioning | Tier-1s supply NIO and Xpeng programs without finalized geometry data from cellular architectures. |
| India Manufacturing Footprint Establishment | PLI scheme incentives attract acoustic module assembly to Tamil Nadu and Gujarat corridors. |
Research Methodology
Multi-period observation of specification cycle compression, REACH regulatory trajectory, and cell-to-pack architecture adoption anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-1 acoustic module procurement leads, polyurethane compounder technical directors, and aftermarket distribution channel managers. Secondary validation drew from MIIT GB standard publications, ECHA restriction consultations, EPA noise emission filings, customs trade data for polyurethane precursor flows, and SEC 10-K disclosures from diversified chemical producers. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Segment-weighting across material type, technology intensity, application zone, and end-user procurement authority shaped the analytical framework. Modeled dimensions included foam versus composite versus rubber chemistry tiers, passive versus active noise control hardware integration, battery-adjacent versus cabin-facing application zones, and OEM-direct versus tier-1-mediated purchasing channels. CAGRs derived from elasticity modeling of NVH content per vehicle against EV production ramp curves. Forecast inputs incorporated thermal runaway propagation test protocol evolution and carbon-footprint disclosure rule implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-safety standard harmonization conflicts between NHTSA and UN protocols, acoustic engineer talent scarcity constraining simulation throughput, and potential REACH flame-retardant bans extending qualification timelines. A small set of triggers—ECHA SVHC list velocity, India PLI scheme disbursement pacing, and Chinese OEM export program acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-SUV Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market