
 Electric Commercial Vehicle Market | 2026-2036
Electric Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Commercial Vehicle Market Intelligence
Market Context
Cell-to-pack battery architecture is tilting commercial EV design away from modular pack assemblies toward integrated floorpan structures. BYD leverages in-house lithium-iron-phosphate cell production to control vertical costs across its bus and truck portfolio. Daimler Truck AG anchors European heavy-duty electrification through its Mercedes-Benz eActros and Freightliner eCascadia platforms. Tesla competes on energy density and software-integrated powertrain management for its Semi program.
Technical Definition and Segment Structure
An electric commercial vehicle is a battery-electric or fuel-cell-electric truck, van, or bus engineered for freight, logistics, or passenger transport duty cycles, typically requiring continuous power output above 75 kW and gross vehicle weights exceeding 3.5 tonnes. Light-duty delivery trucks and medium-duty vans lead present volume due to predictable route profiles and accessible charging infrastructure, while heavy-duty buses command premium pricing through extended-range battery configurations. Solid-state battery technology occupies the fastest-growing technology tier as manufacturers pursue energy density above 400 Wh per kilogram to extend freight haul distances. Last-mile delivery applications sustain the broadest addressable customer base among fleet operators and logistics providers seeking depot-charging simplicity.
Regulatory Framework and Outlook
The EPA, EU Green Deal, and China's MIIT collectively enforce escalating emissions ceilings and zero-emission vehicle mandates that constrain diesel truck registrations across North America, Europe, and East Asia. NHTSA and ECHA standards on battery safety and end-of-life chemical handling add compliance layers that favor established manufacturers with certified testing protocols. Stakeholders must monitor subsidy phase-out schedules and charging infrastructure deployment timelines to time fleet conversion decisions against total cost parity inflections.
Market Dynamics
Cell-to-pack battery architecture is compressing vehicle assembly timelines and forcing chassis redesigns across heavy-duty platforms, while EPA and EU Green Deal mandates are eliminating diesel registration pathways faster than infrastructure deployment can match.
Growth Catalysts
- EU Green Deal ZEV mandates:The framework's escalating emissions ceilings are constraining diesel truck registrations across Germany, France, and the Netherlands, forcing fleet operators toward battery-electric procurement.
- Depot-charging infrastructure:Logistics hubs in California and Texas are installing megawatt-scale charging arrays that enable overnight replenishment for regional-haul duty cycles without public network dependency.
- Lithium-iron-phosphate chemistry:The technology's thermal stability and cost structure are accelerating adoption in urban bus fleets where route predictability eliminates range anxiety.
Market Restraints
- Cathode material concentration:Processing capacity for nickel and cobalt concentrates in the Democratic Republic of Congo and Indonesia creates supply vulnerability for high-nickel battery formulations.
- Charging infrastructure misalignment:Highway corridor electrification lags behind vehicle availability, stranding heavy-duty freight operators on routes exceeding single-charge range.
- Residual value uncertainty:Battery degradation curves and second-life application economics remain unproven at commercial scale, elevating fleet leasing costs.
Strategic Opportunities
- India's FAME III subsidy extension:The scheme's commercial vehicle provisions are opening procurement pathways for electric buses in Delhi, Mumbai, and Bangalore municipal fleets.
- Battery-swapping for last-mile:Station-based exchange systems are emerging as an alternative to depot charging for fragmented delivery operator bases lacking capital for infrastructure.
- Vehicle-to-grid integration:Bidirectional charging protocols are enabling freight operators to monetize stationary battery capacity during peak grid demand periods.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack certified personnel for 800-volt system diagnostics and repair, extending vehicle downtime.
- Homologation timeline compression:NHTSA and KBA certification protocols for new battery configurations are creating 18-to-24-month approval bottlenecks that delay platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Commercial Vehicle Market |
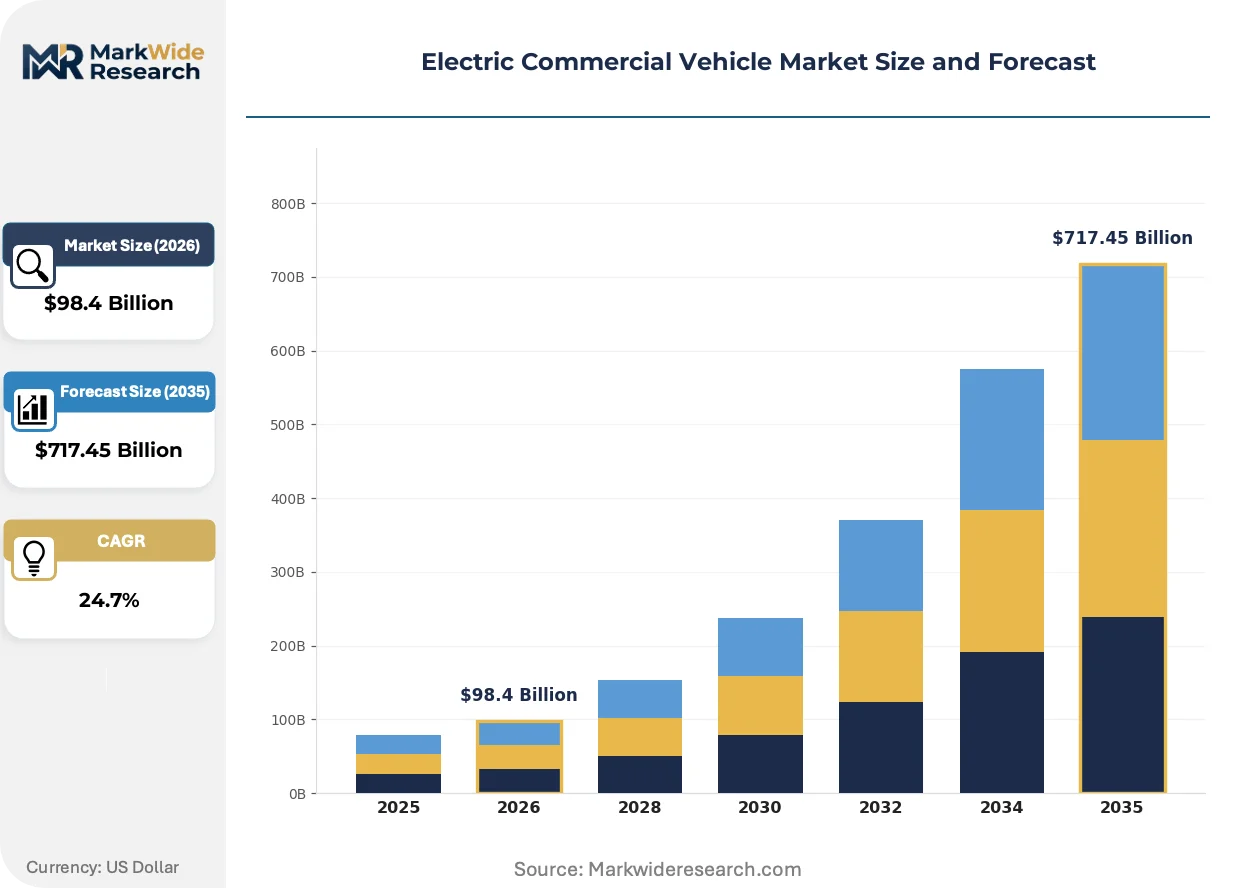
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $717.45 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light-Duty Trucks, Medium-Duty Vans, Heavy-Duty Buses, Delivery Trucks, Cargo Vans Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid, Sodium-Ion Application: Last-Mile Delivery, Public Transit, Freight Transport, Construction Logistics, Waste Management End User: Fleet Operators, Government Agencies, Logistics Providers, Municipal Services, Rental Companies |
| Companies Covered | BYD, Daimler Truck AG, AB Volvo, Tesla, Ford Motor Company, PACCAR Inc., Traton SE, Proterra, Zhengzhou Yutong Bus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Commercial Vehicle Market Strategic Shifts & Innovations
Powertrain integration and energy management software are converging to redefine commercial vehicle architecture, with thermal efficiency and charging speed becoming primary competitive differentiators rather than payload capacity alone.
Silicon-carbide inverters are replacing insulated-gate bipolar transistor modules in heavy-duty traction systems. Freight operators running high-utilization routes across the German autobahn network are adopting the technology for its efficiency gains at sustained highway speeds. The transition is migrating from premium long-haul segments toward medium-duty distribution vehicles as unit costs decline.
The EPA's Phase 3 greenhouse gas standards are mandating progressive emissions reductions through 2032. Heavy-duty truck manufacturers are accelerating electric platform development to avoid non-compliance penalties that would render diesel offerings unviable. California's Advanced Clean Trucks regulation is forcing the earliest compliance timelines, with fleet purchase requirements already active.
Leasing structures are displacing outright purchase for battery-electric commercial vehicles. Third-party fleet management providers in the United Kingdom and the Netherlands are absorbing residual value risk and bundling charging infrastructure into per-mile contracts. The model is concentrating among postal and parcel delivery operators with predictable route densities and centralized depot networks.
Electric Commercial Vehicle Market Segmentation
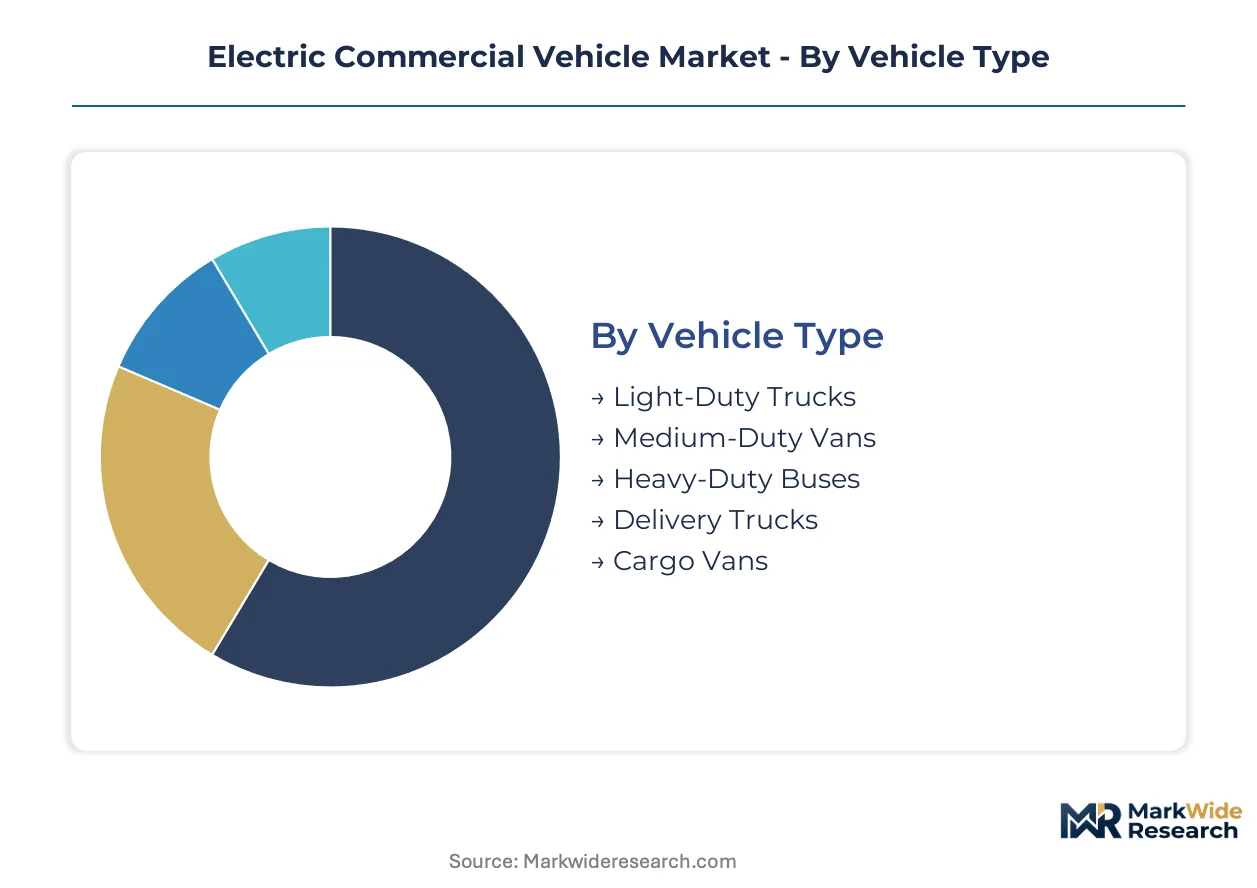
Segmentation reveals how procurement cycles and infrastructure requirements fragment the commercial EV opportunity. Fleet operators prioritize vehicle classes and battery chemistries based on route predictability, depot access, and regulatory compliance timelines.
Vehicle Type:
Replacement cycles vary dramatically across weight classes, with light-duty platforms turning over every 4-6 years while heavy-duty buses operate on 12-15 year lifecycles.
- Light-Duty Trucks:Gross vehicle weights between 3.5 and 7.5 tonnes with modular battery packs enabling overnight depot charging. Urban freight operators in Germany and California concentrate procurement here due to accessible charging infrastructure and EU Green Deal compliance deadlines.
- Heavy-Duty Buses:Articulated and rigid configurations exceeding 12 tonnes with extended-range battery architectures above 400 kWh. Municipal transit authorities in China and the Netherlands dominate demand as diesel bus bans activate across city centers.
- Medium-Duty Vans:Payload-optimized platforms for regional distribution networks.
- Delivery Trucks:Purpose-built last-mile configurations with low-floor access.
- Cargo Vans:Compact urban logistics vehicles maximizing cubic capacity.
Heavy-Duty Buses dominates installed base. Light-Duty Trucks is where expansion concentrates.
Battery Technology:
Cost tiers separate proven chemistries from emerging alternatives, with thermal stability and energy density dictating application fit.
- Lithium-Ion:NMC and LFP variants delivering 150-300 Wh/kg with established recycling pathways. LFP formulations from BYD and CATL supply urban bus fleets in China where MIIT safety standards favor thermal stability over maximum range.
- Solid-State:Ceramic or polymer electrolyte architectures targeting 400+ Wh/kg with reduced fire risk. Toyota and QuantumScape development programs focus on long-haul freight applications where energy density constraints currently block diesel replacement.
- Nickel-Metal Hydride:Legacy chemistry retaining niche hybrid applications.
- Lead-Acid:Cost-minimized auxiliary power units in emerging markets.
- Sodium-Ion:Abundant raw material base attracting CATL and BYD investment for price-sensitive segments.
Lithium-Ion commands current production volumes. Solid-State attracts the steepest expansion trajectory.
Application:
Customer type determines charging strategy complexity, with centralized fleets enabling infrastructure investment that fragmented operators cannot justify.
- Last-Mile Delivery:Predictable sub-100km daily routes with return-to-depot patterns. Amazon and DHL logistics networks in California and Germany anchor procurement as EPA Phase 3 standards tighten.
- Public Transit:Fixed-route bus operations with dedicated charging depots and scheduled downtime. Municipal operators in Shenzhen and Amsterdam lead conversion as diesel restrictions activate in urban cores.
- Freight Transport:Variable long-haul duty cycles exceeding 500km daily distances.
- Construction Logistics:Site-based material movement with severe duty cycles.
- Waste Management:Stop-start collection routes with high regenerative braking potential.
Public Transit dominates installed base. Last-Mile Delivery is where expansion concentrates.
End User:
Procurement scale and subsidy access separate institutional buyers from commercial operators, with government-backed mandates accelerating public sector conversion.
- Fleet Operators:Multi-hundred vehicle procurement programs with centralized maintenance infrastructure. Deutsche Post and FedEx Express operations in Germany and California drive volume through leasing structures that absorb residual value risk.
- Government Agencies:Transit authority and postal service procurement with mandated electrification targets. China's MIIT and the EU Green Deal enforce purchase quotas that guarantee demand visibility.
- Logistics Providers:Third-party freight operators with variable route portfolios.
- Municipal Services:City-owned utility and maintenance vehicle fleets.
- Rental Companies:Short-term commercial vehicle leasing with utilization uncertainty.
Government Agencies dominates installed base. Fleet Operators is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators concentrate procurement decisions in jurisdictions where depot-charging infrastructure and zero-emission mandates align. Municipal transit authorities and logistics providers prioritize markets with visible subsidy continuity and certified technician availability.
China
MIIT production quotas and municipal diesel bus bans in Shenzhen and Beijing are compressing procurement timelines for heavy-duty electric buses. CATL and BYD's captive cell supply secures cost advantages for domestic manufacturers serving state-owned transit fleets. The Yangtze River Delta cluster around Shanghai anchors battery-electric truck deployment for port logistics operators.
Germany
The KBA enforces stringent homologation protocols that favor established manufacturers with certified testing infrastructure. Daimler Truck AG's Stuttgart engineering base supports eActros platform development for autobahn freight corridors. North Rhine-Westphalia logistics hubs in Düsseldorf and Cologne are installing megawatt-scale charging arrays for regional-haul electrification.
United States
EPA Phase 3 greenhouse gas standards and California's Advanced Clean Trucks regulation are mandating fleet purchase requirements through 2032. Tesla's Nevada Gigafactory supplies cells for Semi production targeting long-haul routes. Texas logistics corridors between Dallas and Houston are deploying depot-charging infrastructure independent of federal highway electrification timelines.
India
FAME III subsidy extensions for commercial vehicles are opening procurement pathways for municipal bus fleets in Delhi, Mumbai, and Bangalore. State transport undertakings in Maharashtra and Karnataka are issuing tenders for 12-meter electric bus configurations. The Delhi-NCR region mandates 50% electric bus procurement for all new fleet additions.
Netherlands
EU Green Deal emissions ceilings and Amsterdam's 2025 diesel ban are accelerating transit authority conversion schedules. Arrival's Rotterdam manufacturing presence targets last-mile delivery van production for European postal operators. Randstad logistics clusters are piloting vehicle-to-grid integration for stationary battery monetization during peak demand periods.
Electric Commercial Vehicle Market Key Industry Players
Channel-controlling players compete with product-specialist players across battery chemistry and powertrain integration vectors. The market structures around three tiers: cell-integrated manufacturers with captive supply chains, chassis-assemblers sourcing third-party battery packs, and software-integrated platform developers. Consolidation pressures favor players with certified homologation pathways and multi-year fleet service contracts. Dominant competitive moves include backward integration into cell production and strategic partnerships for charging infrastructure deployment.
Among cell-integrated manufacturers, BYD represents the vertically integrated archetype with in-house lithium-iron-phosphate production. Daimler Truck AG occupies a position within the established OEM tier leveraging Mercedes-Benz and Freightliner brand equity for fleet procurement. Tesla exemplifies the software-integrated platform approach with energy management systems as a primary differentiation vector.
| Leading Market Players |
|---|
| BYD |
| Daimler Truck AG |
| AB Volvo |
| Tesla |
| Ford Motor Company |
| PACCAR Inc. |
| Traton SE |
| Proterra |
| Zhengzhou Yutong Bus |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta cluster around Shanghai anchors cathode active material processing capacity that feeds directly into cell production economics for heavy-duty platforms. Battery pack cost trajectories downstream from this concentration determine whether fleet operators achieve diesel parity before subsidy expiration deadlines.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate cathode material procurement between Chinese suppliers and European OEMs. Three-tier pricing structure across premium, standard, and economy levels separates solid-state pilot programs from LFP volume deployments from lead-acid auxiliary units. Cost compression in the standard tier is intensifying because CATL and BYD are expanding in-house LFP capacity. Municipal transit authorities exhibit the highest price sensitivity due to fixed budget cycles, while long-haul freight operators absorb premium pricing for extended-range configurations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for battery cell sourcing. Processing capacity concentrates in China, South Korea, and Japan, with cathode precursor refining drawing from Indonesian nickel and Chilean lithium deposits. Single-source vulnerability persists for high-purity graphite anodes where synthetic production rests on Chinese petroleum coke supply. Distribution runs through Tier 1 supplier integrators who bundle cells into certified pack assemblies for OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks as a cyclical recovery anchored to battery metal price normalization following the 2022-2023 lithium spike. Fleet procurement cycles will accelerate as cell cost curves intersect diesel total cost of ownership thresholds.
For Market Incumbents: Insulate platform margins by securing captive LFP supply through backward integration into cathode precursor production. Accelerate homologation investment with KBA and NHTSA to compress 18-month certification bottlenecks before Phase 3 enforcement tightens. The priority lever sits with technician certification programs that reduce fleet downtime liability. For New Entrants and Emerging Players: Battery-swapping infrastructure for fragmented last-mile operators in India and Southeast Asia represents the most penetrable entry point. Depot-charging avoidance unlocks capital-constrained delivery fleets lacking infrastructure investment capacity. Partner with state transport undertakings on FAME III tender participation to secure volume anchors. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because charging network ownership will extract recurring revenue as vehicle margins commoditize. Target cell-integrated mid-cap specialists with certified pack architectures and municipal fleet service contracts. Monitor EPA Phase 3 compliance credit pricing as the signal for fleet conversion velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL's LFP supply contracts with Daimler Truck AG secure cost visibility for eActros platform scaling. |
| Charging Infrastructure Partnership | Megawatt-scale depot arrays in Texas logistics corridors bypass federal highway electrification delays. |
| Platform Standardization | Cell-to-pack architecture migration reduces assembly complexity across Mercedes-Benz and Freightliner lineups. |
| Software-Defined Vehicle Investment | Tesla's energy management systems differentiate Semi program through route-optimized thermal efficiency. |
| Geographic Manufacturing Footprint | BYD's in-house cell production controls vertical costs across bus and truck portfolios for state-owned fleets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across fleet procurement directors, battery platform engineers, charging infrastructure developers, and regulatory compliance officers at EPA and MIIT. Secondary validation drew from vehicle production databases, customs trade flows for lithium compounds, SEC filings of listed OEMs, and IEA electric vehicle tracking reports. Bottom-up fleet deployment modeling triangulated against top-down battery capacity expansion announcements.
Calibration against historical fleet conversion rates in Shenzhen and California informed the projection framework across the analysis window. Segmentation dimensions included vehicle weight class, battery chemistry tier, application duty cycle, and end-user procurement structure. CAGRs were derived from installed base turnover assumptions and regulatory mandate compliance timelines. Cell cost learning curves and charging infrastructure deployment schedules served as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in battery metal spot prices or subsidy program continuity would shift the trajectory materially. Forecasts reflect documented assumptions regarding homologation timeline compression and technician certification scaling. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
ASEAN Electric Bicycle Market