
 Middle-East and Africa E-Bike Market | 2026-2036
Middle-East and Africa E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa E-Bike Market Foresight
CE marking compliance for electrical propulsion systems is reorganizing supplier eligibility across the Middle-East and Africa E-Bike Market. Giant Bicycles leverages its established distribution partnerships to anchor presence in Gulf Cooperation Council retail channels. Robert Bosch GmbH sustains technology leadership through its drive system specialization for premium urban models. Trek Bicycle Corporation competes on brand recognition among fitness-oriented consumers in South African metropolitan areas.
An e-bike combines a conventional bicycle frame with an integrated electric motor, battery pack, and controller unit delivering pedal-assist or throttle-based propulsion typically rated between 250W and 750W output. City E-Bikes dominate unit volume across Middle Eastern urban centers where flat topography favors commuter-oriented specifications. Delivery Services represent the fastest-expanding end user category as logistics operators replace petrol mopeds with lithium-ion powered alternatives to reduce operating expenditure. Solid-State battery configurations remain nascent but attract development investment due to thermal stability advantages in arid climates.
The UAE's Ministry of Industry and Advanced Technology enforces conformity assessment protocols that filter non-compliant imports from entering Dubai's duty-free trading hubs. South Africa's National Regulator for Compulsory Specifications mandates SABS mark certification for electrical vehicles sold through formal retail channels. Egypt's General Authority for Investment coordinates with municipal governments to designate dedicated e-mobility lanes in New Cairo and Alexandria. Stakeholders must track how national standards bodies across the region harmonize or diverge their technical requirements to determine manufacturing and import strategies.
Market Dynamics
Last-mile logistics operators across the Middle-East and Africa E-Bike Market are accelerating fleet electrification to offset volatile petrol costs, while Gulf standards bodies tighten conformity assessment protocols that filter import eligibility.
Growth Catalysts
- SASO Energy-Efficiency Labeling:Saudi Arabia's technical regulations are reshaping import requirements for electric mobility products, forcing suppliers to upgrade component specifications to maintain market access.
- Smart City Infrastructure:Government-backed urban planning programs in Dubai and Abu Dhabi embed dedicated e-bike lanes and charging stations into municipal development frameworks.
- Lithium-Ion Cost Curves:Battery cell price compression is enabling logistics operators in Lagos and Cairo to achieve payback periods under eighteen months when replacing petrol mopeds.
Market Restraints
- CE Marking Compliance Costs:Electrical propulsion system certification requirements are reorganizing supplier eligibility, excluding smaller manufacturers lacking testing infrastructure.
- Arid Climate Thermal Stress:Conventional lithium-ion battery configurations face accelerated degradation in ambient temperatures exceeding 45°C, limiting operational lifespan in Gulf Cooperation Council markets.
- Import Duty Layering:Cumulative tariffs across multiple customs checkpoints inflate landed costs for finished e-bikes entering Sub-Saharan African distribution channels.
Strategic Opportunities
- Solid-State Battery Transition:Thermal stability advantages in high-temperature environments are attracting development investment from component suppliers targeting Gulf climate conditions.
- Dedicated E-Mobility Lanes:Egypt's General Authority for Investment is coordinating municipal designations in New Cairo and Alexandria, creating protected infrastructure for commercial delivery fleets.
- SABS Certification Pathways:South Africa's National Regulator for Compulsory Specifications mandates mark certification for formal retail channels, creating first-mover advantage for compliant entrants.
Industry Challenges
- Technical Workforce Scarcity:E-bike maintenance and battery diagnostics require specialized electrical engineering skills that remain concentrated in Johannesburg and Cairo metropolitan areas.
- Standards Harmonization Friction:Divergent technical requirements between SASO, SABS, and UAE conformity assessment protocols complicate pan-regional product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa E-Bike Market |
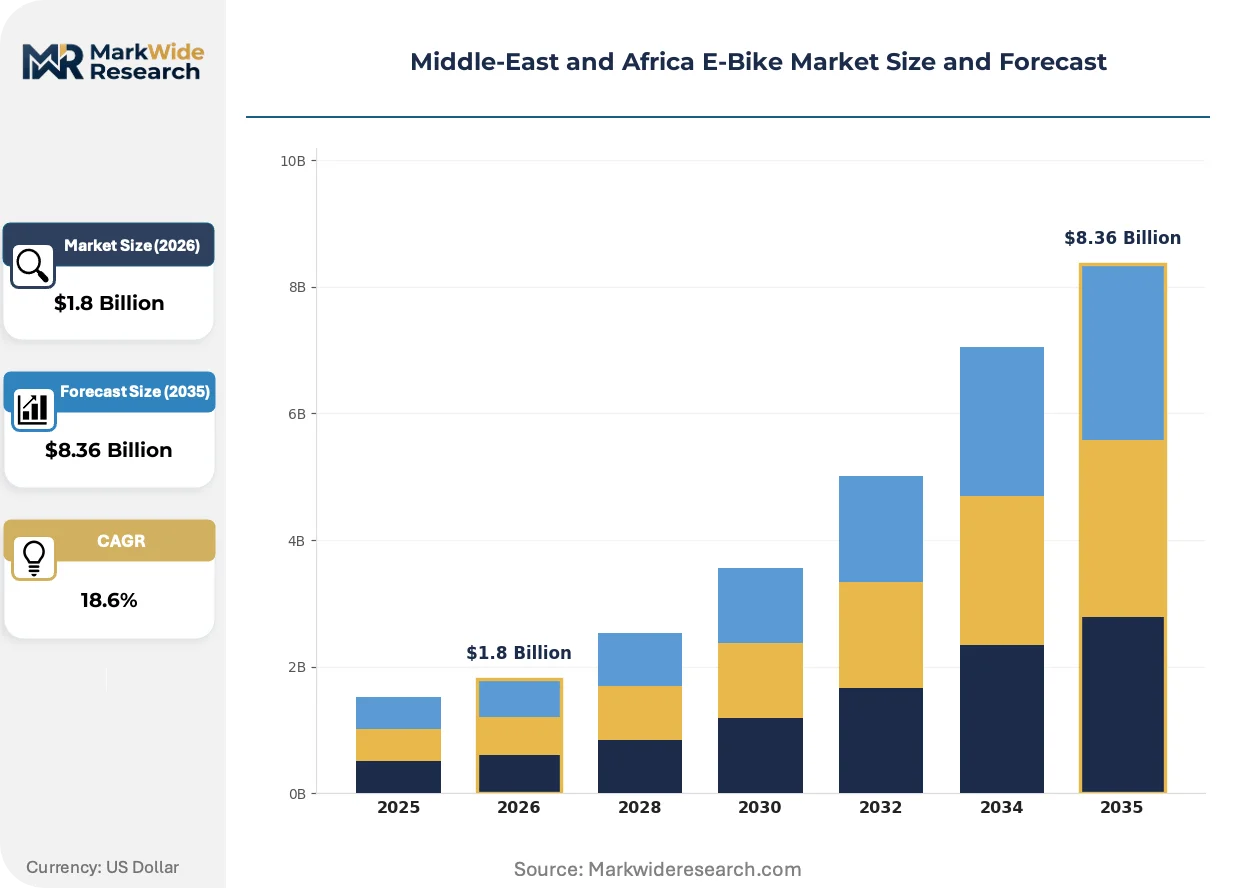
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Hybrid E-Bikes, Folding E-Bikes End User: Commuters, Fitness Enthusiasts, Tourists, Delivery Services Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Giant Bicycles, Trek Bicycle Corporation, TIER Mobility AG, myStromer AG, BIKEERA, Yamaha Motor Co., Ltd., Robert Bosch GmbH, Specialized Bicycle Components, Inc., Accell Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa E-Bike Market Shifts & Advancements
Product architectures and procurement patterns across the Middle-East and Africa E-Bike Market are diverging between premium urban commuter specifications and ruggedized commercial delivery platforms.
Battery chemistry development is bifurcating between nickel-manganese-cobalt formulations optimized for energy density in premium city models and lithium-iron-phosphate cells prioritizing cycle life for high-utilization delivery fleets. Logistics operators in Cairo and Lagos are specifying the latter for replacement cycles exceeding five thousand charge events. This chemistry split is compressing supplier margins on undifferentiated mid-tier packs.
SASO's expanded scope for electric mobility product registration now requires third-party testing documentation for motor controllers and battery management systems. Industrial consequence includes extended lead times for new market entrants lacking established Gulf laboratory relationships. Premium urban e-bike distributors in Riyadh and Jeddah are responding by consolidating procurement through established CE-marked supply chains.
Fleet procurement contracts are displacing individual consumer purchases as the dominant volume channel across North African and Gulf markets. Logistics operators in Dubai and Abu Dhabi are negotiating direct manufacturer relationships that bypass traditional retail markup structures. This channel compression is most visible in the UAE, where government-linked delivery platforms aggregate demand sufficient to justify dedicated production runs.
Middle-East and Africa E-Bike Market Segmentation
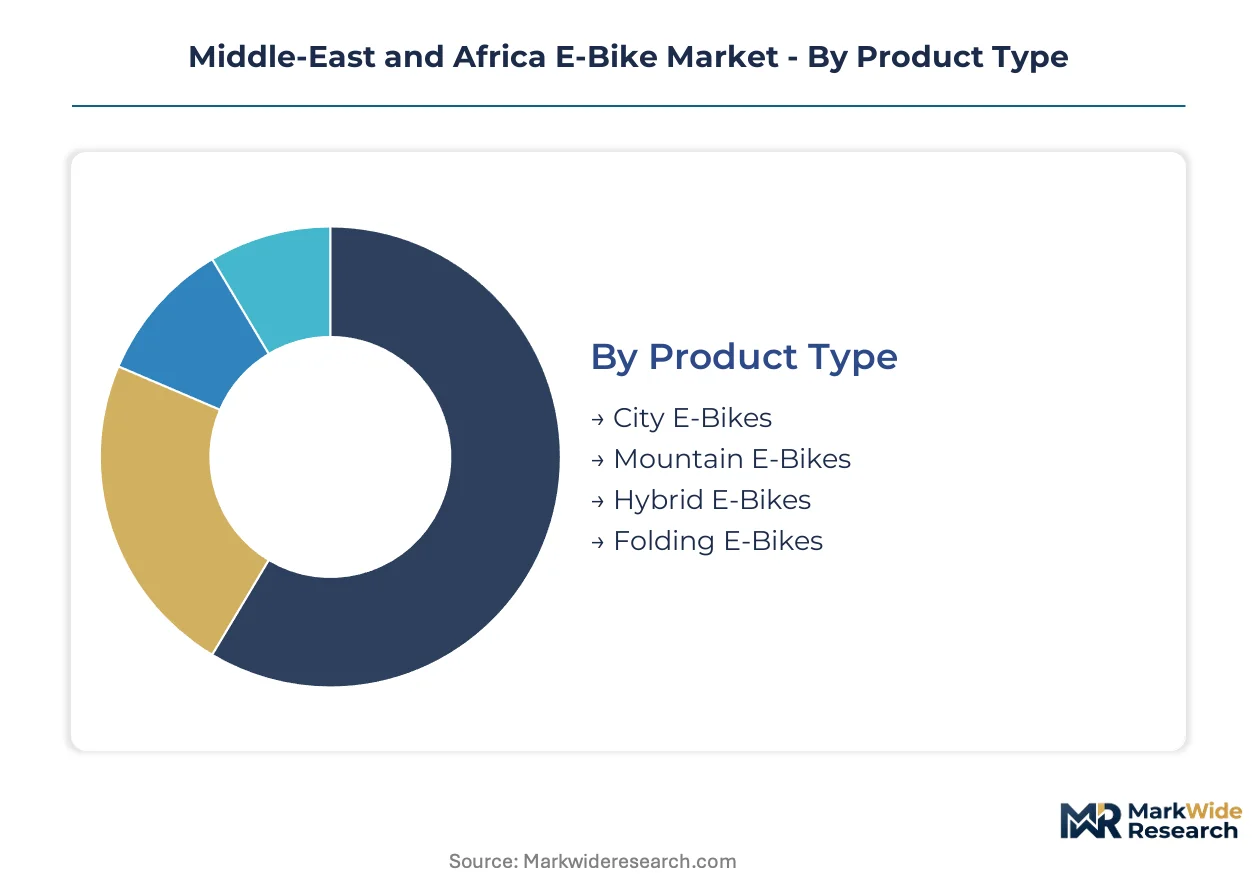
Segmentation across the Middle-East and Africa E-Bike Market reveals distinct procurement patterns between Gulf urban centers and Sub-Saharan commercial corridors. Product specifications diverge sharply between premium commuter-oriented models and ruggedized fleet platforms engineered for high-utilization logistics operations.
Product Type:
Domestic demand concentrates in urban commuter formats across Dubai and Abu Dhabi, while export-oriented supply chains from Chinese manufacturers favor standardized platform architectures adaptable to multiple regional specifications.
- City E-Bikes:These models integrate 250W hub motors with step-through frames optimized for flat Gulf topography. Procurement volumes from Dubai's government-backed smart city programs anchor regional demand for this configuration. SASO energy-efficiency labeling requirements are filtering non-compliant imports from Saudi retail channels.
- Mountain E-Bikes:Mid-drive motor systems with torque sensors dominate specifications here. South African metropolitan consumers in Johannesburg and Cape Town drive premium positioning through fitness-oriented retail channels. SABS certification mandates complicate direct import pathways for specialized distributors.
- Hybrid E-Bikes:Versatile frame geometries accommodate both paved roads and light gravel surfaces across Egyptian and Moroccan urban peripheries.
- Folding E-Bikes:Compact lithium-ion configurations target multi-modal commuters in Cairo's congested metropolitan core where storage constraints dominate purchasing decisions.
City E-Bikes commands the established base. The steepest expansion runs through Mountain E-Bikes.
End User:
Customer archetypes split between individual purchasers optimizing for total cost of ownership and fleet operators negotiating volume procurement contracts that bypass traditional retail markups.
- Commuters:Daily urban travelers across Riyadh and Jeddah prioritize pedal-assist systems with integrated lighting and rack configurations. Dubai's dedicated e-mobility lane infrastructure is accelerating replacement of private vehicle dependency for sub-15 kilometer journeys.
- Delivery Services:Logistics operators in Lagos and Cairo specify lithium-iron-phosphate battery chemistry for replacement cycles exceeding five thousand charge events. Fleet procurement contracts now displace individual consumer purchases as the dominant volume channel across North African markets.
- Fitness Enthusiasts:Performance-oriented consumers in South African metropolitan areas demand integrated power meters and smartphone connectivity.
- Tourists:Rental fleet operators in Dubai and Sharm El-Sheikh favor low-maintenance hub motor configurations with simplified user interfaces.
Commuters anchor current installed base. Delivery Services is climbing the fastest as fuel cost volatility accelerates fleet electrification timelines.
Battery Type:
Chemistry selection tracks directly against utilization intensity and ambient thermal stress, with Gulf climate conditions forcing accelerated degradation trade-offs against energy density optimization.
- Lithium-Ion:Nickel-manganese-cobalt formulations deliver maximum range for premium urban commuter specifications. Arid climate thermal stress above 45°C ambient temperatures limits operational lifespan, compressing replacement cycles in Saudi and UAE markets.
- Solid-State:Thermal stability advantages in high-temperature environments are attracting development investment from component suppliers targeting Gulf climate conditions. Commercial availability remains constrained by manufacturing scale limitations.
- Lead-Acid:Price-sensitive entry-level configurations persist in informal Sub-Saharan distribution channels despite weight and cycle life disadvantages.
- Nickel-Metal Hydride:Legacy chemistry retains niche presence in refurbished fleet operations across Egyptian secondary markets.
Lithium-Ion retains volume leadership. Solid-State is gaining share fastest through targeted R&D investment from thermal management specialists.
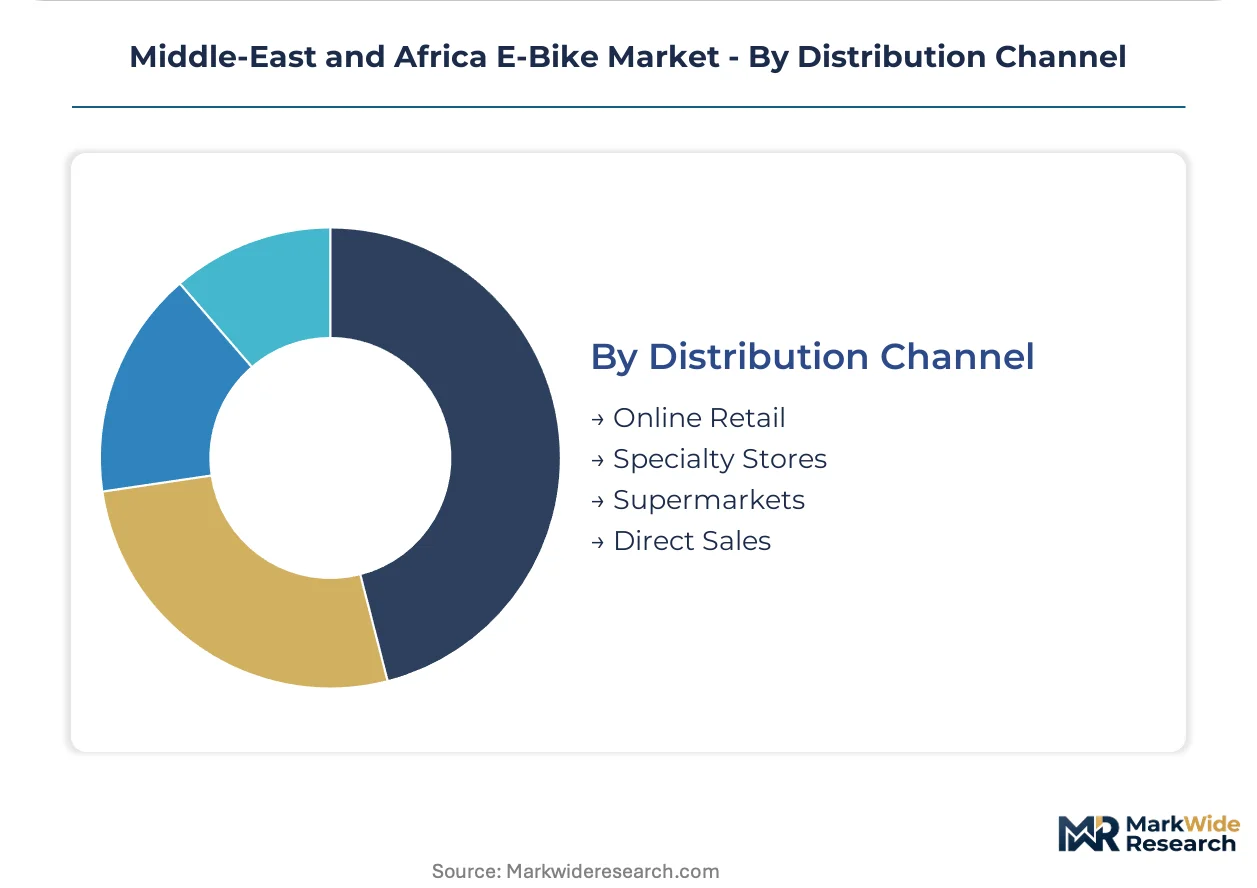
Distribution Channel:
Channel structure bifurcates between established retail networks serving individual consumers and direct manufacturer relationships negotiated by consolidated fleet operators.
- Specialty Stores:Technical consultation and after-sales service capabilities concentrate in Johannesburg and Cairo metropolitan areas. These outlets capture premium positioning through test-ride infrastructure and maintenance contract bundling.
- Direct Sales:Logistics operators in Dubai and Abu Dhabi negotiate manufacturer relationships that aggregate demand sufficient to justify dedicated production runs. Government-linked delivery platforms are compressing traditional distributor margins through volume consolidation.
- Online Retail:Cross-border e-commerce platforms serve price-sensitive consumers in secondary Gulf and North African cities with limited physical retail penetration.
- Supermarkets:Mass-market retail chains in South African urban centers stock entry-level configurations alongside consumer electronics categories.
Specialty Stores commands the established base. Direct Sales shows the steepest trajectory as fleet procurement scales displace fragmented retail volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SASO energy-efficiency labeling rules and the UAE's smart city infrastructure investments are reshaping procurement patterns across Gulf Cooperation Council markets, while North African logistics operators accelerate fleet electrification to offset fuel cost volatility.
United Arab Emirates
Dubai and Abu Dhabi anchor regional demand through government-backed smart city programs embedding dedicated e-bike lanes and charging stations into municipal frameworks. MOHAP conformity assessment protocols filter import eligibility for electrical mobility products entering duty-free trading hubs. Fleet procurement contracts from government-linked delivery platforms in Dubai are compressing traditional distributor margins through volume consolidation.
Saudi Arabia
Riyadh and Jeddah drive premium urban commuter specifications as SASO technical regulations reshape import requirements for electric mobility products. The expanded registration scope now mandates third-party testing documentation for motor controllers and battery management systems. Distributors in Riyadh are consolidating procurement through established CE-marked supply chains to navigate extended lead times.
Egypt
Cairo and Alexandria concentrate logistics operator demand as the General Authority for Investment coordinates municipal designation of dedicated e-mobility lanes. Last-mile delivery fleets specify lithium-iron-phosphate battery chemistry for replacement cycles exceeding five thousand charge events. New Cairo's protected infrastructure is attracting commercial delivery fleet operators replacing petrol mopeds.
South Africa
Johannesburg and Cape Town metropolitan areas anchor technical workforce capabilities for e-bike maintenance and battery diagnostics. The National Regulator for Compulsory Specifications mandates SABS mark certification for electrical vehicles sold through formal retail channels. Specialty stores in Johannesburg capture premium positioning through test-ride infrastructure and maintenance contract bundling.
Nigeria
Lagos concentrates last-mile logistics electrification as operators achieve payback periods under eighteen months when replacing petrol mopeds with lithium-ion alternatives. Cumulative tariffs across multiple customs checkpoints inflate landed costs for finished e-bikes entering Sub-Saharan distribution channels. Informal retail channels in Lagos persist with price-sensitive lead-acid configurations despite weight disadvantages.
Middle-East and Africa E-Bike Market Competitive Landscape
Player mix skews toward established bicycle manufacturers diversifying into electrification and component specialists supplying drive systems to regional assemblers. Market structure exhibits tiered concentration with premium urban commuter specifications dominated by European and East Asian brands, while ruggedized commercial delivery platforms attract Chinese manufacturers. Two strategic archetypes predominate: heritage bicycle brands leveraging distribution partnerships and technology suppliers specializing in motor-battery integration. Competitive moves center on direct fleet procurement relationships bypassing retail markups and certification pathway investments securing first-mover advantage in regulated channels.
Among heritage bicycle manufacturers, Giant Bicycles and Trek Bicycle Corporation exemplify distribution-anchored positioning in Gulf Cooperation Council retail channels. Robert Bosch GmbH occupies the technology supplier archetype through drive system specialization. These three entities represent contrasting entry modes: the bicycle manufacturers leverage established retail networks while the component specialist supplies multiple assemblers across premium urban specifications.
| Leading Market Players |
|---|
| Giant Bicycles |
| Trek Bicycle Corporation |
| TIER Mobility AG |
| myStromer AG |
| BIKEERA |
| Yamaha Motor Co., Ltd. |
| Robert Bosch GmbH |
| Specialized Bicycle Components, Inc. |
| Accell Group |
| Others |
Supply & Pricing Matrix
Chinese lithium-ion cell capacity utilization above 80 percent compresses battery pack costs and anchors price floors across Middle Eastern and African distribution channels. This scale concentration enables Gulf fleet operators to negotiate direct manufacturer relationships that bypass layered distributor markups.
Pricing Analysis
Certification level (CE/SASO/SABS-grade) creates the primary spread between premium urban commuter specifications and entry-level fleet configurations. Three-tier pricing structure across premium, standard, and economy levels tracks battery chemistry and motor controller sophistication. Cost compression in mid-tier lithium-iron-phosphate packs is intensifying because logistics operators aggregate procurement volumes. Fleet buyers in Lagos and Cairo exhibit highest price sensitivity, while Dubai government-linked platforms prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate Chinese component suppliers serving Gulf assembly operations, while strategic stockpiling of battery cells concentrates in Dubai's duty-free trading hubs. Manufacturing gravity centers on China, Taiwan, and Vietnam for motor controllers, frame components, and battery management systems. The supply chain draws from lithium carbonate, rare earth magnets, and aluminum alloy inputs. Single-source vulnerability in solid-state electrolyte development constrains thermal-stable battery introduction. Distribution runs through consolidated fleet procurement contracts displacing fragmented retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa E-Bike Market sits in early-cycle expansion as last-mile logistics electrification accelerates replacement of petrol mopeds across North African commercial corridors.
For Market Incumbents: Secure SASO certification pathways before expanded technical regulations filter import eligibility, locking in Gulf Cooperation Council market access against emerging Chinese manufacturers lacking testing infrastructure. Deepen backward integration into battery management system firmware to defend margin position as fleet procurement contracts compress hardware markups. Prioritize dedicated production runs for Dubai government-linked delivery platforms to anchor volume commitments. For New Entrants and Emerging Players: SABS fast-track certification creates entry opportunity into South African formal retail channels where compliant suppliers capture first-mover positioning. Target Egyptian commercial fleet operators in New Cairo and Alexandria where protected e-mobility lane infrastructure reduces operational friction for new market participants. Pursue direct sales relationships with Lagos logistics aggregators to bypass cumulative tariff layering across Sub-Saharan distribution checkpoints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with drive system integration capabilities over undifferentiated frame assemblers. Long-term viability hinges on solid-state battery chemistry transitions addressing Gulf thermal degradation constraints. Acquisition targets should exhibit established Gulf laboratory relationships and CE-marked supply chain foundations. Watch solid-state electrolyte manufacturing scale achievements as inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Extended registration scope for motor controllers and battery management systems filters non-compliant imports from Saudi retail channels. |
| Direct Fleet Procurement Relationships | Dubai government-linked delivery platforms aggregate demand sufficient to justify dedicated production runs bypassing distributor margins. |
| Solid-State Battery R&D Partnership | Thermal stability advantages in arid climates attract development investment from component suppliers targeting Gulf conditions. |
| Protected Lane Infrastructure Coordination | Egypt's General Authority for Investment municipal designations in New Cairo create operational advantages for commercial delivery fleets. |
| Technical Workforce Development | Specialized electrical engineering skills concentrated in Johannesburg and Cairo metropolitan areas constrain maintenance network expansion. |
Research Methodology
Desk research of customs trade databases, national standards body filings, and municipal smart city planning documents preceded structured interviews with fleet procurement managers, specialty retail operators, battery system engineers, and conformity assessment laboratory directors. Primary fieldwork across Dubai, Riyadh, Cairo, Johannesburg, and Lagos validated secondary data on import volumes and certification pathways. Bottom-up unit shipment estimates triangulated against top-down market value projections derived from battery cost curve analysis.
Variance decomposition across product type, battery chemistry, end-user category, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating lithium-ion price compression trajectories and fleet electrification adoption curves. Industry-specific forecast inputs included SASO regulatory expansion timelines and Dubai smart city infrastructure deployment schedules.
Underlying assumptions cover battery cell cost reduction continuity, Gulf climate thermal management feasibility, and municipal e-mobility lane designation momentum, with deviation risk concentrated in solid-state battery commercialization delays and Sub-Saharan tariff policy shifts. Revision becomes warranted when ambient temperature degradation data for conventional lithium-ion configurations crosses replacement cycle threshold tolerances for fleet operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Europe Electric Vehicle Market