
 Off-Highway Electric Machine Battery Pack Systems Market | 2026-2036
Off-Highway Electric Machine Battery Pack Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Electric Machine Battery Pack Systems Market Insights
Electrochemical engineering talent is bifurcating the competitive landscape as incumbents race to secure battery thermal management expertise. BorgWarner leverages its power electronics heritage to integrate inverter-battery architectures for construction equipment. Caterpillar anchors its position through captive validation labs for extreme-duty cycle testing. Komatsu differentiates via its proprietary battery management algorithms optimized for mining duty profiles.
Off-highway electric machine battery pack systems are engineered electrochemical storage assemblies designed to deliver sustained high-discharge currents under severe vibration, temperature extremes, and shock loads encountered in construction, mining, and agricultural environments; these systems typically employ liquid-cooled lithium-ion cell configurations with reinforced enclosures rated to IP6K9K ingress protection standards to ensure operational integrity in dust-laden and submerged conditions. Lithium-ion chemistry dominates current procurement decisions due to its superior energy density and cycle life relative to legacy lead-acid alternatives, though solid-state formulations represent the emerging frontier for next-generation platforms. Excavators command the largest installed base of electrified off-highway machines, while mining loaders generate the most intensive battery utilization rates and replacement demand. Modular deployment architectures are gaining traction among heavy equipment rental fleets seeking standardized swap protocols across mixed OEM portfolios.
EPA Tier 4 Final regulations in the United States and the EU Green Deal's industrial decarbonization mandates are constricting diesel engine availability while redirecting OEM development budgets toward electrified platforms. China's MIIT enforces GB standards for battery safety and recycling traceability that constrain market entry for non-compliant pack suppliers. Stakeholders must monitor how evolving F-Gas restrictions across Europe reshape thermal management refrigerant selections and supplier qualification requirements.
Market Dynamics
The transition from diesel to electrified powertrains is compressing development cycles as mining operators demand validated battery systems for 24/7 underground operations. OEMs must now integrate thermal management, cell chemistry selection, and enclosure engineering simultaneously rather than sequentially.
Growth Catalysts
- Stage V emissions standards:Europe's stringent particulate and NOx limits are eliminating diesel engine options for new construction equipment, forcing fleet operators toward electrified alternatives with certified battery packs.
- Underground mining electrification:Tunneling operations in Canada, Australia, and Chile are mandating zero-emission zones to eliminate diesel particulate exposure, creating immediate procurement pull for high-discharge battery systems.
- Lithium iron phosphate chemistry:Cell manufacturers are scaling LFP production for heavy-duty applications where thermal stability outweighs energy density requirements, reducing pack cost trajectories for mid-size excavators.
Market Restraints
- Cobalt and lithium price volatility:Cathode material cost swings are compressing pack assembler margins and triggering indexed pricing clauses that delay contract finalization.
- Cell supply concentration:Cylindrical and prismatic cell production clusters in China create geographic single-source risk for European and North American pack integrators seeking qualified supply.
- IP thickets around BMS algorithms:Proprietary battery management software patents held by automotive suppliers are creating licensing friction for construction equipment OEMs developing in-house pack control systems.
Strategic Opportunities
- Second-life stationary storage:Retired mining machine packs with degraded capacity are finding reuse in site-level microgrids, creating circular revenue streams for fleet operators and pack servicers.
- Swappable modular architectures:Rental fleet operators are standardizing on common pack form factors across mixed OEM portfolios, opening aftermarket supply positions for independent pack assemblers.
- India's PLI scheme for ACC batteries:Domestic cell production incentives are attracting pack assembly investment for agricultural tractor electrification programs targeting diesel displacement in Punjab and Haryana.
Industry Challenges
- Thermal runaway containment engineering:Pack designers must demonstrate cell-to-cell propagation prevention under UN 38.3 test protocols, extending validation timelines by 8-14 months for new enclosure designs.
- Electrochemical systems integration talent:The shortage of engineers with combined expertise in cell chemistry, power electronics, and heavy-duty mechanical packaging is constraining OEM internal development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Electric Machine Battery Pack Systems Market |
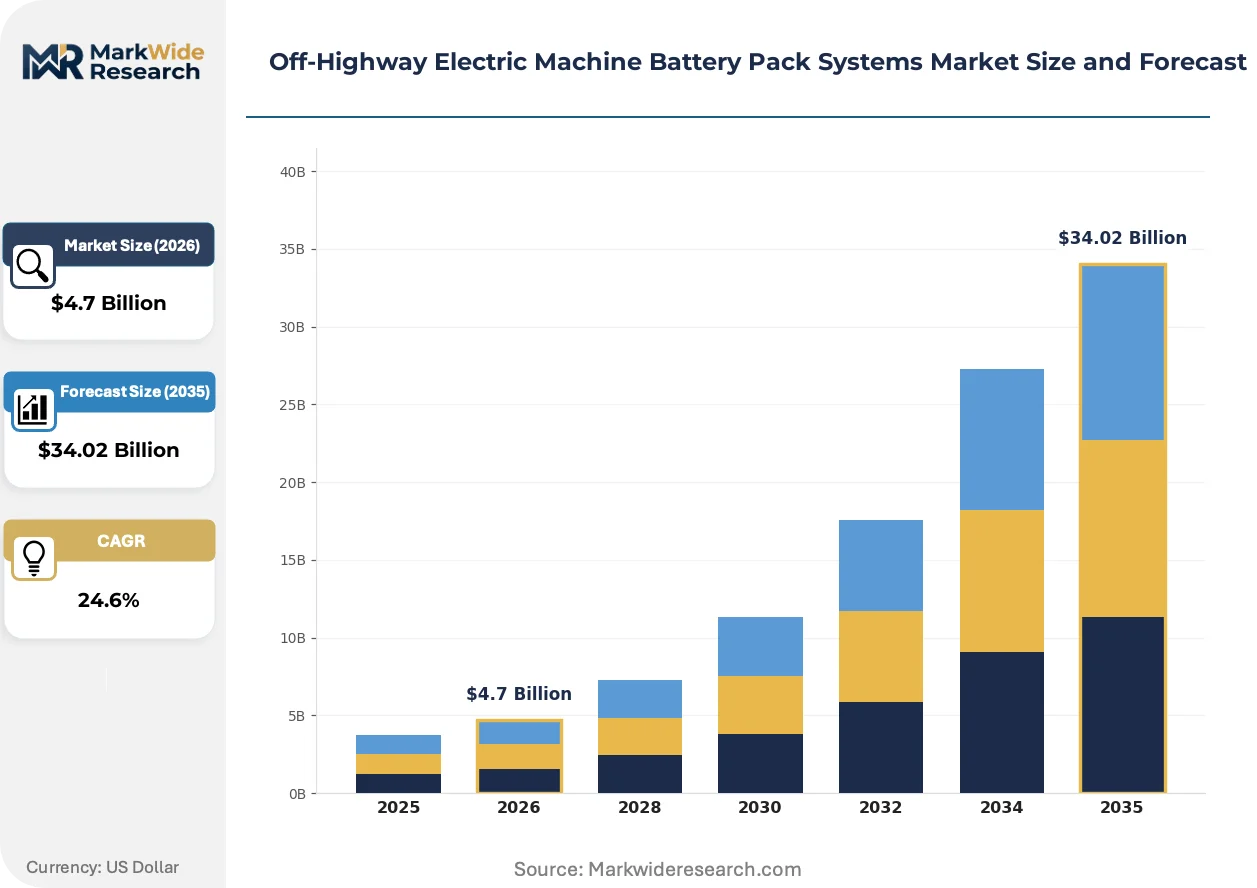
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $34.02 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State, Sodium-Ion Machine Type: Excavators, Agricultural Tractors, Mining Loaders, Forestry Equipment, Construction Cranes Deployment Type: Onboard, Stationary, Portable, Modular, Integrated End User Industry: Mining Operations, Agricultural Enterprises, Construction Firms, Forestry Services, Heavy Equipment Rental |
| Companies Covered | Jungheinrich, BorgWarner, Forsee Power, Turntide Technologies, Volvo Construction Equipment, Wamtechnik, Liebherr, Caterpillar, Komatsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Electric Machine Battery Pack Systems Market Trends and Innovations
Pack architectures are fragmenting as end-use duty profiles diverge, with mining applications demanding ruggedized thermal management while agricultural equipment prioritizes cost-optimized passive cooling. This specialization is forcing cell suppliers to qualify multiple product lines rather than universal platforms.
Solid-state electrolyte formulations are decomposing the traditional liquid-cooled pack paradigm for extreme-duty mining applications. Komatsu and Caterpillar validation programs are accelerating cell testing for 1000-bar operating pressures. The technology is decomposing incumbent lithium-ion supply relationships as solid-state specialists bypass established tiering structures.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in battery thermal management systems, forcing pack assemblers to qualify CO2 or hydrocarbon-based cooling circuits. Equipment OEMs in Germany and Sweden are redesigning heat exchanger architectures to accommodate lower-GWP alternatives. Mining machine producers with underground certification requirements face compressed timelines to demonstrate alternative refrigerant safety compliance.
Fleet procurement departments are unbundling battery pack acquisition from machine purchase, treating energy storage as a separate capital line item with distinct financing structures. Heavy equipment rental operators in Australia and Canada are pioneering power-as-a-service contracts where pack replacement responsibility shifts to third-party energy managers. This restructuring is most advanced in open-pit copper operations where utilization rates justify dedicated battery logistics infrastructure.
Off-Highway Electric Machine Battery Pack Systems Market Segmentation
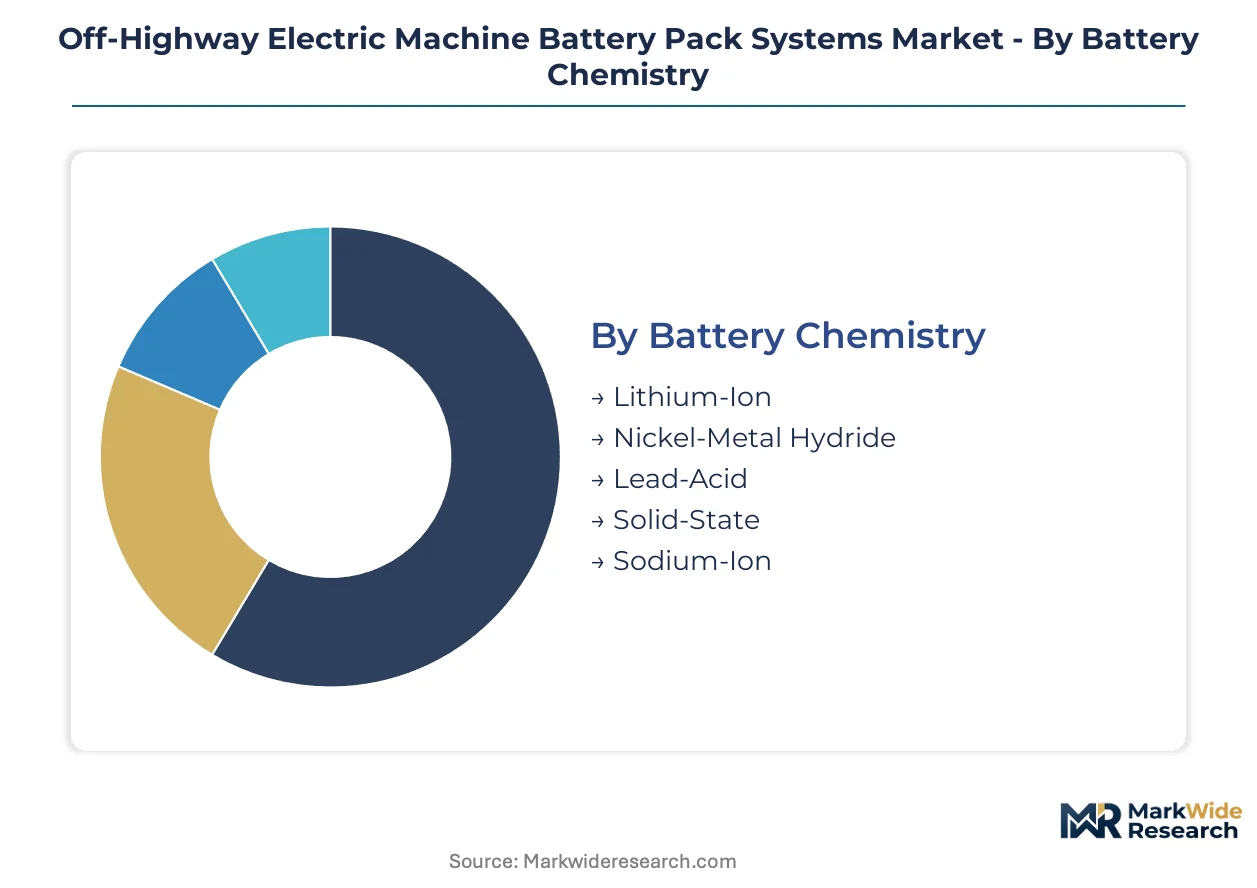
Off-highway electrification demands divergent battery architectures across chemistry, machine integration, and operational deployment. Segment boundaries are hardening as mining duty cycles, agricultural cost constraints, and rental fleet standardization pull specifications in different directions.
Battery Chemistry:
Domestic production clusters in China and South Korea dominate cylindrical and prismatic cell supply, while European and North American pack integrators face qualified supply bottlenecks for solid-state and sodium-ion alternatives.
- Lithium-Ion:Liquid-cooled NMC and LFP configurations deliver the energy density and cycle life required for 24/7 mining operations. German OEMs anchor pack assembly lines around LFP variants for mid-size excavators serving Stage V-compliant construction fleets.
- Solid-State:Sulfide and oxide electrolyte formulations are decomposing incumbent lithium-ion relationships as Komatsu and Caterpillar accelerate validation for 1000-bar operating pressures in underground haul trucks. Cell-to-cell propagation resistance commands premium positioning in extreme-duty applications.
- Nickel-Metal Hydride:Legacy chemistry persists in cost-sensitive agricultural tractors across India's Punjab region where thermal stability requirements are modest.
- Lead-Acid:Remains entrenched in backup power roles for stationary charging infrastructure at remote mining camps.
- Sodium-Ion:Emerging chemistry from Chinese cell suppliers targets price-sensitive construction equipment where energy density penalties are acceptable for short-duty cycle applications.
Lithium-ion holds the largest share; momentum sits with solid-state as mining OEMs validate next-generation platforms.
Machine Type:
Cost tier stratification separates premium thermal management for mining equipment from passive-cooled architectures in agricultural machinery.
- Excavators:Command the largest installed base of electrified off-highway machines with modular pack configurations enabling rapid swap protocols. European construction firms in Germany and Sweden are standardizing on common form factors across mixed OEM portfolios.
- Mining Loaders:Generate the most intensive battery utilization rates with replacement cycles compressed by continuous high-discharge duty. Australian open-pit copper operations are pioneering power-as-a-service contracts where pack logistics shift to third-party energy managers.
- Agricultural Tractors:India's PLI scheme for ACC batteries is attracting pack assembly investment targeting diesel displacement in Haryana's rice-wheat belt.
- Forestry Equipment:Vibration-hardened enclosures with IP6K9K ingress protection are required for submerged and dust-laden conditions in Nordic logging operations.
- Construction Cranes:Stationary deployment models predominate with grid-tied charging infrastructure at urban high-rise sites.
Excavators dominate volume; mining loaders are climbing the fastest as fleet electrification accelerates in zero-emission zones.
Deployment Type:
Customer type fragmentation separates captive fleet operators pursuing integrated architectures from rental companies demanding interchangeable standards.
- Modular:Swappable pack architectures with standardized connectors are gaining traction among heavy equipment rental fleets in Canada and Australia seeking cross-OEM compatibility.
- Onboard:Permanently installed configurations dominate owner-operator mining fleets where machine-pack lifecycle alignment is prioritized.
- Stationary:Fixed charging infrastructure with second-life retired packs is emerging at Chilean copper operations for site-level microgrid stabilization.
- Portable:Mobile charging skids serve remote agricultural operations in India's decentralized farming landscape.
- Integrated:Inverter-battery unified architectures from BorgWarner and similar suppliers are penetrating European construction equipment where space constraints demand compact power electronics.
Onboard configurations retain the largest installed base; modular systems are gaining share fastest as rental fleet standardization advances.
End User Industry:
Maturity gradients separate established mining electrification programs from nascent agricultural transitions and emerging forestry applications.
- Mining Operations:Underground zero-emission mandates in Canada, Australia, and Chile are eliminating diesel particulate exposure through immediate procurement of high-discharge battery systems. Tunneling contractors face compressed validation timelines for UN 38.3 thermal runaway compliance.
- Construction Firms:EPA Tier 4 Final regulations and EU Green Deal industrial decarbonization mandates are constricting diesel engine availability while redirecting OEM development budgets toward electrified platforms.
- Agricultural Enterprises:Diesel displacement programs in India's northern states are driving mid-size tractor electrification with cost-optimized LFP packs.
- Forestry Services:Nordic operators are qualifying ruggedized thermal management systems for extreme temperature cycling.
- Heavy Equipment Rental:Australian and Canadian operators are unbundling battery acquisition from machine purchase with distinct financing structures for energy storage capital.
Mining operations command the largest share; construction firms represent the steepest expansion trajectory as emissions regulations tighten across Germany, France, and Sweden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: mining-dominated markets prioritize thermal resilience and rapid swap protocols, while agricultural regions emphasize cost-optimized passive cooling architectures for seasonal duty cycles.
United States
Underground zero-emission mandates in Nevada and Arizona copper operations are accelerating procurement of high-discharge battery systems for haul trucks and loaders. EPA Tier 4 Final regulations are constricting diesel engine availability for new construction equipment across California and Texas. Detroit anchors battery pack testing infrastructure serving domestic OEM validation programs for extreme-duty cycle certification.
Germany
Construction fleet operators in Bavaria and North Rhine-Westphalia are standardizing on modular pack form factors across mixed OEM portfolios to enable rapid swap protocols. The EU F-Gas Regulation is forcing redesign of thermal management refrigerant circuits toward CO2-based alternatives. Stuttgart hosts concentrated battery assembly lines where Tier 1 suppliers integrate inverter-battery architectures for European construction equipment.
Australia
Open-pit copper and iron ore operations in Western Australia and Queensland are pioneering power-as-a-service contracts where third-party energy managers assume pack replacement responsibility. Zero-emission zone mandates in New South Wales underground coal operations are eliminating diesel particulate exposure. Perth serves as the logistics hub for battery swap infrastructure serving remote mining camps.
China
Domestic OEMs are scaling LFP production for mid-size excavators serving Belt and Road construction projects across Southeast Asia and Africa. MIIT GB standards for battery safety and recycling traceability are constraining market entry for non-compliant pack suppliers. Shenzhen and Ningbo anchor cylindrical and prismatic cell production clusters supplying global pack integrators.
India
Diesel displacement programs in Punjab and Haryana are driving mid-size tractor electrification with cost-optimized LFP packs for rice-wheat cultivation cycles. The PLI scheme for ACC batteries is attracting pack assembly investment targeting agricultural machinery OEMs. Tamil Nadu and Karnataka are emerging as cell production clusters serving domestic agricultural electrification demand.
Off-Highway Electric Machine Battery Pack Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Tier 1 automotive suppliers and captive OEM battery divisions control high-volume assembly capacity and thermal management intellectual property. Mid-scale pack integrators compete on modular swap compatibility and rental fleet aftermarket positioning. Dominant competitive moves include strategic partnerships between cell suppliers and construction equipment OEMs, plus geographic expansion of validation laboratory networks to compress UN 38.3 certification timelines.
Among Germany-based industrial equipment specialists, Jungheinrich and Liebherr exemplify the integrated OEM archetype with captive battery development programs. BorgWarner represents the Tier 1 automotive supplier vector leveraging power electronics heritage for construction equipment integration. Caterpillar and Komatsu anchor the mining-focused tier with proprietary validation infrastructure for extreme-duty applications.
| Leading Market Players |
|---|
| Jungheinrich |
| BorgWarner |
| Forsee Power |
| Turntide Technologies |
| Volvo Construction Equipment |
| Wamtechnik |
| Liebherr |
| Caterpillar |
| Komatsu |
| Others |
Pricing and Supply Chain Analysis
UN 38.3 thermal runaway certification gates both supplier qualification timelines and price differentiation across enclosure tiers, compressing margins for pack assemblers unable to demonstrate cell-to-cell propagation resistance while enabling premium positioning for validated designs.
Pricing Analysis
Long-term offtake contracts dominate procurement for mining fleet operators, with spot purchasing limited to rental fleet replacement cycles. Pricing stratifies across UN 38.3-certified premium enclosures, Stage V-compliant mid-tier configurations, and cost-optimized passive-cooled economy packs for agricultural tractors. Cost compression in mid-tier LFP configurations is intensifying because Chinese cell suppliers are scaling cylindrical production for Belt and Road construction equipment. Rental fleet operators exhibit the highest price sensitivity, while underground mining contractors prioritize thermal resilience over unit economics.
Supply Chain Analysis
China and South Korea anchor cylindrical and prismatic cell production, with Shenzhen and Ningbo clusters feeding global pack integrators. Cathode active material supply draws from Indonesian nickel processing and Chilean lithium carbonate refining. Geographic single-source vulnerability concentrates in Chinese cell production, exposing European and North American assemblers to MIIT GB standard compliance disruptions. Distribution runs through captive OEM logistics networks for mining equipment and independent aftermarket channels for rental fleet modular swaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining capital expenditure cycles are recovering from trough levels as copper and iron ore prices stabilize, redirecting fleet electrification budgets toward validated battery systems for 24/7 underground operations.
For Market Incumbents: Fortify thermal management intellectual property positions through captive validation lab expansion in Germany and Australia, where UN 38.3 certification timelines create defensive moats against emerging solid-state specialists. Deepen backward integration into LFP cell supply through offtake agreements with Chinese producers to offset cobalt and lithium price volatility exposure. For New Entrants and Emerging Players: Differentiate on swappable modular architectures standardized across mixed OEM portfolios, targeting Australian and Canadian rental fleets where power-as-a-service contracts are unbundling battery acquisition from machine purchase. Agricultural tractor electrification in India's Punjab region offers the most penetrable entry point, with PLI scheme incentives reducing effective customer acquisition costs for cost-optimized LFP configurations. For Investors and Strategic Acquirers: Europe's F-Gas Regulation reshapes the acquisition landscape by forcing thermal management refrigerant redesigns that favor pack assemblers with CO2-based cooling circuit expertise. Long-term viability centers on second-life stationary storage revenue streams extending pack economic life beyond mining machine retirement. Monitor solid-state validation milestones at Komatsu and Caterpillar as inflection indicators for next-generation chemistry disruption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Management Refrigerant Redesign | F-Gas Regulation compliance enables European OEM qualification for underground mining contracts. |
| Second-Life Stationary Storage Deployment | Retired mining packs stabilize Chilean copper operation microgrids, creating circular revenue streams. |
| Modular Swap Infrastructure Buildout | Perth logistics hubs serve Western Australian open-pit operations with rapid battery exchange protocols. |
| Backward Integration into LFP Supply | German OEMs secure cell offtake agreements reducing exposure to Chinese supply concentration risk. |
| Power-as-a-Service Contract Structuring | Third-party energy managers assume pack replacement responsibility for Australian rental fleets. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with OEM battery division directors, mining fleet procurement managers, thermal management engineering leads, and rental fleet operations heads; and secondary validation through MIIT GB standard filings, EPA Tier 4 Final regulatory dockets, EU F-Gas Regulation implementation guidance, and customs trade data on cell and cathode material flows. Bottom-up pack shipment estimates triangulated against top-down mining equipment electrification capital expenditure patterns.
Across the analysis window, projections incorporated chemistry-specific adoption curves, machine-type duty cycle intensity differentials, and regional regulatory enforcement timelines. Segmentation dimensions modeled include battery chemistry, machine integration architecture, deployment type, and end-user industry maturity. CAGRs derived from fitted growth curves anchored to mining fleet electrification mandates and construction equipment emissions compliance deadlines.
Material uncertainties — cobalt and lithium price volatility, solid-state cell commercialization timelines, F-Gas refrigerant phase-down enforcement stringency — sit outside the modeled envelope. Recalibration cycles align with material shifts in mining commodity prices and regulatory certification requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
Norway Electric Vehicle Market