
 Canada Connector Market | 2026-2036
Canada Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Connector Market Insights
Market Context with Strategic Players
Trained electromechanical assembly labor is collapsing across southern Ontario manufacturing corridors, forcing connector suppliers to automate or relocate precision operations. TE Connectivity anchors Canadian aerospace connector demand through long-term OEM partnerships in Montreal's avionics supply chain. Molex LLC leverages its fiber optic portfolio to compete for data center contracts in Toronto's growing cloud infrastructure market. Amphenol Corporation sustains defence sector revenue through in-house production of mil-spec interconnects qualified under Canadian military procurement standards.
Technical Definition and Structural Segments
Connectors are electromechanical devices engineered to establish removable conductive pathways between circuits, typically specified by contact pitch, current-carrying capacity, insertion force, and environmental sealing ratings per IP or MIL-STD classifications. Their primary commercial purpose is to enable modular assembly, field serviceability, and signal integrity across electronic systems without permanent soldering. Fiber optic and USB connector types command expanding share as telecommunications and consumer electronics verticals prioritize bandwidth density and standardized charging architectures. Defence and aerospace applications still generate premium margin pools due to extended qualification cycles and traceability requirements that limit supplier entry. Plastic and copper material types dominate volume production, though ceramic substrates gain traction in medical equipment for biocompatibility and thermal stability.
Regulatory Framework and Forward Outlook
Health Canada and the Canadian Standards Association govern medical and general electrical connector safety, while Department of National Defence procurement regulations mandate Canadian value-added content and ITAR-aligned export controls for military interconnects. These frameworks elevate compliance costs but create defensive positioning for qualified domestic suppliers against unapproved imports. Stakeholders must monitor whether NRCan energy efficiency directives extend to data center power distribution connectors, as this would reshape product roadmaps for Ontario and Quebec facility buildouts.
Market Dynamics
Defence procurement cycles and data center buildouts in Ontario and Quebec are compressing supplier qualification timelines while accelerating demand for mil-spec and high-density fiber optic interconnects. This dual-pressure environment is forcing connector manufacturers to balance military traceability requirements against cloud infrastructure speed-to-market demands.
Growth Catalysts
- Health Canada medical device regulations:Biocompatibility mandates for patient-contact equipment are expanding the addressable market for ceramic-substrate connectors in diagnostic and therapeutic devices.
- Department of National Defence procurement:Canadian value-added content requirements and ITAR-aligned export controls are creating defensive positioning for qualified domestic suppliers against unapproved imports.
- Toronto-Montreal corridor concentration:Telecommunications infrastructure and military electronics clusters are generating localized demand pull for precision electromechanical assembly capacity.
Market Restraints
- Copper price volatility:Raw material cost swings in conductive alloys are compressing margin predictability for high-volume plastic and copper connector production.
- Southern Ontario labor scarcity:Collapsing availability of trained electromechanical assembly technicians is forcing automation investments or operational relocation.
- Extended military qualification cycles:Traceability and testing protocols under Canadian military procurement standards limit supplier entry and elongate revenue recognition timelines.
Strategic Opportunities
- Quebec data center expansion:Cloud infrastructure buildouts around Montreal are creating demand for fiber optic interconnects with higher bandwidth density specifications.
- NRCan energy efficiency directives:Potential extension to data center power distribution connectors would reshape product roadmaps for Ontario facility operators.
- 5G telecommunications rollout:Higher-density fiber optic interconnect requirements are opening specification windows for suppliers with advanced signal integrity capabilities.
Industry Challenges
- Automation capex intensity:Precision connector assembly requires capital-intensive robotic systems to offset collapsing manual labor availability in Ontario manufacturing corridors.
- Dual certification complexity:Suppliers must simultaneously satisfy Health Canada medical device regulations and Department of National Defence procurement standards for diversified revenue streams.
- Legacy system integration friction:Military electronics clusters require backward-compatible interconnects that constrain adoption of next-generation form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Connector Market |
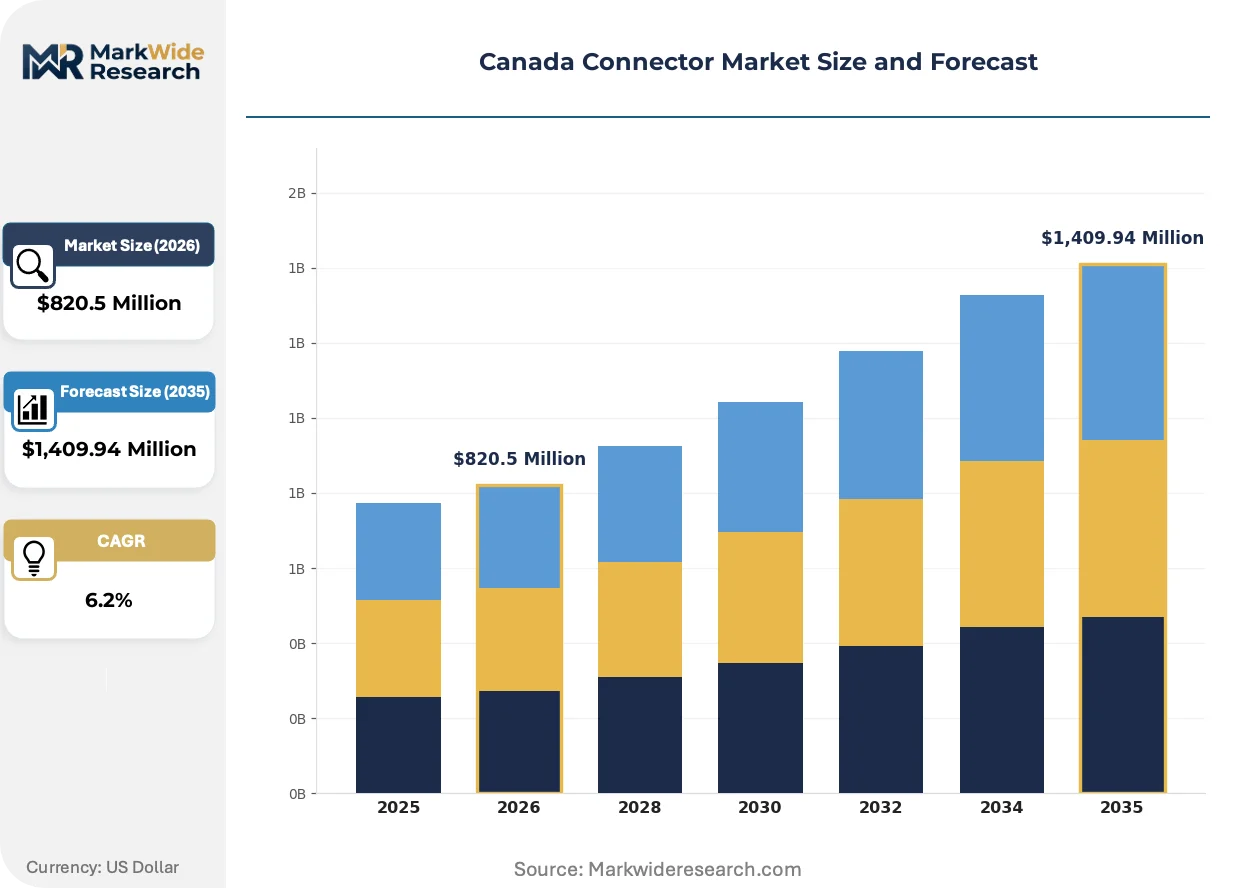
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,409.94 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connector Type: Coaxial, USB, HDMI, RJ45, Fiber Optic, D-Sub Industry Vertical: Telecommunications, Aerospace, Consumer Electronics, Defence, Data Centers, Medical Equipment Material Type: Plastic, Aluminum, Copper, Brass, Stainless Steel, Ceramic End User: OEMs, System Integrators, Aftermarket Suppliers, Contract Manufacturers, Specifiers |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex LLC, Texcan, Canadian Connector Corp., EDAC, Inc., Future Electronics, Hirose Electric Co. Ltd., 3M Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Connector Market Trends and Innovations
Fiber optic technology is actively reshaping competitive positioning in Canadian connector markets as bandwidth density requirements outpace copper's physical limitations. Three convergent forces are redefining product roadmaps and supplier qualification criteria.
Higher-density fiber optic interconnects are supplanting traditional copper backplane connectors in Toronto's expanding cloud infrastructure facilities. Hyperscale operators are specifying single-mode and multi-mode fiber assemblies for intra-rack and inter-rack connectivity. This transition is compressing demand for legacy copper interconnects while elevating suppliers with optical termination expertise.
Health Canada's evolving medical device regulations are mandating enhanced biocompatibility and sterilization resistance for patient-contact connectors. Ceramic substrate materials are gaining specification share in diagnostic imaging and surgical equipment. Equipment OEMs serving Canadian healthcare systems are requalifying supplier bases to meet these material and documentation requirements.
Defence procurement officers are compressing supplier evaluation timelines while maintaining ITAR-aligned traceability standards. This behavioral shift is favoring incumbent manufacturers with established Canadian military qualification histories over new market entrants. The tension between speed and compliance is most acute in Montreal's avionics supply chain, where long-term OEM partnerships anchor purchasing decisions.
Canada Connector Market Segmentation
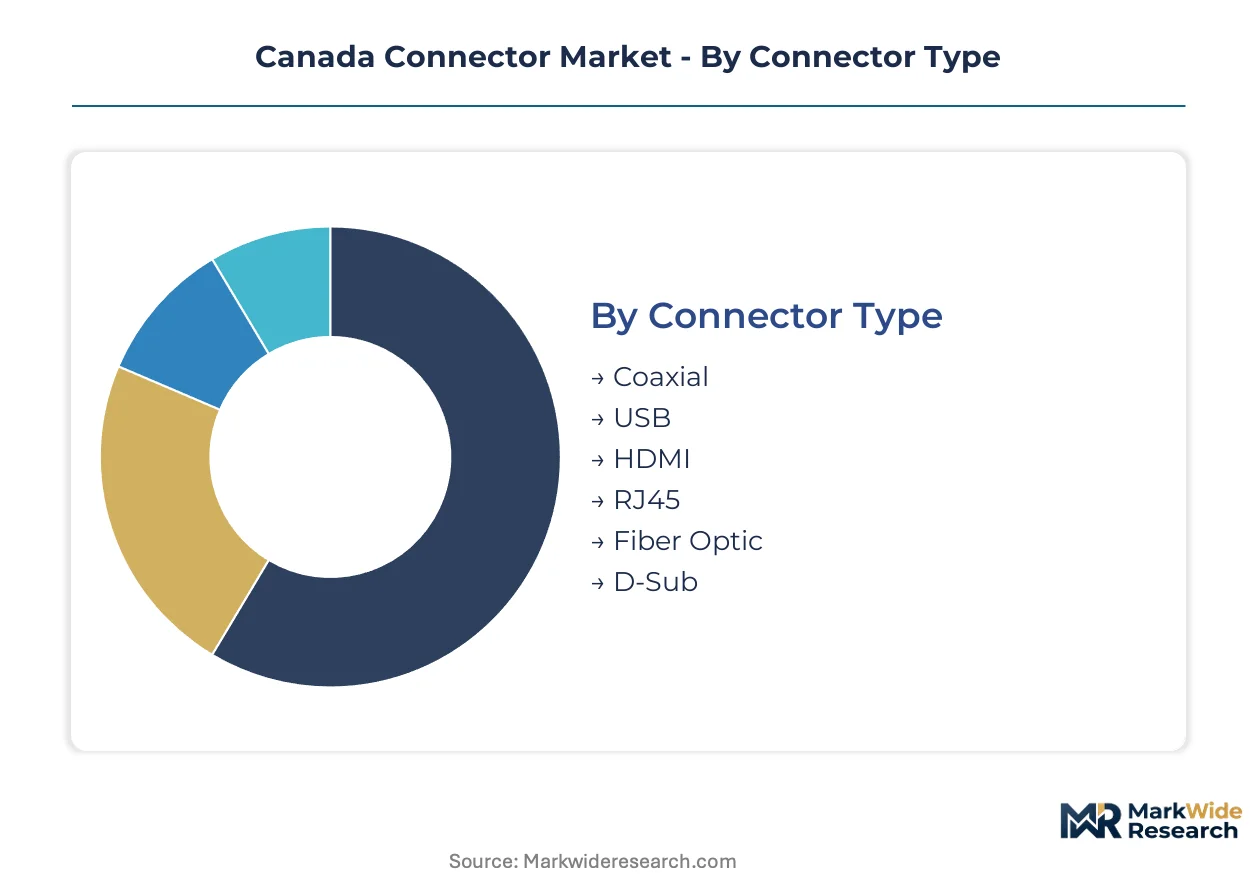
Connector segmentation in Canada reveals divergent margin structures across military, medical, and cloud infrastructure applications. Procurement officers and design engineers prioritize fundamentally different performance attributes, forcing suppliers to maintain parallel product portfolios with distinct qualification pathways.
Connector Type:
Premium margin pools concentrate in fiber optic and mil-spec coaxial formats where qualification barriers limit supplier entry. Volume production favors standardized interfaces with shorter certification cycles.
- Coaxial:Radio-frequency connectors engineered for impedance-matched signal transmission across 50-ohm and 75-ohm standards. Defence electronics clusters around Montreal specify these for radar and communications systems where ITAR traceability requirements sustain elevated pricing.
- Fiber Optic:Single-mode and multi-mode optical interconnects terminating LC, SC, or MPO formats. Hyperscale data center operators in Toronto's cloud corridor are driving demand for higher-density fiber assemblies as copper backplanes reach bandwidth limits.
- USB:Standardized copper interconnects governed by USB-IF specifications for power delivery and data rates.
- HDMI:Consumer electronics interface with established royalty structures and high-volume manufacturing economics.
- RJ45:Copper twisted-pair connector for Ethernet networking with mature supply chains and compressed margins.
- D-Sub:Legacy rectangular connector format with declining specification share outside industrial and military maintenance applications.
Fiber optic holds installed capacity. USB is rotating up the share rankings.
Industry Vertical:
Application requirements fragment across extended qualification cycles in defence and aerospace versus compressed procurement timelines in cloud infrastructure.
- Defence:Mil-spec interconnects subject to Department of National Defence procurement standards and Canadian value-added content mandates. Montreal avionics OEMs anchor long-term supply agreements with traceability documentation requirements that elongate revenue recognition.
- Data Centers:Cloud facility buildouts in Ontario and Quebec specify high-density fiber optic interconnects for intra-rack and inter-rack connectivity. Procurement officers prioritize speed-to-market over extended qualification protocols.
- Telecommunications:5G infrastructure rollout demands signal integrity optimization across outdoor and indoor deployment scenarios.
- Aerospace:Commercial and military aviation applications with AS9100 quality system requirements and extended product lifecycle support obligations.
- Consumer Electronics:High-volume, short-lifecycle applications with standardized interfaces and aggressive cost-down pressures.
- Medical Equipment:Patient-contact devices governed by Health Canada biocompatibility regulations mandating ceramic substrate materials in diagnostic and surgical equipment.
Defence commands pricing power. Data centers are expanding most quickly.
Material Type:
Raw material selection directly determines thermal performance, corrosion resistance, and regulatory compliance pathways across end-use applications.
- Copper:Primary conductive alloy for signal and power transmission with established plating and termination processes. Price volatility in London Metal Exchange contracts compresses margin predictability for high-volume connector manufacturers serving consumer and industrial markets.
- Ceramic:Alumina and zirconia substrate materials specified for biocompatibility and sterilization resistance under Health Canada medical device regulations. Diagnostic imaging OEMs are requalifying supplier bases to meet material documentation requirements.
- Plastic:Injection-molded housings in PBT, PA, and LCP resins for cost-sensitive high-volume applications.
- Aluminum:Lightweight conductive shells for aerospace and military applications requiring electromagnetic interference shielding.
- Brass:Machined contact bodies with nickel and gold plating for moderate-duty commercial applications.
- Stainless Steel:Corrosion-resistant shells for harsh environment deployments in marine and industrial settings.
Copper dominates volume throughput. Ceramic is climbing the fastest.
End User:
Purchasing authority concentrates among OEM design engineers and military procurement officers with divergent technical evaluation criteria.
- OEMs:Original equipment manufacturers in Toronto and Montreal corridors specifying connectors during product design phases. Long-term supply agreements with TE Connectivity, Molex, and Amphenol anchor procurement decisions for avionics and telecommunications platforms.
- Contract Manufacturers:Electromechanical assembly providers facing trained labor scarcity across southern Ontario manufacturing corridors. Automation investments or operational relocation are becoming necessary to maintain precision assembly capacity.
- System Integrators:Infrastructure contractors specifying interconnects for data center and telecommunications deployment projects.
- Aftermarket Suppliers:Maintenance and repair organizations sourcing legacy-compatible connectors for extended-lifecycle military and industrial equipment.
- Specifiers:Consulting engineers and procurement consultants influencing connector selection through technical specifications and approved vendor lists.
OEMs retain design authority. Contract manufacturers are gaining procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada and the Department of National Defence anchor regulatory frameworks across Canadian provinces, with connector demand concentrating in Ontario and Quebec manufacturing corridors where defence procurement and data center buildouts intersect.
Ontario
Data center buildouts in Toronto's cloud infrastructure corridor are accelerating demand for high-density fiber optic interconnects. NRCan energy efficiency directives may extend to power distribution connectors, reshaping procurement specifications for facility operators. Southern Ontario manufacturing corridors face trained electromechanical assembly labor scarcity, forcing automation investments among precision connector suppliers.
Quebec
Defence procurement programs and Montreal's avionics supply chain sustain premium demand for mil-spec interconnects with ITAR-aligned traceability requirements. Canadian value-added content mandates under Department of National Defence standards create defensive positioning for qualified domestic suppliers. Long-term OEM partnerships in aerospace electronics clusters anchor purchasing decisions and elongate revenue recognition timelines.
British Columbia
Telecommunications infrastructure deployment along the Pacific coast generates demand for 5G-optimized connectors with signal integrity specifications. The province's technology sector procurement patterns prioritize speed-to-market over extended qualification protocols common in defence applications. Vancouver-area system integrators specify interconnects for smart city and transportation electrification projects.
Alberta
Energy sector automation and industrial IoT deployments drive demand for harsh-environment connectors in oilfield and mining equipment. Provincial industrial safety regulations govern electrical interconnect specifications for hazardous location installations. Calgary-based system integrators source connectors for midstream infrastructure digitization projects.
Canada Connector Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around companies possessing dual military-commercial qualification capabilities. The competitive terrain splits between incumbent manufacturers with established Canadian defence procurement histories and challengers targeting data center speed-to-market demands. Strategic archetypes include vertically integrated global suppliers, regional specialists with niche certification expertise, and distribution-focused intermediaries. Dominant competitive moves center on automation capex deployment to offset Ontario labor scarcity and strategic partnerships with hyperscale data center operators.
Among North American integrated suppliers, TE Connectivity and Amphenol Corporation exemplify the qualification-heavy archetype with established Canadian military and aerospace positioning. Molex LLC represents the fiber optic-specialized tier competing for Toronto data center contracts. These three entities anchor the competitive structure, with their divergent geographic and technological emphases reflecting the market's bifurcation between defence traceability requirements and cloud infrastructure speed demands.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex LLC |
| Texcan |
| Canadian Connector Corp. |
| EDAC, Inc. |
| Future Electronics |
| Hirose Electric Co. Ltd. |
| 3M Company |
| Others |
Pricing and Supply Chain Analysis
Health Canada medical device regulations and Department of National Defence procurement standards simultaneously gate supplier qualification and stratify price tiers across the Canadian connector market. These dual certification regimes force manufacturers to absorb compliance costs that translate directly into premium pricing for qualified products while compressing margins on unapproved imports.
Pricing Analysis
Long-term offtake agreements anchor pricing for mil-spec interconnects serving Montreal's avionics OEMs, while spot-market transactions dominate fiber optic procurement for Toronto data center buildouts. Three-tier pricing structure across ITAR-qualified, Health Canada-certified, and standard commercial levels reflects traceability documentation burdens. Cost compression in high-volume copper connector production intensifies as London Metal Exchange alloy volatility erodes margin predictability. Contract manufacturers exhibit highest price sensitivity due to automation capex burdens, whereas defence procurement officers prioritize qualification certainty over unit cost.
Supply Chain Analysis
Port congestion across Vancouver and Montreal trade lanes elevates inbound logistics costs for ceramic substrate materials sourced from Japanese and German specialty suppliers. Manufacturing concentration rests on China for injection-molded plastic housings, Mexico for machined brass contacts, and the United States for mil-spec coaxial assemblies. Single-source vulnerability in optical fiber preform supply constrains Toronto data center deployment timelines. Distribution runs through authorized distributors with Health Canada and DND qualification credentials, bypassing open-market channels for regulated applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision electromechanical assembly labor scarcity across southern Ontario corridors is constraining output expansion and forcing capital reallocation toward automation. This capability gap rewards suppliers with qualified robotic assembly capacity while penalizing manual-dependent operations.
For Market Incumbents: Consolidate long-term OEM partnerships in Montreal's avionics supply chain through exclusive qualification support and co-development programs. Deepen backward integration into ceramic substrate machining to capture Health Canada medical device margin expansion. Prioritize automation deployment in Ontario manufacturing corridors to offset collapsing technician availability.
For New Entrants and Emerging Players: Health Canada certification fast-track programs offer entry pathways into diagnostic imaging connector supply chains underserved by incumbent capacity. Target data center fiber optic specifications where speed-to-market demands outpace legacy supplier response times. Pursue system integrator partnerships for Toronto cloud infrastructure projects bypassing traditional OEM channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic precision assembly sub-segments as labor substitution becomes mandatory. Five-to-ten year viability favors targets with dual DND-Health Canada qualification histories and installed automation base. Monitor NRCan energy efficiency directive announcements as inflection signal for power distribution connector specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Assembly Automation | Offsets southern Ontario electromechanical technician scarcity for precision connector manufacturing. |
| Dual Certification Investment | Simultaneous Health Canada and DND qualification expands addressable market across medical and defence verticals. |
| Fiber Optic Capacity Expansion | Captures Toronto data center demand as copper backplanes reach bandwidth density limits. |
| Ceramic Substrate Backward Integration | Secures biocompatibility-compliant material supply for diagnostic imaging equipment connectors. |
| Hyperscale Data Center Partnership | Direct specification relationships with cloud operators compress procurement cycles versus OEM channels. |
Research Methodology
Initial hypotheses were tested against primary input from connector procurement officers at Toronto data center operators, Montreal avionics OEM supply chain directors, Health Canada regulatory affairs specialists, and southern Ontario contract manufacturing executives and refined through secondary validation. Primary fieldwork combined structured interviews with electromechanical assembly technicians and procurement decision-makers. Secondary sources encompassed Department of National Defence procurement bulletins, Health Canada medical device establishment licenses, Canadian Standards Association certification databases, and hyperscale operator capex disclosures. Bottom-up demand modeling and top-down supply capacity estimates were triangulated for coherence.
Variance decomposition across connector type, industry vertical, material substrate, and end-user purchasing authority informed the analytical framework. Modeled dimensions included fiber optic versus copper architectures, defence versus medical versus data center applications, ceramic versus plastic versus metallic materials, and OEM versus contract manufacturer procurement channels. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Forecast inputs incorporated NRCan facility energy standards evolution and 5G infrastructure deployment cadence.
The analysis sits within stated boundaries; outcomes outside sustained defence procurement continuity, Health Canada regulatory stability, or southern Ontario labor market conditions would require recalibration. Forecasts reflect documented assumptions regarding certification timeline durations and raw material cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
IC Socket Market
Connectors
Filtered Connectors Market
Connectors
Global Automotive Connector Market
Connectors
Mexico Connector Market
Connectors
Smart Crimper Market
Connectors
Power Connector Market
Connectors
Circular Connectors Market
Connectors
Circular Waterproof Connector Market
Connectors
Connector Adapter Kits Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Underwater Mate Connectors Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Japan Connector Market
Connectors
Automotive Data Connectors Market
Connectors
PCI-E Connectors Market
Connectors
5G Connector Market