
 Global Board to Board (BTB) Connectors Market | 2026-2036
Global Board to Board (BTB) Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Board to Board (BTB) Connectors Market Intelligence
Distributor consolidation among electronics component resellers is narrowing the path to market for mid-tier BTB connector suppliers. TE Connectivity leverages its vertically integrated manufacturing footprint to sustain pricing power across high-reliability segments. Hirose Electric Co Ltd. anchors its competitive position through precision micro-connector specialization in Japanese robotics and medical equipment channels.
Board to board (BTB) connectors are electromechanical interfaces that establish signal and power pathways between printed circuit boards through plated contact arrays, typically engineered with pitch spacing from 0.35mm to 2.54mm and current ratings spanning 1A to 50A depending on application load requirements. These components serve as the structural backbone of modular electronic architectures, enabling system scalability without custom PCB redesign. Stacking configurations command premium positioning due to their space-efficient vertical orientation in compact consumer electronics and telecommunications hardware. Surface mount installation types are displacing through-hole alternatives in high-volume consumer applications where automated assembly throughput determines cost structure.
REACH compliance in Europe and RoHS substance restrictions across multiple jurisdictions are elevating material certification costs while phasing out legacy lead-bearing alloys in contact plating formulations. China's GB standards and the EU's CE marking frameworks create divergent testing protocols that fragment product qualification timelines for multi-region suppliers. Stakeholders must weigh regional certification burden against manufacturing concentration when selecting qualification strategies for next-generation connector portfolios.
Market Dynamics
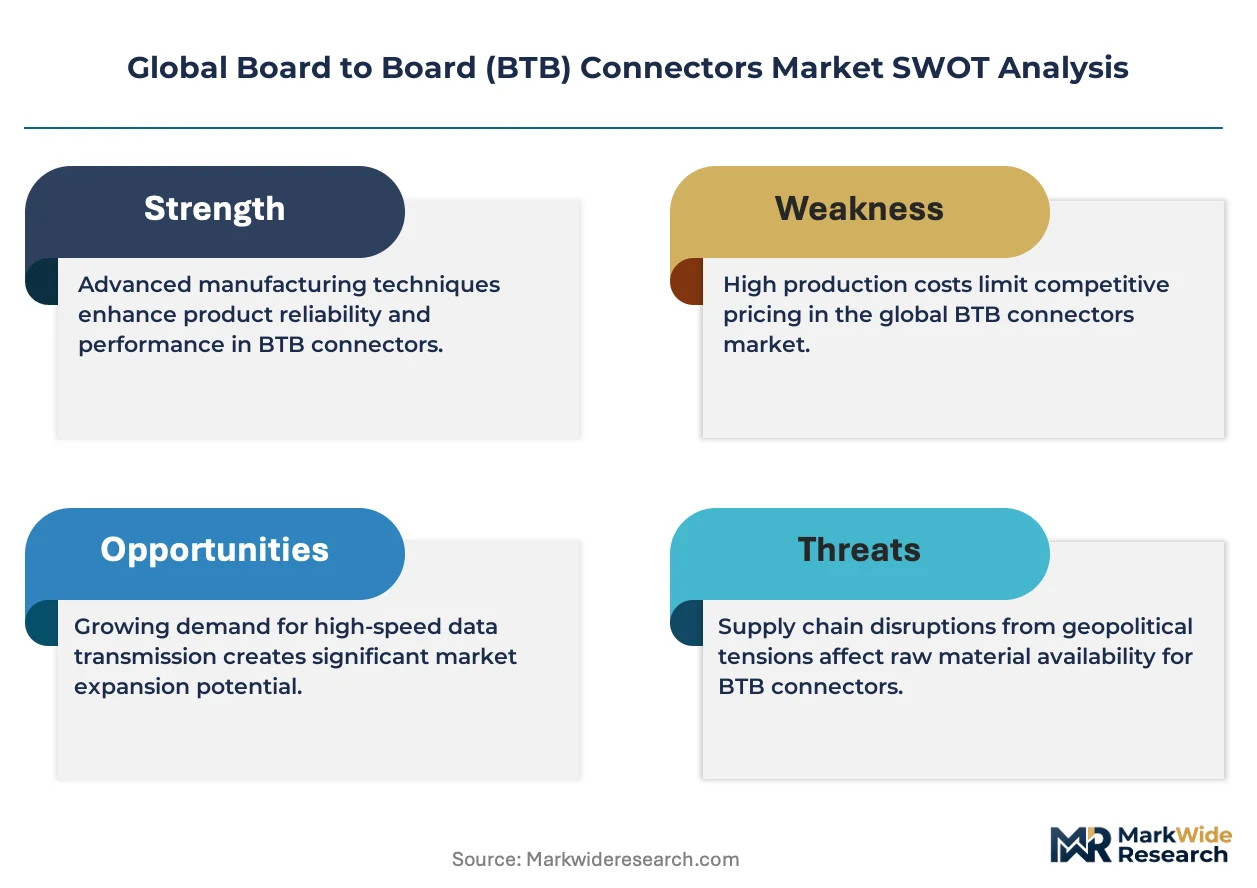
Pitch compression below 0.35mm in consumer electronics is forcing connector architectures toward micro-precision manufacturing, while data center server deployments scale procurement volumes for high-density interconnects.
Growth Catalysts
- Data Center Expansion:Hyperscale server deployments in the United States and China are absorbing high-current BTB variants rated above 30A for power distribution modules.
- RoHS Substance Mandates:Lead-free plating requirements across European and Asian jurisdictions are accelerating tin-silver-copper alloy adoption in contact metallurgy.
- Robotics Integration:Japanese industrial automation OEMs are specifying vibration-resistant locking mechanisms for articulated arm applications.
Market Restraints
- Raw Material Concentration:High-purity copper cathode supply from Chilean and Peruvian mining operations creates price volatility in contact substrate costs.
- Technical Ceiling:Signal integrity degradation below 0.25mm pitch limits further miniaturization without dielectric material breakthroughs.
- REACH Certification Burden:ECHA substance of very high concern (SVHC) screening adds 8-14 weeks to European market entry timelines.
Strategic Opportunities
- Medical Device Convergence:Portable diagnostic equipment combining imaging and biosensing functions demands hybrid power-signal BTB stacks.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are attracting connector qualification programs for smartphone and automotive Tier-1 suppliers.
- 5G mmWave Infrastructure:Base station antenna arrays require sub-millimeter pitch connectors with controlled impedance for 28GHz signal paths.
Industry Challenges
- Precision Tooling Scarcity:Stamping die fabrication for sub-0.4mm terminals requires Swiss and Japanese CNC equipment with 24-month order backlogs.
- Multi-Jurisdiction Testing:GB standards divergence from IEC 60603 creates redundant qualification cycles for products serving Chinese and European OEMs simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Board to Board (BTB) Connectors Market |
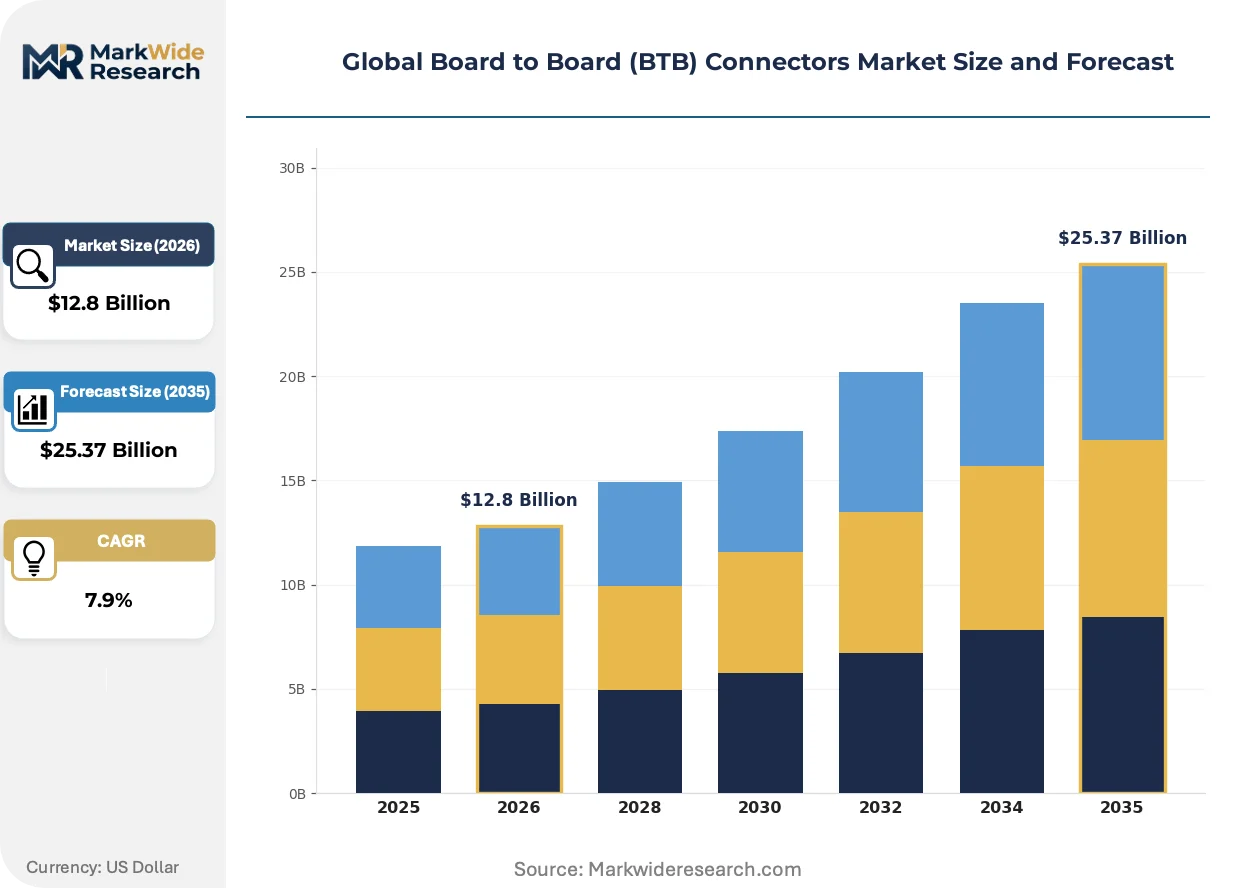
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $25.37 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Row, Double Row, Stacking, Breakaway End User: Consumer Electronics, Telecommunications, Automotive, Industrial Equipment Installation Type: Through Hole, Surface Mount, Press Fit, Embedded Material: Plastic, Metal, Alloy, Ceramic |
| Companies Covered | Molex, Samtec, TE Connectivity, Omron Corporation, CSCONN Corporation, Amphenol Corporation, Japan Aviation Electronics Industry, Ltd., Kyocera Corporation, Hirose Electric Co Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Board to Board (BTB) Connectors Market Strategic Shifts & Innovations
Connector architectures are converging around three vectors: contact physics at atomic scales, regulatory material substitution mandates, and procurement consolidation among electronics manufacturing services.
Laser micro-welding of palladium-nickel barrier layers is digitizing contact fabrication by enabling 3D interconnect geometries impossible with traditional stamping. Medical imaging equipment manufacturers in Germany and Japan are qualifying these structures for 10,000+ insertion cycle lifespans. The technology is digitizing quality assurance protocols through inline X-ray inspection integration.
EU F-Gas Regulation phase-down schedules are pressuring connector housing suppliers to eliminate fluoropolymer dielectrics in favor of liquid crystal polymer alternatives. Automotive Tier-1 suppliers in Stuttgart and Munich face 2027 compliance deadlines for high-voltage battery management interconnects. The transition is compressing material qualification windows and forcing parallel validation tracks.
Consolidated electronics manufacturing services in Taiwan and Mexico are unbundling connector specification authority from traditional OEM engineering teams. Foxconn and Jabil now dictate pitch standards and plating specifications for mid-tier consumer electronics brands. This concentration is visible in smartphone and tablet supply chains where EMS volume commitments override individual OEM preferences.
Global Board to Board (BTB) Connectors Market Segmentation
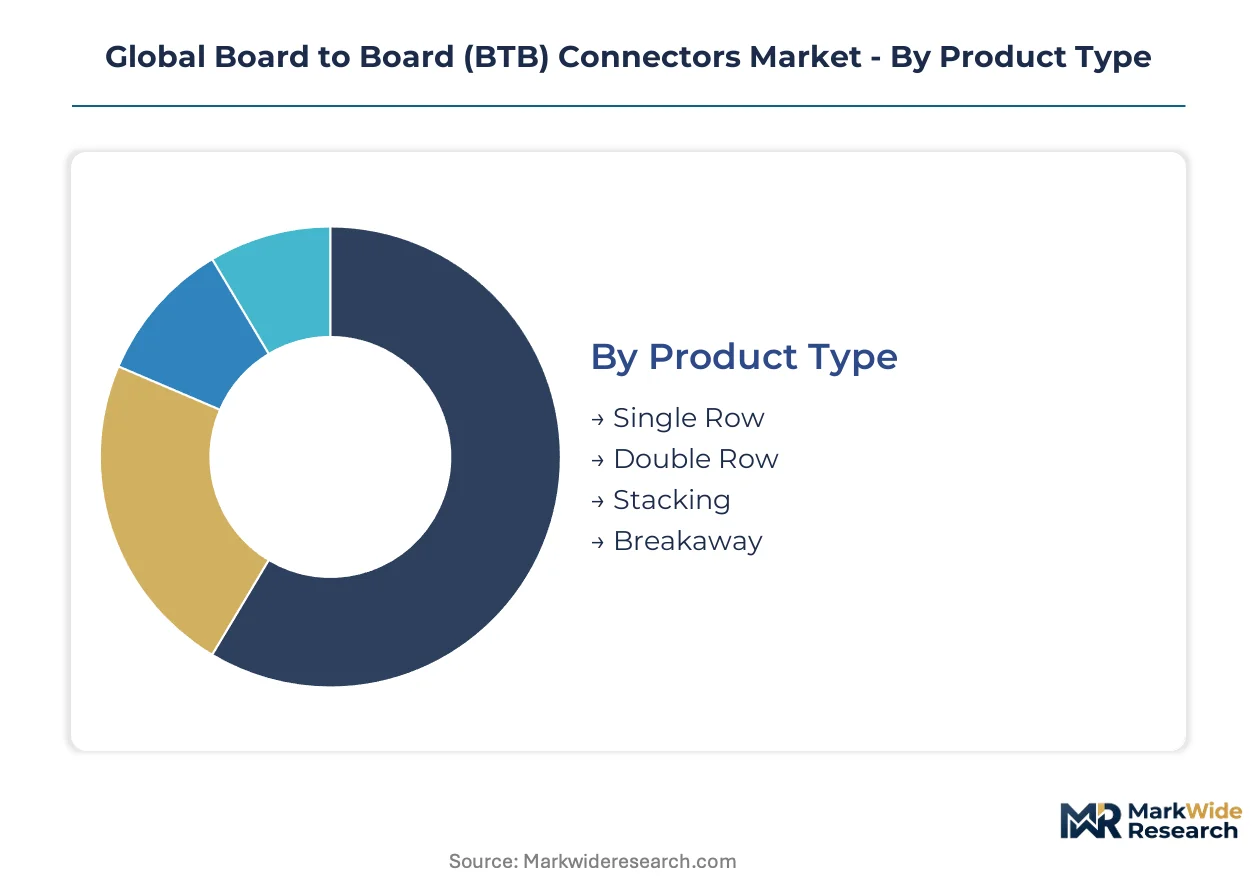
BTB connector procurement patterns diverge sharply across application contexts, with after-sales service intensity varying from minimal in consumer electronics to extensive in industrial automation. Technical specifications cascade differently through each segment tier, shaping supplier qualification requirements and inventory strategies.
Product Type:
After-sales service intensity escalates with connector complexity, stacking configurations demanding field engineering support while breakaway variants require minimal post-installation intervention.
- Stacking:Vertical orientation enables space-efficient PCB arrangements in smartphones and wearables. Shenzhen and Dongguan manufacturing clusters absorb the majority of procurement volumes as consumer electronics OEMs compress device thickness. Signal integrity engineering for high-speed differential pairs drives premium pricing tiers.
- Double Row:Dual-contact arrays double density within equivalent footprint constraints. Data center server backplanes in Ashburn, Virginia and Frankfurt specify these variants for memory module interconnects where current carrying capacity exceeds 15A per contact.
- Single Row:Linear contact arrangements suit cost-sensitive peripheral applications. Japanese automotive Tier-1 suppliers specify these for dashboard module interfaces.
- Breakaway:Frangible designs protect PCBs during assembly misalignment. Mexican contract manufacturers favor these for high-mix, low-volume production runs.
By volume, Double Row leads. By growth pace, Stacking is ahead.
End User:
Margin structures compress toward consumer electronics while industrial equipment sustains premium pricing through qualification longevity and technical support bundling.
- Consumer Electronics:Smartphones, tablets, and wearables drive sub-0.4mm pitch demand. South Korean display panel manufacturers specify micro-connectors for foldable device hinge assemblies where flex cycling exceeds 200,000 repetitions.
- Telecommunications:Base station antenna arrays and router backplanes require controlled impedance matching. Ericsson and Nokia procurement teams in Stockholm and Espoo mandate RoHS-compliant tin-silver-copper plating for 5G mmWave infrastructure deployment.
- Automotive:Battery management systems and ADAS sensor modules specify vibration-resistant locking. Stuttgart OEMs enforce AEC-Q200 qualification for high-voltage interconnects in electric powertrains.
- Industrial Equipment:Factory automation and process control systems prioritize insertion cycle durability. Japanese robotics manufacturers in Nagoya specify 10,000+ cycle lifespans for articulated arm applications.
Consumer Electronics commands the largest revenue pool. Industrial Equipment delivers the steepest expansion trajectory.
Installation Type:
Assembly automation penetration determines installation method selection, with surface mount dominating high-volume consumer applications and press fit gaining traction in automotive power modules.
- Surface Mount:Reflow-compatible termination enables full automation in high-volume production. Taiwanese EMS providers specify these for smartphone motherboard assembly where placement speed exceeds 80,000 components per hour.
- Press Fit:Compliant pin interfaces eliminate soldering for power distribution applications. German automotive suppliers adopt these for battery junction boxes where thermal cycling resistance is critical.
- Through Hole:Mechanical anchoring suits high-vibration environments. Industrial motor drives in the United States retain these for IGBT module connections.
- Embedded:PCB-integrated contacts enable ultra-thin device architectures. Korean consumer electronics OEMs qualify these for tablet and laptop hinge interconnects.
Surface Mount dominates unit volumes. Press Fit is climbing the fastest.
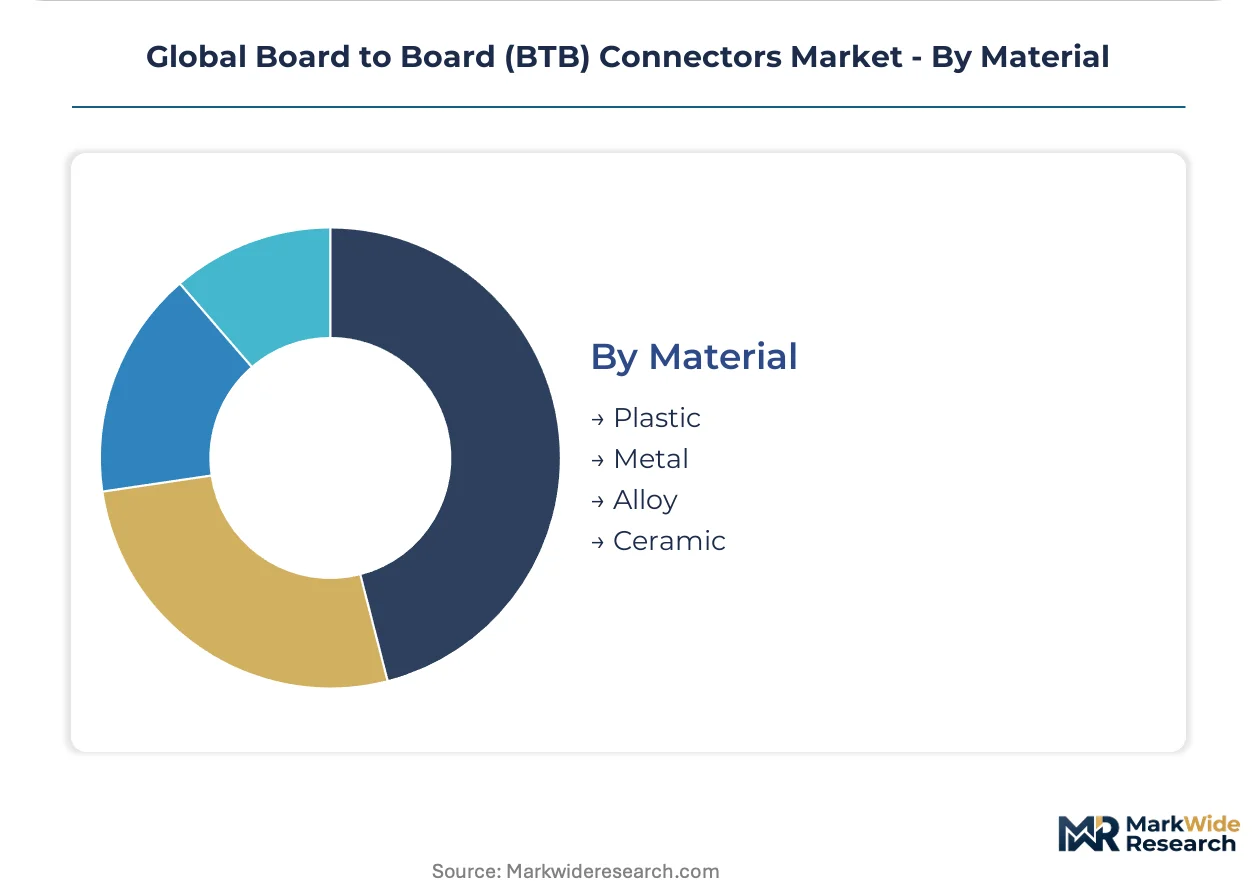
Material:
Dielectric selection balances flammability ratings against dimensional stability, with liquid crystal polymer displacing fluoropolymers under EU F-Gas Regulation pressure.
- Plastic:Liquid crystal polymer and high-temperature nylon dominate housing fabrication. Chinese connector manufacturers in Guangdong province source these for cost-optimized consumer electronics variants.
- Alloy:Copper-beryllium and copper-nickel-silicon deliver spring force retention. Japanese precision component suppliers specify these for sub-0.35mm pitch contact arrays in medical imaging equipment.
- Metal:Brass and phosphor bronze substrates provide conductivity and formability. European automotive suppliers specify tin-silver-copper plated variants for power distribution modules.
- Ceramic:Alumina and aluminum nitride enable extreme temperature operation. Aerospace and defense contractors in the United States specify these for satellite payload interconnects.
Plastic leads by unit shipment. Alloy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and dual carbon goals in China are redirecting connector procurement flows across manufacturing clusters. German automotive OEMs enforce REACH and RoHS compliance for high-voltage battery interconnects. Japanese robotics manufacturers specify vibration-resistant locking mechanisms for factory automation.
United States
Hyperscale data center deployments in Ashburn and Dallas absorb high-current BTB variants rated above 30A for power distribution modules. NHTSA and FAA regulations govern automotive and aerospace interconnect qualification respectively. Silicon Valley EMS providers dictate pitch standards for mid-tier consumer electronics brands.
China
MIIT dual carbon goals accelerate lead-free plating adoption in contact metallurgy across Shenzhen and Dongguan manufacturing clusters. GB standards divergence from IEC protocols creates redundant qualification cycles for multi-region suppliers. Shanghai and Suzhou electronics manufacturing services concentrate procurement authority for smartphone and tablet supply chains.
Germany
Stuttgart and Munich automotive Tier-1 suppliers enforce AEC-Q200 qualification for electric powertrain interconnects facing 2027 EU F-Gas Regulation compliance deadlines. ECHA REACH substance screening adds certification burden for European market entry. Bavarian industrial automation OEMs specify 10,000+ insertion cycle lifespans for articulated robotics applications.
Japan
METI-backed robotics integration programs drive vibration-resistant locking mechanism demand in Nagoya manufacturing corridors. JIS standards anchor precision micro-connector specifications for medical imaging equipment. Osaka and Tokyo precision component suppliers specialize in sub-0.35mm pitch contact arrays.
India
PLI scheme incentives for semiconductor packaging attract connector qualification programs for smartphone and automotive Tier-1 suppliers. BIS standards create domestic certification requirements distinct from IEC frameworks. Karnataka and Tamil Nadu electronics manufacturing clusters absorb disproportionate demand share from contract manufacturers.
Global Board to Board (BTB) Connectors Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated specialists and precision micro-connector fabricators with captive plating capabilities. Three archetypes dominate: diversified electromechanical conglomerates with global manufacturing footprints, Japanese precision component specialists serving robotics and medical channels, and Taiwan-based EMS-integrated suppliers. Competitive moves center on backward integration into high-purity copper substrate supply and strategic partnerships with Swiss and Japanese CNC equipment vendors to secure stamping die fabrication capacity.
Within the diversified conglomerate tier, TE Connectivity and Amphenol Corporation exemplify scale-driven positioning through vertically integrated manufacturing footprints. Among Japanese precision specialists, Hirose Electric Co Ltd. and Japan Aviation Electronics Industry, Ltd. occupy positions anchored by micro-connector specialization in robotics and medical equipment channels. Kyocera Corporation represents the ceramic substrate vector for extreme temperature aerospace and satellite applications.
| Leading Market Players |
|---|
| Molex |
| Samtec |
| TE Connectivity |
| Omron Corporation |
| CSCONN Corporation |
| Amphenol Corporation |
| Japan Aviation Electronics Industry, Ltd. |
| Kyocera Corporation |
| Hirose Electric Co Ltd. |
| Others |
Cost & Logistics Intelligence
Shenzhen and Dongguan manufacturing clusters concentrate surface-mount BTB connector capacity, and this geographic density amplifies pricing power for vertically integrated suppliers serving high-volume consumer electronics contracts. Raw material volatility in copper cathode markets and extended qualification timelines for REACH-compliant plating formulations feed downstream cost structures, compressing margins for mid-tier fabricators while reinforcing premium positioning for certified specialists.
Pricing Analysis
Certification level (AEC-Q200/REACH/RoHS-grade) creates the primary spread between premium and standard tiers, with automotive-qualified variants commanding substantial markups over consumer-grade equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity: premium tiers incorporate field engineering support and cycle-life guarantees, while economy variants compete purely on unit cost. Cost compression in consumer electronics tiers is intensifying because Taiwanese EMS providers consolidate procurement authority and squeeze supplier margins. Data center and industrial automation buyers exhibit lowest price sensitivity due to reliability premiums, whereas smartphone OEMs drive hardest bargain terms.
Supply Chain Analysis
Extended payment terms from consolidated electronics manufacturing services in Taiwan and Mexico are reshaping working capital requirements for component suppliers, forcing mid-tier fabricators to seek supply-chain finance facilities. Raw material sourcing draws from Chilean and Peruvian copper cathode operations, Japanese precision alloy suppliers, and Chinese rare earth processors. Single-source vulnerability concentrates in Swiss and Japanese CNC equipment for sub-0.4mm terminal stamping dies, where 24-month order backlogs create qualification bottlenecks. Distribution runs through authorized distributor networks and direct EMS contracts, with Foxconn and Jabil unbundling traditional OEM specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BTB connector demand tracks semiconductor capital expenditure cycles, and the current recovery phase in data center server deployments signals favorable absorption capacity across the projection horizon.
For Market Incumbents: Pre-empt margin erosion from EMS procurement consolidation by securing captive plating capabilities and locking multi-year offtake agreements with Chilean copper suppliers. Channel control through exclusive distributor partnerships in Japanese robotics corridors defends positioning against emerging precision specialists from South Korea. Certification investment in AEC-Q200 and EU F-Gas-compliant liquid crystal polymer formulations creates switching costs for Stuttgart automotive Tier-1 suppliers. For New Entrants and Emerging Players: Medical imaging equipment in Germany and Japan represents the most penetrable entry point, where 10,000+ insertion cycle requirements and palladium-nickel barrier layer specifications favor specialized fabricators over diversified conglomerates. Indian smartphone and automotive Tier-1 suppliers under PLI scheme incentives offer second white-space target, with BIS certification creating domestic qualification barriers that foreign entrants can leverage through local joint ventures. Go-to-market angle: partner with Osaka precision component suppliers for micro-connector technology transfer. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Japanese precision specialists serving medical and robotics channels, where qualification longevity and technical support bundling generate multi-year contract visibility. Acquisition target archetype: sub-0.35mm pitch fabricators with captive plating and existing AEC-Q200 certification, positioned for electric powertrain and ADAS sensor module growth. Signal to watch as inflection indicator: order backlog duration at Swiss and Japanese CNC equipment vendors, which predicts capacity constraints and pricing power shifts across the precision connector tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Copper Substrate Supply | Captive sourcing from Chilean and Peruvian mining operations insulates margin volatility from cathode price swings. |
| Strategic Partnership with Swiss and Japanese CNC Equipment Vendors | Secured stamping die fabrication capacity breaks 24-month bottlenecks for sub-0.4mm terminal production. |
| Liquid Crystal Polymer Material Qualification | EU F-Gas Regulation compliance by 2027 deadlines opens Stuttgart and Munich automotive Tier-1 supplier access. |
| Medical Imaging Equipment Channel Development | German and Japanese OEM 10,000+ cycle specifications command premium positioning and technical support bundling. |
| India PLI Scheme Localization | Karnataka and Tamil Nadu electronics manufacturing cluster access captures smartphone and automotive Tier-1 procurement growth. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with connector procurement managers at Taiwanese EMS providers, platform engineers at German automotive Tier-1 suppliers, biomedical equipment specialists in Japan, and data center infrastructure planners in the United States; alongside secondary validation through SEC 10-K filings, customs and trade data, MIIT dual carbon policy documents, ECHA REACH substance databases, and IEC/GB standards divergence analysis. Bottom-up and top-down triangulation cross-validated segment-level volume estimates against aggregate market sizing.
Forecast inputs considered product type segmentation across stacking, double row, and single row configurations; end-use splits spanning consumer electronics, telecommunications, automotive, and industrial equipment; and installation method differentiation between surface mount, press fit, and through hole variants. CAGRs derived from regression analysis of historical procurement patterns and forward-looking capital expenditure disclosures from hyperscale data center operators and semiconductor packaging facilities. Industry-specific inputs included pitch compression trajectories, insertion cycle durability benchmarks, and regional certification timeline differentials.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, copper cathode spot prices, or EMS consolidation velocity would shift the trajectory. Forecasts reflect documented assumptions about technology adoption curves, regulatory compliance deadlines, and supply chain configuration stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Space Grade Connectors Market
Connectors
Terminal Pins Market
Connectors
Canada Connector Market
Connectors
Press Fit Connector Market
Connectors
Australia Connector Market
Connectors
Liquid Cooling Connector Market
Connectors
Global Fiber Optic Connectors Market
Connectors
Japan Connector Market
Connectors
Connector Market
Connectors
High-Reliability Connectors Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Global Automotive Connector Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Mexico Connector Market
Connectors
LCP Connectors Market