
 Global Biological Microscope Objectives Market | 2026-2036
Global Biological Microscope Objectives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biological Microscope Objectives Market Foresight
EU MDR is repositioning the cost-of-entry calculus for objective manufacturers serving diagnostic end users. Olympus leverages its vertically integrated glass formulation capabilities to sustain margin structures under tighter traceability mandates. Nikon anchors its position through proprietary immersion media chemistry that extends working distance specifications. Carl Zeiss differentiates via extreme ultraviolet-grade polishing competencies originally developed for semiconductor lithography.
Biological microscope objectives are precision optical assemblies comprising multiple lens elements with sub-micron centering tolerances, designed to resolve cellular structures at magnifications typically spanning 4x to 100x with numerical apertures determining light-gathering capacity. Plan Apochromat objectives command premium positioning due to chromatic correction across four or more wavelengths, while Plan Fluorite variants occupy the high-volume middle tier favored by academic institutions balancing performance against grant-funded capital constraints. Anti-reflection coatings and phase contrast optical treatments represent margin-accretive aftermarket attachment points as laboratories retrofit existing objective turrets rather than replace complete microscope systems.
FDA 21 CFR Part 820 quality system requirements shape design control documentation for objectives incorporated into registered diagnostic devices, while ISO 10993 biocompatibility protocols govern immersion oil contact surfaces. Japan's METI maintains JIS standards for optical performance testing that influence procurement specifications across Asia-Pacific research consortia. Stakeholders must monitor convergence between medical device software validation requirements and embedded firmware in automated turret positioning systems.
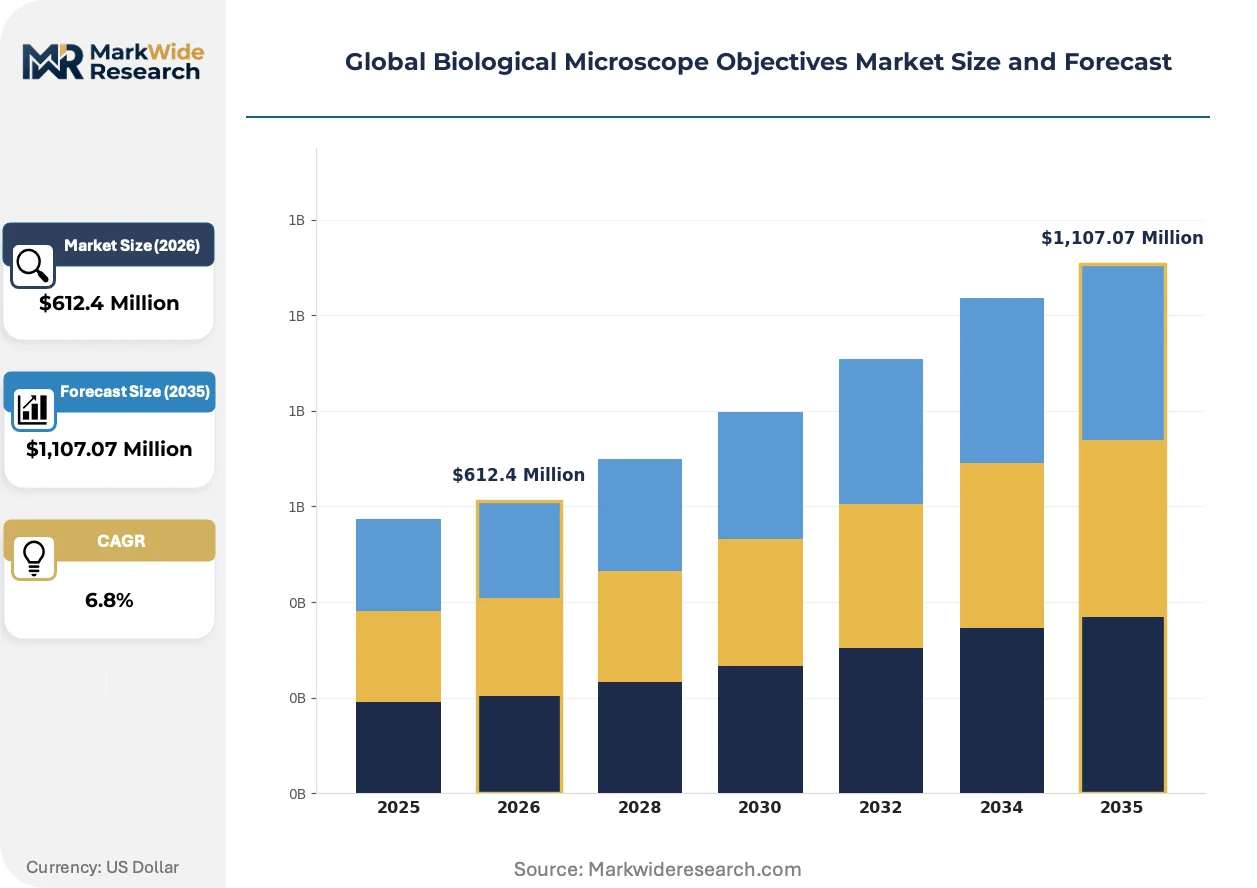
Market Dynamics
EU MDR documentation mandates are forcing objective manufacturers to restructure quality management systems around optical traceability, compressing margins for smaller suppliers while rewarding vertically integrated glass formulators with captive metrology capabilities.
Growth Catalysts
- Cell-based assay workflows:Pharmaceutical developers are scaling high-numerical-aperture objective procurement to support phenotypic screening pipelines. FDA 21 CFR Part 820 design controls are accelerating documentation standardization across diagnostic device integrations.
- Semiconductor lithography spillover:Extreme ultraviolet-grade polishing competencies developed for chip fabrication are migrating into biological objective manufacturing, enabling sub-wavelength surface finishes previously unattainable in life sciences optics.
- Japan METI JIS standards:Asia-Pacific research consortia are adopting Japanese optical performance testing protocols as procurement baselines, expanding addressable demand across Singapore, South Korea, and Australian institutional buyers.
Market Restraints
- Fluorite crystal supply concentration:High-grade synthetic fluorite for Plan Fluorite objectives originates from three primary chemical synthesis facilities in Germany and Japan, creating input vulnerability.
- Anti-reflection coating equipment capex:Ion-beam sputtering systems for broadband AR stacks require 18-24 month lead times and specialized cleanroom infrastructure, gating capacity expansion.
- ISO 10993 biocompatibility testing timelines:Immersion oil contact surface validation protocols extend product launch cycles by 8-14 months for diagnostic-registered objectives.
Strategic Opportunities
- Indian research infrastructure buildout:Department of Biotechnology funding for national microscopy facilities is creating demand for Plan Apochromat objectives in Bangalore, Hyderabad, and Delhi institutional clusters.
- Embedded firmware convergence:Automated turret positioning systems integrating medical device software validation requirements are opening aftermarket retrofit revenue streams.
- Phase contrast retrofit kits:Academic laboratories facing grant-funded capital constraints are purchasing optical treatment attachments rather than complete objective replacements.
Industry Challenges
- Optomechanical assembly technician scarcity:Sub-micron lens centering and cementing skills require 4-7 year apprenticeship pipelines that German and Japanese training institutions struggle to fill.
- Legacy microscope turret compatibility:RMS thread standard variations across 20-year installed bases force manufacturers to maintain redundant mechanical interface tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biological Microscope Objectives Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plan Achromat, Plan Fluorite, Plan Apochromat, Achromat, Semi Plan Optical Coating: Anti-Reflection, Fluorite Coating, Sapphire Coating, Phase Contrast, Neutral Density Application: Pathology, Cytology, Microbiology, Molecular Biology, Cell Research End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Diagnostic Centers |
| Companies Covered | Olympus, Motic, Leica Microsystems, Newport, Thorlabs, Nikon, Meiji Techno, Mitutoyo, Carl Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biological Microscope Objectives Market Shifts & Advancements
Computational microscopy architectures are automating optical design workflows, compressing the iteration cycle between specification and prototype while embedding quality prediction algorithms directly into manufacturing execution systems.
Artificial intelligence-driven aberration correction is automating real-time wavefront optimization in high-throughput screening platforms. Pharmaceutical contract research organizations in Massachusetts and North Carolina are deploying these systems to reduce z-stack acquisition times by eliminating mechanical focus drift. The technology is automating the displacement of manual objective selection protocols in multi-modal imaging suites.
EU MDR Annex I general safety and performance requirements are mandating optical performance documentation traceable to ISO 17025-accredited laboratories. Diagnostic device manufacturers in Germany and the Netherlands are restructuring supplier qualification audits to capture refractive index homogeneity data across individual lens elements. Plan Apochromat objective categories face the steepest compliance burden due to multi-element complexity.
Academic procurement committees are unbundling after-sales service contracts from capital equipment purchases, favoring third-party maintenance providers over manufacturer-captive service networks. Major research universities in California, Massachusetts, and Texas are negotiating parts-availability guarantees independent of original equipment vendor relationships. This pattern is most visible in National Institutes of Health-funded institutions operating under fixed-cost grant structures.
Global Biological Microscope Objectives Market Segmentation
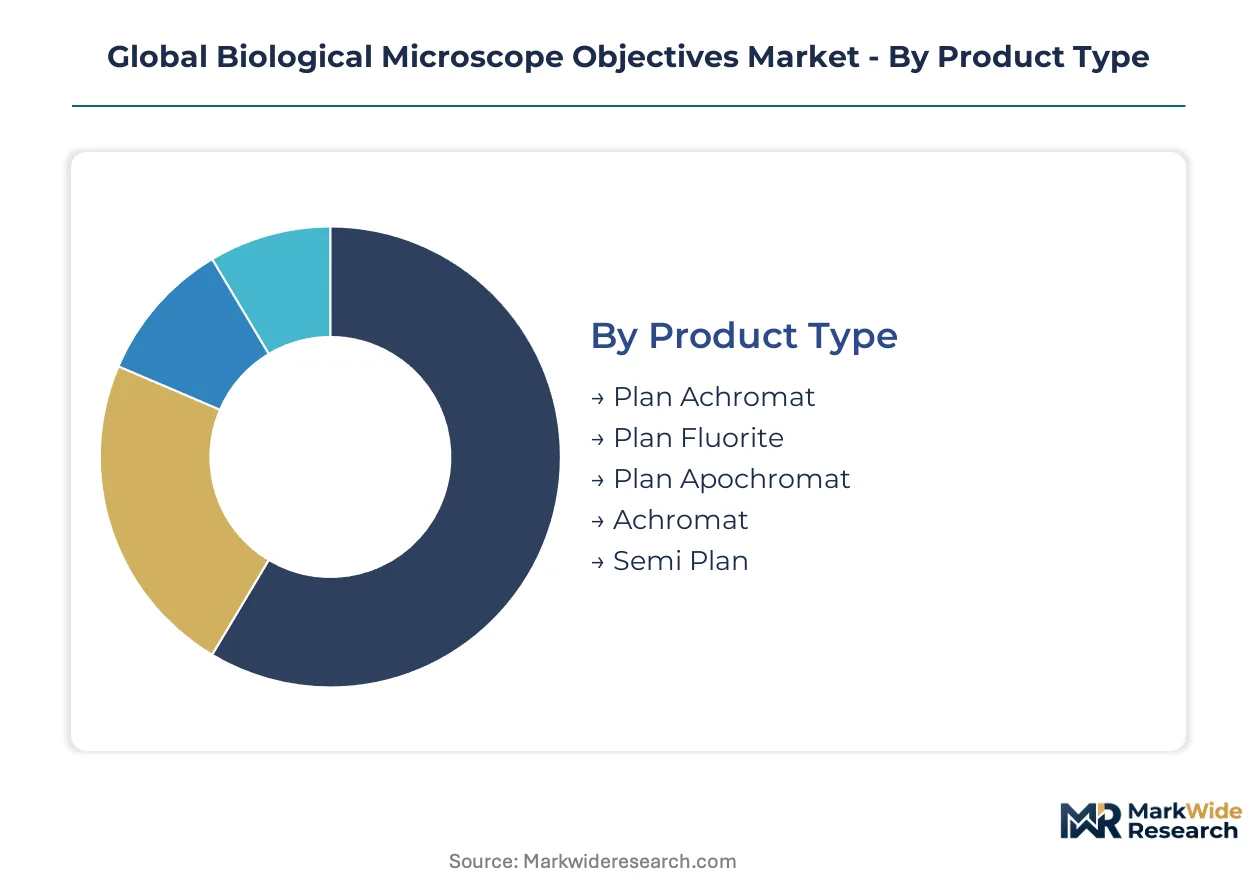
Biological microscope objectives segment across technical specifications, optical treatments, and institutional procurement patterns that determine margin structures and competitive positioning. Understanding these divisions reveals where capital concentrates and where aftermarket retrofit opportunities emerge.
Product Type:
Academic procurement committees weigh chromatic correction performance against grant-funded capital constraints when selecting objective categories.
- Plan Achromat:Corrects for field curvature and spherical aberration across two wavelengths, serving as the entry-level standard for undergraduate teaching laboratories in India and Brazil. Demand clusters in institutional clusters where equipment replacement cycles stretch to 7-10 years.
- Plan Fluorite:Delivers chromatic correction across three wavelengths using calcium fluoride elements, occupying the high-volume middle tier favored by National Institutes of Health-funded researchers balancing performance against fixed-cost grant structures. Working distance specifications typically extend 0.5-1.0mm beyond Plan Achromat equivalents.
- Plan Apochromat:Commands premium positioning through chromatic correction across four or more wavelengths with highest numerical aperture values. Carl Zeiss and Nikon anchor manufacturing in Germany and Japan.
- Achromat:Basic spherical and chromatic correction for entry-level educational microscopy. Schools in Southeast Asia and Latin America represent primary demand nodes.
- Semi Plan:Intermediate field flatness correction bridging Achromat and full Plan specifications. Budget-conscious pathology laboratories in Eastern Europe favor this category.
Plan Fluorite leads on scale; Plan Apochromat leads on momentum.
Optical Coating:
Aftermarket attachment rates vary by coating complexity and cleanroom reprocessing infrastructure availability.
- Anti-Reflection:Multi-layer dielectric stacks reduce surface reflections below 0.5% per interface through ion-beam sputtering deposition. Pharmaceutical high-throughput screening platforms in Massachusetts and North Carolina specify broadband AR treatments to maximize photon collection efficiency.
- Fluorite Coating:Protective layers for calcium fluoride elements vulnerable to humidity and thermal shock. German and Japanese manufacturers maintain captive coating facilities.
- Sapphire Coating:Extreme hardness surface treatments for objectives subject to repeated cleaning protocols in clinical diagnostic settings. EU MDR documentation requirements are accelerating adoption.
- Phase Contrast:Optical path difference treatments enabling unstained live cell observation. Academic retrofit kits represent margin-accretive revenue streams.
- Neutral Density:Attenuation coatings for fluorescence microscopy preventing photobleaching. Confocal imaging suites in Singapore and South Korea specify these treatments.
Anti-Reflection dominates volume; Phase Contrast retrofit demand is climbing the fastest.
Application:
Regulatory registration pathways shape objective specification requirements across diagnostic versus research use cases.
- Pathology:FDA 21 CFR Part 820 design controls govern objectives integrated into registered diagnostic devices. Netherlands and German device manufacturers demand ISO 17025-accredited optical performance documentation.
- Cytology:Pap smear and liquid-based cytology workflows require consistent color reproduction across batch-processed slides. Clinical laboratories in Texas and California specify Plan Fluorite minimums.
- Microbiology:Long working distance objectives for biosafety cabinet compatibility. BSL-3 facilities in Maryland and Georgia prioritize mechanical ruggedness.
- Molecular Biology:Fluorescence in situ hybridization and CRISPR imaging demand highest numerical aperture values. Research consortia in Cambridge, UK and Heidelberg, Germany anchor demand.
- Cell Research:Live-cell time-lapse microscopy requiring environmental chamber compatibility. Bangalore and Hyderabad institutional clusters in India are expanding procurement.
Pathology leads on scale; Cell Research is gaining share fastest.
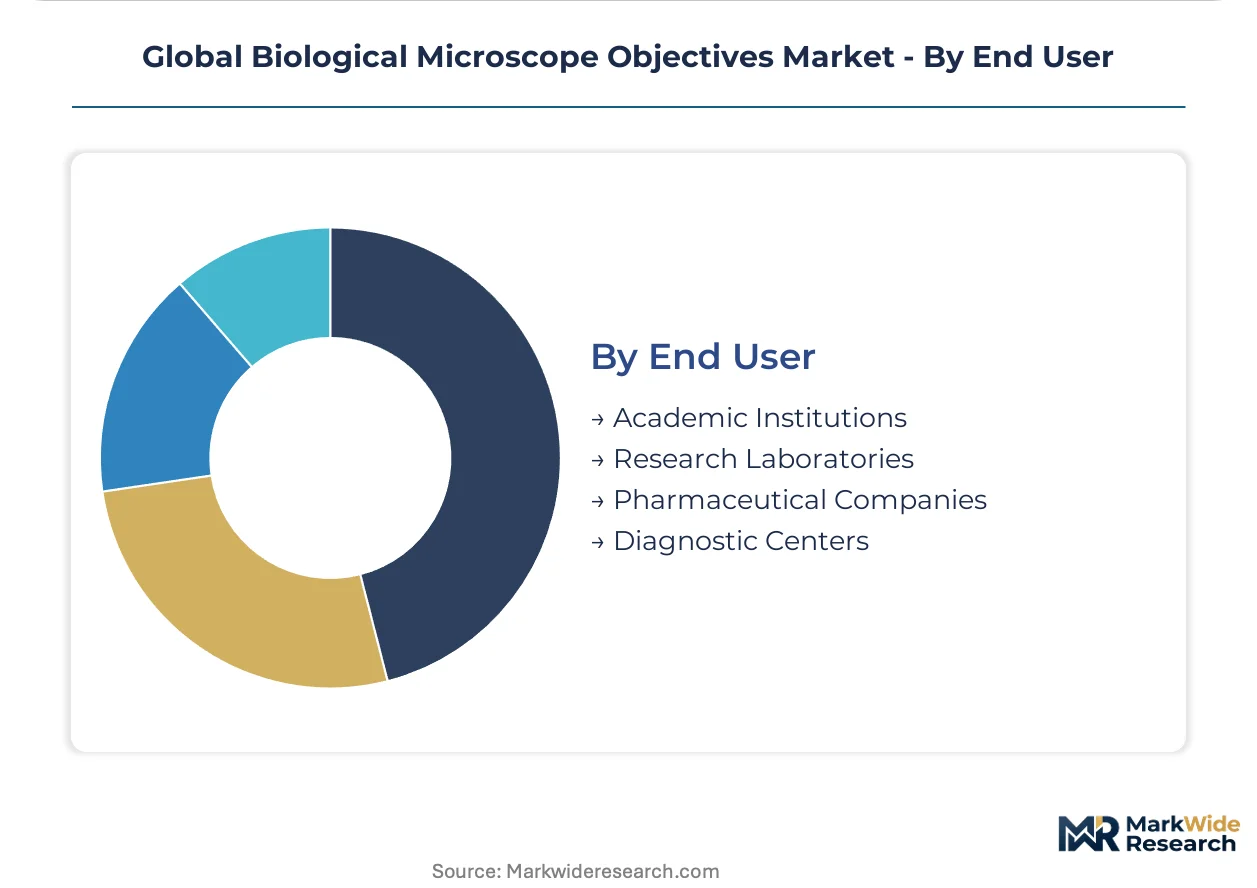
End User:
Procurement authority structures and funding mechanisms create distinct specification and pricing sensitivities.
- Academic Institutions:Grant-funded capital constraints favor Plan Fluorite middle tiers and third-party maintenance contracts. Major research universities in California, Massachusetts, and Texas negotiate parts-availability guarantees independent of manufacturer service networks.
- Research Laboratories:Core facility models concentrate high-end Plan Apochromat procurement with shared access charging mechanisms. Singapore and South Korea national research foundations drive specifications.
- Pharmaceutical Companies:Phenotypic screening pipelines are scaling high-numerical-aperture objective procurement. Contract research organizations in North Carolina deploy AI-driven aberration correction systems.
- Diagnostic Centers:EU MDR and FDA quality system requirements mandate traceable optical performance documentation. German and Dutch device manufacturers restructure supplier qualification audits.
Academic Institutions lead on scale; Pharmaceutical Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optomechanical assembly technicians cluster in Germany and Japan, where apprenticeship pipelines require 4-7 years to develop sub-micron lens centering competencies. These workforce concentrations anchor manufacturing gravity for high-numerical-aperture objectives serving pharmaceutical and diagnostic end users.
United States
Pharmaceutical contract research organizations in Massachusetts and North Carolina are scaling phenotypic screening pipelines with AI-driven aberration correction systems. FDA 21 CFR Part 820 quality system requirements shape design control documentation for diagnostic-registered objectives. Greater Boston and Research Triangle Park anchor demand clusters for Plan Apochromat procurement.
Germany
EU MDR Annex I general safety and performance requirements are mandating ISO 17025-accredited optical performance documentation traceable to individual lens elements. German device manufacturers in Jena and Oberkochen are restructuring supplier qualification audits to capture refractive index homogeneity data. Carl Zeiss anchors precision optics manufacturing with extreme ultraviolet-grade polishing competencies.
Japan
METI maintains JIS standards for optical performance testing that influence procurement specifications across Asia-Pacific research consortia. Nikon anchors position through proprietary immersion media chemistry extending working distance specifications. Tokyo and Osaka metropolitan areas concentrate optomechanical assembly expertise and captive glass formulation capabilities.
India
Department of Biotechnology funding for national microscopy facilities is creating demand for Plan Apochromat objectives in Bangalore, Hyderabad, and Delhi institutional clusters. The country's national pharmaceutical regulator aligns with ISO 10993 biocompatibility protocols for immersion oil contact surfaces. Indian research infrastructure buildout favors third-party maintenance contracts over manufacturer-captive service networks.
Singapore
National research foundations drive specifications for core facility models concentrating high-end Plan Apochromat procurement with shared access charging mechanisms. Confocal imaging suites specify neutral density attenuation coatings for fluorescence microscopy preventing photobleaching. Biopolis and one-north research clusters anchor demand for molecular biology and cell research applications.
Global Biological Microscope Objectives Market Competitive Landscape
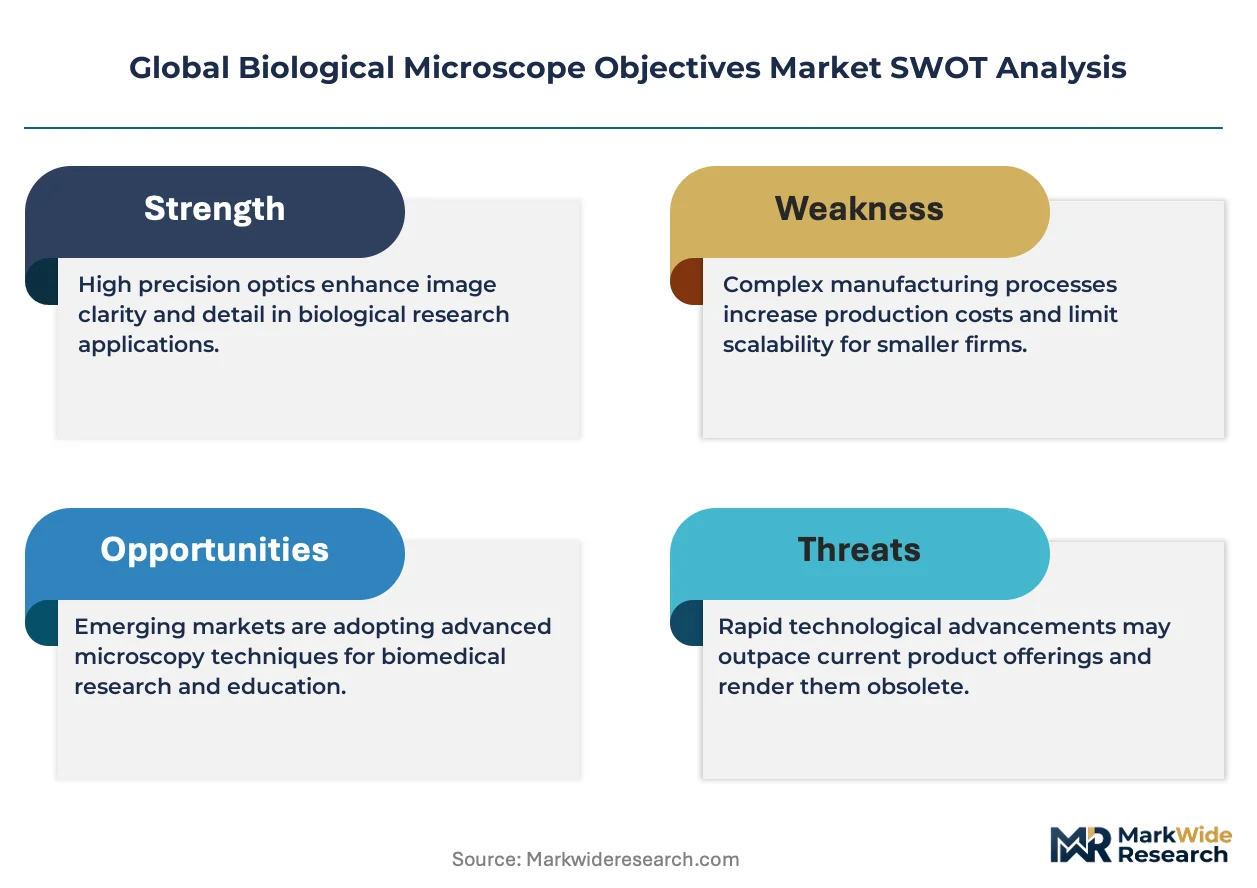
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where captive glass formulation capabilities determine margin sustainability under tightening traceability mandates. The vendor base separates into three strategic archetypes: vertically integrated precision optics manufacturers with semiconductor lithography spillover competencies, mid-tier academic-focused suppliers balancing performance against grant-funded capital constraints, and aftermarket retrofit specialists monetizing phase contrast optical treatments. Dominant competitive moves include M&A targeting ion-beam sputtering coating capabilities and strategic partnerships securing synthetic fluorite supply from German and Japanese chemical synthesis facilities.
Among Germany-based precision optics manufacturers, Carl Zeiss AG and Leica Microsystems GmbH exemplify vertically integrated archetypes with captive metrology and polishing competencies. Nikon Corporation represents Japanese specialists leveraging proprietary immersion media chemistry. Olympus Corporation occupies a diversified conglomerate position with vertically integrated glass formulation capabilities. These three anchors demonstrate how extreme ultraviolet-grade polishing competencies and proprietary chemistry sustain differentiation under EU MDR documentation compression.
| Leading Market Players |
|---|
| Olympus |
| Motic |
| Leica Microsystems |
| Newport |
| Thorlabs |
| Nikon |
| Meiji Techno |
| Mitutoyo |
| Carl Zeiss |
| Others |
Supply & Pricing Matrix
Sub-micron lens centering technicians concentrated in Germany and Japan command 4-7 year apprenticeship premiums that widen spreads between Plan Apochromat premium tiers and Plan Achromat economy positioning. Labor-cost differentials between Jena-Oberkochen and Bangalore-Hyderabad clusters translate into three-tier pricing structures that pharmaceutical buyers navigate against EU MDR compliance budgets.
Pricing Analysis
Bundled after-sales service contracts are unbundling across National Institutes of Health-funded institutions, with third-party maintenance providers capturing pricing power from manufacturer-captive networks. Price differentiation rests on ISO 17025 accreditation status and extreme ultraviolet-grade polishing certification tiers. Cost compression in Plan Fluorite mid-tiers is intensifying as Indian research infrastructure buildout favors third-party service guarantees. Academic procurement committees exhibit highest price sensitivity; diagnostic device manufacturers in Germany and the Netherlands show lowest sensitivity due to regulatory registration requirements.
Supply Chain Analysis
Single-source vulnerability sits with synthetic fluorite chemical synthesis facilities concentrated in Germany and Japan. High-grade calcium fluoride elements draw from three primary production sites, while ion-beam sputtering equipment for anti-reflection coatings sources from German and Japanese cleanroom infrastructure specialists. Tariff exposure runs through precision glass formulation inputs subject to export control classifications. Distribution runs through manufacturer-direct channels for diagnostic-registered objectives and academic distributor networks for research-tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in biological microscope objectives hinges on AI-driven aberration correction premiumization and computational microscopy workflow automation reducing field service intensity.
For Market Incumbents: Deepen captive metrology capabilities to capture refractive index homogeneity data demanded by EU MDR Annex I documentation mandates. Secure long-term synthetic fluorite supply agreements with German and Japanese chemical synthesis facilities before capacity constraints tighten. Threat from embedded firmware convergence in automated turret positioning systems demands software validation competency investments. For New Entrants and Emerging Players: Enter via phase contrast retrofit kit aftermarket channels serving grant-constrained academic laboratories in India and Brazil. White-space targets cluster in third-party maintenance contract aggregation for legacy microscope installed bases. Go-to-market angle centers on parts-availability guarantees independent of original equipment manufacturer relationships. For Investors and Strategic Acquirers: Diversified precision optics conglomerates are the most active acquirer in this space, targeting ion-beam sputtering coating capabilities and JIS-standard metrology competencies. Long-term viability frames around semiconductor lithography spillover sustaining sub-wavelength surface finish differentiation. Acquisition target archetype: mid-tier academic-focused suppliers with installed base retrofit potential. Signal to watch: convergence between medical device software validation requirements and automated turret positioning firmware.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fluorite | Captive supply of calcium fluoride elements insulates Plan Fluorite margins against German-Japanese synthesis facility bottlenecks. |
| ISO 17025 Metrology Laboratory Accreditation | Diagnostic device manufacturers in the Netherlands demand refractive index homogeneity traceability for EU MDR compliance. |
| AI-Driven Aberration Correction Platform Launch | Pharmaceutical CROs in Massachusetts and North Carolina specify real-time wavefront optimization for phenotypic screening throughput. |
| Phase Contrast Retrofit Kit Distribution | Academic laboratories in California, Massachusetts, and Texas unbundle capital purchases from aftermarket optical treatment attachments. |
| Embedded Firmware Validation Partnership | Automated turret positioning systems integrating medical device software requirements open diagnostic-registered revenue streams. |
Research Methodology
Coverage spans Germany, Japan, the United States, India, and Singapore, with primary inputs from each precision optics manufacturing cluster. The analysis combines structured interviews with optomechanical assembly technicians, biomedical engineers at diagnostic device manufacturers, academic procurement committee members, and pharmaceutical high-throughput screening platform operators. Secondary validation draws from FDA 21 CFR Part 820 guidance documents, METI JIS optical performance standards, EU MDR Annex I technical documentation requirements, and ISO 10993 biocompatibility testing protocols. Bottom-up demand modeling from institutional procurement patterns triangulates against top-down supply capacity assessments from glass formulation and coating equipment manufacturers.
Granularity-level modeling disaggregates volume and value outputs across product type, optical coating, application, and end user dimensions throughout the forecast period. Plan Apochromat, Plan Fluorite, and Plan Achromat tiers are modeled separately with numerical aperture and working distance specifications. End-user segmentation distinguishes pharmaceutical phenotypic screening pipelines from academic grant-funded capital constraints. CAGRs derive from iterative reconciliation between historical replacement cycle data and projected buildout of national microscopy facilities in India and Singapore. Industry-specific inputs include synthetic fluorite synthesis capacity utilization and ion-beam sputtering equipment lead time dynamics.
Inputs from optomechanical assembly apprenticeship programs and EU MDR notified body documentation were available through the study window; gaps in real-time pharmaceutical CRO capital expenditure disclosures introduce uncertainty bands around high-numerical-aperture demand trajectories. Forecasts reflect assumptions regarding semiconductor lithography spillover sustainability and METI JIS standard adoption across Asia-Pacific research consortia. Specific risk factors that could revise projections include fluorite crystal supply disruption, cleanroom infrastructure expansion delays, and diagnostic device software validation requirement acceleration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market