
 Middle East and Africa Thermal Cyclers Market | 2026-2036
Middle East and Africa Thermal Cyclers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Thermal Cyclers Market Foresight
South Africa's biomanufacturing corridor is tilting toward molecular diagnostics capacity as public health infrastructure expands. Thermo Fisher Scientific leverages its Cape Town distribution hub to sustain reagent supply chains across sub-Saharan Africa. Bio-Rad Laboratories anchors its regional presence through localized technical service networks. QIAGEN competes with integrated sample-to-insight workflows that reduce laboratory turnaround times.
Thermal cyclers are precision instruments that automate temperature cycling to amplify DNA or RNA segments through polymerase chain reaction, typically operating across 4–96 wells with ramp rates between 1–6°C per second and thermal uniformity within ±0.5°C. Their primary purpose is to enable nucleic acid quantification and genotyping for clinical diagnostics, research, and forensic identification. Real-time PCR systems command premium positioning due to closed-tube quantification and reduced contamination risk, while portable thermal cyclers represent the fastest-growing configuration as point-of-care molecular testing expands beyond centralized laboratories. Gradient thermal cyclers serve method development applications where optimization protocols justify higher per-unit margins.
SFDA in Saudi Arabia and MOHAP in the UAE enforce in-vitro diagnostics registration requirements that shape product entry timelines and clinical validation standards across Gulf Cooperation Council markets. South Africa's Health Products Regulatory Authority applies ISO 13485-aligned quality system inspections that filter out uncertified manufacturers. Stakeholders must monitor harmonization progress between national medical device regulators and the African Medicines Agency's emerging centralized framework.
Market Dynamics
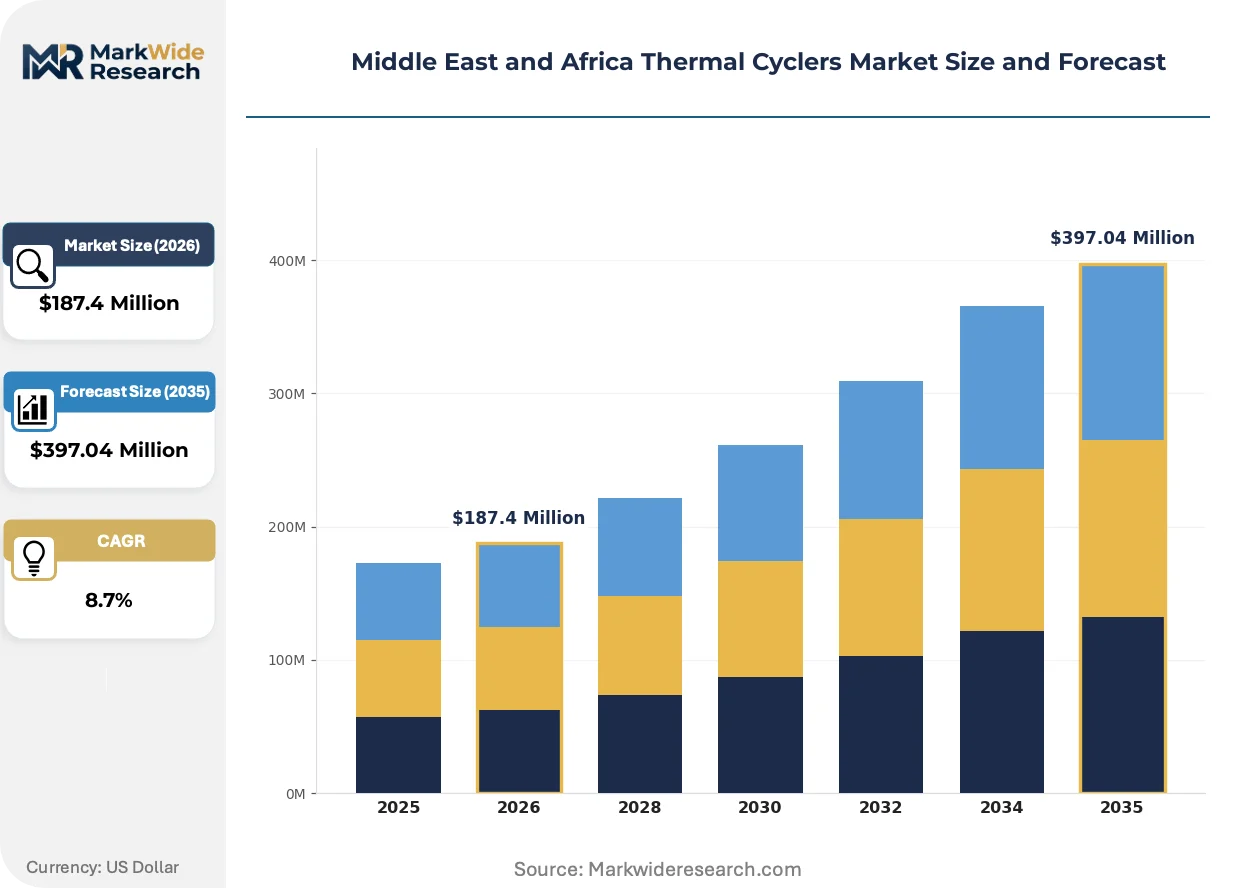
Saudi Arabia's healthcare modernization programs and South Africa's national health laboratory network expansion are concentrating thermal cycler procurement into centralized tenders that favor integrated sample-to-insight workflows over standalone instruments.
Growth Catalysts
- SFDA Registration Pathways:Saudi Arabia's streamlined in-vitro diagnostics approvals are compressing device entry timelines for PCR-based infectious disease testing platforms across Gulf Cooperation Council markets.
- Point-of-Care Molecular Testing:Portable thermal cycler configurations are displacing centralized laboratory workflows as diagnostic capacity extends beyond urban hospital networks into regional clinics.
- South Africa's Biomanufacturing Corridor:Public health infrastructure expansion is tilting procurement toward molecular diagnostics capacity within the national health laboratory network.
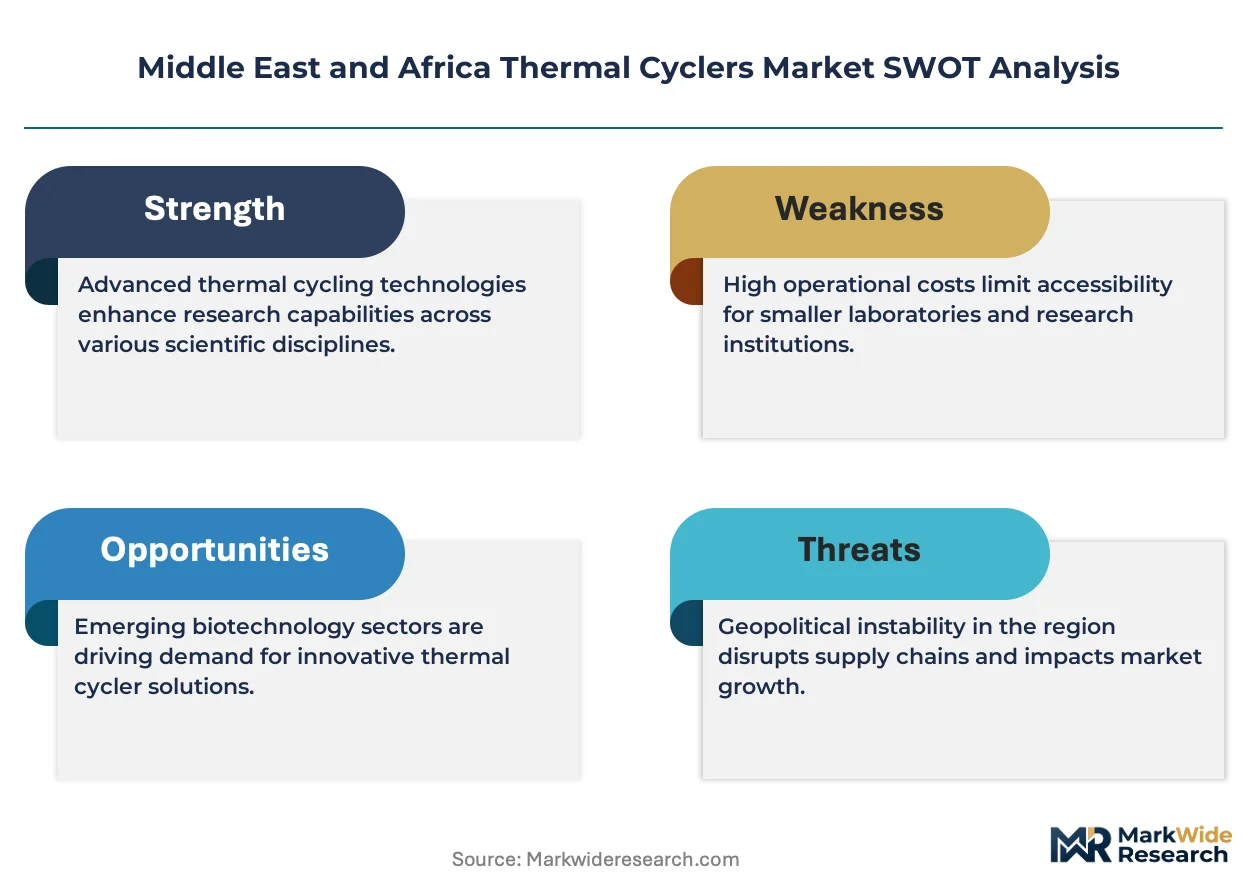
Market Restraints
- Import Dependency:Reagent supply chains for real-time PCR systems concentrate through Cape Town distribution hubs, exposing sub-Saharan African markets to logistics bottlenecks and currency volatility.
- ISO 13485 Certification Barriers:South Africa's Health Products Regulatory Authority applies quality system inspections that filter out uncertified manufacturers, limiting vendor pool depth.
- Gradient Thermal Cycler Substitution:Method development applications face displacement from cloud-based protocol libraries that reduce optimization cycle requirements.
Strategic Opportunities
- MOHAP Harmonization:UAE regulatory alignment with Saudi SFDA standards is creating cross-border tender eligibility for devices validated across multiple Gulf state health systems.
- African Medicines Agency Framework:Emerging centralized regulatory harmonization is opening pathway consolidation opportunities for manufacturers navigating fragmented national approval processes.
- Closed-Tube Quantification Convergence:Integration of real-time fluorescence detection with portable form factors is enabling field-deployable infectious disease surveillance outside laboratory infrastructure.
Industry Challenges
- Technical Service Network Density:Localized maintenance capability for precision thermal uniformity calibration remains sparse outside Johannesburg, Riyadh, and Dubai metropolitan clusters.
- Legacy LIS Integration:Laboratory information system compatibility gaps between new thermal cycler data outputs and existing South African public health network infrastructure are extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Thermal Cyclers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Thermal Cyclers, Real-Time PCR, Gradient Thermal Cyclers, Portable Thermal Cyclers End User: Research Laboratories, Diagnostic Laboratories, Academic Institutions, Pharmaceutical Companies Technology: Polymerase Chain Reaction, Isothermal Amplification, Digital PCR, Multiplex PCR Application: Genetic Research, Clinical Diagnostics, Environmental Testing, Forensic Analysis |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, QIAGEN, Agilent Technologies, Roche Diagnostics, Eppendorf, Analytik Jena, Takara Bio, Merck KGaA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Thermal Cyclers Market Shifts & Advancements
Digital connectivity and regulatory harmonization are compressing the traditional separation between instrument procurement and consumable lock-in, reshaping how thermal cycler vendors structure regional market entry.
Cloud-enabled thermal cycler management platforms are digitizing protocol sharing, remote diagnostics, and compliance documentation for distributed laboratory networks. Diagnostic laboratory chains across Saudi Arabia are adopting these systems to coordinate multi-site assay standardization. This architecture is digitizing vendor-customer relationships from transactional equipment sales toward continuous subscription revenue models.
SFDA and MOHAP are converging in-vitro diagnostics registration requirements toward mutual recognition principles that reduce redundant clinical validation studies. Gulf state health procurement authorities are consolidating tender specifications around these harmonized standards. Multi-national diagnostic chains with presence across Saudi Arabia, UAE, and Kuwait are restructuring regulatory affairs teams to exploit this alignment.
Centralized tendering by national health laboratory networks is compressing vendor negotiation cycles and unbundling after-sales service contracts from equipment pricing. South Africa's public health procurement is separating maintenance obligations into multi-year performance agreements. This pattern concentrates buying power within ministry-level procurement offices while fragmenting service provider relationships.
Middle East and Africa Thermal Cyclers Market Segmentation
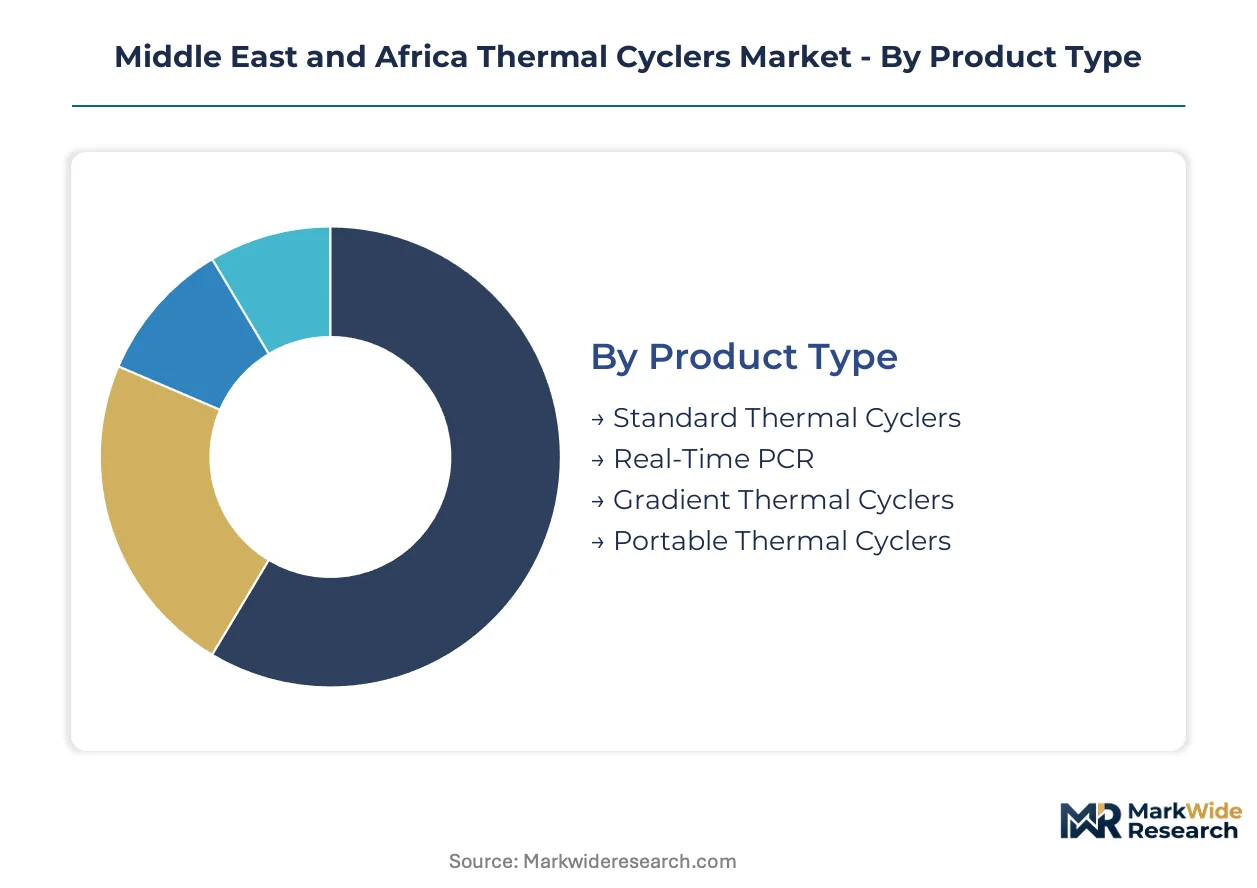
Thermal cycler procurement patterns across the Middle East and Africa diverge sharply by institutional setting and technical sophistication. Public health infrastructure investments favor integrated real-time systems, while research expansion drives demand for specialized gradient and portable configurations.
Product Type:
Cost tier positioning determines procurement authority and vendor negotiation leverage across institutional buyers.
- Standard Thermal Cyclers:These 4–96 well instruments operate at fixed temperatures with ramp rates of 1–4°C per second. Diagnostic laboratories across Saudi Arabia's healthcare modernization programs procure these for high-volume infectious disease screening where protocol standardization outweighs optimization flexibility.
- Real-Time PCR:Integrated fluorescence detection enables closed-tube quantification with thermal uniformity within ±0.5°C. South Africa's national health laboratory network concentrates procurement here for HIV viral load monitoring and tuberculosis drug resistance profiling, prioritizing contamination control over capital cost.
- Gradient Thermal Cyclers:Simultaneous multi-temperature zones support method development applications. Academic institutions in the UAE deploy these for protocol optimization before assay transfer to clinical settings.
- Portable Thermal Cyclers:Battery-powered units weighing under 5kg enable field-deployable molecular testing. Regional clinic networks in Kenya and Nigeria are adopting these for point-of-care infectious disease surveillance beyond centralized laboratory infrastructure.
Real-time PCR commands the established base across Gulf state health systems. The steepest expansion runs through portable configurations as diagnostic capacity extends into sub-Saharan African primary care settings.
End User:
Application maturity shapes purchasing sophistication and service contract expectations among institutional buyers.
- Diagnostic Laboratories:High-throughput facilities process thousands of samples daily with ISO 15189 quality requirements. South Africa's expanding public health laboratory network drives tender consolidation toward integrated sample-to-insight workflows.
- Research Laboratories:Method development focus demands gradient-capable systems with flexible protocol editing. Biotechnology clusters in Cape Town and Riyadh prioritize vendor technical service density over equipment pricing.
- Academic Institutions:Teaching and basic research applications favor entry-level standard thermal cyclers. Universities across Egypt and Morocco face budget constraints that extend replacement cycles beyond optimal calibration intervals.
- Pharmaceutical Companies:GMP-compliant manufacturing operations require validated thermal cyclers with full audit trails. Contract research organizations in Jordan and Tunisia serve European and Gulf state sponsor requirements.
Diagnostic laboratories anchor procurement volume through centralized ministry tenders. Academic institutions present the most price-sensitive demand profile with extended decision timelines.
Technology:
Workflow integration requirements differentiate adoption trajectories across laboratory infrastructure maturity levels.
- Polymerase Chain Reaction:Temperature cycling between denaturation, annealing, and extension temperatures remains the dominant amplification methodology. Standard and real-time thermal cycler configurations both implement this core chemistry.
- Isothermal Amplification:Single-temperature operation eliminates thermal cycling hardware complexity. Point-of-care diagnostic developers in Nigeria and Ghana favor this approach for battery-powered instrument miniaturization.
- Digital PCR:Absolute quantification through sample partitioning delivers precision for rare mutation detection. Oncology research centers in Israel and South Africa deploy these systems for liquid biopsy assay development.
- Multiplex PCR:Simultaneous amplification of multiple targets reduces reagent consumption per sample. Public health surveillance programs across the Gulf Cooperation Council adopt these panels for respiratory pathogen screening.
Conventional polymerase chain reaction retains the installed base advantage. Digital PCR is climbing the fastest among technology categories as precision oncology investment expands across the region.
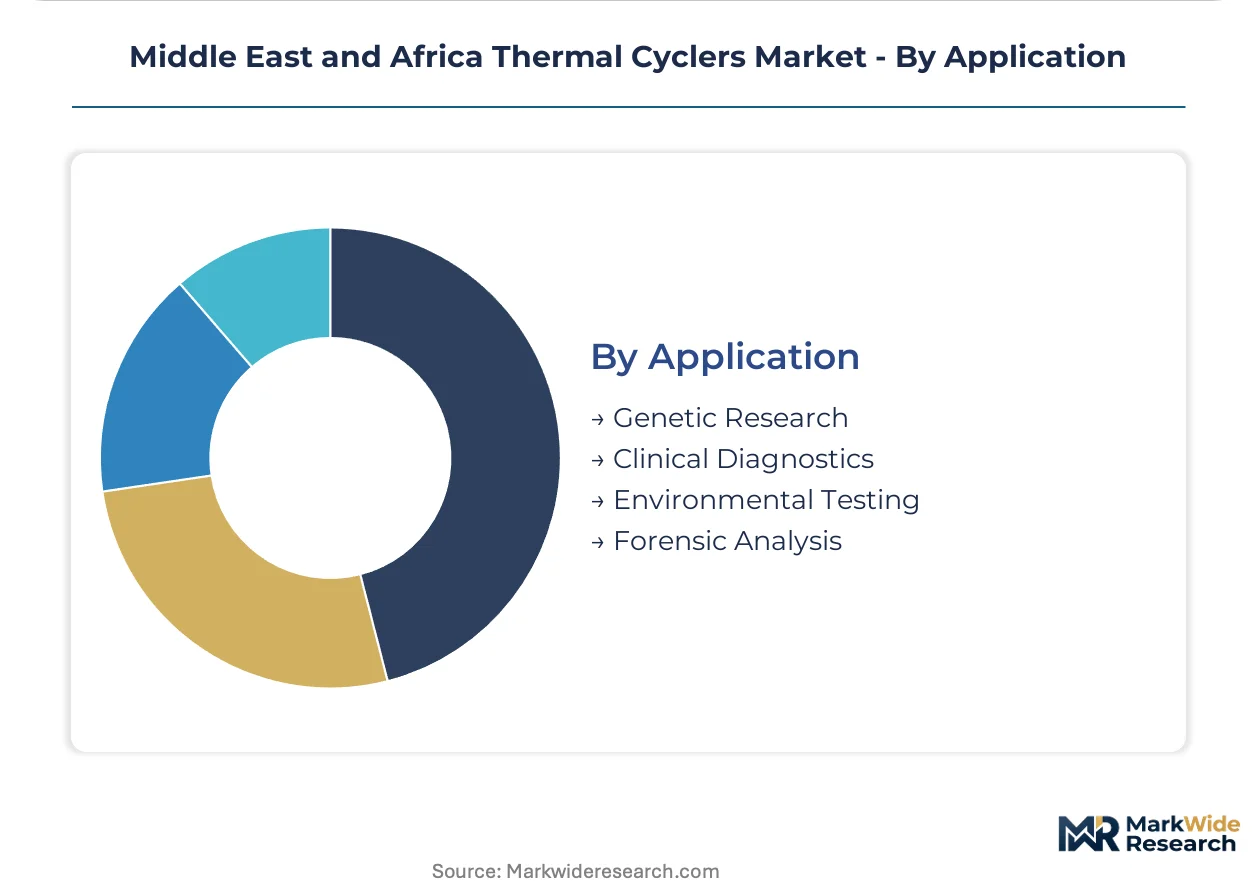
Application:
Regulatory validation burden and reimbursement pathway clarity shape commercial prioritization across use cases.
- Clinical Diagnostics:SFDA and MOHAP registration requirements enforce analytical validation standards for infectious disease testing. Saudi Arabia's centralized procurement favors vendors with established regulatory affairs capabilities across multiple Gulf states.
- Genetic Research:Population genomics initiatives and agricultural biotechnology drive demand for high-throughput sequencing support. Research councils in Qatar and the UAE fund large-scale cohort studies requiring thermal cycler capacity expansion.
- Environmental Testing:Water quality monitoring and food safety applications require portable field-deployable systems. South African municipalities are piloting PCR-based pathogen detection for recreational water surveillance.
- Forensic Analysis:DNA profiling for criminal casework and disaster victim identification demands validated protocols with chain-of-custody documentation. National forensic laboratories in Egypt and Algeria maintain dedicated thermal cycler inventories.
Clinical diagnostics dominates procurement value through regulated testing volumes. Environmental testing is gaining share fastest as water security concerns intensify across water-stressed geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration pathways in Saudi Arabia anchor procurement concentration across Gulf Cooperation Council markets. National health laboratory networks in South Africa and Nigeria drive sub-Saharan demand fragmentation.
Saudi Arabia
Healthcare modernization programs and centralized ministry tenders concentrate real-time PCR procurement. SFDA streamlined in-vitro diagnostics approvals compress device entry timelines for infectious disease testing platforms. Riyadh's King Faisal Specialist Hospital anchors regional reference laboratory capacity expansion.
United Arab Emirates
MOHAP regulatory harmonization with Saudi standards creates cross-border tender eligibility. Dubai's healthcare free zones attract diagnostic chains serving multi-Gulf state operations. The emirate's laboratory networks deploy cloud-enabled thermal cycler management for multi-site assay standardization.
South Africa
National health laboratory network expansion tilts procurement toward integrated sample-to-insight workflows. Health Products Regulatory Authority ISO 13485-aligned inspections filter uncertified manufacturers from vendor pools. Cape Town's biomanufacturing corridor sustains reagent supply chains across sub-Saharan Africa.
Nigeria
Point-of-care molecular testing adoption extends diagnostic capacity beyond urban hospital networks. The country's national pharmaceutical regulator enforces analytical validation standards for field-deployable systems. Lagos and Abuja metropolitan clusters concentrate technical service capability for portable thermal cycler calibration.
Egypt
Academic research expansion and forensic laboratory modernization drive gradient thermal cycler demand. National medical device registration requirements shape product entry timelines for clinical diagnostics. Cairo's universities face budget constraints that extend standard thermal cycler replacement cycles.
Middle East and Africa Thermal Cyclers Market Competitive Landscape
Integrated workflow providers and precision instrument specialists split the market along the fault line between bundled sample-to-insight systems and standalone thermal cycler configurations. Consolidation pressure concentrates within Gulf state ministry tenders that favor vendors with established regulatory affairs capabilities across multiple jurisdictions. Three archetypes dominate: multinational life science conglomerates with reagent lock-in strategies, precision thermal engineering specialists, and point-of-care diagnostic developers. Dominant competitive moves include strategic partnerships for localized technical service density and portfolio diversification into cloud-enabled instrument management platforms.
Among US-based life science conglomerates, Thermo Fisher Scientific and Bio-Rad Laboratories exemplify the integrated workflow archetype, with the former representing reagent supply chain anchoring through regional distribution infrastructure and the latter occupying a position emphasizing localized technical service networks. QIAGEN, a Netherlands-based precision diagnostics specialist, sits within the sample-to-insight tier, exemplifying workflow integration strategies that reduce laboratory turnaround times. These three anchors illustrate the competitive spectrum from capital equipment sales toward continuous consumable revenue models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| QIAGEN |
| Agilent Technologies |
| Roche Diagnostics |
| Eppendorf |
| Analytik Jena |
| Takara Bio |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
German and Japanese precision thermal component suppliers anchor upstream manufacturing, concentrating margin capture in Peltier element and optical detection module tiers while downstream pricing power fragments across Gulf state ministry tenders and South African public health procurement offices.
Pricing Analysis
Real-time PCR systems in Dubai and Riyadh command 40-60% premiums over identical configurations in Lagos or Nairobi due to SFDA-MOHAP registration costs and localized technical service bundling. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified vendors with Gulf state regulatory approvals from uncertified manufacturers filtered by South Africa's Health Products Regulatory Authority. Cost compression in portable thermal cycler tiers is intensifying because battery-powered miniaturization is drawing new entrants from Asian diagnostic developers. Academic institutions across Egypt and Morocco present the most price-sensitive demand profile, while Saudi Arabia's centralized ministry tenders show the least sensitivity due to performance-based contracting separation.
Supply Chain Analysis
Export control regimes limiting fluorescence detection and precision thermal control technologies constrain component flows from US and EU suppliers to Middle East and African assemblers. Manufacturing concentrates in Germany, Japan, and the United States for Peltier elements, optical filters, and thermal sensors. Assembly draws from Chinese and Malaysian contract manufacturers for chassis and electronic subassemblies. Single-source vulnerability runs through Cape Town distribution hubs for reagent supply chains serving sub-Saharan Africa. Distribution runs through Johannesburg, Riyadh, and Dubai metropolitan clusters for technical service and calibration capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-enabled thermal cycler management platforms represent a service-attach opportunity expanding faster than hardware sales as diagnostic laboratory chains across Saudi Arabia adopt subscription-based protocol sharing and remote diagnostics.
For Market Incumbents: Harden regulatory affairs capabilities across multiple Gulf state jurisdictions to defend position in consolidated ministry tenders that favor cross-border SFDA-MOHAP harmonization. Deepen technical service network density in Johannesburg, Riyadh, and Dubai metropolitan clusters to offset unbundling of after-sales contracts from equipment pricing. Vertical integration into reagent supply chains through Cape Town distribution infrastructure reduces exposure to logistics bottlenecks and currency volatility in sub-Saharan markets. For New Entrants and Emerging Players: Build out point-of-care molecular testing capabilities for regional clinic networks in Kenya and Nigeria where portable thermal cycler adoption is accelerating fastest. Target academic institutions in Egypt and Morocco with entry-level standard thermal cyclers facing budget-constrained replacement cycles. Pursue ISO 13485 certification early to clear South Africa's Health Products Regulatory Authority quality system inspections and access national health laboratory network tenders. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision instrument specialists holding regional technical service networks but lacking reagent lock-in revenue streams. The market supports long-term viability for workflow-integrated providers as laboratory automation trends persist. Watch for African Medicines Agency framework harmonization progress as an inflection signal for regulatory pathway consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Enabled Platform Integration | Saudi diagnostic chains adopt subscription-based protocol sharing for multi-site standardization. |
| SFDA-MOHAP Regulatory Harmonization | Cross-border tender eligibility expands for devices validated across Gulf state health systems. |
| Technical Service Network Expansion | Calibration capability gaps outside Johannesburg, Riyadh, and Dubai extend deployment timelines. |
| Reagent Supply Chain Anchoring | Cape Town distribution hub concentration exposes sub-Saharan markets to logistics volatility. |
| Portable Configuration Development | Battery-powered units enable field-deployable infectious disease surveillance beyond laboratory infrastructure. |
Research Methodology
Operator-level perspectives from laboratory directors, biomedical engineers, regulatory affairs specialists at in-vitro diagnostics manufacturers, and Gulf state health procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from SFDA registration databases, MOHAP medical device listings, South African Health Products Regulatory Authority inspection records, and ISO 13485 certification registries. Bottom-up thermal cycler shipment analysis triangulated against top-down healthcare infrastructure investment flows across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type, end user, technology, and application segmentation dimensions alongside regional regulatory cluster variations. CAGRs derived from instrument replacement cycle analysis, laboratory expansion pipeline tracking, and infectious disease testing volume trends. Forecast inputs incorporated point-of-care molecular testing adoption curves and cloud-enabled platform penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian diagnostic developers with isothermal amplification platforms would shift outcomes. Material shifts in African Medicines Agency framework implementation or Gulf state regulatory divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Medical Oxygen Cylinders Market