
 Medical Ultrasonic Cleaners Market | 2026-2036
Medical Ultrasonic Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Ultrasonic Cleaners Market Intelligence
The expansion into veterinary clinics for surgical instrument cleaning is broadening the market beyond its core hospital and dental segments. Elma Schmidbauer GmbH leverages its specialization in high-frequency units to serve both medical and specialized laboratory end-users. Emerson Electric Co. competes through its extensive distribution network and brand recognition in industrial-grade ultrasonic components. SharperTek differentiates with its range of portable and tabletop cleaners, targeting smaller clinics and private practices.
Medical ultrasonic cleaners use high-frequency sound waves to create cavitation, a physical process that dislodges contaminants from instruments. This function is essential for pre-cleaning complex surgical tools before final sterilization, mitigating infection risk. By product type, tabletop cleaners are dominant in volume for settings like dental clinics, whereas industrial cleaners are prevalent in hospitals. Digital ultrasonic technology offers superior process control and is displacing older analog systems.
Regulatory frameworks such as the US FDA's guidance on reprocessing and the EU's Medical Device Regulation (MDR) dictate stringent cleaning validation requirements. In parallel, manufacturers must adhere to quality management standards like ISO 13485 for market access in most regions. Forward-looking success will depend on a vendor's ability to provide robust documentation proving cleaning efficacy for new, complex surgical instruments.
Market Dynamics
The central tension shaping the medical ultrasonic cleaner market is the growing complexity of surgical instruments clashing with zero-tolerance policies for hospital-acquired infections. This dynamic forces healthcare facilities to adopt advanced, verifiable cleaning technologies that can meet stringent regulatory documentation requirements.
Growth Catalysts
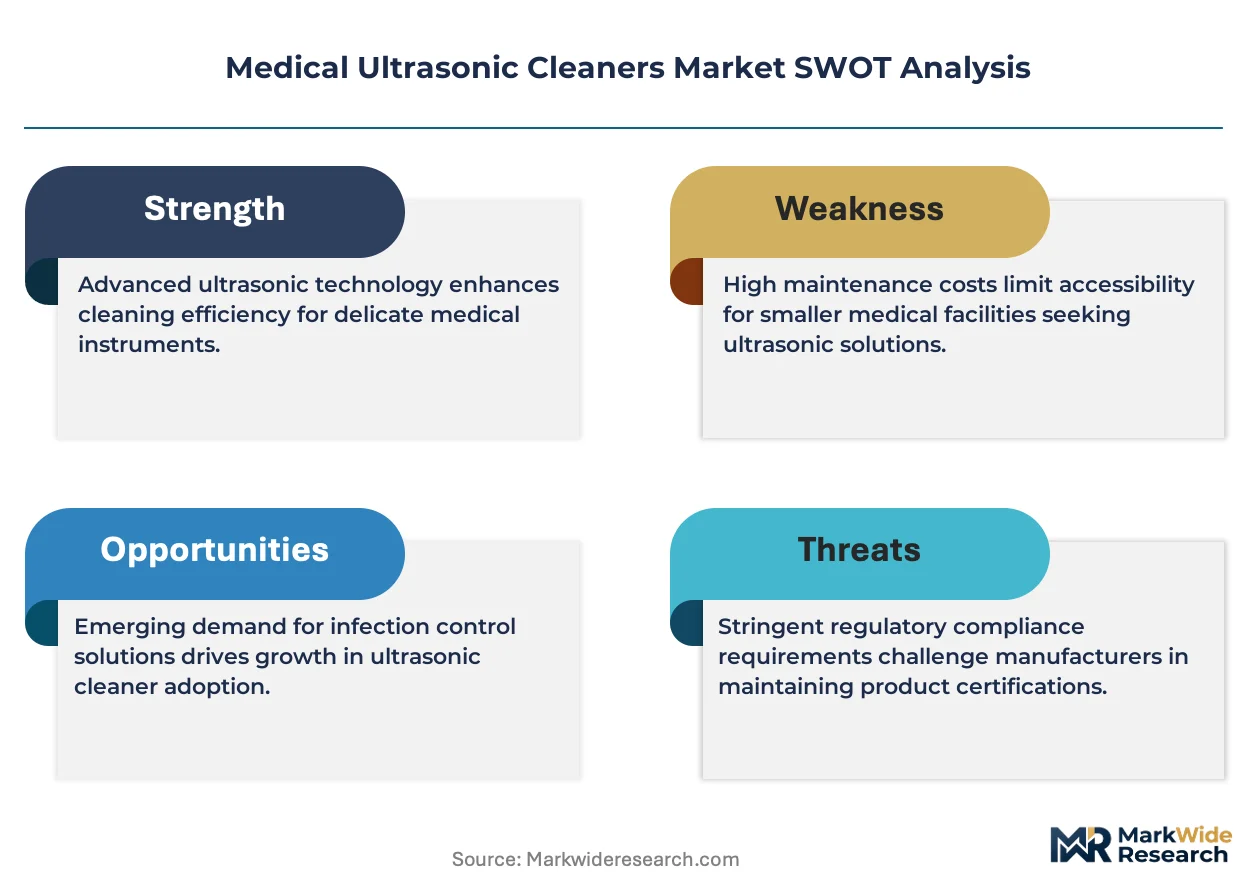
- Regulatory Mandates:Stricter reprocessing standards, such as the EU's Medical Device Regulation (MDR), compel healthcare providers to invest in ultrasonic cleaners that offer validated and documented cleaning cycles for compliance.
- Ambulatory Surgery Center Expansion:The proliferation of ambulatory surgery centers (ASCs) creates demand for compact, efficient tabletop ultrasonic cleaners capable of rapid instrument turnaround in outpatient settings.
- Healthcare Modernization:Government-led healthcare infrastructure investments in Southeast Asian nations are upgrading hospital sterilization departments, driving first-time adoption of modern ultrasonic cleaning systems over manual methods.
Market Restraints
- High Capital Cost:The significant initial investment required for advanced digital ultrasonic cleaners with data logging capabilities can be a barrier for smaller dental clinics, private practices, and facilities in emerging economies.
- Technical Validation Hurdles:Validating cleaning effectiveness for new generations of complex, cannulated, or robotic surgical instruments is difficult and time-consuming, which can slow the adoption of both the instruments and the cleaners.
- Threat of Substitution:For non-critical and semi-critical instruments, some facilities opt for lower-cost alternatives like automated washer-disinfectors or enhanced manual cleaning protocols, limiting the addressable market for ultrasonic technology.
Strategic Opportunities
- Veterinary Medicine Penetration:Specialized veterinary hospitals and surgical centers represent an underpenetrated segment, offering an opportunity to adapt medical-grade cleaners for the sterilization of veterinary surgical tools.
- IoT and Data Integration:Developing cleaners with integrated IoT connectivity for remote monitoring, predictive maintenance, and automatic logging of cleaning cycles can meet hospital demand for enhanced traceability and workflow automation.
- Targeted Geographic Expansion:Modernization programs in Latin American healthcare systems, particularly in Brazil and Mexico, present new growth avenues for vendors offering compliant and cost-effective cleaning solutions.
Industry Challenges
- Complex Validation Requirements:Manufacturers face lengthy and expensive processes to provide efficacy data for their cleaners against a constantly expanding list of complex surgical instruments, creating a significant compliance burden.
- End-User Training Deficits:Inadequate training of hospital sterile processing staff on proper loading techniques, cycle selection, and maintenance can lead to suboptimal cleaning performance and damage to the ultrasonic units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Ultrasonic Cleaners Market |
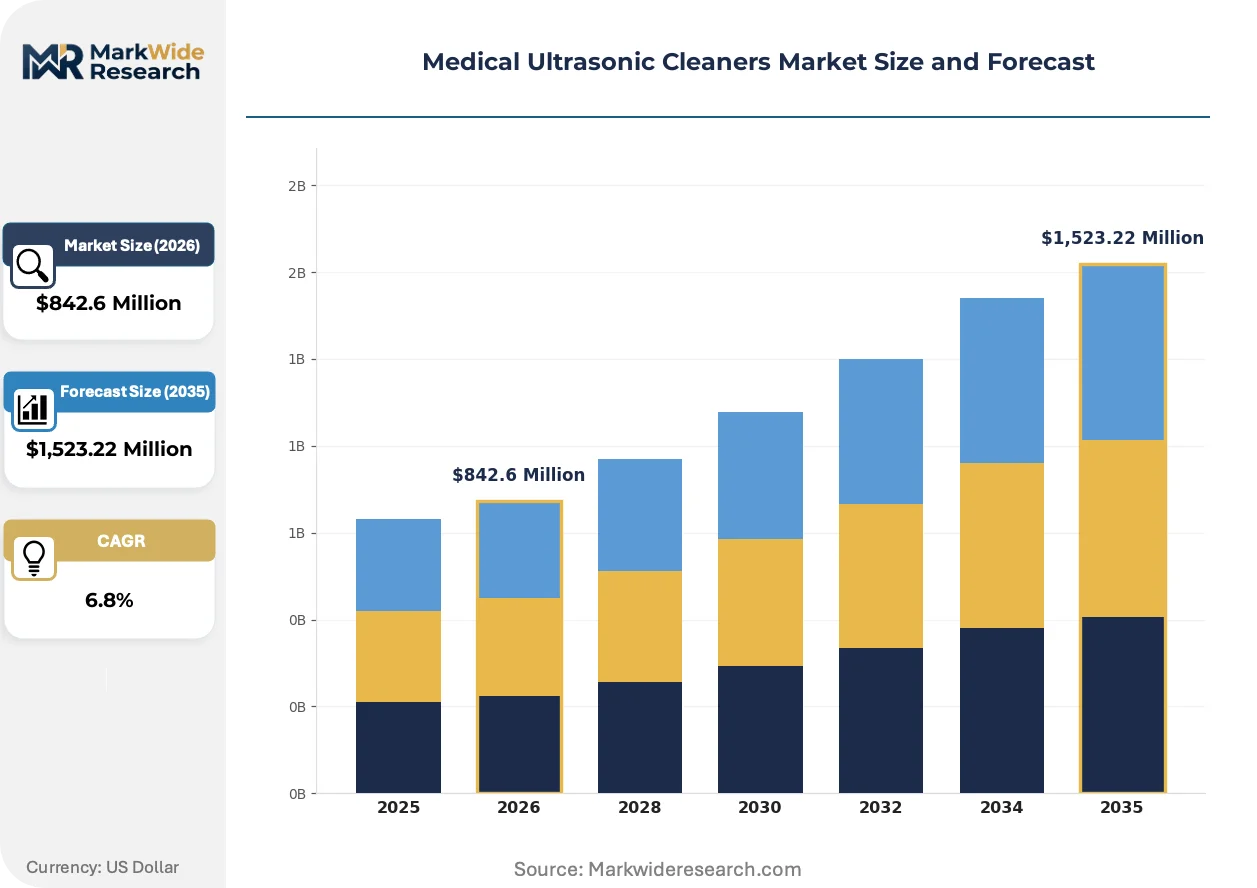
| Market Size in 2026 | $842.6 Million |
| Market Size in 2035 | $1,523.22 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Cleaners, Industrial Cleaners, Portable Cleaners, Customized Cleaners Technology: Ultrasonic Cavitation, High-Frequency Ultrasonic, Digital Ultrasonic, Analog Ultrasonic End User: Hospitals, Dental Clinics, Laboratories, Veterinary Clinics Application: Instrument Cleaning, Jewelry Cleaning, Parts Cleaning, Surgical Cleaning |
| Companies Covered | Emerson Electric Co., Crest Ultrasonics Corporation, Mettler Electronics Corp., SharperTek, Elma Schmidbauer GmbH, L&R Manufacturing, Steelco S.p.A., Tangshan UMG Medical Instrument Co., Ltd., Blue Wave Ultrasonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Ultrasonic Cleaners Market Strategic Shifts & Innovations
A fundamental shift toward automated, data-driven cleaning assurance is defining the market's evolution. This move prioritizes verifiable decontamination over simple cleaning, embedding ultrasonic systems deeper into the hospital's risk management and quality control framework.
Adaptive frequency sweeping technology is a key product evolution. These systems automatically adjust ultrasonic frequencies in real-time to match the size, mass, and complexity of the instrument load. Central sterile services departments (CSSDs) in major hospitals are the primary adopters, seeking to improve consistency. This intelligent technology is unifying the cleaning process for diverse instruments, from delicate ophthalmology tools to heavy orthopedic implants, within a single validated cycle.
Regulatory frameworks increasingly demand empirical proof of cleaning efficacy. The US FDA's guidance on the reprocessing of reusable medical devices pressures instrument makers to provide specific, validated cleaning instructions. This forces ultrasonic cleaner manufacturers to demonstrate their equipment can meet these precise protocols for instruments like complex endoscopes. The orthopedic and neurosurgery segments are most affected, fostering closer collaboration between instrument and cleaner vendors to achieve co-validated solutions.
Customer procurement behavior is evolving beyond simple equipment acquisition toward total lifecycle management. Hospital networks and group purchasing organizations are increasingly bundling the purchase of ultrasonic cleaners with multi-year service contracts that include installation qualification, operational qualification, and performance qualification (IQ/OQ/PQ) services. This disrupts the traditional capital sales model, favoring vendors with strong service and support infrastructures. This trend is most visible in the North American and German healthcare markets.
Medical Ultrasonic Cleaners Market Segmentation
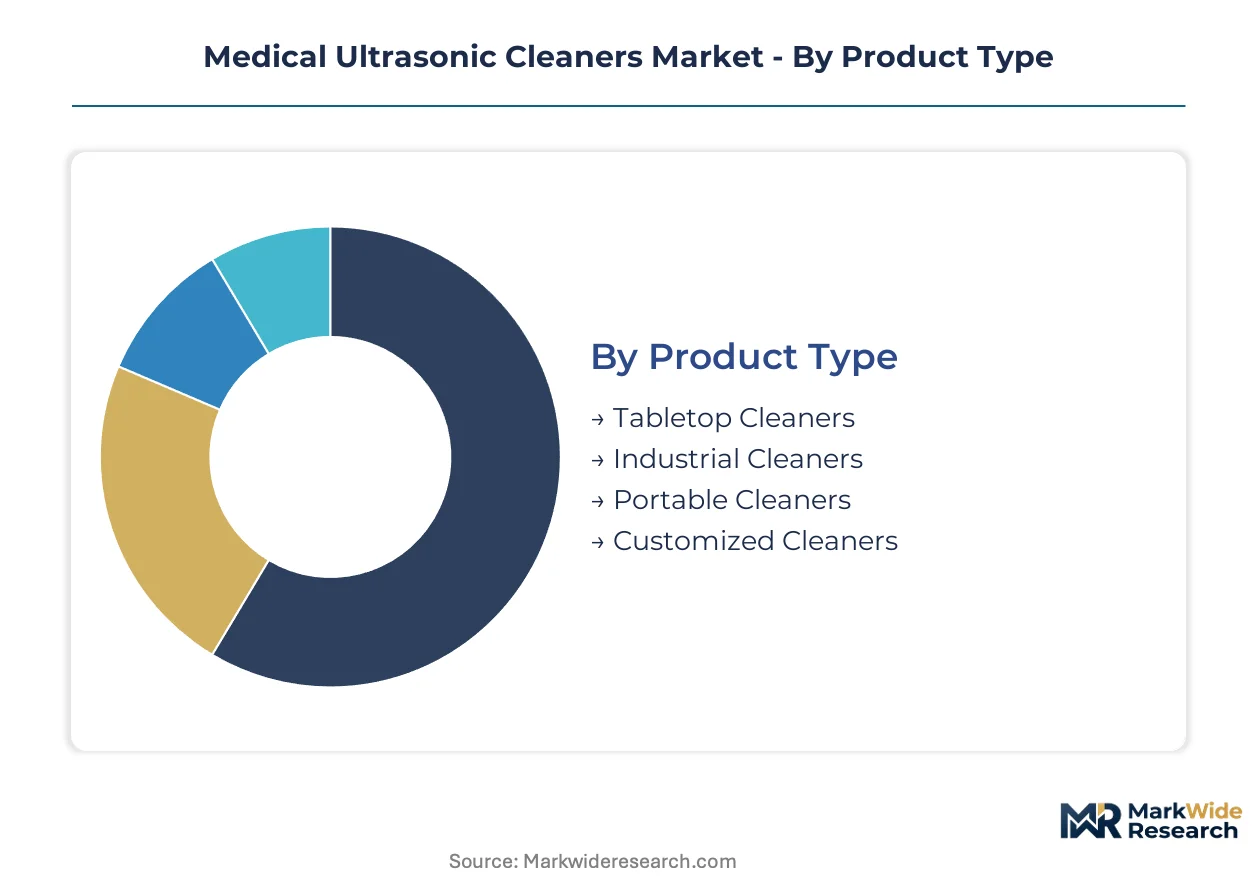
Understanding the Medical Ultrasonic Cleaners Market requires dissecting its core components, which reveal distinct user needs and technological preferences. Segmentation highlights where specialized solutions are developed versus where standardized products dominate. This granular view informs strategic planning for manufacturers and healthcare providers.
Product Type:
The product type segmentation reflects the customization-versus-standardization spectrum of ultrasonic cleaning equipment. This ranges from general-purpose units to highly specialized systems tailored for specific medical environments and instrument types.
- Tabletop Cleaners:These compact units are designed for smaller volumes and rapid turnaround, frequently used in dental clinics and private practices. Their demand concentrates in outpatient settings due to space constraints and the need for efficient pre-cleaning of instruments.
- Industrial Cleaners:Larger, high-capacity systems are engineered for continuous operation within central sterile services departments of major hospitals. Their prevalence in hospital networks stems from the necessity to process large batches of diverse surgical instruments.
- Portable Cleaners:These lightweight, mobile units offer flexibility for various departmental needs or off-site medical applications.
- Customized Cleaners:Tailored solutions address unique requirements for specialized instruments or high-volume, automated workflows in large medical facilities.
Leading the category by volume: Tabletop Cleaners. Growing fastest: Customized Cleaners.
Technology:
Technology segmentation illustrates the evolutionary maturity and performance capabilities embedded in medical ultrasonic cleaning systems. Advanced features enhance cleaning efficacy and process control, differentiating modern solutions.
- Digital Ultrasonic:These systems offer precise control over frequency, power, and cycle times, often with data logging capabilities for regulatory compliance. Demand for digital ultrasonic technology is accelerating within central sterile services departments requiring verifiable decontamination proof.
- High-Frequency Ultrasonic:Employing higher sound frequencies, these units generate smaller cavitation bubbles, suitable for cleaning delicate instruments and complex geometries without damage. Elma Schmidbauer GmbH leverages this specialization for both medical and laboratory end-users.
- Ultrasonic Cavitation:This foundational principle describes the formation and implosion of microscopic bubbles that dislodge contaminants from instrument surfaces.
- Analog Ultrasonic:Older systems provide basic ultrasonic cleaning functionality with manual controls, gradually being displaced by more advanced digital offerings.
The segment with the most advanced features is Digital Ultrasonic, while High-Frequency Ultrasonic is expanding most quickly for specialized applications.
End User:
End-user segmentation highlights the diverse operational contexts and instrument processing volumes across different healthcare settings. Each segment presents unique requirements for equipment scale and integration.
- Hospitals:These institutions demand robust, high-capacity ultrasonic cleaners integrated into complex sterile processing workflows for a wide array of surgical tools. Hospitals represent a significant portion of the market due to their large patient volumes and extensive surgical procedures.
- Dental Clinics:Smaller-scale operations require compact tabletop cleaners for efficient sterilization of handpieces and other dental instruments. The proliferation of dental clinics globally drives consistent demand for accessible and reliable cleaning solutions.
- Laboratories:Research and diagnostic laboratories utilize ultrasonic cleaners for glassware, scientific instruments, and precision components requiring thorough decontamination.
- Veterinary Clinics:Specialized animal hospitals and practices are increasingly adopting medical-grade ultrasonic cleaners for surgical instrument reprocessing, broadening the market beyond human healthcare.
Dominant in terms of application scope is Hospitals, with Veterinary Clinics showing significant expansion.
Application:
Application segmentation delineates the specific cleaning tasks performed by ultrasonic systems, reflecting varied levels of criticality and instrument complexity. This impacts the design and validation requirements for the cleaners.
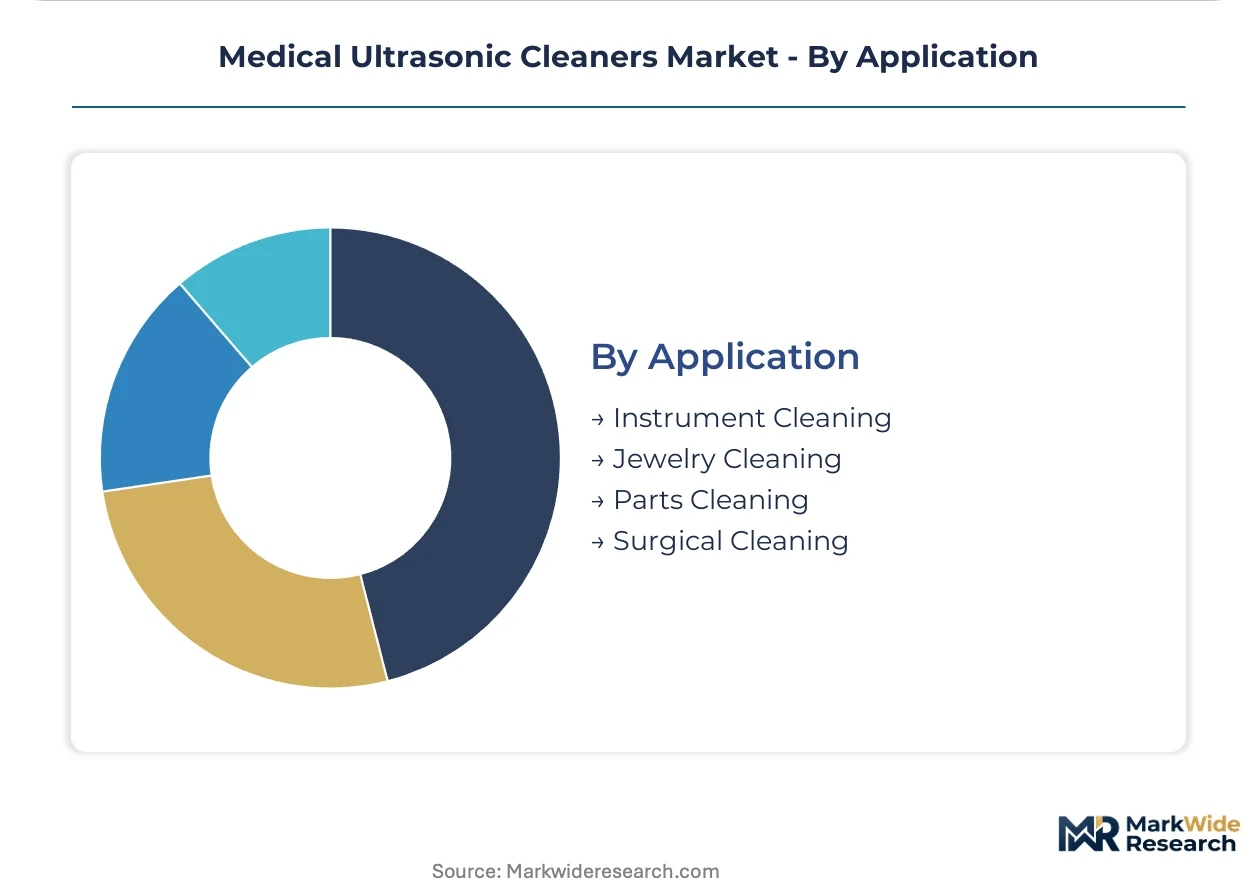
- Surgical Cleaning:This critical application involves pre-cleaning complex and cannulated surgical instruments to remove bioburden before sterilization, directly mitigating infection risks. Stringent regulatory guidelines from bodies like the US FDA drive demand for validated surgical cleaning solutions.
- Instrument Cleaning:General instrument cleaning encompasses a broad range of medical devices, ensuring basic hygiene and extending the lifespan of reusable tools. This application forms the foundational demand across most healthcare facilities.
- Parts Cleaning:Certain medical device manufacturing processes and maintenance require ultrasonic cleaning for small components and precision parts.
- Jewelry Cleaning:While not directly medical, some clinics might use basic ultrasonic units for personal item hygiene, though this is a minor market segment.
The largest revenue contribution comes from Surgical Cleaning, and Instrument Cleaning is demonstrating the highest growth velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device manufacturing hubs, often supported by favorable regulatory environments, drive significant demand for advanced ultrasonic cleaning systems. These zones foster innovation and production, compelling local healthcare facilities to adopt high-standard cleaning technologies for instrument reprocessing. This concentration of medical device manufacturing and export activity shapes regional market dynamics.
United States
The United States market for medical ultrasonic cleaners is propelled by the widespread adoption of complex surgical instruments and the expansion of ambulatory surgery centers. US FDA guidance on reprocessing reusable medical devices mandates stringent cleaning protocols, ensuring high demand for validated systems. Major medical device clusters in states like California and Minnesota actively integrate advanced ultrasonic cleaning into their manufacturing and healthcare ecosystems.
Germany
Germany exhibits robust demand for medical ultrasonic cleaners, underpinned by its advanced healthcare infrastructure and strong medical device export sector. The EU's Medical Device Regulation (MDR) enforces rigorous cleaning validation requirements, pushing facilities towards high-performance digital ultrasonic systems. The Baden-Württemberg region, a significant hub for MedTech innovation, sees consistent investment in sophisticated cleaning technologies for hospitals and research institutions.
Japan
Japan's market growth is supported by an aging population requiring frequent medical interventions and a focus on precision healthcare. PMDA regulations ensure that medical facilities maintain high standards for instrument sterilization, driving the adoption of specialized ultrasonic cleaners. Industrial clusters in Tokyo and Kyoto, known for their advanced medical technology research and development, are key areas for sophisticated cleaning equipment deployment.
Brazil
Brazil represents a growing market, fueled by government-led healthcare modernization initiatives and increasing surgical volumes across its public and private sectors. ANVISA regulations guide the adoption of medical devices and reprocessing equipment, promoting safer patient care practices. The São Paulo state, a major economic and medical hub, features a concentration of hospitals and medical equipment manufacturers investing in advanced cleaning solutions.
India
India's demand for medical ultrasonic cleaners is expanding due to significant investments in hospital infrastructure and a burgeoning medical tourism sector. CDSCO guidelines for medical device quality and reprocessing are gradually formalizing cleaning standards, encouraging facilities to move beyond manual methods. Emerging medical device parks in states such as Gujarat and Andhra Pradesh are fostering local production and adoption of modern cleaning technologies.
Medical Ultrasonic Cleaners Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the competitive dynamics within the medical ultrasonic cleaners market. The market features a mix of established industrial players and specialized medical device suppliers. Strategic archetypes include niche technology innovators, scale-focused providers with broad distribution, and comprehensive solution providers. Geographic expansion into high-growth regions and technology licensing agreements represent dominant competitive moves.
Specialists in high-frequency units, such as Elma Schmidbauer GmbH, offer advanced solutions for delicate instruments and laboratory applications. Emerson Electric Co. occupies a position as a scale-driven provider, leveraging its extensive industrial-grade ultrasonic component expertise and broad distribution network. SharperTek exemplifies a niche player, focusing on portable and tabletop cleaners to serve smaller clinics and private practices with tailored solutions.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Crest Ultrasonics Corporation |
| Mettler Electronics Corp. |
| SharperTek |
| Elma Schmidbauer GmbH |
| L&R Manufacturing |
| Steelco S.p.A. |
| Tangshan UMG Medical Instrument Co., Ltd. |
| Blue Wave Ultrasonics |
| Others |
Cost & Logistics Intelligence
The London Metal Exchange (LME) nickel price impacts stainless steel costs, which then cascade through the medical ultrasonic cleaner supply chain into equipment pricing tiers. This directly influences manufacturing expenses for specialized units and standard models.
Pricing Analysis
Shorter lead times for advanced digital ultrasonic cleaners command a premium, while older analog systems or standard tabletop units may see discounts on spot inventory. The dominant pricing structure involves contract-based long-term agreements for hospitals, with per-unit transactional sales for smaller clinics. Price differentiation stems from customization levels for specialized systems and bundled after-sales service packages. Pricing softness reflects the availability of lower-cost alternatives for non-critical instrument cleaning.
Supply Chain Analysis
Direct sales teams and specialized medical distributors handle high-end systems for hospitals, while broader industrial distribution networks serve smaller clinics. Supply concentration for advanced components is notable in Germany and Japan, with basic parts sourced from China. The market draws from specialized transducers, control electronics, and medical-grade stainless steel. Single-source vulnerability for high-frequency transducers represents a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical ultrasonic cleaners market is undergoing a significant technology transition, with advanced digital ultrasonic systems rapidly displacing older analog models. This shift prioritizes verifiable decontamination and process control.
For Market Incumbents:Anchor existing hospital relationships by offering bundled IQ/OQ/PQ services and multi-year maintenance contracts. Invest in R&D for adaptive frequency sweeping technology to counter emerging entrants offering cost-effective digital solutions. Pursue strategic acquisitions of niche technology innovators specializing in IoT integration for enhanced traceability. Strengthen certification investment for new complex instrument reprocessing to maintain market leadership.
For New Entrants and Emerging Players:The EU's Medical Device Regulation (MDR) in Europe opens a window for new entrants to provide compliant, cost-effective digital tabletop cleaners. Target underpenetrated segments like veterinary clinics and ambulatory surgery centers with compact, efficient solutions. Focus on offering validated tabletop units with basic data logging capabilities for smaller private practices. A go-to-market angle emphasizing ease of validation and rapid instrument turnaround will resonate.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking long-term growth opportunities in healthcare infrastructure over the next decade. Target mid-sized specialists with strong intellectual property in high-frequency ultrasonic technology or IoT integration capabilities. These firms offer differentiation against broader industrial players. Increased hospital procurement mandates for IoT-enabled cleaners will signal market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop IoT-enabled cleaner platforms | Enhances traceability and workflow automation for central sterile services departments. |
| Expand into Latin American markets | Addresses healthcare modernization initiatives in Brazil and Mexico. |
| Acquire high-frequency transducer specialists | Secures critical component supply for delicate instrument cleaning. |
| Partner with surgical instrument manufacturers | Achieves co-validated cleaning solutions for complex orthopedic instruments. |
| Offer bundled IQ/OQ/PQ services | Meets hospital demand for comprehensive lifecycle management in Germany. |
Research Approach
Independent corroboration across US FDA guidance documents, EU MDR publications, and WHO sterilization guidelines underwrites the qualitative findings. Primary interviews with hospital sterile processing managers, dental clinic owners, and ultrasonic cleaner R&D leads provided critical insights. Secondary validation from industry association reports further informed the analysis. This approach ensured robust bottom-up and top-down triangulation of market dynamics.
Rate-of-change decomposition informed the forecast framework across the analysis window, modeling market evolution. Segmentation dimensions included product type, technology, end-user, application, and regional healthcare spending. Compound annual growth rates were derived from historical trends and projected regulatory impacts. Key forecast inputs included surgical procedure volumes and evolving medical device reprocessing guidelines.
Caveats apply where unforeseen regulatory changes or global economic downturns could materially shift the outlook. Forecasts reflect a base case built on current market conditions and projected trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Autoclaves Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market