
 Global Gynecological Examination Chairs Market | 2026-2036
Global Gynecological Examination Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gynecological Examination Chairs Market Foresight
Multi-source component procurement is realigning supply chain economics for gynecological examination chair manufacturers. Medifa leverages captive metalworking capabilities in Germany to control frame production costs. Arjo sustains competitive positioning through specialized pressure-relief upholstery systems for extended examinations. Hillrom dominates North American distribution through direct hospital contracting relationships.
Gynecological examination chairs are height-adjustable medical furniture engineered for pelvic examinations, typically supporting patient loads exceeding 200 kg with electric or hydraulic lift mechanisms and Trendelenburg tilt functionality. Electric chairs command premium positioning due to programmable position memory and integrated foot controls, while manual chairs retain cost-sensitive segments in resource-limited settings. Gynecology clinics represent the largest application channel, though ambulatory surgical centers are expanding fastest as same-day hysteroscopy and colposcopy volumes rise. Adjustable height technology anchors baseline expectations, yet integrated LED examination lighting and antimicrobial upholstery materials now differentiate mid-tier from premium configurations.
FDA 510(k) clearance requirements and IEC 60601-1 third-edition electrical safety standards govern product entry into US and European markets respectively, compelling manufacturers to maintain dual certification portfolios. India's CDSCO medical device rules and BIS certification for imported electromechanical equipment add compliance layers for suppliers targeting Asia's fastest-growing procurement corridors. Stakeholders must monitor evolving MDR transition timelines in Europe and emerging compulsory quality standards in Southeast Asian import regimes to preserve market access trajectories.
Market Dynamics
Powered examination platforms with programmable position memory are displacing manual hydraulic systems as hospital outpatient departments in developing economies prioritize throughput efficiency and staff ergonomics.
Growth Catalysts
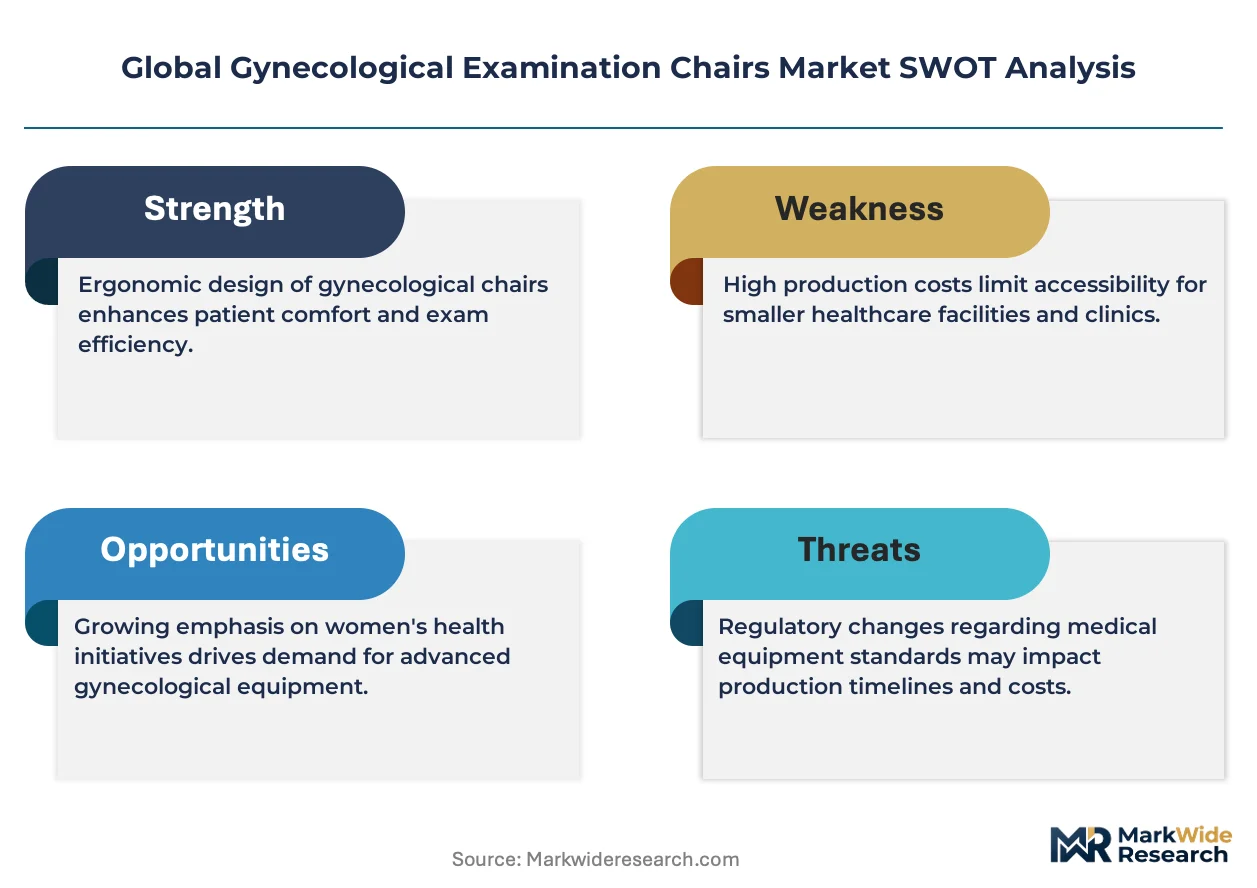
- CE marking under MDR:European regulatory upgrades are filtering out uncertified manufacturers, concentrating procurement among compliant suppliers with established technical documentation.
- Antimicrobial upholstery materials:Infection control protocols in ambulatory surgical centers are mandating surface technologies that reduce pathogen transmission during high-volume colposcopy procedures.
- Vietnam:Primary care infrastructure expansion for maternal health services is creating sustained equipment procurement pipelines through district-level hospital networks.
Market Restraints
- Stainless steel frame costs:Volatility in nickel and chromium input prices compresses margins for manufacturers without captive metalworking capabilities or long-term supply agreements.
- IEC 60601-1 third-edition compliance:Electrical safety testing and documentation requirements extend product development cycles by 8-14 months for new market entrants.
- Manual chair substitution:Cost-sensitive segments in resource-limited settings continue specifying hydraulic lift mechanisms over electric alternatives, constraining premium product penetration.
Strategic Opportunities
- Brazil:SUS (Unified Health System) expansion into underserved northern municipalities is opening tender opportunities for mid-tier electric examination platforms with basic position memory.
- LED-integrated examination lighting:Convergence of surgical illumination standards with gynecological furniture specifications is creating premium differentiation points for manufacturers with optical engineering partnerships.
- Direct hospital contracting:Bypassing traditional medical equipment distributors through dedicated sales teams is capturing margin previously allocated to channel intermediaries in North American procurement.
Industry Challenges
- Biomedical technician certification:Shortage of trained personnel for preventive maintenance on electromechanical lift systems is extending warranty claim resolution times and eroding customer satisfaction scores.
- Legacy facility electrical infrastructure:Older hospital buildings in secondary cities lack adequate grounding and circuit capacity for Class I medical devices, requiring costly site modifications before installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gynecological Examination Chairs Market |
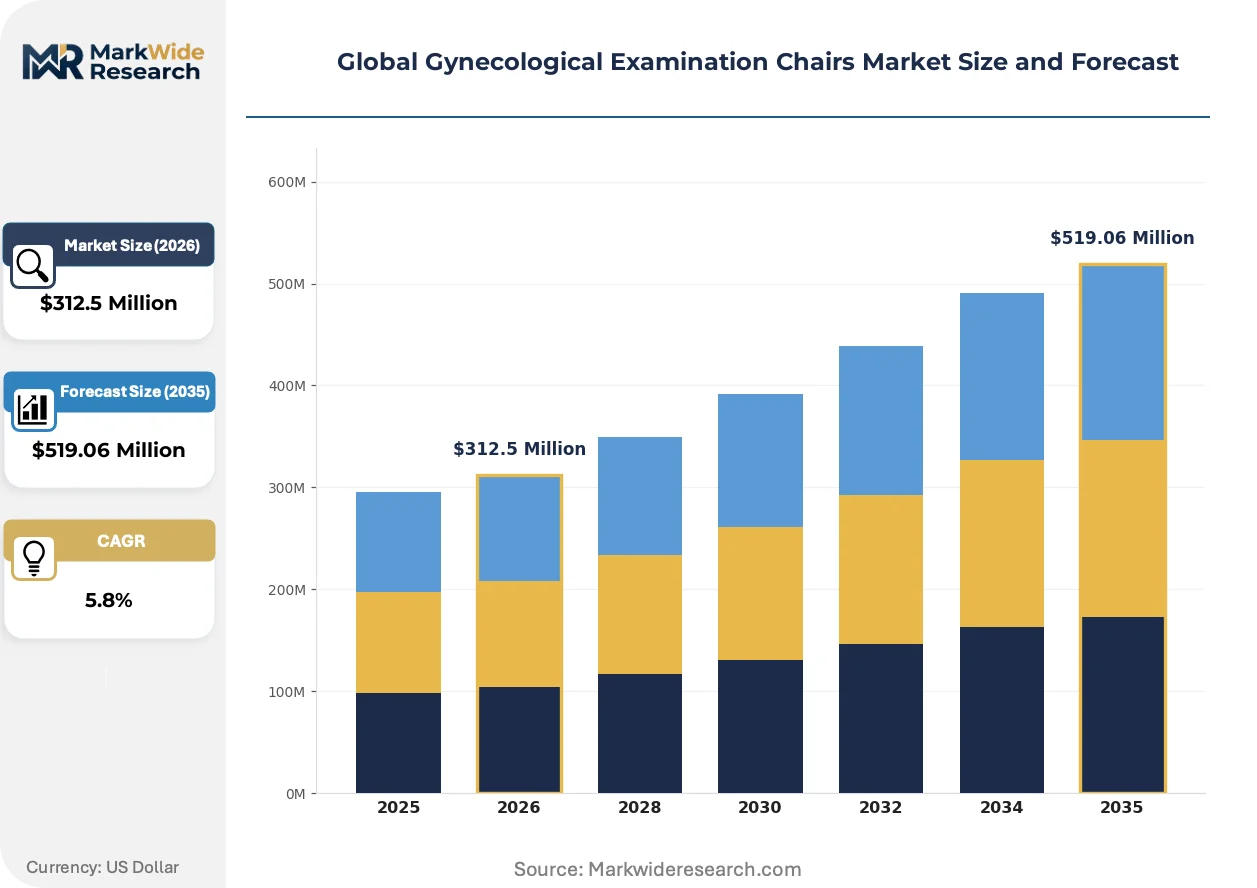
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Chairs, Hydraulic Chairs, Manual Chairs, Portable Chairs, Fixed Chairs Application: Gynecology Clinics, Women’s Health Centers, Diagnostic Laboratories, Ambulatory Surgical Centers, Fertility Clinics End User: Gynecologists, Obstetricians, Medical Institutions, Research Facilities, Specialized Clinics Technology: Adjustable Height, Tilt Function, Integrated Lighting, Armrest Design, Footrest Mechanism, Upholstery Material |
| Companies Covered | Medifa, Arjo, Favero Health Projects Spa, Malvestio, SCHMITZ, Hillrom, Oakworks Inc., Promotal, Harbin Howell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gynecological Examination Chairs Market Shifts & Advancements
Digital position control systems and connected device architectures are redefining baseline expectations for gynecological examination furniture, shifting competitive advantage toward software-integrated hardware platforms.
Programmable memory modules with foot-activated controls are expanding into high-throughput hospital outpatient departments where examination cycle time directly impacts revenue per clinical hour. Large women's health networks in India are specifying these systems for standardized patient positioning protocols across multi-site operations. The technology is compressing demand for manual hydraulic alternatives in urban tertiary care settings while creating service revenue streams through firmware update subscriptions.
India's CDSCO medical device rules are tightening registration requirements for electromechanical equipment imported without prior BIS certification or local testing laboratory validation. Manufacturers targeting Asia's fastest-growing procurement corridors must now maintain dual regulatory portfolios with extended technical file documentation. Mid-tier suppliers without dedicated compliance teams are exiting the market rather than absorbing certification cost burdens.
Consolidated procurement through centralized hospital purchasing cooperatives is displacing individual department-level buying authority for capital equipment acquisitions. Large health systems in the United States are negotiating multi-year supply agreements with exclusive vendor commitments that bundle examination chairs with stretchers and surgical tables. This concentration is visible most acutely in integrated delivery networks where standardization mandates override individual physician equipment preferences.
Global Gynecological Examination Chairs Market Segmentation
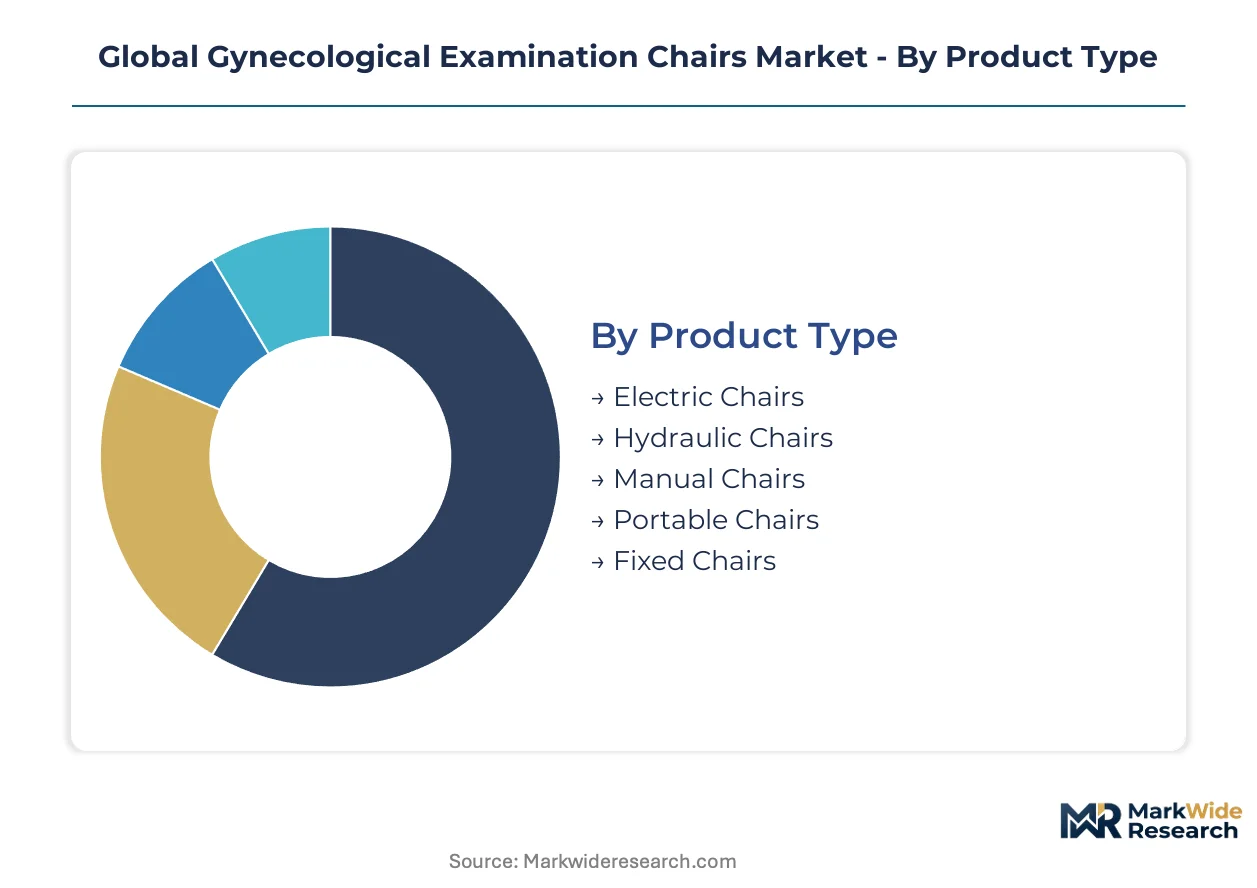
Gynecological examination chair procurement patterns diverge sharply by facility type, technology tier, and clinical workflow intensity. Understanding these fault lines reveals where manufacturers must configure product portfolios and where service revenue opportunities concentrate.
Product Type:
Capital allocation thresholds and electrical infrastructure capacity separate buyers across power mechanism categories.
- Electric Chairs:Programmable position memory and foot-activated controls support high-throughput hospital outpatient departments. India's expanding women's health networks specify these for standardized protocols across multi-site operations.
- Hydraulic Chairs:Manual lift mechanisms with pneumatic assist retain dominance in resource-limited settings lacking reliable electrical supply. Brazil's SUS expansion into northern municipalities sources these for basic examination capacity.
- Manual Chairs:Fixed-height mechanical platforms serve temporary screening camps and mobile outreach programs.
- Portable Chairs:Collapsible aluminum-frame units with detachable components address field deployment requirements.
- Fixed Chairs:Stationary examination platforms with welded steel construction occupy legacy clinic installations.
Volume sits with hydraulic chairs; growth tilts toward electric chairs.
Application:
Procedure complexity and reimbursement rates determine equipment specification intensity across care settings.
- Gynecology Clinics:Dedicated pelvic examination facilities generate the highest chair utilization rates. India's district-level hospital networks are expanding procurement of mid-tier electric platforms with basic position memory.
- Ambulatory Surgical Centers:Same-day hysteroscopy and colposcopy volumes are climbing fastest. These facilities mandate antimicrobial upholstery and integrated LED examination lighting to meet infection control protocols.
- Women's Health Centers:Comprehensive service delivery models require versatile positioning for contraceptive counseling through minor procedures.
- Diagnostic Laboratories:Specimen collection and preliminary screening workflows prioritize rapid patient turnover over advanced positioning features.
- Fertility Clinics:Ultrasound-guided procedures demand extended Trendelenburg tilt capability and pressure-relief upholstery for prolonged examinations.
Revenue concentrates in gynecology clinics; expansion is steepest in ambulatory surgical centers.
End User:
Decision-making authority and maintenance capability shape purchasing criteria across practitioner categories.
- Gynecologists:Individual practitioners and small group practices prioritize ergonomic controls and patient comfort features that reduce physical strain during extended examinations.
- Medical Institutions:Hospital systems negotiate centralized procurement agreements bundling examination chairs with stretchers and surgical tables, overriding individual physician preferences.
- Obstetricians:Prenatal examination workflows require rapid height adjustment for third-trimester patient accommodation.
- Specialized Clinics:Colposcopy and LEEP procedure centers specify premium configurations with integrated video documentation mounts.
- Research Facilities:Academic medical centers demand interoperability with electronic health record systems and clinical trial data capture protocols.
Installed base dominates medical institutions; specialized clinics are gaining share fastest.
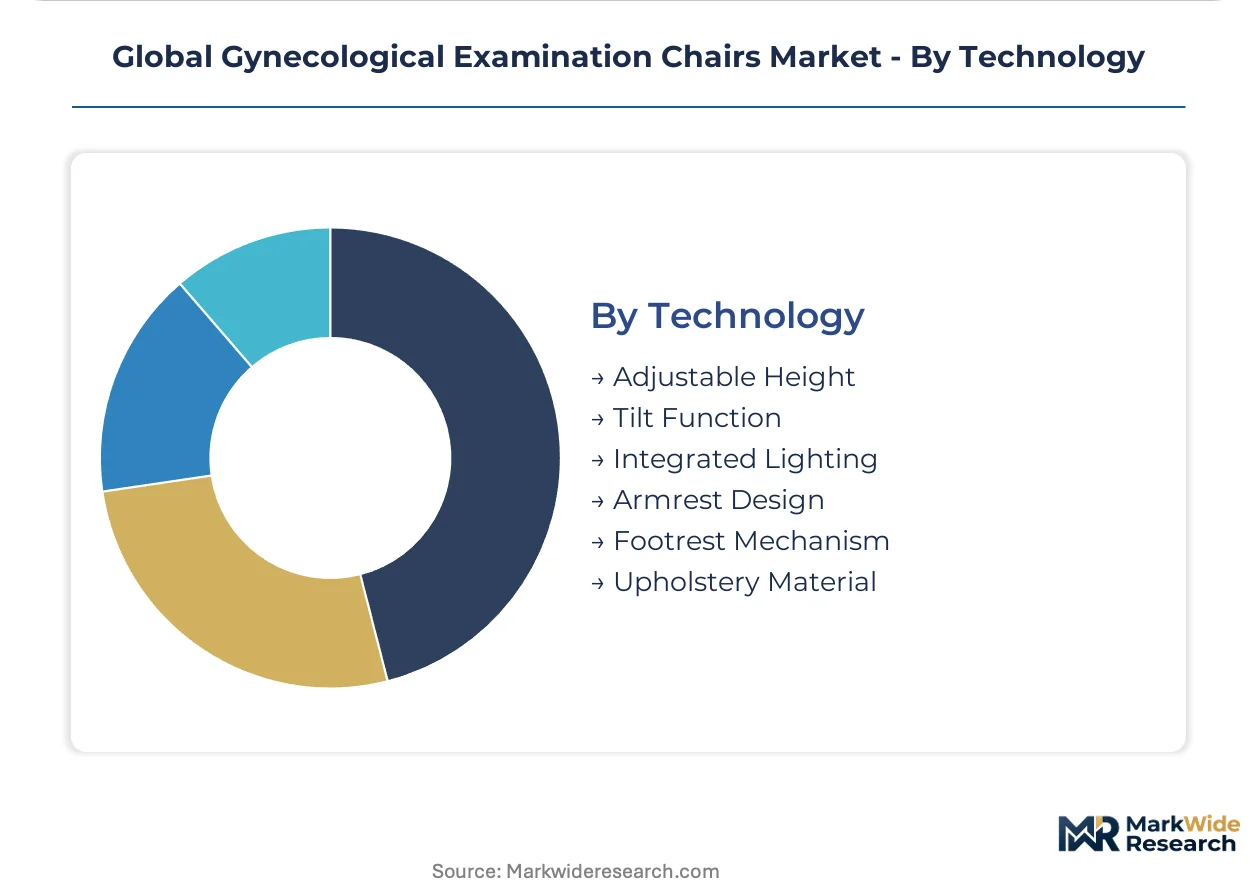
Technology:
Component integration depth separates baseline commodity offerings from premium differentiated configurations.
- Adjustable Height:Electric linear actuators with 50-80 cm vertical travel range anchor baseline category expectations. Vietnam's primary care infrastructure expansion specifies this capability as mandatory for district hospital procurement.
- Integrated Lighting:LED examination lamps with adjustable color temperature converge surgical illumination standards with gynecological furniture specifications. Manufacturers with optical engineering partnerships capture premium positioning.
- Tilt Function:Trendelenburg positioning with 15-30 degree incline supports laparoscopic examination and minor surgical procedures.
- Armrest Design:Articulating supports with 180-degree rotation facilitate patient transfer and procedural access.
- Footrest Mechanism:Split-leg stirrup configurations with independent positioning accommodate diverse examination protocols.
- Upholstery Material:Antimicrobial vinyl and silicone-coated fabrics reduce pathogen transmission in high-volume colposcopy settings.
Adoption is broadest for adjustable height; integrated lighting commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German stainless steel processing centers supply frame components to examination chair fabricators across three continents. Nickel and chromium price volatility from Indonesian mining operations directly impacts manufacturing economics in European and North American assembly plants.
United States
Hospital outpatient departments drive specification intensity for powered platforms with programmable memory. FDA 510(k) clearance requirements govern product entry and sustain dual-certification portfolios among incumbent suppliers. Texas Medical Center procurement networks in Houston negotiate multi-year supply agreements bundling examination chairs with surgical tables.
Germany
Captive metalworking capabilities anchor frame production for premium electric examination platforms. CE marking under MDR filters uncertified manufacturers and concentrates procurement among compliant suppliers with established technical documentation. Baden-Württemberg industrial clusters around Stuttgart maintain specialized upholstery supply chains for pressure-relief systems.
India
District-level hospital networks expand procurement of mid-tier electric platforms with basic position memory. CDSCO medical device rules and BIS certification for imported electromechanical equipment add compliance layers for foreign suppliers. Maharashtra's women's health networks specify standardized patient positioning protocols across multi-site Mumbai and Pune operations.
Brazil
SUS expansion into underserved northern municipalities opens tender opportunities for mid-tier electric examination platforms. Manual hydraulic chairs retain dominance in resource-limited settings lacking reliable electrical supply. São Paulo state health secretariats centralize capital equipment acquisitions through cooperative purchasing agreements.
Vietnam
Primary care infrastructure expansion for maternal health services creates sustained equipment procurement pipelines. Adjustable height capability is mandatory for district hospital procurement under national health facility standards. Ho Chi Minh City medical equipment distributors serve as procurement gateways for southern provincial hospital networks.
Global Gynecological Examination Chairs Market Competitive Landscape
Global majors compete with regional champions across regulatory certification depth and distribution reach. Market structure tilts toward consolidated procurement through centralized hospital purchasing cooperatives, displacing individual department-level buying authority. Three archetypes dominate: European engineering specialists with captive metalworking, North American scale players with direct hospital contracting, and Asian value-tier fabricators with modular platform designs. Competitive moves center on M&A for regulatory portfolio expansion and strategic partnerships for optical engineering capabilities in integrated lighting systems.
Among European engineering specialists, Medifa GmbH and SCHMITZ u. Söhne GmbH & Co. KG exemplify the captive manufacturing archetype with in-house frame production control. Hillrom Holdings, Inc. anchors the North American direct-contracting tier through dedicated hospital sales teams. Arjo AB occupies a position bridging European engineering standards with global distribution scale. Malvestio S.p.A. and Favero Health Projects Spa represent Italian upholstery specialization within the mid-premium segment. Harbin Howell Medical Apparatus & Instrument Co., Ltd. sits within the Asian value-tier cluster serving cost-sensitive procurement corridors.
| Leading Market Players |
|---|
| Medifa |
| Arjo |
| Favero Health Projects Spa |
| Malvestio |
| SCHMITZ |
| Hillrom |
| Oakworks Inc. |
| Promotal |
| Harbin Howell |
| Others |
Supply & Pricing Matrix
CE marking under the EU Medical Device Regulation gates qualified supply access and premium-tier pricing power, filtering uncertified manufacturers from European procurement channels while elevating compliance costs as a mandatory cost-of-entry component for market participation.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium electric platform suppliers from unbundled economy-tier competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and after-sales service inclusion. Cost compression in the hydraulic chair segment intensifies because manual mechanism suppliers compete on stripped-down specifications for resource-limited settings. Public hospital procurement committees in Brazil and Vietnam exhibit highest price sensitivity; private ambulatory surgical centers in the United States demonstrate lowest sensitivity due to reimbursement rate insulation.
Supply Chain Analysis
India's BIS certification requirements and local-content preferences for electromechanical medical equipment are reshaping sourcing strategies for foreign suppliers targeting district hospital networks. Frame fabrication concentrates in Germany, China, and India; upholstery systems draw from Italian and German specialized suppliers. Nickel and chromium price volatility from Indonesian mining operations creates commodity exposure for stainless steel component costs. Distribution runs through hospital purchasing cooperatives and dedicated medical equipment distributors serving provincial health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance narrative where IEC 60601-1 third-edition electrical safety certification creates a structural barrier-to-entry moat, advantaging incumbents with established technical documentation and testing infrastructure.
For Market Incumbents: Deploy firmware update subscription models to capture recurring revenue from installed electric chair bases and offset hardware margin compression. In-house production of linear actuator assemblies reduces exposure to component supply disruptions. Biomedical technician certification shortages threaten service quality metrics; accredited training partnerships with technical institutes defend customer retention rates. For New Entrants and Emerging Players: The mid-tier price-point gap between premium European electric platforms and basic Asian manual chairs offers white-space opportunity for standardized electric models with basic position memory. Brazil's SUS northern municipality expansion represents the most penetrable procurement corridor for new suppliers. CDSCO registration facilitation through Indian joint venture structures accelerates market access without full BIS laboratory investment. For Investors and Strategic Acquirers: MDR transition completion timelines for legacy CE-marked portfolios are the leading indicator that consolidation pressure will intensify among mid-tier European fabricators lacking dedicated compliance teams. Five-to-ten year viability favors suppliers with dual FDA and MDR certification depth and established direct hospital contracting relationships. Watch for distressed acquisition opportunities among Italian upholstery specialists facing optical engineering capability gaps in integrated lighting convergence.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation investment filters competition and secures European hospital access. |
| Hospital System Partnership | Multi-year supply agreements with integrated delivery networks override individual physician preferences. |
| Software Companion Development | Programmable position memory modules create firmware subscription revenue streams beyond hardware sales. |
| Backward Integration into Actuators | In-house linear actuator production reduces supply disruption exposure and protects margin structure. |
| Optical Engineering Partnership | LED examination lighting integration captures premium positioning as surgical illumination standards converge. |
Research Methodology
Independent corroboration across hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and regulatory affairs leads at medical device manufacturers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, CDSCO registration databases, hospital capital equipment tender records, and EU MDR notified body documentation. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable-period anchoring to historical procurement cycles across the analysis window informed the projection framework. Segmentation dimensions modeled include power mechanism category, application setting, end-user decision authority, and technology integration depth. CAGRs were derived from fitted growth curves incorporating equipment replacement cycles, infrastructure expansion budgets, and regulatory transition timelines. Forecast inputs incorporated district-level hospital network procurement pipelines and maternal health service expansion targets.
Inputs from procurement databases and regulatory filing systems were available through the study window; gaps in real-time tender outcome data introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding MDR enforcement consistency and electrical infrastructure upgrade rates in secondary cities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
MRI Transport Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market