
 Synthetic Gypsum Market | 2026-2036
Synthetic Gypsum Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Gypsum Market Outlook
The EU Green Deal's circular-economy mandates for construction materials is pivoting procurement patterns across European building supply chains. Saint-Gobain leverages its integrated FGD gypsum processing network to secure feedstock for wallboard operations in France and Germany. Knauf Group anchors its competitive position through captive supply agreements with coal-fired utilities in Poland and the United Kingdom.
Synthetic gypsum is a calcium sulfate dihydrate (CaSO4·2H2O) material recovered from industrial flue gas desulfurization, phosphoric acid production, and titanium dioxide manufacturing, typically containing 95-99% gypsum content with controlled moisture levels below 10%. It serves primarily as a direct substitute for mined natural gypsum in cement retardation and wallboard core formulations. Flue gas desulfurization gypsum dominates volume due to sustained coal-plant operations in Asia-Pacific and North American utility fleets. Wallboard manufacturing captures the largest value share, while soil amendment applications in the agriculture sector are gaining traction as sulfur-deficient cropland expands.
The US EPA regulates coal combustion residual handling under federal groundwater protection standards, while China's MEE enforces dual carbon goals that mandate industrial by-product utilization rates. REACH registration requirements in Europe restrict heavy-metal content in construction-grade gypsum, shaping product specifications for cross-border trade. Stakeholders must monitor tightening landfill diversion targets and utility decarbonization timelines that threaten long-term FGD feedstock availability.
Market Dynamics
The synthetic gypsum market pivots on coal-fired utility decarbonization timelines that threaten to sever feedstock pipelines before alternative industrial sources mature, forcing wallboard manufacturers to secure long-term offtake contracts or diversify raw material sourcing.
Growth Catalysts
- EU Green Deal circular-economy mandates:Construction material diversion targets redirect flue gas desulfurization by-product into processed gypsum streams across France, Germany, and Poland.
- Wallboard core formulation substitution:Cement retardation applications expand as sulfur-deficient agricultural zones drive soil amendment demand in the American Midwest.
- China's GB standards on industrial by-product utilization:MEE enforcement of dual carbon goals mandates specific utilization rates for phosphoric acid and titanium dioxide manufacturing residues.
Market Restraints
- FGD feedstock concentration risk:Midwest and Southeast utility corridors dominate North American supply, creating geographic vulnerability to plant retirements.
- Heavy-metal content thresholds:REACH registration requirements in Europe restrict cross-border trade of construction-grade material exceeding specified contaminant limits.
- Natural gypsum price volatility:Mined mineral from Spanish and Thai quarries fluctuates with energy costs, compressing synthetic product margin buffers.
Strategic Opportunities
- Phosphogypsum processing expansion:Florida and Idaho fertilizer manufacturing corridors offer untapped calcium sulfate dihydrate recovery potential for wallboard feedstock.
- Agricultural sulfur deficiency correction:Corn and soybean belt expansion in Illinois and Iowa creates soil amendment pull for high-purity synthetic gypsum.
- Carbon capture integration:Mineralization pathways at coal-plant sites combine flue gas treatment with CO2 sequestration, qualifying projects for IRA production tax credits.
Industry Challenges
- Moisture control specification compliance:Wallboard manufacturers require sub-10% moisture content that demands precise drying infrastructure investment.
- Cross-state transport logistics friction:EPA coal combustion residual classification variations create permitting complexity for interstate material movement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Gypsum Market |
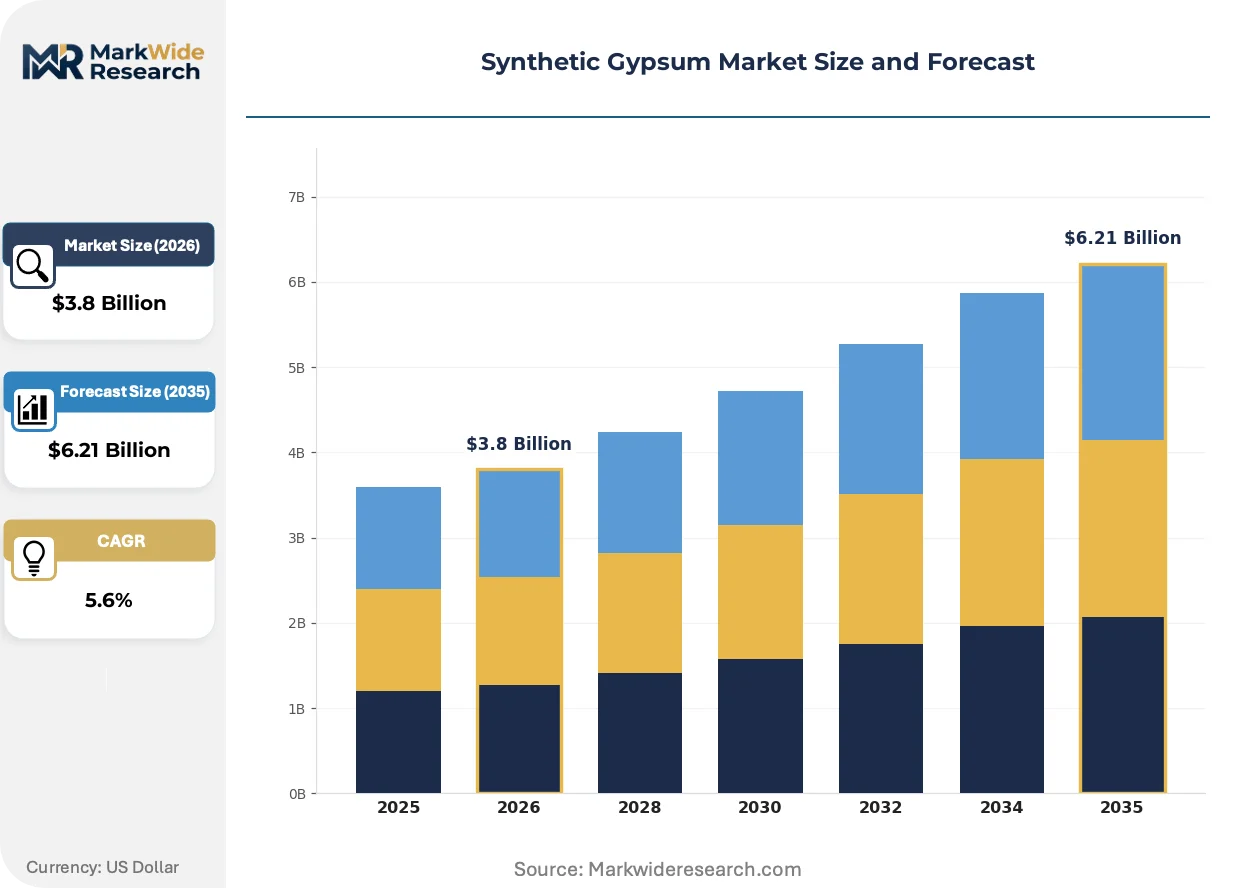
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flue Gas Desulfurization Gypsum, Phosphogypsum, Titanium Dioxide Gypsum, Industrial By-Product Gypsum Application: Cement Production, Soil Amendment, Wallboard Manufacturing, Industrial Application End User: Construction Industry, Agriculture Sector, Manufacturing Sector, Energy Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Saint-Gobain, Georgia-Pacific, Knauf Group, Yoshino Gypsum, LafargeHolcim, USG Corporation, Etex Group, American Gypsum Company, National Gypsum Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Gypsum Market Strategic Shifts
Processing technology convergence and regulatory reclassification are compressing traditional supply chain configurations while opening novel feedstock pathways from non-coal industrial sources.
Dryer-kiln hybrid systems are unifying moisture reduction and calcination stages into continuous processing lines. Wallboard producers in the American Southeast deploy these integrated units to handle variable FGD gypsum input quality. The technology is unifying previously separate capital equipment investments, reducing plant footprints and energy intensity for synthetic feedstock preparation.
REACH heavy-metal testing protocols now mandate batch-level certification for construction-grade gypsum entering European customs zones. German and French importers have restructured supplier qualification programs to document trace element compliance before shipment. Wallboard manufacturers with integrated FGD processing networks absorb compliance costs more efficiently than merchant traders.
Long-term offtake contracting now dominates utility-sector procurement negotiations as plant operators seek revenue stability ahead of retirement deadlines. Midwest wallboard plants lock in decade-long supply agreements with coal generators, displacing spot-market purchasing that prevailed through the 2010s. This contractual pivot concentrates negotiating leverage with integrated manufacturers possessing dedicated logistics infrastructure.
Synthetic Gypsum Market Segmentation
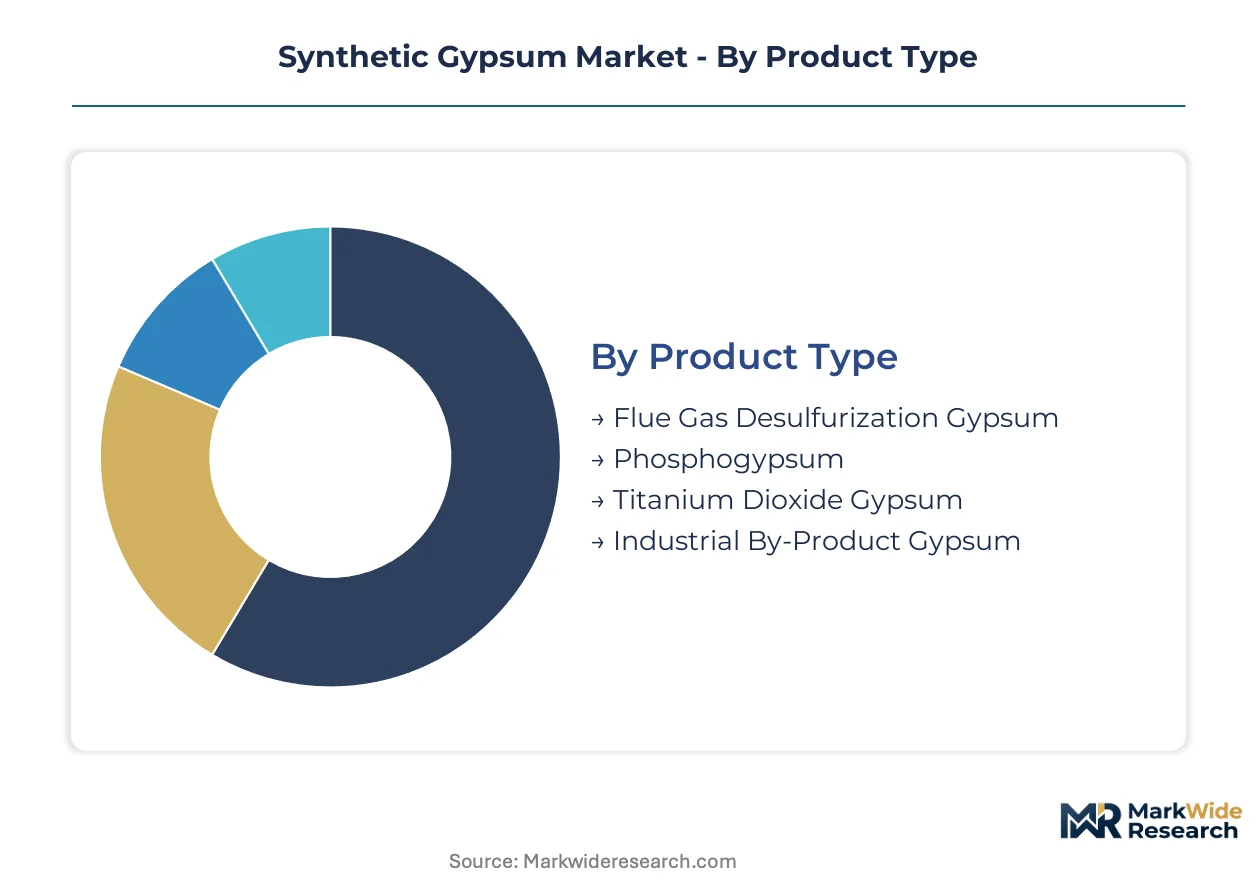
Segmentation in synthetic gypsum markets reveals divergent capital requirements and margin structures across feedstock types and end-use channels. Procurement patterns vary sharply between integrated wallboard manufacturers and merchant traders serving agricultural or cement customers.
Product Type:
Capital intensity peaks with flue gas desulfurization processing, where dedicated dewatering and drying infrastructure at utility sites demands substantial upfront investment.
- Flue Gas Desulfurization Gypsum:Calcium sulfate dihydrate recovered from coal-plant scrubber systems, typically 95-99% purity with controlled moisture below 10%. Demand concentrates in the American Midwest and Southeast, where integrated wallboard plants source directly from adjacent utility corridors. EPA coal combustion residual rules mandate specific handling protocols that favor long-term offtake contracting over spot markets.
- Phosphogypsum:By-product of phosphoric acid manufacturing, containing elevated radionuclide levels that restrict construction-grade applications in most jurisdictions. Processing for agricultural soil amendment in Florida and Idaho fertilizer corridors requires specialized beneficiation equipment to meet purity thresholds.
- Titanium Dioxide Gypsum:Sulfate-process residue from pigment manufacturing, characterized by finer particle size distribution. Chemical sector captive supply agreements dominate procurement in China and Germany.
- Industrial By-Product Gypsum:Miscellaneous calcium sulfate streams from citric acid, hydrofluoric acid, and other chemical processes. Merchant traders aggregate fragmented supply for cement retardation applications.
Most installed capacity flows through flue gas desulfurization gypsum. Expansion is steepest in phosphogypsum processing as fertilizer manufacturers seek landfill diversion pathways.
Application:
Application segmentation tracks diverging specification stringency, with wallboard manufacturing imposing the tightest quality controls while soil amendment tolerates broader compositional variance.
- Wallboard Manufacturing:Core formulation demands precise particle size distribution and sub-10% moisture content for continuous board-line operations. Knauf Group and Saint-Gobain operate integrated FGD processing networks across Poland, France, and Germany to secure compliant feedstock. REACH heavy-metal thresholds restrict cross-border sourcing flexibility.
- Cement Production:Gypsum serves as set-retarder in Portland cement grinding, requiring 35-45% calcium sulfate content. Cement plants in China source phosphogypsum under MEE-mandated industrial by-product utilization rates.
- Soil Amendment:Sulfur-deficient cropland in Illinois and Iowa drives demand for high-purity calcium sulfate. Agricultural distributors favor bulk rail delivery over bagged product.
- Industrial Application:Foundry mold release, glass manufacturing, and chemical feedstock uses absorb lower-grade material rejected by construction applications.
Volume concentration sits with wallboard manufacturing. Agricultural soil amendment is climbing the fastest as sulfur deficiency spreads across American corn and soybean belts.
End User:
End user segmentation reflects fundamentally different procurement behaviors, with construction sector buyers prioritizing supply security and agricultural buyers optimizing delivered cost per ton of sulfur equivalent.
- Construction Industry:Wallboard and cement manufacturers dominate value capture. Long-term offtake contracts with coal utilities have displaced spot purchasing across the American Midwest.
- Agriculture Sector:Corn and soybean producers in Illinois, Iowa, and Indiana apply synthetic gypsum for sulfur nutrition and soil structure improvement. Co-op purchasing aggregates fragmented farm demand.
- Manufacturing Sector:Chemical, glass, and foundry operations source lower-specification material through merchant distributors.
- Energy Sector:Coal-plant operators themselves consume processed gypsum for on-site landfill cover and stabilization applications.
Construction industry procurement absorbs the highest-grade output. Agriculture sector demand is expanding most quickly as sulfur deficiency correction gains agronomic attention.
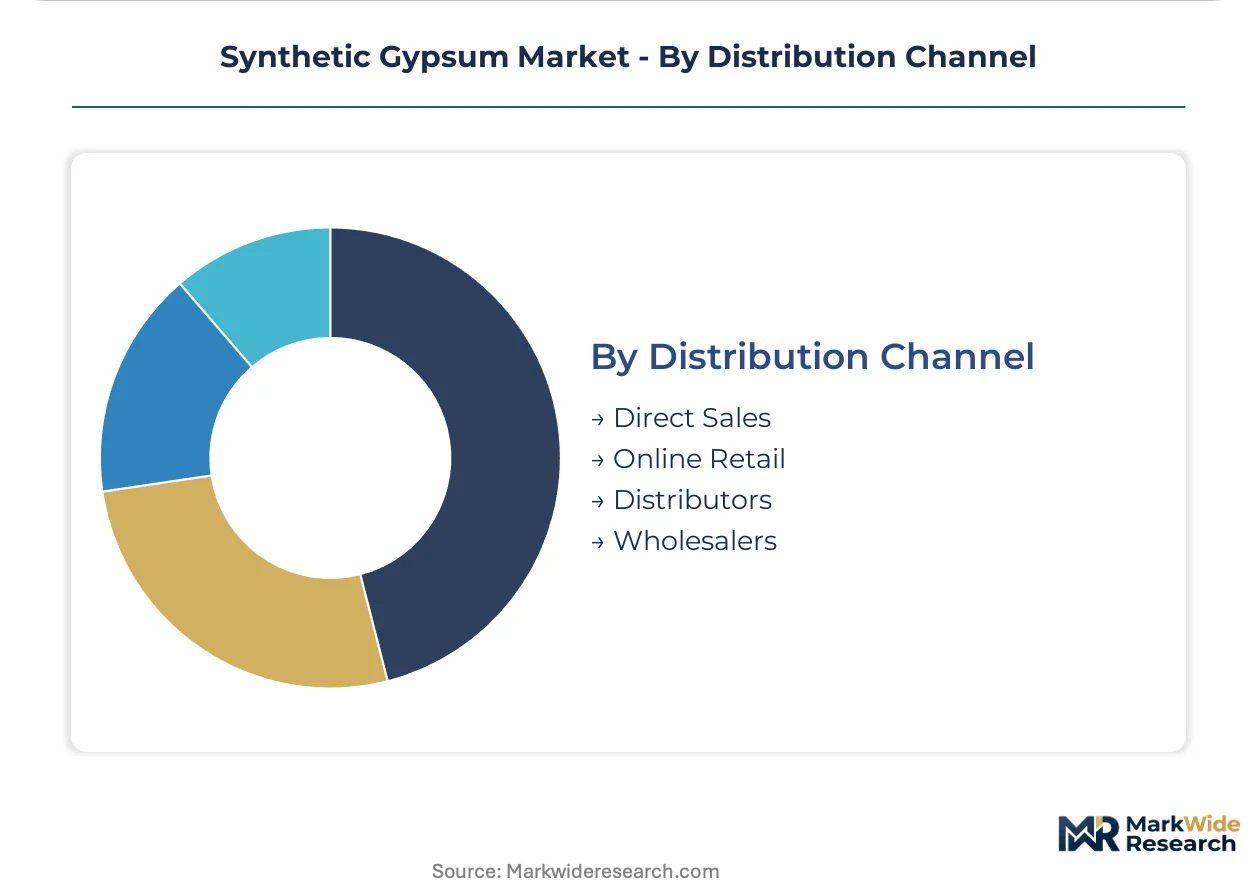
Distribution Channel:
Channel segmentation tracks the shift from merchant intermediaries toward direct procurement as wallboard manufacturers deepen backward integration into FGD processing.
- Direct Sales:Integrated wallboard plants source directly from adjacent coal utilities via dedicated conveyor or short-haul truck. This channel captures the highest volume and lowest logistics cost.
- Distributors:Regional construction material distributors serve mid-size cement plants and wallboard operations lacking captive supply agreements. Inventory carrying costs concentrate in the Great Lakes and Ohio River corridors.
- Wholesalers:Agricultural supply wholesalers aggregate synthetic gypsum with lime and fertilizer products for farm-gate delivery.
- Online Retail:Bagged specialty products for residential lawn and garden applications move through e-commerce platforms, representing minimal volume share.
Direct sales channels handle the majority of tonnage. Distributor relationships are gaining share fastest among second-tier wallboard producers seeking supply diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The synthetic gypsum industry traces its commercial roots to coal-fired utility expansion across the American Midwest during the 1970s Clean Air Act era, when flue gas desulfurization systems created calcium sulfate dihydrate recovery economics. Wallboard manufacturers subsequently built integrated processing networks adjacent to power plants, establishing the template now replicated in Europe and Asia.
United States
Midwest and Southeast utility corridors supply integrated wallboard plants in Indiana, Ohio, and Georgia with FGD gypsum feedstock. The EPA's coal combustion residual rules mandate specific groundwater protection protocols that favor long-term offtake contracting over spot markets. Saint-Gobain and USG Corporation operate captive processing facilities in Michigan and North Carolina, converting adjacent power plant output directly into wallboard core material.
Germany
Knauf Group anchors its European supply position through backward integration into coal-utility partnerships across North Rhine-Westphalia and Saxony. The EU Green Deal's circular-economy construction mandates redirect industrial by-product streams into processed gypsum under diversion targets enforced by national implementation laws. REACH registration requirements for heavy-metal content restrict cross-border sourcing flexibility, favoring domestic integrated networks over merchant traders.
China
GB standards on industrial by-product utilization mandate specific recovery rates for phosphoric acid and titanium dioxide manufacturing residues under MEE enforcement of dual carbon goals. Wallboard and cement producers in Shandong and Hebei provinces source synthetic gypsum from captive chemical sector agreements. The Yangtze River Delta hosts concentrated phosphogypsum processing capacity serving agricultural soil amendment demand in sulfur-deficient cropland.
Poland
Knauf Group maintains captive supply agreements with coal-fired utilities in the Silesian industrial basin, securing feedstock for wallboard operations serving Central European construction markets. National implementation of EU landfill diversion targets accelerates FGD gypsum recovery from power plants scheduled for phase-out under decarbonization timelines. Processing infrastructure in Upper Silesia connects directly to German distribution networks via rail corridors.
Japan
Yoshino Gypsum exemplifies integrated FGD processing architecture, operating dewatering and drying facilities adjacent to coal and oil-fired power stations in Chubu and Kansai industrial zones. METI industrial waste utilization guidelines encourage synthetic gypsum substitution for mined natural material in cement retardation applications. The Seto Inland Sea chemical manufacturing corridor generates titanium dioxide gypsum streams captured for construction-grade processing.
Synthetic Gypsum Market Competitive Environment
Capital-heavy producers compete with asset-light traders across a market structure consolidating around integrated wallboard manufacturers with captive supply agreements. The vendor base separates into three archetypes: utility-integrated processors controlling feedstock pipelines, merchant traders aggregating fragmented industrial by-product supply, and chemical sector captives consuming internal gypsum streams. Dominant competitive moves include backward integration into FGD processing infrastructure and long-term offtake contracting ahead of utility decarbonization deadlines.
Among North American building material specialists, Georgia-Pacific and National Gypsum Company exemplify utility-integrated processing archetypes, while Saint-Gobain anchors European competitive positioning through multinational captive network architecture. These three entities occupy positions defined by geographic concentration of coal-utility partnerships rather than product differentiation, with competitive advantage deriving from logistics infrastructure ownership and contractual feedstock security.
| Leading Market Players |
|---|
| Saint-Gobain |
| Georgia-Pacific |
| Knauf Group |
| Yoshino Gypsum |
| LafargeHolcim |
| USG Corporation |
| Etex Group |
| American Gypsum Company |
| National Gypsum Company |
| Others |
Value Chain & Pricing Dynamics
Captive backward integration into FGD processing infrastructure anchors both supply security and pricing power for wallboard manufacturers in the American Midwest, where dedicated conveyor links to coal utilities eliminate merchant feedstock premiums and buffer margin compression from natural gypsum volatility.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing structures, with volume scale and moisture-content certification grade as primary price differentiation drivers. Cost compression in standard-grade feedstock is intensifying because utility decarbonization timelines compress contract renewal windows. Cement producers exhibit highest price sensitivity due to thinner margin structures, while integrated wallboard plants absorb premiums for guaranteed sub-10% moisture specifications.
Supply Chain Analysis
Skilled technician availability in Michigan, Ohio, and Indiana manufacturing clusters supports dryer-kiln hybrid system operations critical to moisture-control compliance. Supply concentrates in the United States, China, and Germany, drawing from coal-plant FGD systems, phosphoric acid manufacturing, and titanium dioxide production residues. Single-source vulnerability to utility retirement schedules threatens feedstock continuity. Distribution runs through direct conveyor links and short-haul truck networks serving adjacent wallboard plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the American Midwest's dense utility-corridor feedstock and Europe's landfill-diversion premiums under EU Green Deal mandates.
For Market Incumbents: Hedge against FGD feedstock depletion by securing phosphogypsum processing rights in Florida and Idaho fertilizer corridors. Deepen backward integration into carbon-capture-integrated mineralization projects qualifying for IRA production tax credits, insulating margin structures from natural gypsum price swings. For New Entrants and Emerging Players: E-commerce platforms for bagged agricultural soil amendment products offer white-space entry, targeting sulfur-deficient corn and soybean belt co-ops in Illinois and Iowa underserved by bulk-rail infrastructure. Pursue toll-processing partnerships with stranded phosphogypsum stockpiles as lowest-capital feedstock access. For Investors and Strategic Acquirers: Roll-up economics work for regional merchant traders with captive logistics infrastructure because utility decarbonization timelines force distressed asset sales ahead of contract expiration. Monitor EPA coal combustion residual reclassification proceedings as inflection signal for interstate transport cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Midwest wallboard plants lock in decade-long FGD offtake ahead of utility retirement deadlines. |
| Backward Integration | Knauf and Saint-Gobain operate captive dewatering facilities eliminating merchant feedstock markups. |
| Capacity Expansion | Phosphogypsum processing buildout in Florida diverts fertilizer by-product from landfill liabilities. |
| Joint Venture | Utility-wallboard partnerships share dryer-kiln hybrid capital costs across feedstock processing. |
| Green Certification Program | REACH batch-level heavy-metal documentation enables cross-border construction-grade gypsum trade. |
Study Parameters
Direct dialogue with utility plant managers, wallboard procurement directors, agricultural co-op agronomists, and EPA regulatory affairs specialists combined with customs trade data, ACC construction material reports, SEC 10-K filings, and state-level coal combustion residual databases. Bottom-up feedstock volume estimates triangulated against top-down wallboard production capacity.
Segmented outputs across feedstock type, application channel, and end-user procurement behavior modeled over the projection horizon. CAGRs derived from utility retirement schedule probability-weighting and phosphogypsum processing capacity buildout curves. Forecast inputs incorporated EPA coal combustion residual rule implementation timing and EU landfill diversion target enforcement.
The model assumes a particular technology adoption path; alternative pathways for carbon-capture mineralization integration would alter the outlook. Forecasts reflect assumptions regarding utility decarbonization timeline adherence and REACH heavy-metal threshold stability. Material deviation in EPA reclassification proceedings or MEE dual carbon goal enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market