
 Global Cholera Vaccines Market | 2026-2036
Global Cholera Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cholera Vaccines Market Foresight
Bangladesh is rewriting regional supply security through expanded bulk antigen manufacturing and local formulation capacity. EuBiologics Co., Ltd. anchors Korean export volumes through dedicated cholera vaccine production lines. Sanofi S.A. leverages its established tropical disease portfolio to sustain institutional procurement relationships across endemic zones. Valneva SE specializes in traveler-focused distribution through regulated travel clinic networks in Europe and North America.
Cholera vaccines are sterile biological preparations containing killed or live attenuated Vibrio cholerae strains, formulated for oral or parenteral administration to induce protective mucosal and systemic immunity against toxigenic serogroups O1 and O139. Oral cholera vaccine dominates procurement volumes due to thermostable formulation advantages and ease of mass administration in resource-limited settings. Inactivated vaccine occupies the stable core of WHO prequalified stockpiles, while live attenuated vaccine segments attract interest for single-dose convenience in traveler vaccination channels. Public health agencies represent the deepest margin pool given multi-year tender structures and volume commitments through Gavi and PAHO revolving funds.
WHO prequalification requirements and national regulatory authority inspections in India, South Korea, and EU member states shape manufacturing standards and market access timelines for producers. FDA oversight applies to US traveler vaccine indications, while EMA centralized procedures govern European marketing authorizations for imported products. Stakeholders must monitor evolving WHO strategic advisory group recommendations on dose-sparing regimens and fractional dosing protocols, as these directly alter procurement economics and manufacturing capacity planning across supplier networks.
Market Dynamics
Oral cholera vaccine procurement is consolidating around WHO prequalification status, creating a bifurcation between qualified suppliers serving Gavi-funded stockpiles and non-qualified manufacturers locked into domestic tender markets with fragmented purchasing power.
Growth Catalysts
- Sub-Saharan African stockpile expansion:Public health agencies in Ethiopia, Nigeria, and the Democratic Republic of Congo are scaling multi-year procurement commitments through Gavi and PAHO revolving funds, anchoring demand visibility for qualified manufacturers.
- India's PLI biotechnology scheme:Domestic fill-finish capacity expansion under the Production Linked Incentive scheme is reducing import dependency for bulk antigen and enabling regional supply hub formation.
- Thermostable formulation advances:Cold-chain-independent oral vaccines are unlocking last-mile distribution in conflict zones and remote riverine settlements where refrigeration infrastructure remains absent.
Market Restraints
- Single-source bulk antigen dependency:Concentrated Vibrio cholerae strain banking in Korean and European reference laboratories creates supply vulnerability for manufacturers lacking captive seed stock.
- FDA traveler indication barriers:Extended clinical trial requirements for US marketing authorization limit revenue diversification beyond institutional procurement channels.
- Serogroup O139 emergence:Epidemiological shifts toward non-O1 toxigenic strains are eroding protective coverage from O1-monovalent formulations in Southeast Asian estuarine zones.
Strategic Opportunities
- Fractional dosing protocol adoption:WHO Strategic Advisory Group of Experts recommendations for reduced-dose regimens in outbreak response are expanding effective coverage per manufactured lot.
- Travel clinic channel development:Regulated private vaccination networks in Germany, France, and the United Kingdom offer premium pricing escape from tender-driven margin compression.
- Bangladesh manufacturing localization:Expanded bulk antigen production and local formulation capacity in Dhaka industrial zones are positioning the country as a regional export hub for South Asian endemic markets.
Industry Challenges
- WHO prequalification timeline compression:Inspection backlogs at national regulatory authorities in India and South Korea are extending market access delays for new manufacturing entrants.
- Clinical endpoint standardization gaps:Disparate immunogenicity correlates of protection across serogroups are complicating trial design and regulatory dossier preparation for bivalent candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cholera Vaccines Market |
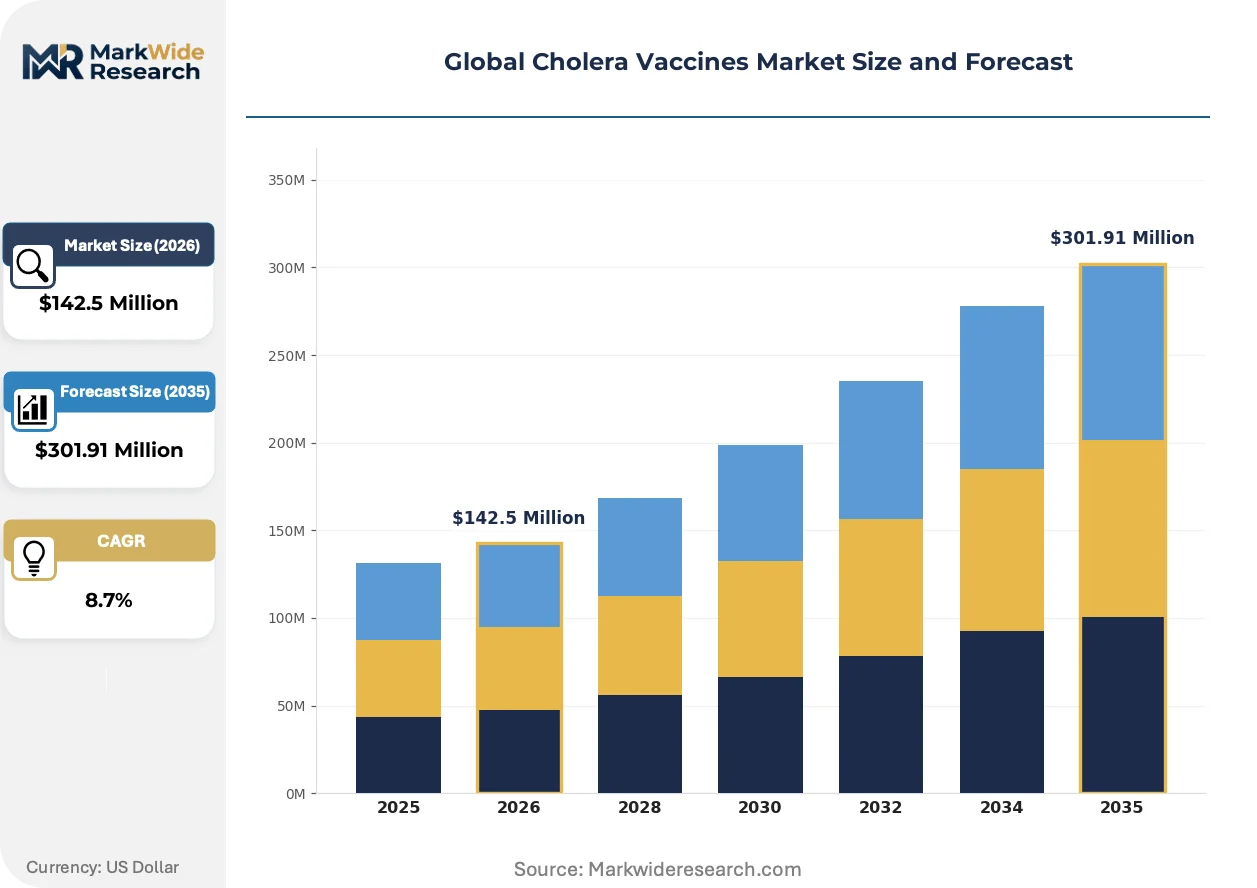
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Oral Cholera Vaccine, Injectable Cholera Vaccine, Live Attenuated Vaccine, Inactivated Vaccine Indication: Pre-Exposure Prophylaxis, Post-Exposure Prevention, Outbreak Control, Endemic Areas Immunization, Traveler Vaccination End User: Public Health Agencies, Travel Clinics, Military Medical Facilities, Humanitarian Organizations Distribution Channel: Hospitals, Pharmacies, Government Immunization Programs, Non-Profit Organizations, Private Clinics |
| Companies Covered | PaxVax Inc., Shantha Biotechnics Limited, Valneva SE, Astellas Pharma Inc., Hilleman Laboratories, Sanofi S.A., EuBiologics Co., Ltd., Incepta Vaccine Ltd., Emergent BioSolutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cholera Vaccines Market Shifts & Advancements
Formulation science and procurement mechanics are converging to reshape competitive advantage, with thermostability and regulatory pathway efficiency displacing traditional scale economies as primary value drivers.
Lyophilized live attenuated platforms are collapsing the cold chain infrastructure requirement that has historically constrained campaign reach. Travel medicine providers in North American and European urban centers are adopting these single-dose formats for pre-departure consultation efficiency. The technology is collapsing distribution cost structures for manufacturers seeking premium channel penetration outside institutional tender systems.
WHO prequalification pathway streamlining is compressing time-to-market for qualified manufacturers. The revised assessment framework prioritizes manufacturing consistency over redundant clinical efficacy demonstrations for established oral platforms. Bangladeshi and Korean producers with existing EMA or FDA inspections are leveraging mutual recognition agreements to accelerate dossier review timelines.
Humanitarian procurement consolidation is compressing supplier rosters toward multi-year framework agreement holders. Médecins Sans Frontières and International Medical Corps are shifting from spot purchases to pooled demand commitments through the WHO-managed International Coordinating Group stockpile mechanism. This concentration is most visible in sub-Saharan African outbreak response campaigns where single-source supply contracts now dominate emergency deployment logistics.
Global Cholera Vaccines Market Segmentation
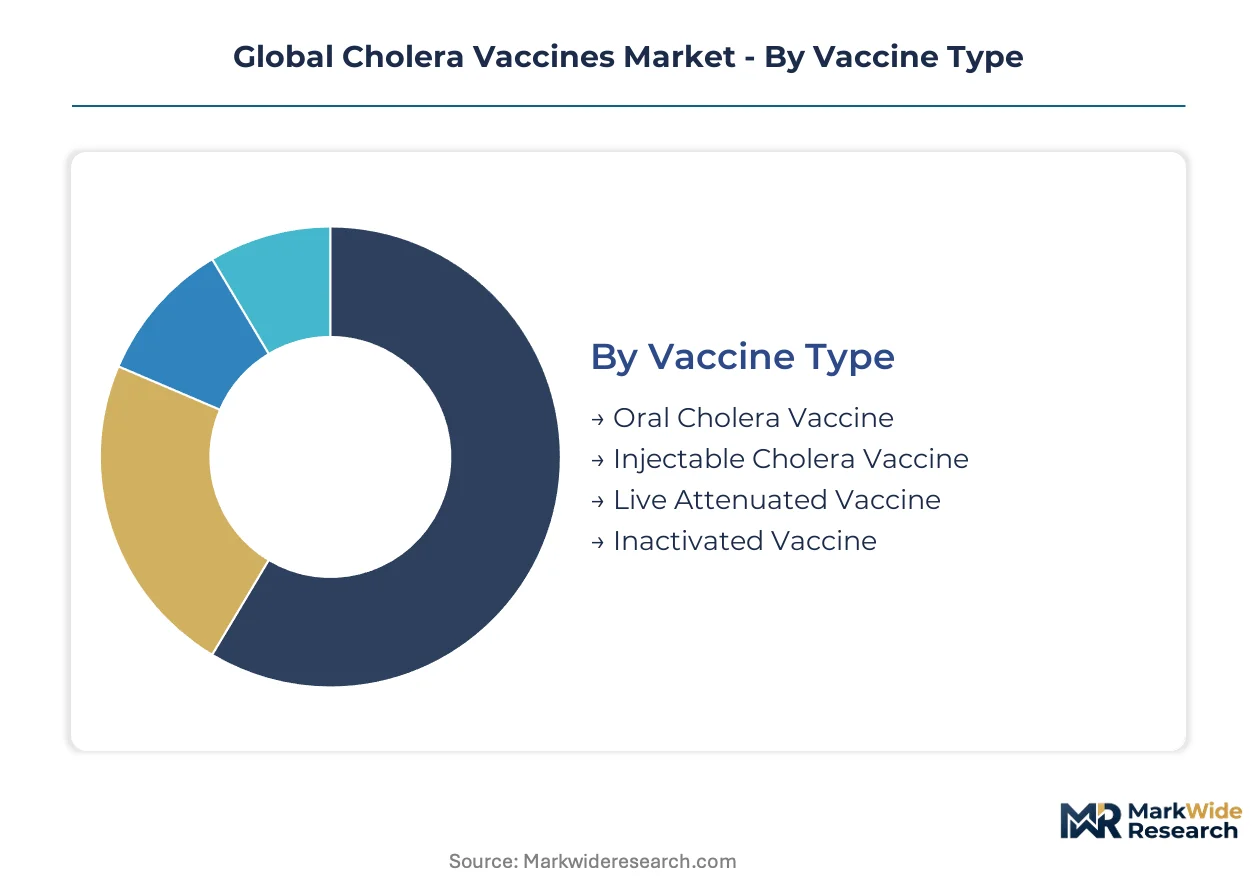
Segmentation in the cholera vaccines market reveals how procurement economics, regulatory pathways, and distribution infrastructure create divergent margin structures across product formats and customer channels. Manufacturers must align production scale and cold-chain capabilities to the specific service intensity each segment demands.
Vaccine Type:
After-sales service intensity varies sharply across vaccine formats, with lyophilized live attenuated platforms requiring minimal cold-chain support while bulk liquid inactivated formulations demand continuous temperature monitoring through last-mile deployment.
- Oral Cholera Vaccine:Thermostable liquid or lyophilized formulations containing killed or live attenuated Vibrio cholerae strains enable mass administration without injection equipment. Demand concentrates in Bangladesh and sub-Saharan African outbreak zones where WHO prequalified stockpiles sustain multi-year procurement through Gavi and PAHO revolving funds.
- Inactivated Vaccine:Killed whole-cell preparations formulated with or without B-subunit comprise the stable core of institutional procurement, offering established immunogenicity correlates and regulatory dossiers. Bangladesh's expanding bulk antigen manufacturing and Dhaka-based formulation capacity are reducing regional import dependency for this segment.
- Live Attenuated Vaccine:Single-dose oral platforms eliminate cold-chain infrastructure requirements and unlock traveler vaccination channels in North American and European urban centers.
- Injectable Cholera Vaccine:Parenteral formulations persist in limited military and specialized healthcare settings requiring rapid seroconversion documentation.
By volume, Oral Cholera Vaccine leads institutional procurement. By growth pace, Live Attenuated Vaccine is gaining share fastest through private travel clinic expansion.
Indication:
Cost tier differentiation separates mass public health deployment from premium-priced traveler prophylaxis, with outbreak response campaigns operating on emergency procurement timelines that compress supplier margins.
- Outbreak Control:Emergency deployment protocols require immediate stockpile release and rapid field distribution to contain epidemic spread in conflict zones and refugee settlements. Ethiopia, Nigeria, and the Democratic Republic of Congo are scaling multi-year framework agreements through the WHO-managed International Coordinating Group mechanism.
- Traveler Vaccination:Pre-departure immunization for tourists and business travelers to endemic regions commands premium pricing through regulated private clinic networks in Germany, France, and the United Kingdom.
- Pre-Exposure Prophylaxis:Systematic immunization of high-risk occupational groups including healthcare workers and water utility staff in endemic urban centers.
- Endemic Areas Immunization:Recurring seasonal campaigns in riverine settlements and estuarine zones sustain the largest national programs.
- Post-Exposure Prevention:Ring vaccination strategies deployed around confirmed case clusters to interrupt transmission chains.
Outbreak Control absorbs the highest absolute doses. Traveler Vaccination delivers the steepest per-dose revenue trajectory.
End User:
Customer type determines tender structure complexity, with public health agencies negotiating multi-year volume commitments while humanitarian organizations operate on emergency spot purchasing cycles.
- Public Health Agencies:Government ministries and national immunization programs anchor procurement volumes through Gavi-funded stockpiles and PAHO revolving fund mechanisms, with Bangladesh sustaining the largest recurring national program.
- Humanitarian Organizations:Médecins Sans Frontières and International Medical Corps are consolidating demand through pooled commitments to the WHO-managed International Coordinating Group stockpile.
- Travel Clinics:Regulated private vaccination networks in Europe and North America offer margin escape from tender-driven pricing compression.
- Military Medical Facilities:Defense procurement channels require rapid deployment capabilities and documented seroconversion for force protection.
Public Health Agencies command procurement volume leadership. Humanitarian Organizations are expanding most quickly through pooled demand consolidation.
Distribution Channel:
Supply concentration shapes channel access, with government immunization programs controlling bulk allocation while non-profit organizations manage last-mile distribution in infrastructure-constrained settings.
- Government Immunization Programs:National health ministries and sub-national authorities administer mass campaigns through fixed sites and mobile outreach teams, with India's PLI biotechnology scheme enabling domestic fill-finish capacity expansion.
- Non-Profit Organizations:International Medical Corps and similar entities operate cold-chain-independent distribution networks reaching remote riverine settlements and conflict-affected zones.
- Hospitals:Tertiary care facilities manage severe case treatment and targeted immunization of high-risk inpatients.
- Pharmacies:Retail channels support traveler vaccination access in urban centers with established regulatory oversight.
- Private Clinics:Specialized travel medicine providers in European and North American cities deliver premium-priced pre-departure consultations.
Government Immunization Programs dominate dose volume. Non-Profit Organizations are climbing the fastest through emergency response network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
WHO prequalification pathways and national regulatory authority inspections in India, South Korea, and EU member states anchor manufacturing standards and market access timelines for oral cholera vaccine producers.
Bangladesh
Recurring seasonal outbreaks sustain the largest recurring national immunization program globally. The country's expanding bulk antigen manufacturing and local formulation capacity in Dhaka industrial zones are reducing regional import dependency. Domestic fill-finish operations position Bangladesh as a regional export hub for South Asian endemic markets.
India
Domestic fill-finish capacity expansion under the CDSCO-oversight Production Linked Incentive biotechnology scheme is reducing import dependency for bulk antigen. Shantha Biotechnics Limited and Incepta Vaccine Ltd. anchor manufacturing presence through WHO prequalification-aligned facilities. The PLI scheme incentivizes regional supply hub formation for sub-Saharan African stockpile procurement.
South Korea
EuBiologics Co., Ltd. anchors Korean export volumes through dedicated cholera vaccine production lines and captive Vibrio cholerae strain banking. MFDS inspections and EMA mutual recognition agreements accelerate dossier review timelines for qualified manufacturers. Seoul-based reference laboratory concentration creates supply vulnerability mitigation through diversified seed stock repositories.
United States
FDA oversight applies to traveler vaccine indications with extended clinical trial requirements limiting revenue diversification beyond institutional procurement channels. PaxVax Inc. and Emergent BioSolutions Inc. occupy positions within the regulated private vaccination network segment. Premium pricing through travel clinic channels offers margin escape from tender-driven compression.
France
Valneva SE specializes in traveler-focused distribution through regulated travel clinic networks across European urban centers. ANSM marketing authorization procedures and EMA centralized pathways govern European import product registrations. Lyon-based formulation science capabilities support lyophilized live attenuated platform development for cold-chain-independent deployment.
Global Cholera Vaccines Market Competitive Landscape
Capability concentration sits with WHO prequalified manufacturers possessing captive strain banks and thermostable formulation expertise; scale advantage sits with diversified pharmaceutical conglomerates leveraging tropical disease portfolio breadth. The market structures around three tiers: prequalified stockpile suppliers serving Gavi-funded procurement, domestic tender-locked manufacturers with fragmented purchasing power, and traveler-focused specialists commanding premium clinic pricing. Strategic archetypes include institutional procurement anchors, regional export hub developers, and private channel premiumizers. Dominant competitive moves encompass manufacturing localization in Dhaka and Mumbai industrial zones, and lyophilized platform licensing for cold-chain collapse.
Among Korean and European fabricators, EuBiologics Co., Ltd. and Valneva SE exemplify divergent archetype positioning— the former anchoring bulk antigen export volumes, the latter occupying traveler vaccination premium channels. Sanofi S.A. represents the diversified conglomerate tier with tropical disease portfolio breadth sustaining institutional relationships. These three entities collectively illustrate how regulatory pathway efficiency and formulation thermostability displace traditional manufacturing scale as primary competitive moats in oral cholera vaccine supply.
| Leading Market Players |
|---|
| PaxVax Inc. |
| Shantha Biotechnics Limited |
| Valneva SE |
| Astellas Pharma Inc. |
| Hilleman Laboratories |
| Sanofi S.A. |
| EuBiologics Co., Ltd. |
| Incepta Vaccine Ltd. |
| Emergent BioSolutions Inc. |
| Others |
Supply & Pricing Matrix
Bulk antigen concentration in Korean reference laboratories and Dhaka industrial zones funnels margin capture toward WHO prequalified manufacturers with captive strain banking, while non-qualified competitors absorb tender-driven compression in fragmented domestic markets.
Pricing Analysis
Price spreads between European travel clinic channels and sub-Saharan African institutional tenders exceed fourfold, with Valneva SE commanding premium positioning through ANSM-regulated private networks while Gavi-funded procurement anchors contract-based long-term offtake structures. Three-tier pricing structure across premium traveler, standard institutional, and economy outbreak-response levels differentiates on regulatory certification tier and cold-chain service bundling. Pricing pressure stems from multi-year framework agreement consolidation through the WHO-managed International Coordinating Group mechanism. Humanitarian organizations exhibit highest price sensitivity due to emergency spot purchasing cycles, while regulated travel clinics in Germany and France demonstrate lowest sensitivity.
Supply Chain Analysis
Export control regimes governing Vibrio cholerae strain banking and live attenuated platform technology limit technology transfer to non-reference laboratories, constraining supply base expansion. Manufacturing gravity centers on Bangladesh, South Korea, and India, with Dhaka industrial zones and Seoul-based facilities anchoring bulk antigen output. Seed stock repositories, lyophilization capacity, and B-subunit adjuvant supply constitute critical input dependencies. Single-source vulnerability in Korean strain banking creates systemic exposure to regulatory inspection backlogs at MFDS and CDSCO. Distribution runs through government immunization programs for institutional volume, with non-profit organizations managing last-mile deployment in infrastructure-constrained settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification pathway streamlining is collapsing time-to-market differentials and enabling platform economics where manufacturing consistency and regulatory dossier efficiency displace scale as primary competitive moats.
For Market Incumbents: Entrench position through backward integration into captive Vibrio cholerae strain banking and lyophilized platform licensing to collapse cold-chain dependency. Expand fill-finish capacity in Dhaka and Mumbai industrial zones to defend against emerging regional hub developers. Threat from fractional dosing protocol adoption erodes per-dose revenue, requiring volume commitment renegotiation with Gavi and PAHO revolving funds. For New Entrants and Emerging Players: Mid-tier domestic tender markets in Southeast Asian endemic zones represent the most penetrable entry point given lower WHO prequalification barriers and fragmented purchasing power. Travel clinic channel white space in Southern European urban centers offers premium pricing escape from tender compression. Go-to-market angle should leverage EMA mutual recognition agreements for accelerated dossier review. For Investors and Strategic Acquirers: Capital is best deployed toward manufacturers possessing thermostable formulation IP and existing EMA or FDA inspection records that enable WHO prequalification fast-tracking. Long-term viability hinges on five-to-ten year demand visibility from multi-year framework agreements. Signal to watch is WHO Strategic Advisory Group of Experts recommendations on dose-sparing regimens, which would compress manufacturing capacity requirements and reshape supplier economics.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | EMA and FDA inspection records accelerate dossier review timelines for qualified manufacturers. |
| Lyophilized Platform Licensing | Cold-chain-independent deployment unlocks last-mile distribution in conflict zones and remote settlements. |
| Manufacturing Localization | India's PLI biotechnology scheme incentivizes domestic fill-finish capacity for regional supply hub formation. |
| Fractional Dosing Protocol Adoption | WHO Strategic Advisory Group recommendations expand effective coverage per manufactured lot. |
| Travel Clinic Channel Development | ANSM-regulated private networks in France and Germany offer premium pricing escape from tender compression. |
Research Methodology
Initial hypotheses were tested against primary input from vaccine development executives, regulatory affairs leads at CDSCO and MFDS, Gavi procurement managers, and hospital formulary directors, and refined through secondary validation against WHO prequalification dossiers, EMA centralized procedure records, ClinicalTrials.gov entries, and Gavi annual reports. Bottom-up manufacturer capacity assessments were triangulated with top-down demand modeling from national immunization program procurement disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning vaccine type, indication, end user, and distribution channel, plus regional regulatory cluster as an industry-specific overlay. CAGRs were derived from modeled volume trajectories intersecting with pricing tier assumptions. Forecast inputs incorporated thermostable formulation adoption curves and WHO Strategic Advisory Group protocol recommendation timelines.
Macroeconomic conditions sit as an overlay; deviation in Gavi funding allocations, PAHO revolving fund liquidity, or Indian PLI scheme continuation would shift the trajectory. Forecasts reflect documented assumptions regarding dose-sparing protocol adoption rates and prequalification inspection timeline compression. Material shifts in WHO prequalification requirements or serogroup O139 epidemiological emergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Intravenous Solutions Market