
 Carbon Black in Lead-Acid Battery Market | 2026-2036
Carbon Black in Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Black in Lead-Acid Battery Market Analysis
Maintenance service agreements for battery fleet performance monitoring are restructuring how carbon black suppliers engage downstream customers. Birla Carbon leverages its integrated carbon black manufacturing network to secure long-term supply contracts with regional battery assemblers. Cabot Corporation anchors its competitive position through specialized conductive grades engineered for deep-cycle applications. Orion Engineered Carbons differentiates via technical service programs that optimize carbon black dispersion in paste formulations.
Carbon black in lead-acid batteries constitutes a nano-structured carbon additive, typically furnace black with 20-50 nm primary particle size and 50-150 m²/g surface area, manufactured through partial combustion of hydrocarbon feedstocks to enhance electronic conductivity in negative active material. Its primary industrial purpose centers on reducing internal resistance, suppressing sulfation, and extending cycle life under partial state-of-charge operation. Traditional flooded batteries retain dominant volume share, though AGM segments command superior margin pools due to stricter vibration resistance requirements in commercial vehicle applications. Energy storage applications within the application dimension represent the fastest-growing structural category, driven by grid-scale battery deployments requiring enhanced charge acceptance.
EPA regulations under the Clean Air Act govern carbon black manufacturing emissions, while OSHA standards limit workplace respirable exposure during battery plate production, collectively elevating compliance costs for integrated producers. REACH registration requirements in Europe constrain import pathways for non-compliant carbon black grades, reshaping supplier qualification protocols for battery manufacturers serving EU markets. Stakeholders must monitor evolving carbon footprint disclosure mandates, as Scope 3 emissions tracking threatens to reposition supply chain preferences toward regional producers with verified lifecycle data.
Market Dynamics
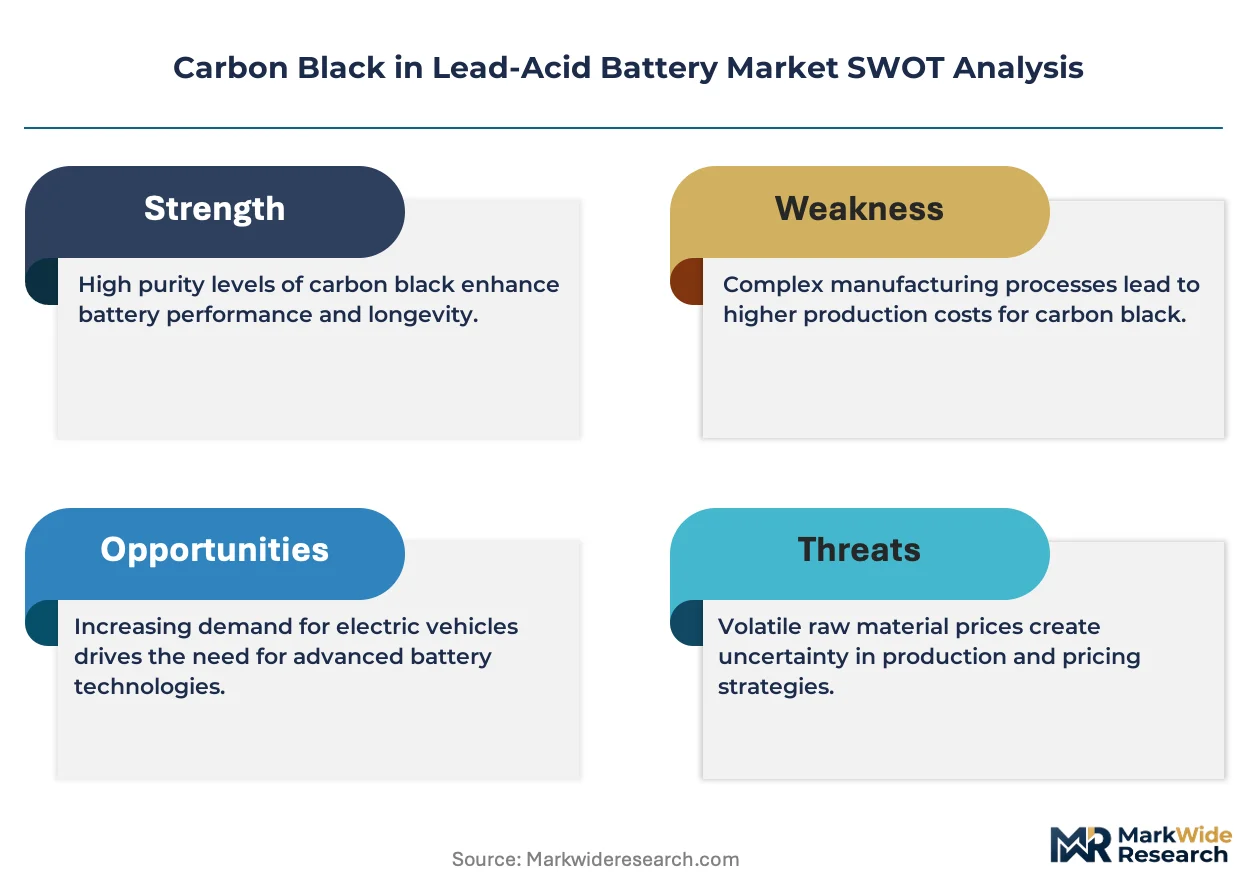
EU Battery Regulation mandates are forcing carbon black suppliers to redesign additive formulations for closed-loop recyclability, compressing qualification timelines and fragmenting supplier tiers between compliant and non-compliant producers.
Growth Catalysts
- EU Battery Regulation recyclability mandates:Battery manufacturers serving European markets must source additives compatible with hydrometallurgical recovery processes, creating qualified supplier preference for reformulated carbon black grades.
- Grid-scale energy storage deployments:Utility-scale lead-acid installations for frequency regulation and backup power require enhanced charge acceptance, driving specification upgrades to high-surface-area conductive additives.
- China's vehicle electrification pipeline:Domestic production of start-stop batteries and mild-hybrid systems concentrates demand for advanced negative active material formulations in Shandong and Jiangsu manufacturing clusters.
Market Restraints
- Feedstock cost volatility:Carbon black production depends on residual fuel oil and coal tar derivatives, exposing margin stability to crude oil price swings and refinery output fluctuations.
- Supplier concentration in carbon black manufacturing:Five integrated producers control over seventy percent of furnace black capacity, creating bottleneck risk for battery-grade material allocation during supply shocks.
- Lithium-ion substitution in motive power:Forklift and material handling equipment fleets are transitioning to lithium iron phosphate systems, eroding the addressable market for deep-cycle lead-acid applications.
Strategic Opportunities
- India's automotive battery localization:PLI scheme incentives for advanced chemistry cell manufacturing extend to lead-acid supply chain components, opening qualification pathways for carbon black suppliers establishing technical service presence.
- Carbon footprint disclosure differentiation:Battery OEMs responding to CSRD reporting requirements are prioritizing suppliers with verified Scope 3 emissions data, creating positioning advantage for producers with lifecycle assessments.
- Recycled content integration:Pyrolysis-derived carbon black from end-of-life tire processing is achieving battery-grade purity thresholds, enabling circular feedstock claims for sustainability-positioned product lines.
Industry Challenges
- Paste formulation technical expertise gap:Battery manufacturers lack in-house dispersion optimization capability, requiring carbon black suppliers to embed application engineers at customer facilities.
- REACH registration compliance timelines:Non-European producers face eighteen-month qualification windows for new carbon black grades, delaying market entry and locking in incumbent positions.
- Integration complexity with automated plate production:High-speed pasting lines demand consistent additive batch-to-batch performance, punishing suppliers with quality variation in furnace operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Black in Lead-Acid Battery Market |
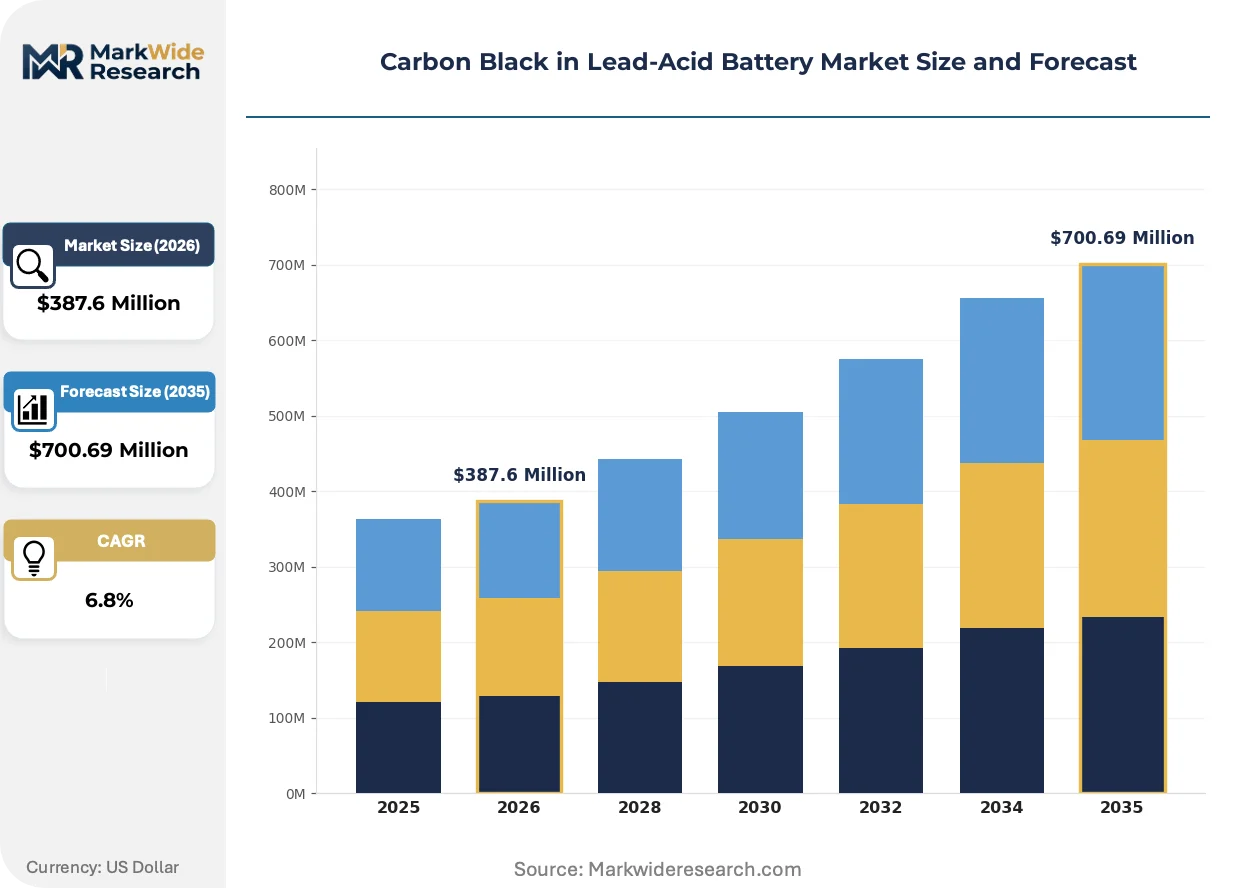
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, AGM, Gel, Enhanced Flooded End User: Automobile, UPS, Renewable Energy, Telecommunications Application: Starting, Lighting, Ignition, Energy Storage Technology: Valve-Regulated, Flooded Lead-Acid, Gel Technology, Enhanced Technology |
| Companies Covered | Birla Carbon, Cabot Corporation, Orion Engineered Carbons, Denka, Imerys, Mitsubishi Chemical, SGL Carbon, Continental Carbon, IsraZion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Black in Lead-Acid Battery Market Emerging Trajectories
Reformulation pressures from sustainability mandates and performance requirements are reshaping carbon black specification roadmaps, with technical service intensity emerging as the primary competitive differentiator.
Surface-oxidized carbon black variants with enhanced hydrophilicity are overtaking standard furnace grades in AGM battery applications. European commercial vehicle battery assemblers have accelerated qualification of these modified additives since 2023. The shift is compressing margins on commodity conductive grades while rewarding suppliers with in-house surface chemistry capability.
REACH registration requirements for carbon black imports into the European Union have tightened substance data submission protocols. Battery manufacturers now demand full dossier transparency from additive suppliers to satisfy downstream compliance audits. This regulatory friction has redirected sourcing preferences toward European-based carbon black producers with established registration histories.
Long-term paste formulation service contracts are displacing transactional spot purchasing in the aftermarket battery segment. Regional battery assemblers in Southeast Asia are bundling technical support with material supply to secure formulation consistency. This bundling pattern is most pronounced in Indonesia and Vietnam, where local producers lack independent R&D infrastructure.
Carbon Black in Lead-Acid Battery Market Segmentation
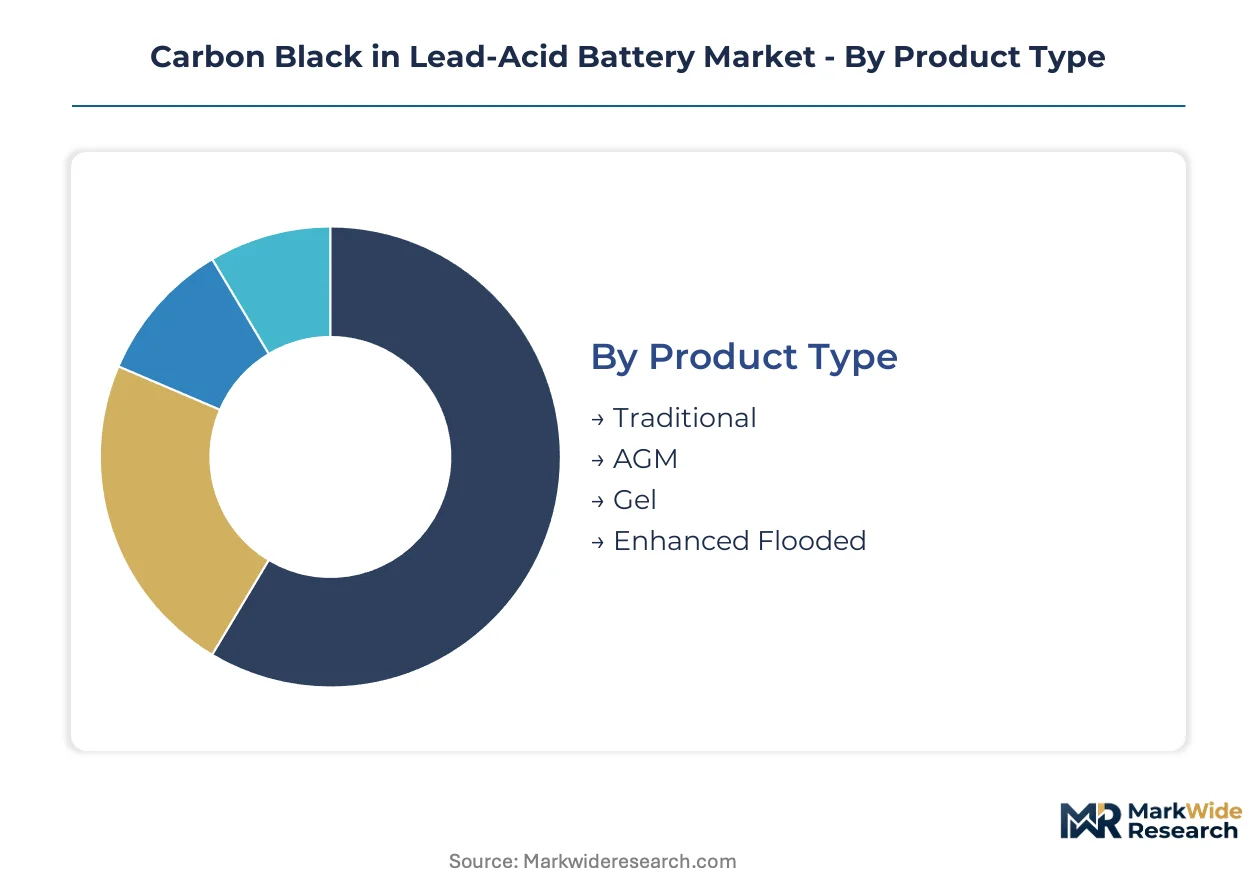
Carbon black specification requirements diverge sharply across battery architectures, with paste formulation chemistry dictating surface area targets and dispersion protocols. Manufacturers must align additive portfolios against distinct performance envelopes rather than treating conductive carbon as a commodity input.
Product Type:
Standardization dominates flooded formats while AGM and gel systems demand customized surface chemistry modifications.
- Traditional:Conventional flooded lead-acid batteries utilize standard furnace black with 50-80 m²/g surface area for basic conductivity enhancement in negative active material. Demand concentrates in aftermarket automotive replacement channels across India and Southeast Asia where cost sensitivity limits specification upgrades. Sulfation suppression remains the primary functional driver rather than cycle life extension.
- AGM:Absorbent glass mat separators require surface-oxidized carbon black variants with enhanced hydrophilicity to optimize electrolyte distribution and charge acceptance. European commercial vehicle OEMs have accelerated qualification of these modified additives to meet vibration resistance specifications in heavy-duty applications.
- Gel:Thixotropic silica gel electrolytes demand ultra-low moisture content carbon black with controlled surface functionalization to prevent particle agglomeration during paste mixing.
- Enhanced Flooded:EFB designs for start-stop vehicle systems utilize intermediate surface area grades balancing cost against partial state-of-charge cycling durability.
Most installed capacity flows through Traditional formats. Expansion is steepest in AGM.
End User:
Volume concentration sits with automotive OEMs while margin capture favors stationary power applications with technical service bundling.
- Automobile:Original equipment and aftermarket segments drive baseline demand for conductive additives, with start-stop system proliferation in China and Germany pulling specification upgrades toward enhanced negative active material formulations. Passenger vehicle electrification pipelines in these manufacturing clusters are reshaping carbon black surface area requirements.
- UPS:Uninterruptible power supply installations prioritize consistent float life performance over cycle depth, favoring standardized conductive grades with proven long-term stability in valve-regulated configurations.
- Renewable Energy:Grid-scale solar and wind storage deployments are climbing the fastest, with frequency regulation duty cycles demanding high-surface-area additives for rapid charge acceptance.
- Telecommunications:Remote base station backup power in Indonesia and Vietnam favors gel battery formats with specialized carbon black dispersion support from regional suppliers.
Automotive channels absorb the greatest additive tonnage. Renewable energy is gaining share fastest.
Application:
Starting function specifications are commoditized while energy storage applications reward technical differentiation.
- Starting:Cranking amp delivery requires minimal carbon black loading compared to deep-cycle designs, with paste formulations optimized for initial conductivity rather than long-term structural stability.
- Lighting:Auxiliary power applications in commercial vehicles utilize intermediate additive loadings balancing engine-off electrical draw against battery mass constraints.
- Ignition:Motorcycle and small engine batteries represent a price-sensitive segment where carbon black suppliers compete primarily on logistics reliability rather than technical specification.
- Energy Storage:Utility-scale installations and residential backup systems are expanding most quickly, with charge rate specifications driving adoption of high-structure conductive blacks in Shandong manufacturing clusters.
Starting applications retain the largest installed base. Energy storage is accelerating fastest.
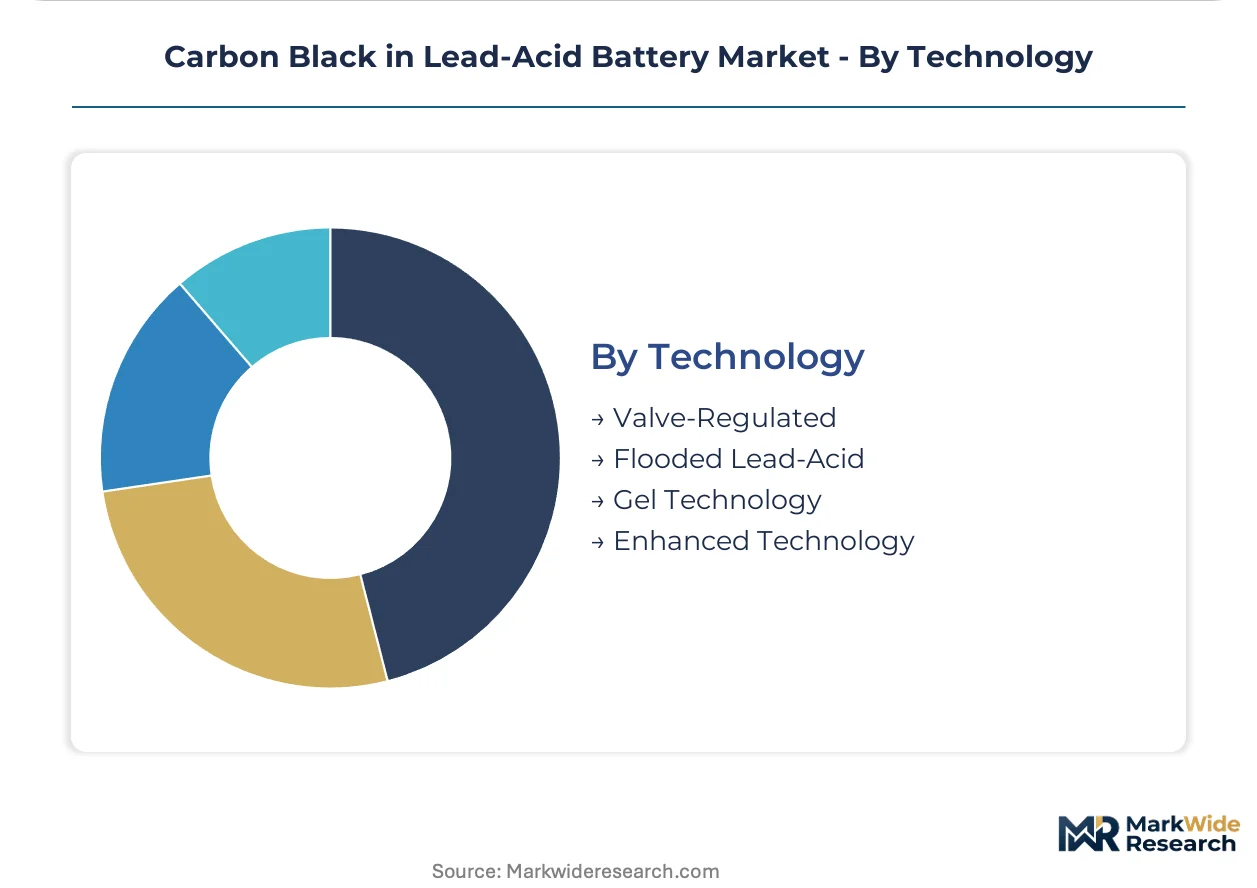
Technology:
Valve-regulated designs concentrate premium additive demand while flooded formats sustain commodity volume.
- Valve-Regulated:VRLA configurations require precisely controlled carbon black surface chemistry to manage oxygen recombination efficiency and minimize water loss, with European producers leading qualification protocols.
- Flooded Lead-Acid:Ventilated wet cell technology dominates replacement markets in India and Brazil where established supply chains favor conventional furnace black grades without surface modification.
- Gel Technology:Immobilized electrolyte systems demand specialized dispersion expertise from additive suppliers, with technical service contracts increasingly bundled with material supply.
- Enhanced Technology:EFB and advanced flooded designs for micro-hybrid vehicles utilize proprietary carbon black formulations developed through joint R&D programs between battery assemblers and conductive additive producers.
Flooded lead-acid technology processes the greatest additive volume. Enhanced technology is scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China processes substantially greater carbon black tonnage for lead-acid batteries than any other single country, while Germany's commercial vehicle sector drives the most demanding specification upgrades for surface-modified conductive additives.
China
Domestic production of start-stop batteries and mild-hybrid systems concentrates demand for advanced negative active material formulations. MIIT dual carbon goals are pressuring manufacturers to document Scope 3 emissions across additive supply chains. Shandong and Jiangsu manufacturing clusters host the densest concentrations of battery assemblers integrating high-surface-area carbon blacks.
Germany
Heavy-duty commercial vehicle OEMs specify AGM batteries with vibration-resistant performance envelopes. KBA type-approval requirements for commercial vehicle electrical systems mandate validated additive traceability. The industrial corridor between Stuttgart and Munich anchors qualification programs for surface-oxidized carbon black variants.
United States
Grid-scale energy storage deployments for frequency regulation require enhanced charge acceptance specifications. EPA Clean Air Act enforcement elevates compliance costs for carbon black manufacturing emissions. Texas and California utility markets are driving specification upgrades for high-structure conductive additives in stationary power applications.
India
Automotive aftermarket replacement channels absorb the greatest additive volumes across cost-sensitive segments. PLI scheme incentives for advanced chemistry cell manufacturing extend qualification pathways to lead-acid supply chain components. Tamil Nadu and Haryana production clusters are attracting technical service investments from regional carbon black suppliers.
Japan
Valve-regulated battery exports to Southeast Asian telecommunications markets demand consistent batch-to-batch additive performance. METI industrial standards govern carbon black purity thresholds for stationary power applications. The Kansai industrial zone maintains specialized dispersion expertise serving gel battery format producers.
Carbon Black in Lead-Acid Battery Market Vendor Landscape
Top-tier vendors anchor integrated manufacturing networks, while mid-scale specialists compete through technical service bundling. Five integrated producers control the majority of furnace black capacity, creating allocation bottleneck risk during supply shocks. Strategic archetypes include global carbon black conglomerates with battery-grade purification capabilities, regional specialists with embedded application engineering, and petrochemical-integrated producers leveraging feedstock access. Dominant competitive moves center on long-term paste formulation service contracts and backward integration into specialty feedstock processing.
Within the integrated producer tier, Birla Carbon, Cabot Corporation, and Orion Engineered Carbons exemplify contrasting geographic and capability positioning. Birla Carbon represents the Asian-integrated archetype with manufacturing density proximate to Chinese battery production clusters. Cabot Corporation anchors North American conductive grade development through specialized formulations for deep-cycle applications. Orion Engineered Carbons occupies the European technical service position, with qualification protocols aligned to REACH compliance requirements for battery manufacturers serving EU markets.
| Leading Market Players |
|---|
| Birla Carbon |
| Cabot Corporation |
| Orion Engineered Carbons |
| Denka |
| Imerys |
| Mitsubishi Chemical |
| SGL Carbon |
| Continental Carbon |
| IsraZion |
| Others |
Supply Flow & Price Mechanics
EU Battery Regulation recyclability mandates gate both qualified supply and premium-tier pricing access, forcing battery manufacturers to source reformulated carbon black grades compatible with hydrometallurgical recovery processes. This regulatory filter stratifies suppliers into compliant tiers commanding formulation service premiums versus commodity producers locked into spot-market price competition.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard furnace black grades while European surface-oxidized variants sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects REACH registration status, technical service bundling intensity, and verified Scope 3 emissions documentation. Cost compression in economy-tier flooded battery segments is intensifying because Indian and Southeast Asian assemblers prioritize logistics reliability over specification upgrades. Aftermarket automotive replacement channels exhibit the greatest price sensitivity, while German commercial vehicle OEMs demonstrate lowest sensitivity due to vibration resistance mandates.
Supply Chain Analysis
Reverse-logistics flows for end-of-life battery collection are creating regional feedstock pools for pyrolysis-derived carbon black, tightening circularity claims among sustainability-positioned producers. Manufacturing concentration centers on China, India, and Germany, with Shandong and Jiangsu clusters anchoring furnace black capacity proximate to battery assembly. Production draws from residual fuel oil, coal tar derivatives, and emerging tire pyrolysis streams, exposing margin stability to crude price volatility and refinery output fluctuations. Single-source vulnerability concentrates in furnace black purification capabilities controlled by five integrated producers. Distribution runs through long-term paste formulation service contracts displacing transactional spot purchasing, particularly in Indonesia and Vietnam where technical service bundling secures customer lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EU Battery Regulation closed-loop mandates forcing continuous additive reformulation and compressing supplier qualification timelines.
For Market Incumbents: Cement defensive positioning through backward integration into specialty feedstock processing and captive supply of surface-modified carbon black variants. Lock in German commercial vehicle OEMs via KBA-validated additive traceability protocols. Expand technical service engineering presence in Tamil Nadu and Haryana to capture PLI scheme incentives before regional specialists establish footholds. For New Entrants and Emerging Players: Begin with India's automotive aftermarket replacement channels where cost sensitivity limits incumbent specification upgrades and logistics reliability gaps create service bundling opportunities. Target gel battery format producers in Indonesia and Vietnam lacking independent R&D infrastructure. Lead with technical service contracts embedding application engineers at customer facilities rather than competing on commodity furnace black pricing. For Investors and Strategic Acquirers: Roll-up economics work for regional carbon black specialists with embedded application engineering because battery manufacturers lack in-house dispersion optimization capability and increasingly outsource paste formulation expertise. Five-to-ten year viability hinges on REACH registration compliance and verified lifecycle assessment data positioning. Monitor CSRD reporting requirement adoption rates among European battery OEMs as the signal for premium-tier supplier preference inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Feedstock Processing | Circular pyrolysis-derived carbon black from tire processing achieves battery-grade purity thresholds for sustainability claims. |
| Long-term Paste Formulation Service Contracts | Technical service bundling displaces spot purchasing in Indonesia and Vietnam where R&D infrastructure is limited. |
| REACH Registration Compliance Investment | ECHA substance data submission protocols redirect sourcing preferences toward European producers with established registration histories. |
| Technical Service Presence Expansion | Application engineers embedded at customer facilities address paste formulation expertise gaps among regional battery assemblers. |
| Joint R&D Programs for EFB Formulations | Proprietary carbon black development for micro-hybrid vehicle systems locks in OEM qualification pathways. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with carbon black plant managers, battery assembler procurement leads, technical R&D directors at additive suppliers, and aftermarket distribution channel partners with secondary validation against customs and trade data, SEC filings from integrated producers, ACC industry reports, and EPA Clean Air Act enforcement records. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Segment-weighting approaches distributed value and volume across product type, end user, application, and technology dimensions throughout the forecast period. CAGRs derived from elasticity modeling against lead-acid battery production forecasts, feedstock cost trajectories, and regulatory compliance timeline assumptions. Industry-specific inputs included MIIT dual carbon goal implementation schedules and KBA type-approval requirement propagation.
Several conditions sit outside the modeled scope, including abrupt lithium-ion substitution acceleration in motive power segments and geopolitical disruptions to hydrocarbon feedstock supply. Forecasts reflect documented assumptions about REACH registration timeline adherence and carbon footprint disclosure mandate adoption rates. Practitioners should monitor EU Battery Regulation secondary legislation developments and CSRD reporting phase-in schedules for early signals of supplier preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc Carbon Battery Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Marine Low-Voltage Battery Market
Batteries
North America Consumer Battery Market
Batteries
Silicon Battery Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Taiwan Battery Market
Batteries
Portable Battery Pack Market
Batteries
India Battery Cell Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Leisure Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
Advanced Batteries Market