
 Europe Battery Market | 2026-2036
Europe Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Battery Market Analysis
Capital-intensity divergence between fully integrated cell producers and pack assemblers is unwinding legacy competitive moats in the Europe battery sector. Northvolt leverages captive cathode production and Swedish hydropower to sustain cost positions that Asian incumbents struggle to match on the continent. LG Energy Solution anchors its Polish operations with established automotive customer relationships, while CATL competes through aggressive licensing of its cell-to-pack architecture to European OEMs seeking faster deployment timelines.
A battery is an electrochemical device storing and releasing energy through reversible redox reactions between electrodes separated by an electrolyte, with lithium-ion variants achieving energy densities exceeding 250 Wh/kg through layered oxide cathodes and graphite or silicon-composite anodes. Its primary commercial purpose is to decouple energy generation from consumption, enabling mobility electrification, grid stabilization, and portable power across industrial and consumer applications. Lithium-ion chemistry dominates product type dynamics due to its superior energy density and cycle life, though solid-state technology is attracting R&D investment as manufacturers seek to displace liquid electrolytes with ceramic or polymer conductors that eliminate thermal runaway risks. Among end users, electric vehicles command the largest revenue pool, while renewable energy storage represents the fastest-expanding application as wind and solar intermittency drives utility-scale battery procurement across the continent.
The EU Battery Regulation, REACH, and CE marking collectively reshape market access by imposing due diligence on raw material sourcing, mandating minimum recycled content thresholds, and standardizing safety testing protocols for cells entering European commerce. ECHA substance restrictions and the EU Green Deal's carbon border adjustments are forcing non-European suppliers to document supply chain emissions or face competitive exclusion from public procurement tenders. Stakeholders must monitor how delegated acts under the Battery Regulation specify performance criteria, as these technical details will determine which chemistries and manufacturing locations qualify for preferential treatment in European automotive supply chains.
Market Dynamics
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are restructuring procurement criteria across European automotive supply chains, forcing OEMs to requalify suppliers based on documented emissions and material provenance rather than unit cost alone.
Growth Catalysts
- EU Green Deal carbon border adjustments:The mechanism penalizes imported cells with unverified supply chain emissions, advantaging European producers with renewable-powered manufacturing and documented ESG credentials.
- Electric vehicle fleet electrification:Germany, France, and the Netherlands are absorbing lithium-ion capacity faster than regional cell production can expand, creating sustained demand-pull for gigafactory investment.
- Solid-state electrolyte R&D:Ceramic and polymer conductors eliminate thermal runaway risks while enabling higher energy densities, attracting capital from automotive OEMs seeking next-generation performance differentiation.
Market Restraints
- Raw material supply concentration:Cobalt and lithium refining capacity concentrates in non-European jurisdictions, exposing cell producers to geopolitical disruption and forced labor due diligence failures under EU Battery Regulation.
- Energy cost differentials:Swedish hydropower and Nordic grid decarbonization sustain cost positions that Continental European producers struggle to match without state subsidy support.
- Technical limitation of liquid electrolytes:Conventional lithium-ion architectures face inherent thermal management constraints that limit fast-charging rates and pack-level energy density gains.
Strategic Opportunities
- Poland's industrial corridor:Established automotive supplier networks and EU structural fund access position the country for mid-tier cell and module assembly serving Central European OEM plants.
- Cell-to-pack architecture licensing:OEMs seeking faster deployment timelines are adopting licensed designs that eliminate module housings and reduce pack complexity.
- Utility-scale renewable storage:Wind and solar intermittency across Iberia and the Nordics is driving procurement of grid-stabilization batteries outside traditional automotive channels.
Industry Challenges
- Electrochemical engineering talent scarcity:European universities produce insufficient graduates with expertise in solid-state interfaces and dry electrode coating processes required for next-generation manufacturing.
- REACH compliance timeline compression:Substance restriction notifications and safety data documentation requirements are extending product qualification cycles beyond automotive platform development windows.
- Legacy pack assembly retooling:Established module suppliers face stranded asset risk as cell-to-pack designs eliminate intermediate assembly steps and reshape supplier tiering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Battery Market |
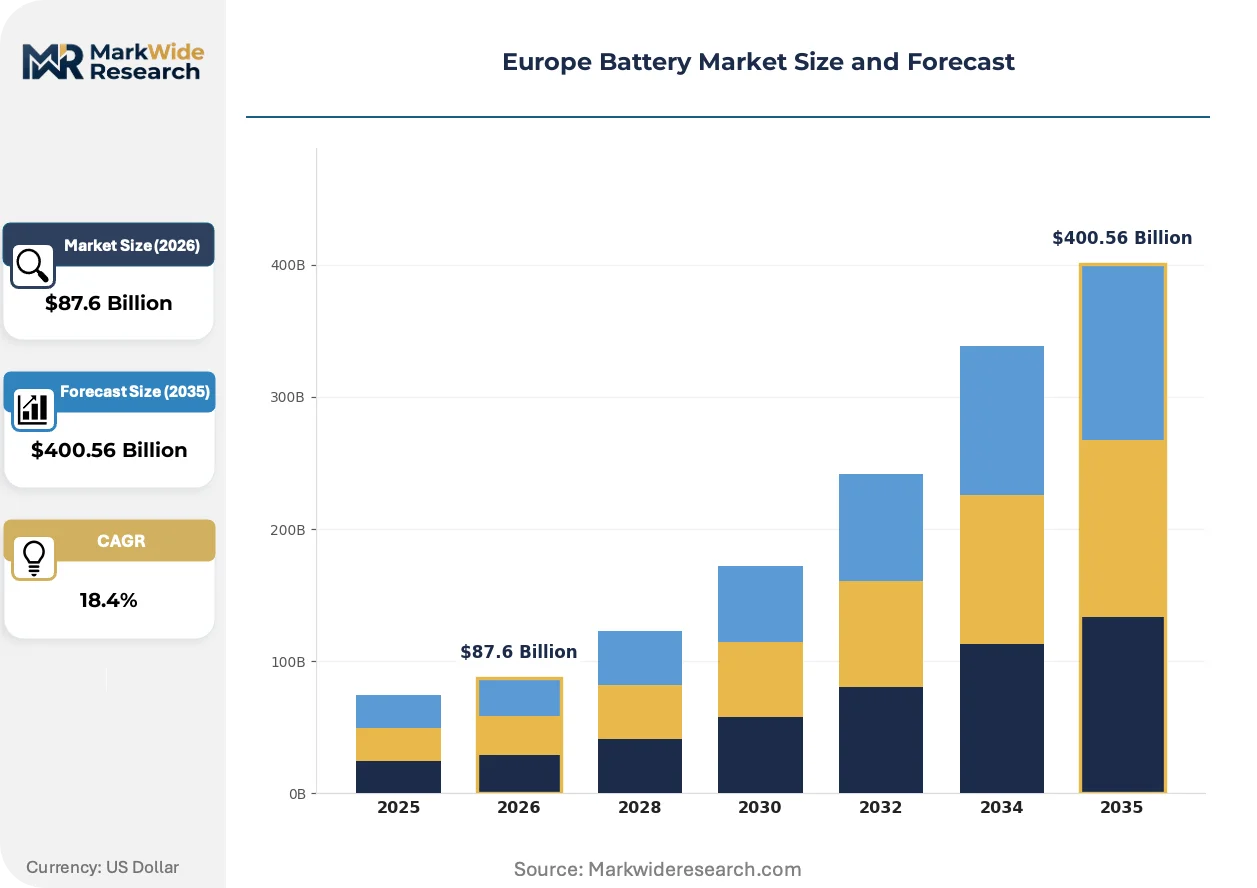
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead Acid, Nickel-metal Hydride, Flow Batteries End User: Electric Vehicles, Consumer Electronics, Industrial Equipment, Renewable Energy Technology: Solid-state, Lithium Polymer, Rechargeable, High-capacity Application: Energy Storage Systems, Automotive, Portable Devices, Grid Management |
| Companies Covered | Northvolt, Saft Groupe SA, LG Energy Solution, CATL, Samsung SDI, Panasonic Holdings Corporation, GS Yuasa, BYD Company, EVE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Battery Market Emerging Trajectories
Solid-state battery development, regulatory carbon accounting mandates, and procurement model centralization are converging to reshape competitive positioning across European cell manufacturing and automotive integration.
Silicon-composite anodes are displacing graphite in premium cell designs by accommodating higher lithium-ion storage capacity per unit mass. BMW and Mercedes-Benz cell qualification programs are accelerating silicon loadings from five to fifteen percent. This chemistry shift is displacing incumbent graphite suppliers from high-margin automotive contracts and compressing anode supply chain margins for non-specialized producers.
REACH substance restrictions and delegated acts under the EU Battery Regulation are mandating due diligence documentation for cobalt, lithium, and nickel sourcing. The industrial consequence is a bifurcation between suppliers with audited supply chains and those facing competitive exclusion from public procurement tenders. Automotive OEMs in Germany are most affected, responding by locking in long-term offtake agreements with certified European refiners.
Fleet procurement centralization is consolidating buying power among leasing companies and corporate mobility providers that specify performance guarantees and residual value protection. Direct OEM-fleet relationships are replacing fragmented dealer-channel battery sourcing. This concentration is most visible in the Netherlands, where corporate electrification mandates and tax incentives have created large-scale fleet operators with standardized technical specifications.
Europe Battery Market Segmentation
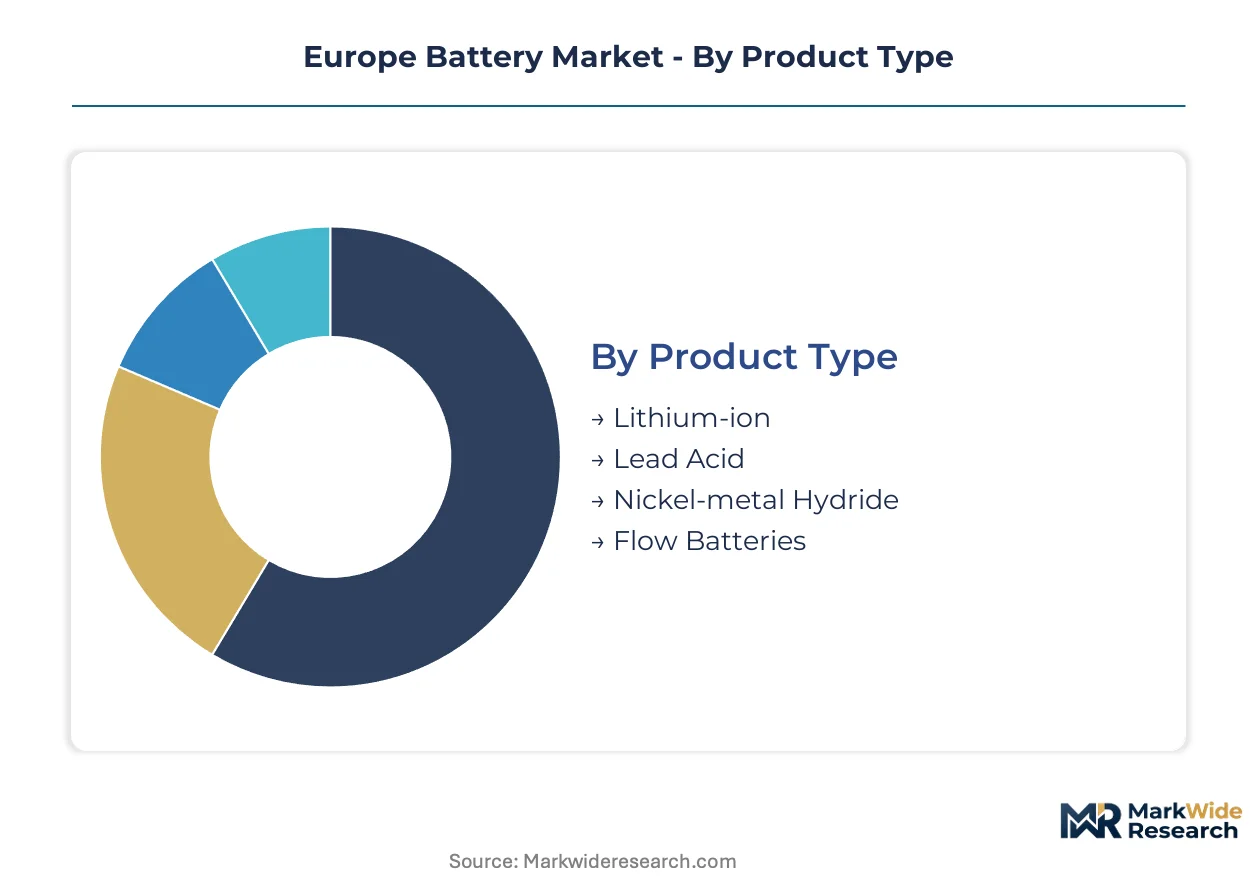
Segmentation in the Europe battery sector reveals how margin pools concentrate around chemistry choices and end-use applications. Understanding these divisions illuminates where procurement power sits and which technologies command premium positioning.
Product Type:
Margin concentration in European cell manufacturing tilts heavily toward advanced lithium-ion architectures with documented carbon footprints.
- Lithium-ion:Layered oxide cathodes paired with graphite or silicon-composite anodes deliver energy densities exceeding 250 Wh/kg. German automotive OEMs in Baden-Württemberg and Bavaria absorb the majority of regional capacity, driven by EU Battery Regulation mandates for recycled content and supply chain due diligence that favor established producers with audited sourcing.
- Lead Acid:Mature flooded and valve-regulated designs serve industrial backup power and commercial vehicle starting applications. Demand concentrates in Poland's manufacturing corridor where cost-sensitive fleet operators prioritize unit economics over energy density specifications.
- Nickel-metal Hydride:Hybrid electric vehicle battery packs retain niche relevance in legacy Toyota and Honda platforms assembled in the UK and France.
- Flow Batteries:Vanadium redox systems enable multi-hour grid storage for utility-scale renewable integration in Iberia and the Nordics.
Lithium-ion holds installed capacity across European gigafactories. Flow batteries are rotating up the share rankings as wind and solar intermittency drives long-duration storage procurement.
End User:
Application-specific requirements create divergent procurement patterns across mobility, consumer, industrial, and grid segments.
- Electric Vehicles:Battery electric and plug-in hybrid platforms from Volkswagen, BMW, and Mercedes-Benz dominate cell offtake agreements. French and Dutch fleet electrification mandates accelerate volume concentration among leasing companies with standardized performance specifications.
- Consumer Electronics:Smartphone, laptop, and power tool manufacturers source cylindrical and pouch cells through established Asian supply chains with CE marking compliance.
- Industrial Equipment:Forklift fleets and material handling systems in Germany's logistics hubs transition from lead-acid to lithium-ion for opportunity charging.
- Renewable Energy:Utility-scale wind and solar projects in Spain, Portugal, and Scandinavia procure containerized battery systems for grid stabilization services.
Electric Vehicles anchor current revenue concentration. Renewable Energy is climbing the fastest as national energy storage targets reshape procurement timelines.
Technology:
Manufacturing complexity and intellectual property protection determine which technology platforms sustain premium pricing.
- Solid-state:Ceramic and polymer electrolytes eliminate thermal runaway risks while enabling higher energy densities. BMW and Mercedes-Benz qualification programs in Germany are accelerating silicon loadings and solid-state interface engineering.
- Lithium Polymer:Flexible pouch formats serve consumer electronics and aerospace applications requiring form-factor customization.
- Rechargeable:Conventional liquid electrolyte architectures dominate volume production with established supply chain maturity.
- High-capacity:Silicon-anode and advanced cathode chemistries target premium automotive contracts with extended range specifications.
Rechargeable technology retains volume leadership. Solid-state is gaining share fastest as OEMs seek next-generation performance differentiation.
Application:
System integration requirements and customer procurement cycles segment the market across stationary and mobile use cases.
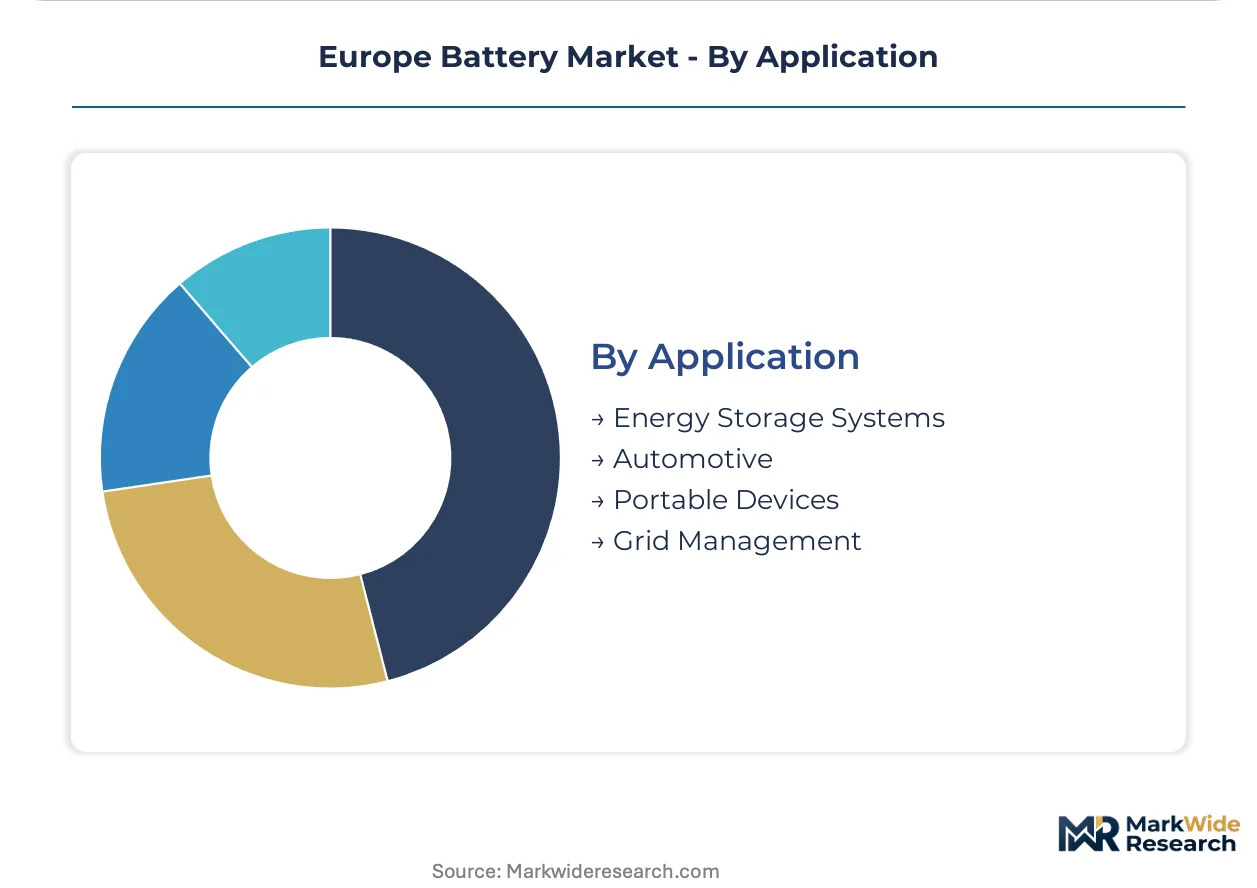
- Energy Storage Systems:Containerized lithium-ion and flow battery installations provide peak shaving and frequency regulation for grid operators. Spanish and Portuguese renewable clusters drive procurement outside traditional automotive channels.
- Automotive:Cell-to-pack architectures from CATL and licensed European designs are eliminating module housings and reducing pack complexity for German OEM platform rollouts.
- Portable Devices:Cylindrical and prismatic formats power consumer electronics with standardized UN 38.3 transportation testing compliance.
- Grid Management:Transmission system operators in the Netherlands and Germany procure ancillary services from distributed battery assets.
Automotive applications command the largest revenue pool. Energy Storage Systems are expanding most quickly as national renewable targets accelerate utility-scale deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in the Netherlands exhibit the highest price elasticity, squeezing margins on standardized lithium-ion packs, while German automotive OEMs absorb premium pricing for certified low-carbon cells without volume reduction.
Germany
Volkswagen, BMW, and Mercedes-Benz anchor cell offtake agreements that outstrip domestic gigafactory output. The EU Battery Regulation's carbon footprint declarations force requalification of Asian suppliers lacking documented renewable energy inputs. Baden-Württemberg and Bavaria concentrate cathode active material plants and cell assembly lines along the industrial corridor between Stuttgart and Munich.
Sweden
Northvolt leverages Swedish hydropower to sustain manufacturing cost positions below Continental European competitors. ECHA substance restrictions under REACH accelerate due diligence documentation for cobalt and nickel sourcing. Skellefteå hosts the flagship gigafactory complex, with Västerås anchoring precursor cathode active material production for integrated supply chain control.
Poland
Established automotive supplier networks in Lower Silesia and Silesia absorb module and pack assembly investment from Korean and Chinese cell producers. EU structural fund access subsidizes factory construction for mid-tier producers serving Central European OEM plants. LG Energy Solution anchors the Wrocław industrial zone with established automotive customer relationships.
France
Renault and Stellantis electrification platforms drive lithium-ion demand that exceeds domestic cell production capacity. The EU Green Deal's carbon border adjustment mechanism penalizes imported cells with unverified supply chain emissions. Dunkirk hosts emerging gigafactory investment targeting premium automotive contracts with documented low-carbon credentials.
Netherlands
Corporate fleet electrification mandates and tax incentives create large-scale leasing companies with standardized technical specifications and concentrated buying power. CE marking and UN 38.3 transportation testing compliance requirements filter non-specialized suppliers from public procurement tenders. Rotterdam's port infrastructure handles precursor chemical imports for distribution to Continental European cell plants.
Europe Battery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Europe battery sector. Northvolt exemplifies the fully integrated archetype with captive cathode production and renewable-powered manufacturing, while Asian incumbents compete through licensing architectures and established automotive relationships. Specialists concentrate in module assembly and pack integration, facing stranded asset risk as cell-to-pack designs eliminate intermediate steps. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term offtake agreements ahead of qualification completion.
Among the integrated European producers, Northvolt AB exemplifies the captive supply chain archetype with Swedish hydropower integration. LG Energy Solution Ltd. and Contemporary Amperex Technology Co., Limited (CATL) represent contrasting foreign entry strategies—established automotive relationships versus aggressive licensing of cell-to-pack architectures. Samsung SDI Co., Ltd. occupies a position within the premium-tier specialist segment. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic outcomes.
| Leading Market Players |
|---|
| Northvolt |
| Saft Groupe SA |
| LG Energy Solution |
| CATL |
| Samsung SDI |
| Panasonic Holdings Corporation |
| GS Yuasa |
| BYD Company |
| EVE |
| Others |
Supply Flow & Price Mechanics
Silicon-composite anode adoption displacing graphite chemistry simultaneously redistributes procurement geography toward Nordic hydropower corridors and compresses anode supply chain margins for non-specialized producers. Cell producers with captive silicon processing capabilities in Sweden and Norway capture pricing premiums while Asian graphite incumbents face margin erosion.
Pricing Analysis
After-sales service contracts and residual value guarantees drive lifetime value for European fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon cells with documented renewable inputs from commodity imports lacking EU Battery Regulation compliance. Cost compression in the standard tier is intensifying because Dutch leasing companies consolidate buying power through standardized technical specifications. Corporate fleet operators exhibit the highest price sensitivity, while German automotive OEMs absorb premium pricing for certified cells without volume reduction.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium chemical flows from Australian hard-rock mines and Chilean brine operations to Asian refining centers before European cell manufacturing. China, South Korea, and Japan anchor cathode active material production and precursor chemical supply. European cell producers draw from concentrated cobalt refining in the Democratic Republic of Congo and Indonesia, exposing supply chains to forced labor due diligence failures under EU Battery Regulation. Distribution runs through Rotterdam port infrastructure for precursor chemical dispersal to Continental European gigafactories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense where solid-state electrolyte technology threatens to displace conventional lithium-ion architectures. Incumbents must navigate qualification timelines for ceramic and polymer conductors that eliminate thermal runaway risks.
For Market Incumbents: Secure long-term offtake agreements with certified European refiners before REACH compliance timelines compress qualification windows. Lock in Swedish hydropower capacity additions to sustain cost positions against Continental competitors dependent on grid-subsidized renewable inputs. Solid-state R&D partnerships with BMW and Mercedes-Benz qualification programs represent the critical defensive lever against Asian licensing strategies.
For New Entrants and Emerging Players: Lead with utility-scale renewable storage procurement in Iberia and the Nordics, where wind and solar intermittency drives grid-stabilization battery demand outside automotive channel concentration. Poland's industrial corridor offers mid-tier cell and module assembly access through EU structural fund subsidization. Cell-to-pack architecture licensing to European OEMs seeking faster deployment timelines provides the most penetrable go-to-market angle against integrated incumbent capacity.
For Investors and Strategic Acquirers: The EU Battery Regulation's delegated acts on performance criteria reshape the acquisition landscape by determining which chemistries qualify for preferential automotive supply chain treatment. Five-to-ten year viability hinges on documented carbon footprint capabilities and recycled content processing infrastructure. Acquisition targets should exhibit captive cathode production or hydropower-tied manufacturing positions. The signal to watch is delegated act publication timing specifying technical thresholds for recycled content quotas.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Renault and Stellantis offtake contracts secure volume ahead of Dunkirk gigafactory completion. |
| Backward Integration | Northvolt's Västerås precursor cathode active material plant eliminates third-party chemical dependency. |
| Technology Licensing | CATL's cell-to-pack architecture licensing accelerates European OEM platform deployment timelines. |
| Green Certification Program | Swedish hydropower documentation satisfies EU Green Deal carbon border adjustment requirements. |
| Joint Venture | LG Energy Solution's Wrocław operations leverage established automotive customer relationships in Poland. |
Methodological Framework
Operator-level perspectives from cell production engineers, automotive platform procurement leads, utility storage project developers, and EPC contractors anchored the qualitative base. Primary interviews with Tier 1 supplier technical directors and OEM battery strategy executives combined with secondary validation from ECHA substance restriction databases, EU Battery Regulation delegated act drafts, and national energy storage procurement announcements. Bottom-up cell capacity buildout tracking and top-down automotive electrification mandate analysis provided triangulation across modeling approaches.
Sensitivity analysis on hydropower cost differentials and carbon border adjustment stringency framed the analytical approach across the projection horizon. Segmentation dimensions modeled include chemistry type, end-use application, technology platform, and regional manufacturing cluster. CAGRs derived from production capacity ramp schedules and automotive platform launch timelines incorporated silicon-anode adoption curves and solid-state qualification milestones as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Battery Regulation enforcement or accelerated solid-state commercialization would require recalibration. Forecasts reflect documented assumptions on renewable energy cost trajectories and raw material supply concentration. Practitioners should keep alternative scenarios live as delegated act technical specifications and carbon border adjustment implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
India Battery Cell Market
Batteries
North America Consumer Battery Market
Batteries
Battery Simulator Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Sweden Rechargeable Battery Market
Batteries
West Africa Battery Market
Batteries
United States Household Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Proton Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Battery Light Towers Market
Batteries
Military Battery Packs Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market