
 Absorbent Glass Mat (AGM) Battery Market | 2026-2036
Absorbent Glass Mat (AGM) Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbent Glass Mat (AGM) Battery Market Outlook
Original equipment supply contracts for European and North American automakers is rewriting how AGM battery manufacturers secure volume commitments. Clarios leverages its aftermarket footprint to sustain replacement cycle revenue across both passenger and commercial vehicle pools. GS Yuasa Corporation anchors Asian production capacity through dedicated facilities serving Japanese and Southeast Asian OEMs. EnerSys competes in industrial motive power segments where deep-cycle AGM reliability commands premium positioning.
Absorbent Glass Mat batteries contain electrolyte fully absorbed into a fiberglass mat separator, enabling operation in any orientation without spillage and delivering superior vibration resistance compared to flooded lead-acid designs. The primary industrial purpose centers on providing maintenance-free, high-rate discharge capability for applications where reliability and spatial flexibility outweigh pure energy density requirements. Valve Regulated Lead Acid products dominate current manufacturing output due to established cost structures and broad compatibility with existing charging infrastructure. Electric Vehicles application demand is expanding fastest among mobility segments, though Solar Power Systems installation represents the deepest margin pool where cycle-life specifications justify premium pricing.
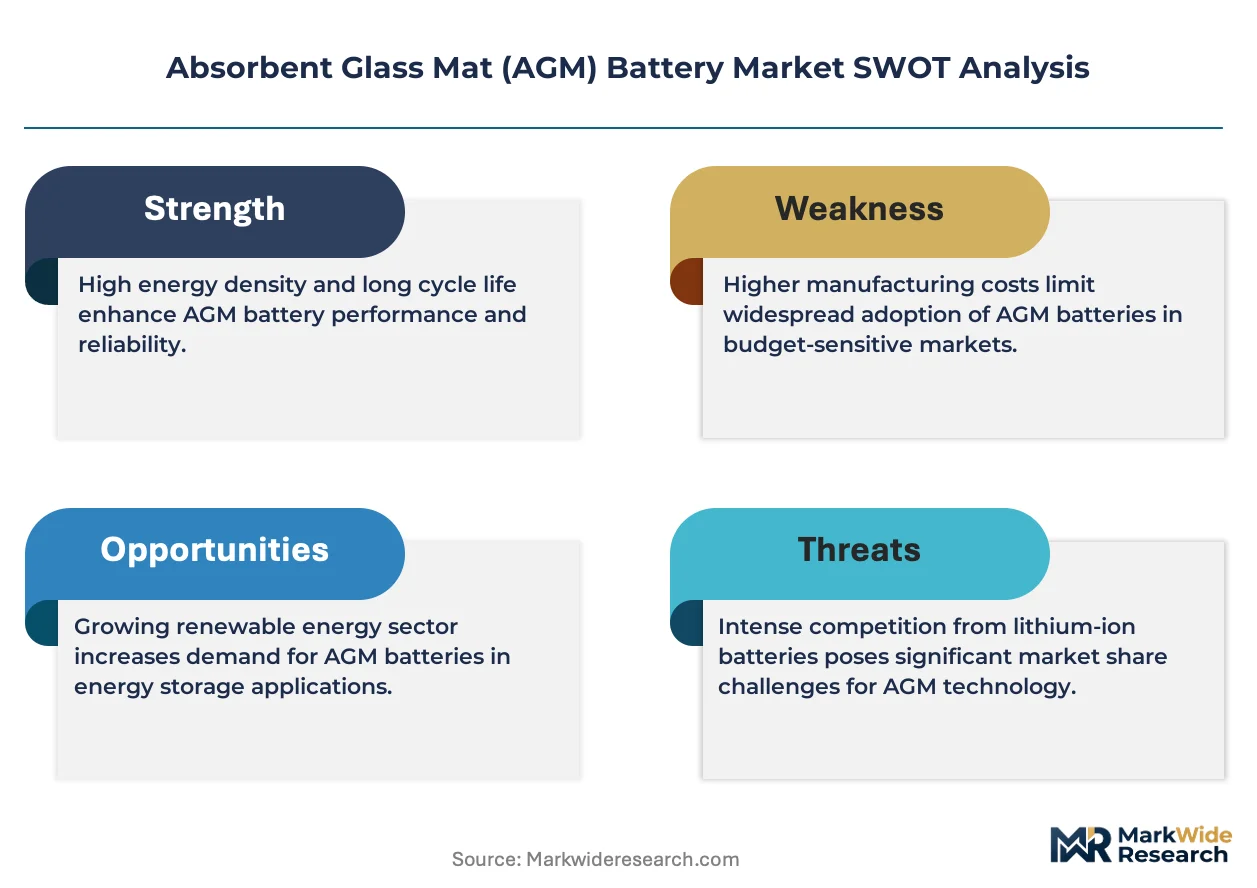
EPA tailpipe regulations and the EU Green Deal emissions framework directly mandate start-stop technology adoption, creating specification pull for AGM over conventional flooded alternatives in new vehicle platforms. NHTSA safety standards and ISO 9001 quality certifications further constrain market access for suppliers lacking validated production traceability. Stakeholders must monitor how solid-state and lithium-ion cost curves influence OEM dual-sourcing strategies in the decade ahead.
Market Dynamics
EPA tailpipe mandates and EU Green Deal emissions frameworks are forcing automakers to specify AGM batteries for start-stop systems, compressing the competitive window for conventional flooded lead-acid suppliers and rewiring procurement relationships across North American and European OEM supply chains.
Growth Catalysts
- EU Green Deal emissions mandates:The framework mandates CO2 reduction targets that require start-stop technology, creating specification pull for AGM batteries in new vehicle platforms across Germany, France, and Italy.
- Deep-cycle reliability demand:Solar power installations and telecom backup systems specify AGM for cycle-life performance in harsh environments where maintenance access is limited.
- German OEM concentration:Premium automakers headquartered in Stuttgart and Munich specify AGM for original equipment fitment, creating volume anchors that sustain regional production capacity.
Market Restraints
- Lead price volatility:Raw material input costs for lead and sulfuric acid fluctuate with commodity markets, compressing margin predictability for manufacturers without long-term smelter contracts.
- Lithium-ion substitution pressure:Declining cost curves for lithium iron phosphate cells threaten AGM's position in motive power and light electric vehicle applications where energy density carries premium weighting.
- Recycling infrastructure gaps:Closed-loop collection systems for spent AGM batteries remain underdeveloped in Southeast Asian markets, creating compliance friction with emerging extended producer responsibility frameworks.
Strategic Opportunities
- India automotive electrification:The PLI scheme for advanced chemistry cell manufacturing creates adjacent demand for AGM in hybrid transition vehicles before full battery electric penetration.
- Marine and RV aftermarket expansion:Dual-purpose AGM configurations are capturing share in recreational vehicle and boat electrical systems where vibration resistance and deep-cycling overlap.
- Data center UPS specification:Hyperscale facility operators in Virginia and Texas are standardizing on AGM for short-duration backup where runtime requirements favor lead-acid economics over lithium-ion capital intensity.
Industry Challenges
- ISO 9001 traceability requirements:OEM qualification timelines extend 18-24 months for new production facilities, constraining capacity expansion speed for suppliers without existing certified footprints.
- Electrolyte saturation consistency:Manufacturing variance in fiberglass mat absorption rates creates yield losses that compound at scale, demanding precision process control investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbent Glass Mat (AGM) Battery Market |
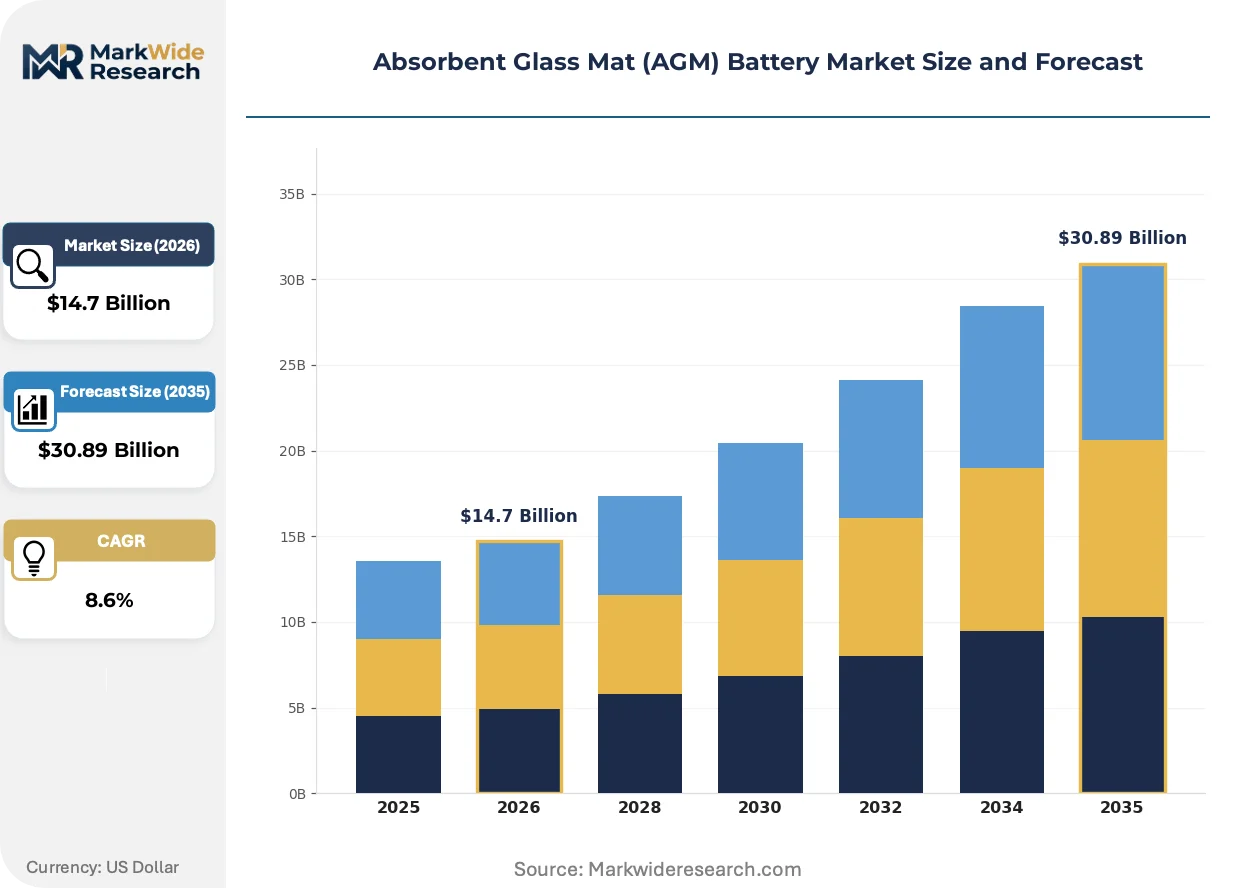
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Lead Acid, Gel, Flooded, Valve Regulated Lead Acid End User: Automotive, Renewable Energy, Telecommunications, Uninterruptible Power Supply Installation: Onshore, Offshore, Residential, Commercial Application: Solar Power Systems, Electric Vehicles, Backup Power, Medical Equipment |
| Companies Covered | East Penn Manufacturing, Panasonic Corporation, Exide Technologies, GS Yuasa Corporation, Robert Bosch GmbH, Clarios, C&D Technologies, Inc., Power Sonic Corporation, EnerSys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbent Glass Mat (AGM) Battery Market Strategic Shifts
Material science advances and regulatory compression timelines are converging to reshape how AGM batteries compete against alternative chemistries, with manufacturing process innovation becoming the primary differentiation vector rather than incremental capacity expansion.
Carbon-enhanced negative active material formulations are collapsing the cycle-life gap between premium AGM and entry-level lithium-ion alternatives in stationary storage applications. Telecommunications infrastructure operators in Germany and South Korea are adopting these enhanced cells for remote site backup, enabling vendors to defend positioning in accounts that previously accelerated lithium conversion timelines.
REACH substance restrictions and the EU Battery Regulation are mandating recycled content thresholds and supply chain due diligence disclosures that favor producers with integrated smelting and closed-loop collection networks. European OEMs are now requiring battery passports documenting origin and chemistry, pushing specification decisions toward suppliers with verified circular economy infrastructure rather than pure cost minimization.
Fleet operators are consolidating procurement through national service contracts that bundle battery supply with installation and core exchange, displacing fragmented distributor relationships. Commercial vehicle leasing companies in the United States are centralizing specification authority at headquarters level, compressing the number of approved suppliers and rewarding vendors with nationwide service density and standardized warranty administration.
Absorbent Glass Mat (AGM) Battery Market Segmentation
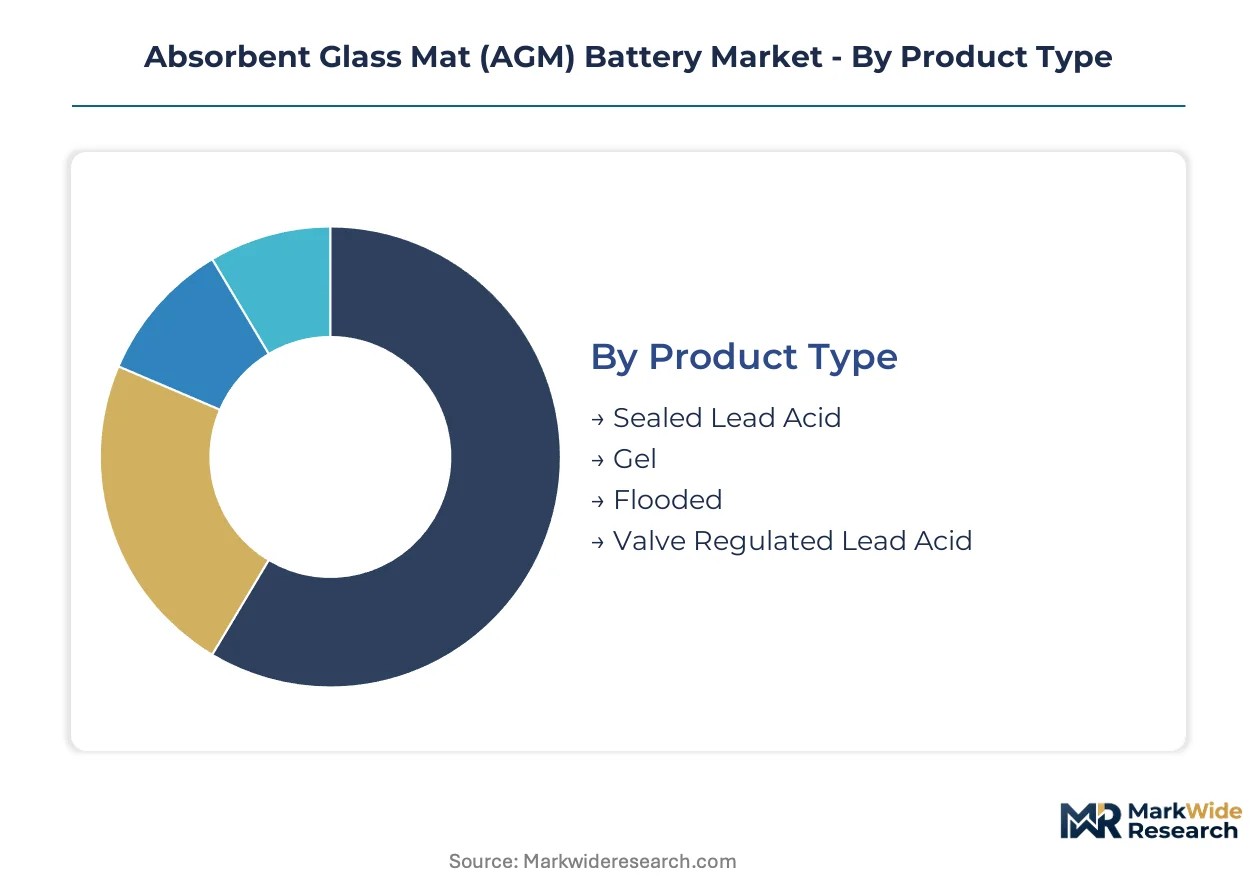
AGM battery procurement patterns diverge sharply across product architectures and use-case environments, with specification requirements in automotive start-stop systems bearing little resemblance to deep-cycle solar installations. Understanding these segment boundaries clarifies where manufacturers must deploy distinct technical competencies versus standardized platform economics.
Product Type:
Mature flooded designs dominate replacement channel economics while emerging sealed configurations capture specification-sensitive OEM fitments.
- Valve Regulated Lead Acid:Electrolyte is immobilized within a fiberglass mat separator, eliminating spillage risk and enabling installation in any orientation. German premium automakers specify VRLA-AGM for start-stop systems under EU Green Deal emissions mandates, compressing procurement windows for conventional flooded alternatives.
- Sealed Lead Acid:Maintenance-free construction with recombinant gas technology prevents water loss during operation. Telecom infrastructure operators in South Korea specify sealed AGM for remote site backup where technician access intervals exceed 24 months.
- Gel:Silica-thickened electrolyte provides enhanced cycle stability in high-temperature environments.
- Flooded:Liquid electrolyte design persists in cost-sensitive commercial vehicle replacement cycles.
VRLA handles the majority of throughput; sealed configurations are the fastest mover on share.
End User:
Volume concentration tracks regulatory compression timelines, with automotive emissions mandates pulling capacity ahead of stationary storage margin expansion.
- Automotive:Start-stop systems require high-rate discharge capability and vibration resistance for engine compartment mounting. EPA tailpipe regulations and EU Green Deal frameworks mandate CO2 reduction technologies that specify AGM over flooded lead-acid in new vehicle platforms across Michigan and Stuttgart manufacturing clusters.
- Renewable Energy:Deep-cycle duty and partial state-of-charge tolerance suit off-grid solar installations. Installers in Texas and Arizona specify AGM for residential battery banks where maintenance access is limited and cycle-life economics outweigh lithium-ion capital intensity.
- Telecommunications:Remote site backup demands 10-15 year service life with minimal intervention.
- Uninterruptible Power Supply:Short-duration discharge requirements favor lead-acid cost structures over lithium-ion in data center applications.
Automotive absorbs the greatest production volume; renewable energy climbs fastest as solar deployment accelerates.
Installation:
Cost tier differentiation separates capital-intensive offshore marine specifications from residential retrofit economics.
- Commercial:Fleet operators and facility managers prioritize standardized warranty administration and nationwide service density. Hyperscale data center operators in Virginia standardize on AGM for UPS backup where runtime requirements under 15 minutes favor lead-acid procurement economics.
- Residential:Homeowners balance upfront cost against maintenance burden in solar-plus-storage configurations. German households installing rooftop PV systems specify AGM for basement-mounted battery banks where ventilation constraints eliminate flooded alternatives.
- Onshore:Industrial motive power and stationary applications dominate land-based installations.
- Offshore:Marine environments demand corrosion-resistant terminals and enhanced vibration tolerance.
Commercial installations command the largest addressable spend; residential retrofits expand most quickly as distributed generation penetration deepens.
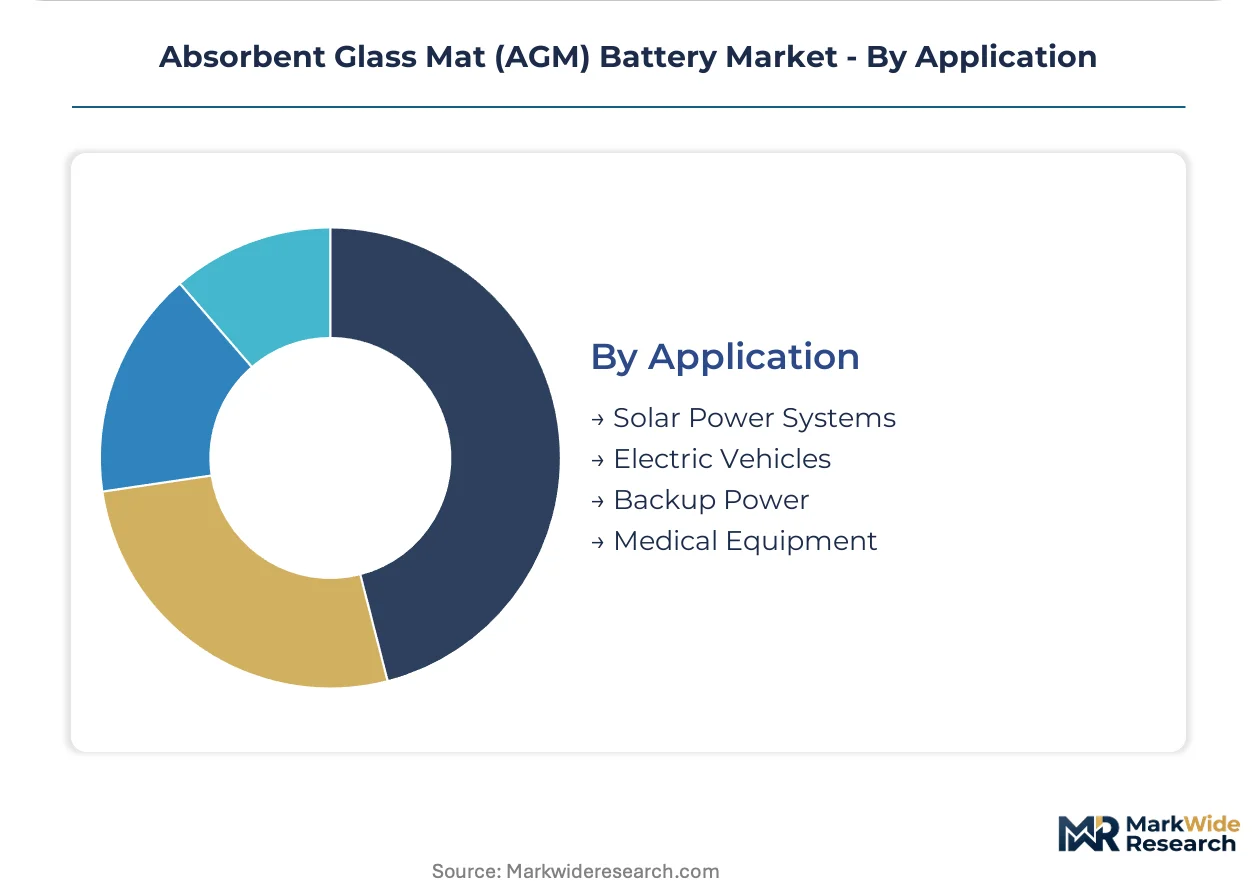
Application:
Margin structure inverts between high-volume mobility platforms and premium-priced stationary storage where cycle-life specifications justify cost premiums.
- Solar Power Systems:Daily deep-cycling requirements and 20-year project financing horizons demand predictable degradation curves. Off-grid developers in Arizona and Rajasthan specify AGM for battery banks where temperature extremes and maintenance access constraints eliminate flooded alternatives.
- Backup Power:Grid instability and reliability mandates drive specification across healthcare and critical infrastructure. Hospital operators in Florida specify AGM for emergency power systems where NHTSA safety standards and ISO 9001 traceability requirements constrain supplier qualification.
- Electric Vehicles:Light electric vehicles and hybrid transition platforms create adjacent demand before full battery electric penetration.
- Medical Equipment:Portable device manufacturers specify AGM for mobility carts and emergency equipment where spill-proof construction is mandatory.
Backup power anchors current revenue concentration; solar applications gain share fastest as renewable deployment timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emissions mandates anchor European specification pull for AGM technology, while EPA tailpipe regulations drive parallel adoption across North American automotive clusters. Production capacity concentrates near premium OEM assembly plants in Germany, Michigan, and Japan.
United States
EPA tailpipe regulations mandate CO2 reduction technologies that specify AGM batteries for start-stop systems across light-duty vehicle platforms. The Inflation Reduction Act incentivizes domestic battery manufacturing investments near automotive assembly corridors. Clarios and East Penn Manufacturing anchor production capacity in Michigan and Pennsylvania to serve Detroit Three OEM supply chains.
Germany
Premium automakers headquartered in Stuttgart and Munich specify AGM for original equipment fitment under EU Green Deal emissions frameworks. REACH substance restrictions mandate recycled content thresholds that favor producers with integrated smelting networks. Robert Bosch GmbH maintains production facilities in Baden-Württemberg to supply BMW, Mercedes-Benz, and Volkswagen Group platforms.
China
Dual carbon goals and MIIT fuel consumption standards accelerate hybrid vehicle adoption requiring AGM technology for start-stop configurations. GB standards for automotive electrical systems specify vibration-resistant battery constructions for domestic OEM platforms. Production clusters in the Yangtze River Delta serve SAIC Motor and Geely Automotive assembly operations.
Japan
METI energy efficiency mandates and JIS quality standards constrain market access for suppliers lacking certified production traceability. GS Yuasa Corporation anchors Asian production capacity through dedicated facilities serving Toyota, Honda, and Nissan hybrid platforms. The Kanto region concentrates R&D investment for next-generation absorbent glass mat formulations.
India
The PLI scheme for advanced chemistry cell manufacturing creates adjacent demand for AGM in hybrid transition vehicles before full battery electric penetration. BIS certification requirements extend qualification timelines for new market entrants. Tamil Nadu and Maharashtra host emerging production facilities to serve Maruti Suzuki and Tata Motors supply chains.
Absorbent Glass Mat (AGM) Battery Market Competitive Environment
Integrated battery manufacturers and specialized industrial power suppliers split the market between automotive OEM channels and aftermarket replacement cycles. Tier-1 suppliers with captive smelting operations command specification authority in European and North American premium vehicle programs. Three archetypes dominate: vertically integrated lead-acid specialists, diversified electronics conglomerates, and industrial motive power focused operators. Competitive dynamics center on long-term OEM supply contracts and closed-loop recycling network density rather than pure manufacturing scale expansion.
Among Japanese and South Korean battery fabricators, GS Yuasa Corporation and Panasonic Corporation exemplify the diversified conglomerate archetype with automotive and industrial segment exposure. East Penn Manufacturing represents the vertically integrated North American specialist with captive lead processing and nationwide distribution infrastructure. These three anchors illustrate how geographic production concentration and recycling network control determine specification access in emissions-regulated automotive markets.
| Leading Market Players |
|---|
| East Penn Manufacturing |
| Panasonic Corporation |
| Exide Technologies |
| GS Yuasa Corporation |
| Robert Bosch GmbH |
| Clarios |
| C&D Technologies, Inc. |
| Power Sonic Corporation |
| EnerSys |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's premium automotive manufacturing cluster concentrates AGM production capacity, giving German suppliers outsized leverage in contract negotiations with North American and Asian OEMs seeking EU-compliant start-stop battery specifications.
Pricing Analysis
Geographic price spreads of 15-25% separate German OEM supply contracts from aftermarket replacement channels. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 certification grade and captive smelter integration. Cost compression in the economy tier is intensifying because Chinese producers are expanding VRLA-AGM export volumes. Fleet operators exhibit the highest price sensitivity, while data center UPS procurement teams prioritize reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates at Clarios facilities in Michigan, GS Yuasa plants in Japan's Kanto region, and Bosch operations in Baden-Württemberg. Lead ingot supply draws from Australian mining operations and Chinese secondary smelters, with fiberglass mat separators sourced from specialized textile producers in Germany and the United States. Single-source vulnerability in lead oxide processing creates exposure to commodity price spikes. Distribution runs through OEM direct supply agreements and national battery distributor networks serving independent repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profitable participation in this market hinges on securing validated production traceability, a capability gap that extends OEM qualification timelines to 18-24 months for new entrants lacking existing certified footprints.
For Market Incumbents: Entrench specification authority by deepening captive lead smelting capacity and securing 5-7 year OEM supply contracts before lithium iron phosphate cost curves compress the hybrid vehicle window. Prioritize carbon-enhanced negative active material R&D to defend cycle-life positioning against entry-level lithium substitution in telecom backup accounts. For New Entrants and Emerging Players: Build out marine and RV aftermarket distribution in coastal U.S. states and Mediterranean markets where vibration-resistant dual-purpose configurations command premium positioning. Target India's hybrid transition vehicle segment under PLI scheme incentives before domestic cell manufacturing matures. Lead with installation and core-exchange bundling to displace fragmented distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized battery divisions lacking closed-loop recycling infrastructure. Frame long-term viability around the 10-15 year hybrid vehicle transition runway in emerging markets. Monitor solid-state battery pilot production announcements as the signal indicating accelerated lithium substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive supply of secondary lead insulates margin from LME price volatility and satisfies EU Battery Regulation recycled content mandates. |
| Carbon-Enhanced Formulation Launch | Cycle-life extension defends AGM positioning against lithium-ion conversion in German and South Korean telecom infrastructure accounts. |
| OEM Supply Contract Extension | Long-term volume commitments with Stuttgart and Munich automakers anchor capacity utilization through EU Green Deal implementation phases. |
| Closed-Loop Collection Network Expansion | Integrated recycling infrastructure satisfies REACH due diligence requirements and secures battery passport compliance for European OEM qualification. |
| Marine Aftermarket Channel Partnership | Coastal distributor alliances in Florida and Mediterranean markets capture share in vibration-resistant dual-purpose configurations. |
Study Parameters
The analysis maps automotive start-stop, stationary storage, and motive power sub-sectors, each validated through procurement directors at European and North American OEMs, plant managers at lead-acid manufacturing facilities, and aftermarket distribution executives. Primary interview findings were cross-checked against EPA regulatory filings, EU Battery Regulation implementation guidance, IHS Markit vehicle production databases, and customs trade data for lead ingot flows. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Assumptions held fixed include current EU Green Deal and EPA tailpipe regulatory trajectories, while lithium-ion cost curve slopes and lead price volatility bands were varied across sensitivity scenarios. Segmentation dimensions encompassed product architecture, end-use application, installation environment, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle timing. Key inputs included automotive platform electrification roadmaps and solar deployment timelines in target markets.
Stress conditions across lead price spikes, accelerated lithium substitution, and Southeast Asian recycling infrastructure development were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including supply chain disruption and regulatory timeline shifts. Quarterly review of OEM platform electrification announcements and lithium iron phosphate capacity buildouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Lead Acid Battery Market
Batteries
Lithium Starters Market
Batteries
East Africa Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Lead Carbon Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
North America Lead Acid Battery Market
Batteries
48 Volt Battery System Market
Batteries
Alkaline Secondary Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Myanmar Battery Market
Batteries
Battery Separators Market
Batteries
N-Type Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Industrial Battery Charger Market