
 Global Tissue Sealants Market | 2026-2036
Global Tissue Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tissue Sealants Market Foresight
Hospital-grade sealant specifications is rotating toward higher-purity fibrin formulations with extended working times. Baxter International leverages its plasma-derived protein platform to sustain leadership in hemostatic biologics. Johnson & Johnson anchors the competitive set through its broad surgical portfolio and Ethicon-branded adhesive technologies. Medtronic differentiates via integrated operating-room ecosystems that bundle sealants with energy-based surgical instruments.
Tissue sealants comprise biologically active or synthetic adhesive formulations designed to achieve hemostasis, seal fluid leaks, or bond tissue planes during operative procedures; fibrin-based variants typically combine human thrombin with concentrated fibrinogen to mimic the final coagulation cascade phase, achieving gelation within seconds to minutes depending on component ratios. Synthetic polymer alternatives employ polyethylene glycol or cyanoacrylate chemistries for situations where blood-derived products carry contraindications. Among product types, fibrin sealants occupy the dominant revenue position due to established reimbursement pathways and surgeon familiarity, while synthetic polymers represent the fastest-expanding category as material science yields improved elasticity and reduced inflammatory response profiles. Application segmentation shows cardiovascular surgery generating premium pricing, whereas trauma care volumes scale through military and emergency-medicine procurement channels.
FDA premarket notification requirements under 21 CFR 878.4490 govern absorbable surgical sealant classifications, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for Class III implantable adhesives. Japan's PMDA enforces Good Manufacturing Practice standards for biological starting materials, creating compliance complexity for multinational suppliers. ISO 10993 biocompatibility testing series provides the harmonized framework most manufacturers adopt across jurisdictions. Stakeholders must monitor evolving reimbursement thresholds for sealant-assisted procedures versus conventional suturing techniques as health technology assessment bodies recalibrate cost-effectiveness benchmarks.
Market Dynamics
Integrated delivery networks in the United States are consolidating procurement authority for surgical supplies, compressing vendor margins while elevating scale requirements for fibrin sealant suppliers seeking hospital formulary placement.
Growth Catalysts
- Fibrin Formulation Purity Standards:Extended working times in next-generation hemostatic biologics enable complex aortic reconstructions. Cardiovascular surgery suites in Germany and Japan are expanding adoption.
- EU Medical Device Regulation:Stricter biocompatibility documentation for Class III implantable adhesives is accelerating quality differentiation. Manufacturers with robust clinical evidence portfolios capture premium tier positioning.
- Synthetic Polymer Elasticity:Polyethylene glycol chemistries with reduced inflammatory profiles address contraindications to blood-derived products. Trauma care channels in military and emergency medicine represent volume scaling pathways.
Market Restraints
- Plasma-Derived Input Volatility:Human thrombin and fibrinogen sourcing concentrates in fractionation facilities with limited geographic dispersion. Baxter International's plasma platform dominance creates supply concentration risk.
- Reimbursement Compression:Health technology assessment bodies in England and France are recalibrating cost-effectiveness benchmarks for sealant-assisted procedures versus conventional suturing techniques.
- Cyanoacrylate Substitution Threat:Synthetic alternatives with faster polymerization times challenge fibrin sealants in superficial wound closure applications where hemostasis speed outweighs biocompatibility.
Strategic Opportunities
- Underpenetrated Indian Market:Central Drugs Standard Control Organization pathways for biological starting materials remain nascent. Early entrants establishing Good Manufacturing Practice compliance capture surgeon training relationships.
- Robotic Surgery Integration:Convergence of sealant delivery systems with da Vinci and Versius platforms enables precision application in minimally invasive procedures. Medtronic's ecosystem bundling strategy provides template.
- Japan PMDA Biological Material Standards:Stringent starting material traceability requirements create compliance moats. Manufacturers with established Japanese pharmacovigilance infrastructure defend against late entrants.
Industry Challenges
- ISO 10993 Testing Bottlenecks:Biocompatibility evaluation timelines for novel polymer chemistries extend 18-24 months, delaying product launches and consuming R&D capital without revenue offset.
- Legacy Suturing Technique Persistence:Surgical training curricula in Eastern European and Latin American markets emphasize conventional closure methods, requiring expensive surgeon education investments to shift practice patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tissue Sealants Market |
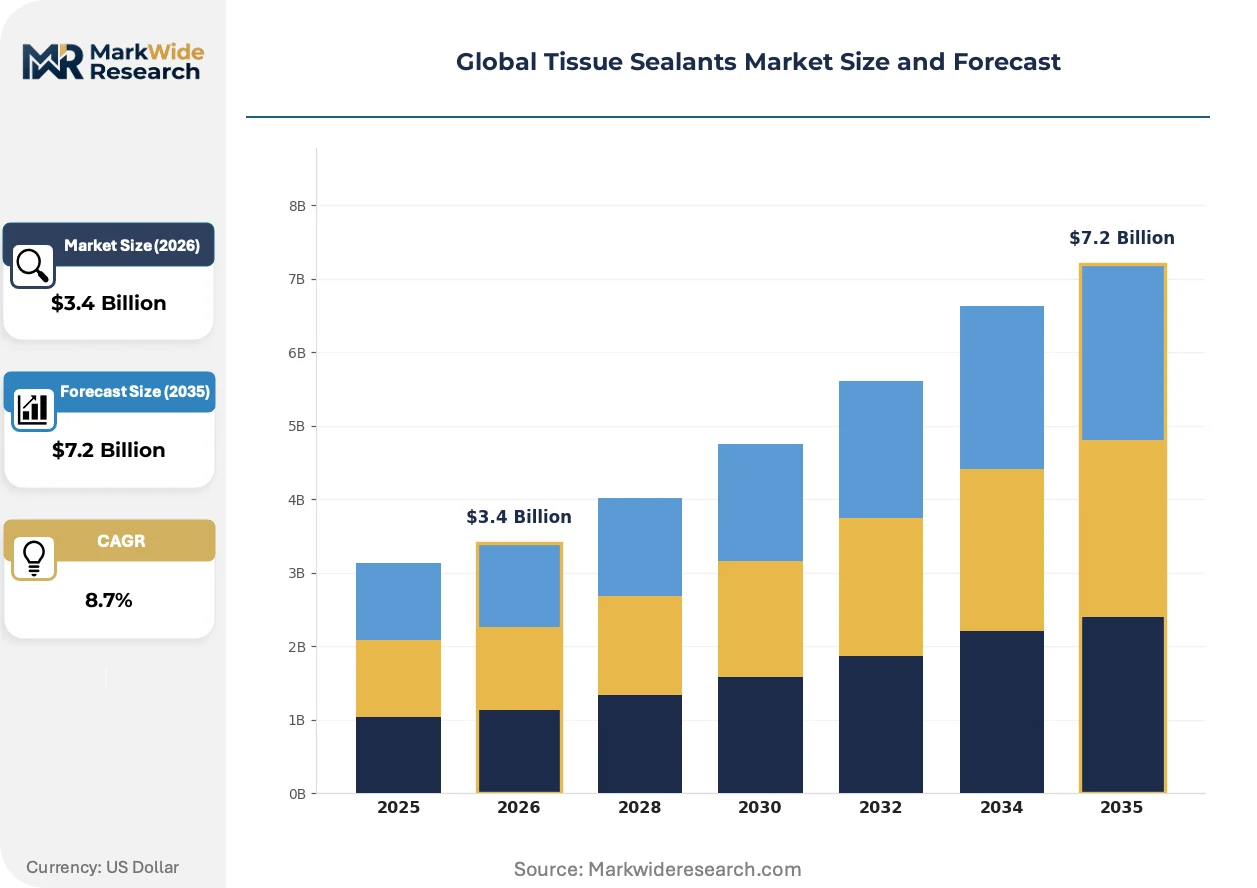
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrin Sealants, Synthetic Polymers, Albumin-Based Sealants, Collagen Sealants, Cyanoacrylate Adhesives Application: Surgical Procedures, Dental Surgery, Trauma Care, Cardiovascular Surgery, Ophthalmic Surgery End User: Hospitals, Ambulatory Surgical Centers, Dental Clinics, Specialty Surgery Centers, Trauma Centers Administration Form: Liquid, Spray, Foam, Patch, Powder |
| Companies Covered | Johnson & Johnson, Baxter International, Medtronic, Integra LifeSciences, CryoLife, CSL Behring, Becton Dickinson, Smith & Nephew, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tissue Sealants Market Shifts & Advancements
Material science advances in synthetic polymer elasticity and fibrin formulation stability are compressing the performance gap between biologic and synthetic sealant categories while regulatory harmonization efforts reshape competitive entry barriers.
Next-generation polyethylene glycol sealants with tunable degradation profiles are miniaturizing application volumes required for effective hemostasis. Ambulatory surgery centers in the United States are adopting these formulations for outpatient cardiovascular interventions where rapid discharge protocols demand reliable sealing with minimal inflammatory response. The technology is miniaturizing the addressable procedure universe by enabling safe deployment in settings previously restricted to fibrin-based alternatives.
EU Medical Device Regulation post-market surveillance mandates for Class III implantable adhesives are extending clinical evidence requirements beyond premarket approval. Manufacturers must now maintain active registries tracking long-term biocompatibility outcomes, elevating compliance costs disproportionately for mid-scale competitors. Cardiovascular surgery applications face the steepest documentation burdens given the extended patient monitoring horizons required for aortic procedures.
Hospital procurement committees are consolidating vendor contracts under value-based frameworks that unbundle sealant pricing from instrument bundles. Integrated delivery networks in Texas and California are piloting direct manufacturer agreements that bypass distributor markups, compressing channel margins while rewarding suppliers with comprehensive surgeon training programs. This behavioral shift is most visible in cardiovascular service lines where procedure volumes justify dedicated supply chain infrastructure.
Global Tissue Sealants Market Segmentation
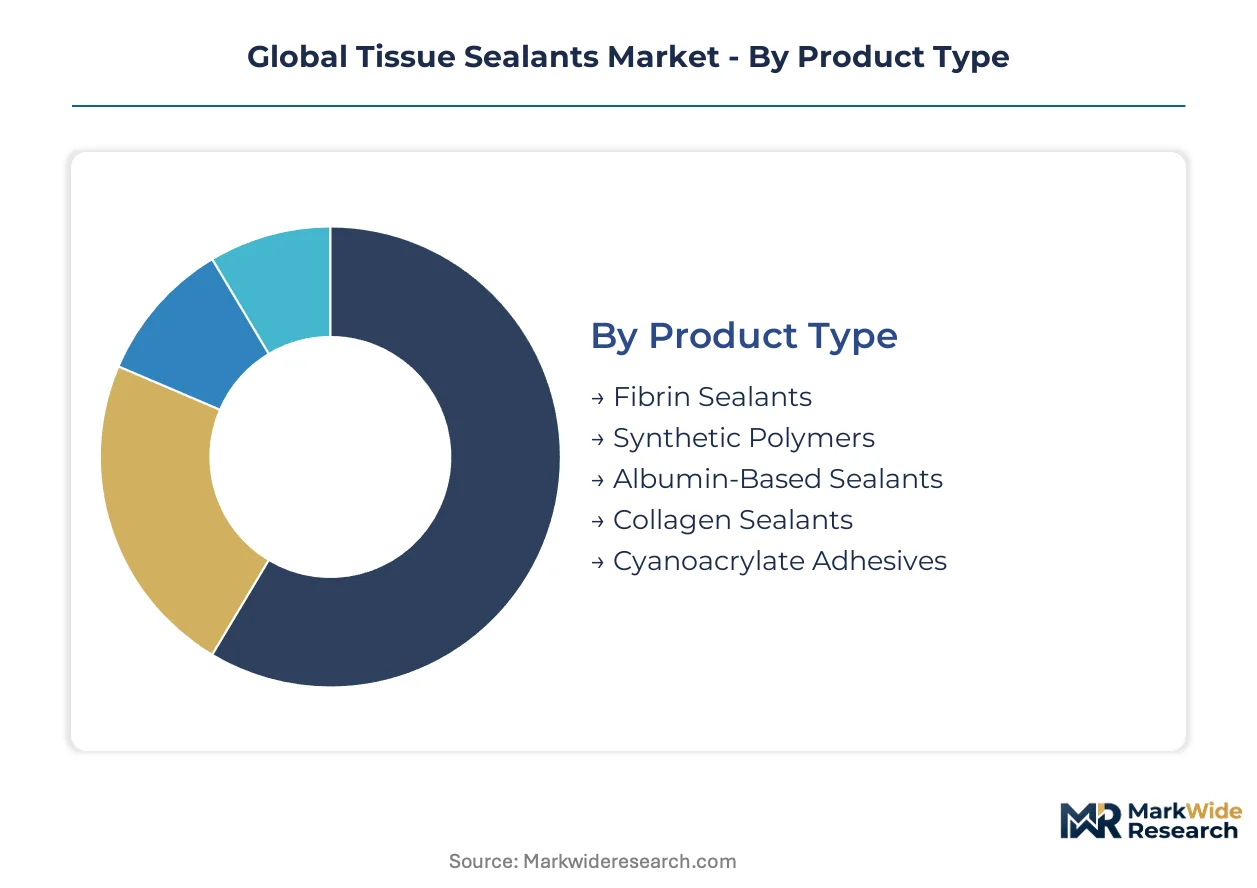
Tissue sealant procurement channels diverge sharply by clinical setting and reimbursement pathway. Hospital formulary committees evaluate fibrin formulations against synthetic alternatives through total cost-of-ownership frameworks, while ambulatory centers prioritize rapid polymerization profiles that support same-day discharge protocols.
Product Type:
Product category selection determines distribution channel access and margin structure, with plasma-derived biologics flowing through specialty distributors and synthetic alternatives penetrating direct hospital contracts.
- Fibrin Sealants:Human thrombin and concentrated fibrinogen combinations replicate the final coagulation cascade phase, achieving gelation within seconds to minutes. Cardiovascular surgery suites in Germany and Japan generate premium pricing for extended working-time formulations that enable complex aortic reconstructions. Baxter International's plasma platform dominance concentrates supply in fractionation facilities with limited geographic dispersion.
- Synthetic Polymers:Polyethylene glycol and cyanoacrylate chemistries address contraindications to blood-derived products through tunable degradation profiles. Trauma care channels in military and emergency medicine represent the steepest expansion trajectory as material science yields improved elasticity and reduced inflammatory response profiles. Ambulatory surgery centers in the United States adopt these for outpatient cardiovascular interventions.
- Albumin-Based Sealants:Bovine-derived protein formulations serve niche applications where synthetic elasticity requirements conflict with biocompatibility thresholds. Specialty surgery centers in Switzerland maintain limited formulary positions.
- Collagen Sealants:Porcine or bovine extracellular matrix scaffolds provide structural support alongside hemostatic function. Dental surgery applications in South Korea show modest adoption.
- Cyanoacrylate Adhesives:Rapid polymerization chemistries challenge fibrin alternatives in superficial wound closure where speed outweighs biocompatibility. Superficial applications face reimbursement compression in England and France.
Fibrin sealants dominate installed base through established reimbursement pathways and surgeon familiarity. Synthetic polymers are where expansion concentrates as ISO 10993 biocompatibility testing validates next-generation formulations.
Application:
Procedure complexity and reimbursement tiering create distinct demand profiles across surgical disciplines, with cardiovascular interventions commanding premium pricing and trauma care scaling through volume procurement.
- Cardiovascular Surgery:Aortic procedures require extended working-time sealants capable of withstanding pulsatile flow conditions. EU Medical Device Regulation post-market surveillance mandates impose the steepest documentation burdens given extended patient monitoring horizons.
- Trauma Care:Military and emergency medicine procurement channels prioritize rapid deployment and shelf stability. Volume scaling occurs through centralized defense contracts rather than hospital formulary placement.
- Surgical Procedures:General operative applications span hemostasis, fluid leak sealing, and tissue plane bonding across multiple disciplines. Integrated delivery networks in Texas and California pilot direct manufacturer agreements that bypass distributor markups.
- Dental Surgery:Oral tissue bonding applications favor cyanoacrylate alternatives for mucosal closure speed. Dental clinics in India represent underpenetrated demand with nascent CDSCO pathways for biological starting materials.
- Ophthalmic Surgery:Micro-scale application requirements demand specialized delivery system integration. Precision constraints limit synthetic polymer adoption pending miniaturization advances.
Surgical procedures capture the broadest installed base across hospital service lines. Cardiovascular surgery is where margin expansion concentrates despite regulatory documentation intensity.
End User:
Customer type segmentation reflects capital intensity and procurement sophistication, with integrated delivery networks consolidating authority while specialty centers pursue niche clinical differentiation.
- Hospitals:Academic medical centers and community hospitals maintain the largest sealant inventories across multiple product categories. Value-based procurement frameworks unbundle pricing from instrument bundles in cardiovascular service lines.
- Ambulatory Surgical Centers:Outpatient facilities prioritize rapid polymerization and minimal inflammatory response to support same-day discharge. United States adoption of next-generation polyethylene glycol formulations is compressing the addressable procedure universe.
- Specialty Surgery Centers:Orthopedic and ophthalmic focused facilities demand procedure-specific formulation portfolios. Japan PMDA biological material standards create compliance moats defending established suppliers.
- Trauma Centers:Level I and II emergency departments maintain military-surplus compatible inventories for mass casualty readiness. Procurement flows through federal emergency preparedness channels rather than commercial distribution.
- Dental Clinics:Standalone oral surgery practices represent fragmented demand with limited formulary standardization. Surgeon education investments required to shift from conventional suturing techniques constrain synthetic sealant penetration.
Hospitals dominate installed base through consolidated procurement authority. Ambulatory surgical centers are where volume expansion concentrates as minimally invasive procedure migration accelerates.
Administration Form:
Delivery mechanism selection determines application precision and waste minimization, with liquid and spray formats penetrating high-volume settings and specialized forms serving targeted anatomical constraints.
- Liquid:Standard syringe-dispensed formulations serve the broadest procedure range across surgical disciplines. Manual application requires skilled technique to achieve uniform coverage.
- Spray:Aerosolized delivery enables rapid large-surface coverage in thoracic and abdominal procedures. Robotic surgery integration with da Vinci and Versius platforms enables precision application in minimally invasive settings.
- Foam:Pre-formed scaffold structures provide mechanical support in cavity sealing applications. Limited adoption outside cardiac and thoracic specialties.
- Patch:Solid matrix formats enable controlled release in vascular anastomosis reinforcement. Specialty surgery centers in Germany maintain dedicated inventory for aortic procedures.
- Powder:Granular application formats address diffuse bleeding in hepatic and splenic trauma. Military procurement channels represent primary demand concentration.
Liquid formulations dominate installed base through versatility and cost efficiency. Spray delivery is where technology integration concentrates as robotic surgical platform adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in tissue sealants track closely with plasma fractionation capacity and regulatory harmonization progress. The United States maintains net exporter status through concentrated biologics manufacturing, while Germany and Japan balance domestic production with specialized imports for cardiovascular applications.
United States
Integrated delivery networks in Texas and California consolidate procurement authority for surgical supplies, compressing distributor margins while elevating scale requirements for formulary placement. FDA premarket notification pathways under 21 CFR 878.4490 govern absorbable surgical sealant classifications, creating predictable entry frameworks. Academic medical centers in Boston and Houston anchor cardiovascular surgery innovation, driving demand for extended working-time fibrin formulations.
Germany
Cardiovascular surgery suites in Bavaria and North Rhine-Westphalia generate premium pricing for complex aortic reconstructions requiring advanced hemostatic biologics. EU Medical Device Regulation post-market surveillance mandates impose steep documentation burdens for Class III implantable adhesives, accelerating quality differentiation. Frankfurt and Munich host specialty surgery centers maintaining dedicated inventory for vascular anastomosis reinforcement procedures.
Japan
Stringent PMDA biological material standards concentrate demand among established suppliers with pharmacovigilance infrastructure in Tokyo and Osaka. Extended patient monitoring requirements for implantable adhesives favor manufacturers with proven long-term biocompatibility registries. Kanto region hospitals lead adoption of robotic surgery integration, converging sealant delivery with da Vinci platforms for minimally invasive precision.
India
Underpenetrated surgical sealant demand in Maharashtra and Gujarat creates first-mover opportunities for manufacturers establishing CDSCO compliance for biological starting materials. Central Drugs Standard Control Organization pathways remain nascent, rewarding early entrants with surgeon training relationships. Mumbai and Ahmedabad medical centers show modest synthetic polymer adoption where blood-derived products face cost constraints.
Switzerland
Specialty surgery centers in Zurich and Geneva maintain limited formulary positions for albumin-based sealants serving niche biocompatibility requirements. Swissmedic regulations align with EU MDR frameworks while preserving distinct pharmacovigilance reporting standards. Basel-region biologics manufacturing anchors European supply chain resilience for plasma-derived protein platforms.
Global Tissue Sealants Market Competitive Landscape
Concentration sits with diversified medtech conglomerates controlling plasma fractionation infrastructure and surgical portfolio breadth. Three to four multinational holding companies dominate fibrin sealant revenue through established reimbursement pathways, while synthetic polymer specialists carve faster-growth positions in ambulatory settings. Competitive dynamics revolve around hospital formulary consolidation, integrated operating-room ecosystem bundling, and regulatory evidence portfolio depth. M&A activity targets regional distributors with surgeon training capabilities; strategic partnerships focus on robotic platform integration.
Within the diversified medtech tier, Johnson & Johnson and Baxter International occupy positions reflecting broad surgical portfolio anchoring and plasma-derived protein platform control respectively. Medtronic exemplifies ecosystem bundling strategy, converging sealant delivery with energy-based surgical instruments. These three entities represent distinct competitive archetypes: portfolio breadth, biological supply chain capture, and integrated system architecture.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International |
| Medtronic |
| Integra LifeSciences |
| CryoLife |
| CSL Behring |
| Becton Dickinson |
| Smith & Nephew |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
Synthetic polymer substitution for fibrin formulations in ambulatory cardiovascular procedures simultaneously relocates manufacturing gravity toward polyethylene glycol chemistry specialists in the United States and compresses price premiums previously commanded by plasma-derived biologics, as integrated delivery networks exploit formulation interchangeability to renegotiate hospital formulary contracts.
Pricing Analysis
Integrated delivery networks anchor pricing negotiations through centralized procurement contracts that unbundle sealant costs from surgical instrument bundles. Three-tier pricing structure across premium fibrin formulations, mid-tier synthetic polymers, and economy cyanoacrylate alternatives reflects differentiation by biocompatibility certification grade and extended working-time performance. Cost compression in standard-tier synthetic polymers is intensifying as ambulatory surgery centers prioritize rapid polymerization profiles over clinical evidence depth. Trauma care procurement through military channels exhibits lowest price sensitivity due to shelf-stability requirements, while dental clinics in emerging markets demonstrate highest sensitivity to per-unit costs.
Supply Chain Analysis
Inventory lead times for human thrombin and fibrinogen concentrates extend substantially due to plasma fractionation capacity concentration in the United States, Germany, and Switzerland. Raw material sourcing draws from screened plasma donations, recombinant protein production, and bovine albumin extraction for niche applications. Single-source vulnerability permeates the fibrin sealant tier where Baxter International's plasma platform dominance creates supply concentration risk. Distribution runs through specialty biologics distributors for hospital formulary placement, with direct manufacturer agreements increasingly bypassing channel markups in consolidated United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as procedure migration toward ambulatory settings creates segment-specific formulation demands that diversified conglomerates address suboptimally, opening niches for specialized synthetic polymer developers and regional compliance-focused suppliers.
For Market Incumbents: Consolidate plasma fractionation infrastructure through captive supply agreements with independent collection networks to defend against thrombin sourcing volatility. Deepen backward integration into recombinant protein production to reduce dependence on human plasma donations. Lock in robotic surgery platform partnerships with da Vinci and Versius integrators before synthetic polymer specialists capture minimally invasive delivery system standards.
For New Entrants and Emerging Players: Lead with CDSCO compliance investment in Maharashtra and Gujarat to establish surgeon training relationships ahead of biological starting material pathway maturation. Target ambulatory surgery centers in the United States with next-generation polyethylene glycol formulations featuring tunable degradation profiles. Pursue military trauma care procurement channels where volume scaling occurs through centralized defense contracts rather than fragmented hospital formulary competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed synthetic polymer specialists possessing ISO 10993 biocompatibility portfolios but lacking hospital GPO contract access. Long-term viability over the extended analysis window hinges on regulatory evidence depth rather than manufacturing scale alone. Monitor EU MDR post-market surveillance compliance cost burdens as the inflection indicator for mid-scale competitor distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Fractionation Capacity Expansion | Captive thrombin supply secures fibrin sealant margin defense against synthetic substitution. |
| Robotic Surgery Platform Partnership | da Vinci and Versius integration locks in minimally invasive procedure channel access. |
| EU MDR Clinical Evidence Portfolio Build | Post-market surveillance registries create compliance moats defending premium tier positioning. |
| CDSCO Biological Material Compliance | Early Indian market entry captures surgeon training relationships before pathway standardization. |
| Reimbursement Strategy Development | Health technology assessment alignment determines sealant-assisted procedure cost-effectiveness benchmarks. |
Research Methodology
Operator-level perspectives from cardiovascular surgeons, hospital procurement committee members, plasma fractionation facility managers, and GPO contracts managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and ISO 10993 biocompatibility testing records. Bottom-up procedure volume estimates across application segments triangulated with top-down manufacturer revenue analysis.
Sensitivity analysis around plasma input cost volatility, reimbursement threshold shifts, and synthetic polymer adoption curves informed projection robustness. Segmentation modeling spanned product type, application discipline, end-user facility category, and administration form complexity across the projection horizon. CAGRs derived from weighted average procedure growth rates adjusted for pricing trajectory assumptions and regulatory approval timeline distributions.
Underlying assumptions cover stable plasma collection volumes, EU MDR enforcement continuity, and United States integrated delivery network consolidation pace, with deviation risk concentrated in reimbursement compression events and synthetic polymer biocompatibility breakthroughs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Latex Binders Market