
 UV Adhesives Market | 2026-2036
UV Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
UV Adhesives Market Analysis
Electronics OEMs is reorganizing procurement priorities away from traditional thermal-cure systems toward UV-curable platforms that cut cycle times on automated assembly lines. Henkel AG & Co. KGaA leverages its European R&D infrastructure to anchor formulation leadership in optical-grade products. Dymax Corporation specializes in LED-optimized adhesive systems that dominate North American medical device bonding applications. Sika AG extends its construction chemicals expertise into industrial UV platforms, competing on manufacturing scale across automotive tier-one supply chains.
UV adhesives are polymer-based formulations incorporating photoinitiators that polymerize upon exposure to ultraviolet radiation in the 200-400 nanometer range, delivering cured strengths from 5 to 30 MPa depending on substrate and oligomer chemistry. Their primary commercial purpose centers on precision bonding of dissimilar materials where thermal exposure risks component damage or where production throughput demands sub-second fixture times. Rigid adhesives occupy the largest volume share in electronics display lamination, where glass-to-glass bonding requires high modulus and optical clarity. Flexible adhesives represent the fastest-expanding category, driven by foldable device architectures and wearable medical patches that demand elongation exceeding 150% post-cure. Pressure-sensitive variants command premium pricing in temporary semiconductor wafer processing applications where clean removability protects fragile substrates.
EPA regulations on volatile organic compound emissions constrain solvent-based UV adhesive formulations in US manufacturing facilities, while REACH substance restrictions in Europe accelerate phase-out of bisphenol A-derived oligomers in consumer-facing applications. China's GB standards for industrial chemical safety, enforced by SAMR, mandate hazard communication labeling that affects import eligibility for non-domestic suppliers. Stakeholders must monitor evolving photoinitiator toxicity classifications across these jurisdictions, as regulatory reclassification would force raw material substitution ahead of compliance deadlines.
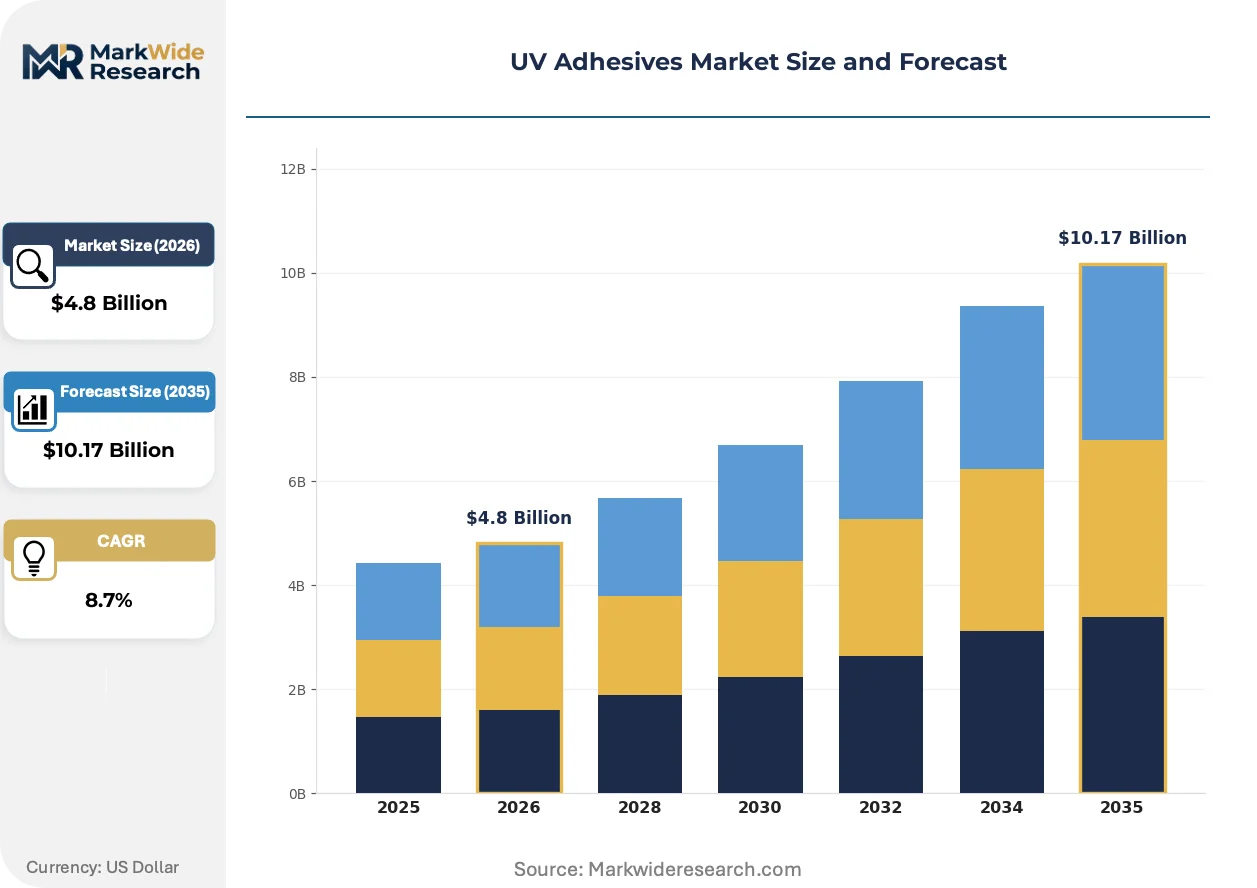
Market Dynamics
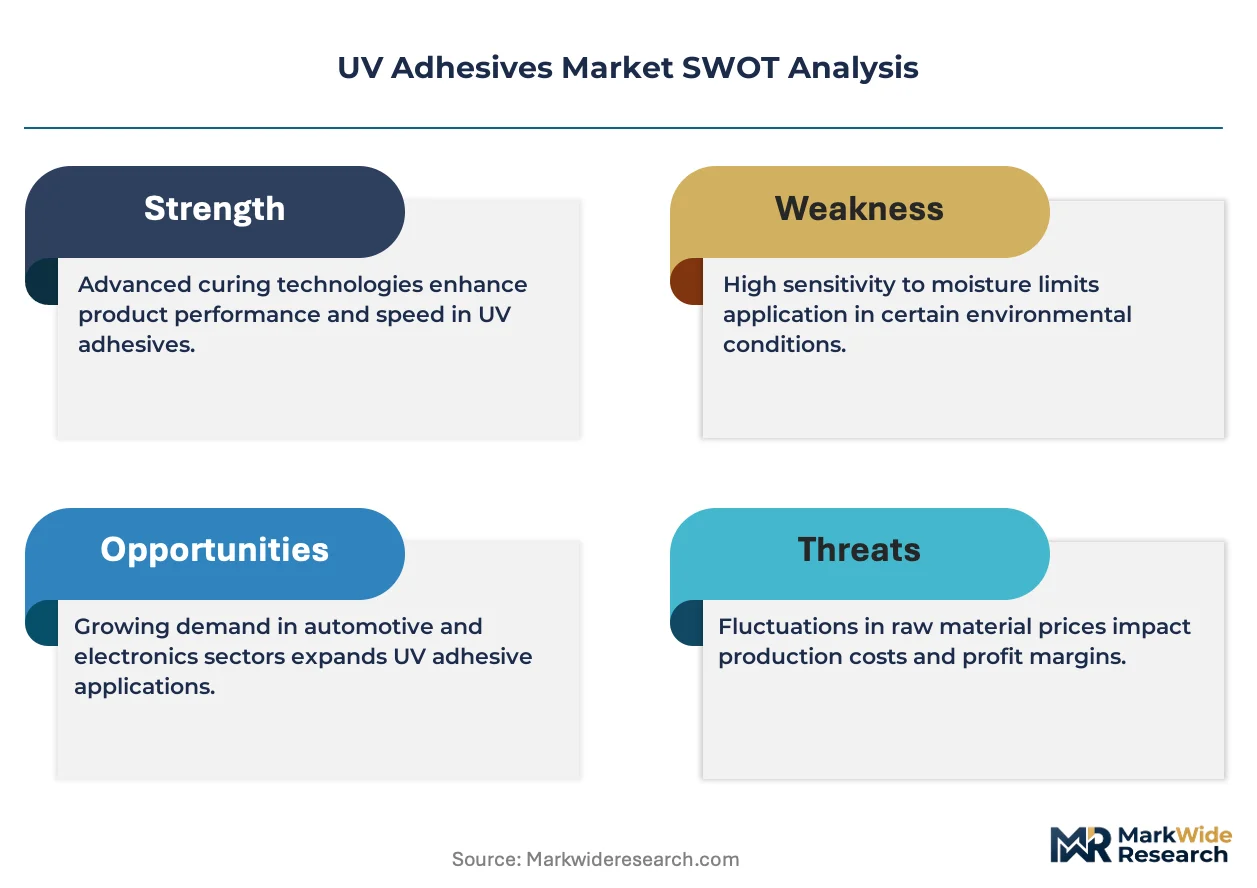
Mercury-free photoinitiator systems are forcing wholesale reformulation across European supply chains as REACH substance restrictions tighten permissible thresholds, compressing development timelines and elevating R&D capex for formulators serving electronics and medical device OEMs.
Growth Catalysts
- Foldable Device Architectures:Wearable medical patches and flexible displays are driving procurement of elongation-capable adhesive systems that exceed 150% post-cure strain tolerance.
- China's LED Curing Deployment:Domestic equipment installation accelerates conversion from thermal processes, concentrating demand in Shenzhen and Suzhou manufacturing clusters.
- RoHS Compliance Deadlines:European electronics manufacturers are advancing UV platform adoption to eliminate thermal-cure bottlenecks on automated assembly lines before substance restriction enforcement dates.
Market Restraints
- Photoinitiator Supply Concentration:Specialty chemical production for mercury-free alternatives clusters in German and Swiss manufacturing bases, creating single-source vulnerability for Asian formulators.
- Substrate Compatibility Limitations:UV-curable systems exhibit adhesion failure on low-surface-energy polymers including polypropylene and polyethylene, constraining penetration in automotive interior applications.
- Bisphenol A Phase-Out Friction:REACH restrictions on BPA-derived oligomers force raw material substitution ahead of compliance deadlines, disrupting established formulation portfolios.
Strategic Opportunities
- Semiconductor Wafer Processing:Pressure-sensitive UV adhesive variants command premium positioning in temporary bonding applications where clean removability protects fragile substrates during backgrinding operations.
- Optical-Grade Product Expansion:Glass-to-glass bonding for augmented reality headsets and automotive head-up displays creates specification windows for high-clarity, low-yellowing formulations.
- SAMR Hazard Communication Alignment:Non-domestic suppliers that adapt labeling and documentation to China's GB standards for industrial chemical safety secure import eligibility advantages.
Industry Challenges
- Formulation Chemistry Expertise Gap:Mercury-free photoinitiator integration demands photochemistry specialization that outpaces current technical training pipelines in Asian manufacturing centers.
- Multi-Jurisdiction Certification Burden:Simultaneous EPA VOC compliance, REACH substance registration, and SAMR documentation creates timeline compression for product launches across North American, European, and Chinese markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Adhesives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Adhesives, Flexible Adhesives, Pressure-Sensitive Adhesives, Optical Adhesives End User: Aerospace, Automotive, Electronics, Healthcare Application: Bonding, Sealing, Coating, Potting Technology: UV Curing, Thermal Curing, Solvent-Based, Water-Based |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, H.B. Fuller Company, Dymax Corporation, Arkema, Sika AG, Permabond Engineering Adhesives, DELO Industrial Adhesives, Panacol-Elosol GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Adhesives Market Emerging Trajectories
UV adhesive technology is compressing cure cycles from minutes to sub-second fixture times while regulatory frameworks simultaneously mandate cleaner chemistries, creating parallel pressure on formulators to deliver performance without legacy photoinitiator systems.
LED-optimized adhesive systems is miniaturizing cure equipment footprints in North American medical device cleanrooms, where manufacturers are replacing mercury-arc lamps to eliminate thermal damage risk on temperature-sensitive components. This conversion is enabling line reconfiguration that doubles throughput density in existing facility envelopes.
REACH substance restrictions are accelerating bisphenol A-derived oligomer phase-outs across European consumer electronics supply chains, forcing formulators to validate alternative backbone chemistries under compressed qualification timelines. Medical device adhesives face the steepest reformulation burden due to biocompatibility re-certification requirements.
Electronics OEMs are consolidating adhesive supplier relationships around platforms that span multiple substrate combinations, displacing fragmented procurement of application-specific grades. This concentration is most visible in Chinese display manufacturing, where tier-one panel makers are reducing qualified vendor lists from twelve to four sources.
UV Adhesives Market Segmentation
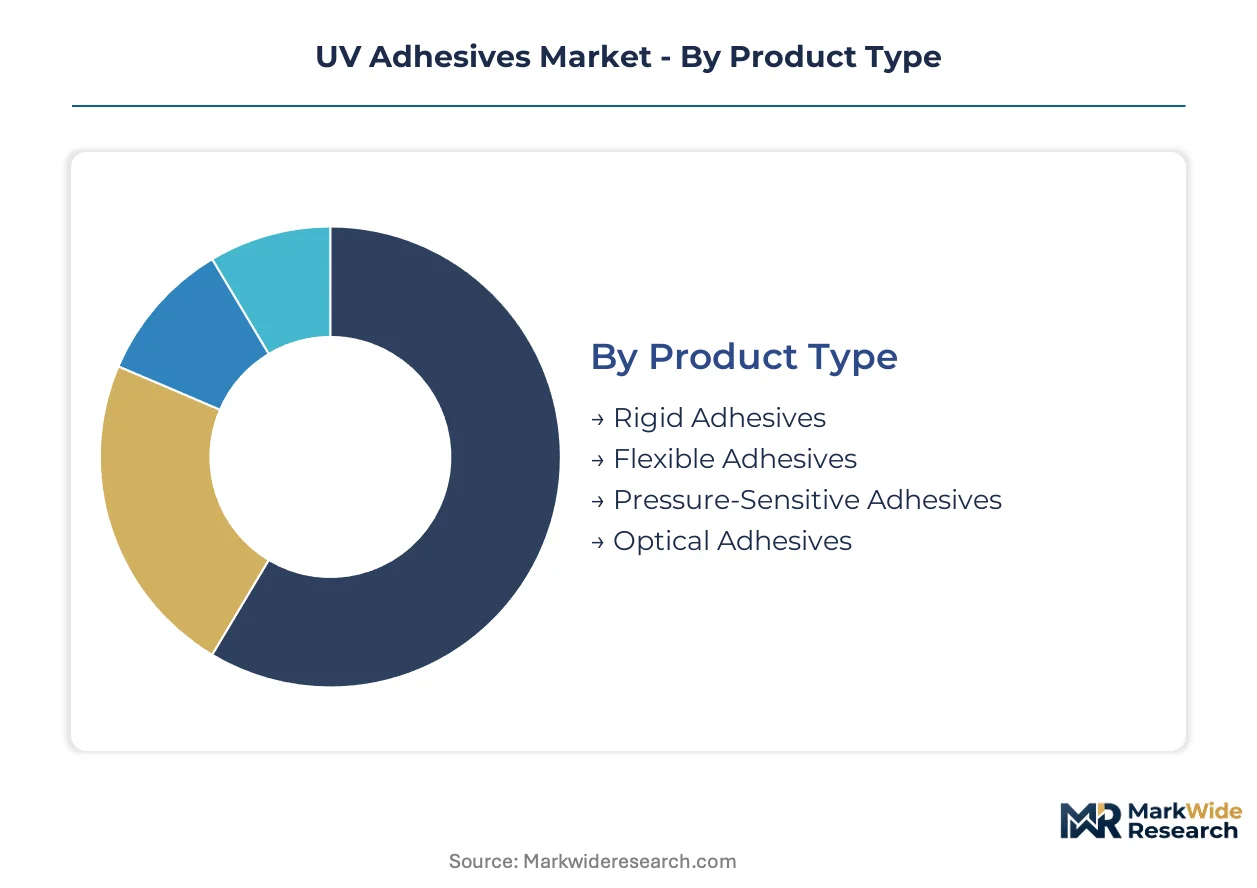
UV adhesive procurement patterns diverge sharply across formulation chemistry and end-use specifications, with electronics OEMs driving premium-grade demand while automotive and aerospace buyers prioritize certified supply chains. Segment boundaries are blurring as multi-functional formulations address bonding-sealing-coating requirements in single-pass processing.
Product Type:
Domestic production clusters serve regional electronics manufacturing, while optical and pressure-sensitive grades flow through export channels to medical device and semiconductor fabrication centers.
- Rigid Adhesives:High-modulus formulations based on epoxy acrylate and urethane acrylate backbones deliver cured strengths of 20-30 MPa. Glass-to-glass bonding for display lamination concentrates demand in Chinese and Korean panel manufacturing corridors, where modulus retention under thermal cycling determines supplier qualification.
- Flexible Adhesives:Elastomer-modified systems achieve post-cure elongation exceeding 150% through aliphatic urethane oligomers. Foldable device architectures and wearable medical patches in Shenzhen and Suzhou clusters are accelerating procurement of strain-tolerant platforms that survive repeated flex cycling.
- Pressure-Sensitive Adhesives:Low-tack UV-curable platforms enable temporary wafer bonding during semiconductor backgrinding operations.
- Optical Adhesives:Refractive-index-matched formulations with sub-1% haze specification serve augmented reality headset and automotive head-up display lamination.
Rigid adhesives command the established base. The steepest expansion runs through flexible adhesives.
End User:
Cost tiers separate commodity bonding applications from certified medical and aerospace grades that command formulation premiums.
- Electronics:Miniaturized component assembly drives the largest procurement volume, with UV platforms displacing thermal-cure systems to eliminate heat damage on temperature-sensitive substrates. Chinese display manufacturers are consolidating qualified supplier lists from twelve sources to four, concentrating procurement power.
- Healthcare:Biocompatibility certification per ISO 10993 and FDA Device Master File requirements create formulation barriers that sustain margin premiums. LED-optimized systems dominate North American cleanroom bonding of catheters, diagnostic cartridges, and wearable patches where mercury-arc thermal damage is unacceptable.
- Automotive:Tier-one supply chains demand IATF 16949-certified production with full material traceability for interior display and sensor bonding.
- Aerospace:Outgassing specifications per ASTM E595 and flame-smoke-toxicity ratings constrain qualified formulation portfolios to specialized suppliers.
Electronics anchors procurement volume. Healthcare delivers the steepest margin expansion trajectory.
Application:
Volume concentration favors bonding operations, while coating and potting applications require specialized rheology control that fragments supply.
- Bonding:Precision assembly of dissimilar materials—glass-to-metal, plastic-to-ceramic—represents the core commercial purpose, with sub-second fixture times enabling automated line speeds that thermal curing cannot match.
- Sealing:Gasketing and enclosure sealing for electronics housings and medical device cartridges demand elongation recovery after compression set.
- Coating:Conformal protective layers on PCBs and optical fibers require controlled viscosity and wetting characteristics.
- Potting:Encapsulation of LED modules and power electronics demands thermal conductivity additives and CTE matching to prevent delamination under thermal shock.
Bonding commands the established base. Potting is climbing the fastest as LED module production scales.
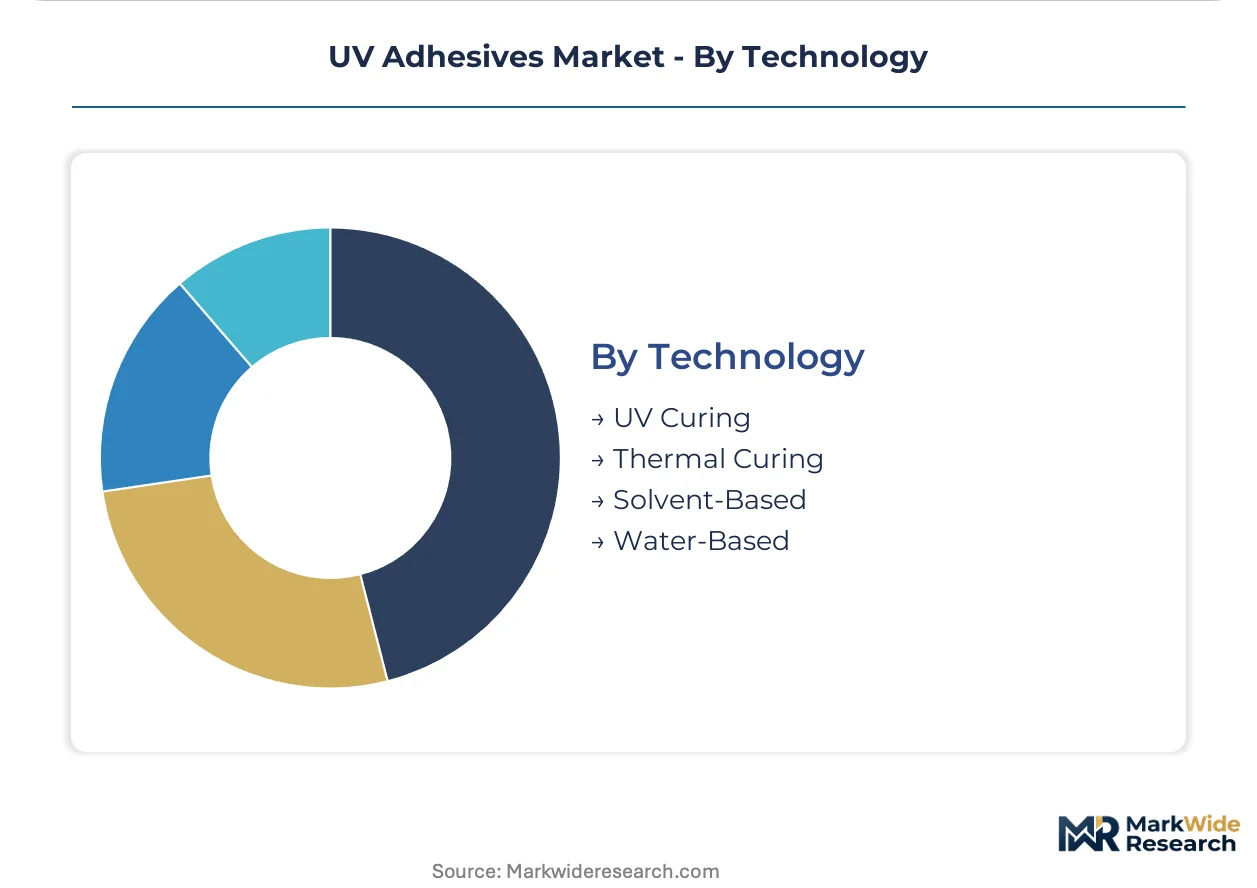
Technology:
Customer type bifurcation separates high-volume electronics manufacturers seeking LED-optimized platforms from legacy industrial users maintaining mercury-arc installations.
- UV Curing:Photoinitiator-activated polymerization at 200-400 nanometers delivers the sub-second cure speeds that automated electronics assembly demands. REACH and RoHS compliance deadlines are accelerating mercury-free photoinitiator adoption across European supply chains.
- Thermal Curing:Epoxy and silicone systems retain position in structural aerospace and automotive applications where UV light penetration is blocked by complex geometries.
- Solvent-Based:VOC emission constraints under EPA regulations are compressing US manufacturing deployment to niche applications.
- Water-Based:Low-VOC platforms serve paper and packaging bonding where optical clarity and structural strength requirements are modest.
UV curing commands the established base. Water-based formulations are gaining share fastest on environmental compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European supply chain integration for UV adhesive raw materials, while China's high-speed rail network connects Pearl River Delta manufacturing clusters to inland industrial zones.
China
Shenzhen and Suzhou electronics corridors drive procurement of LED-optimized UV curing systems for display lamination and semiconductor packaging. SAMR's GB standards for industrial chemical safety mandate hazard communication labeling that affects import eligibility for non-domestic suppliers. Domestic LED curing equipment deployment accelerates conversion from thermal processes in Guangdong and Jiangsu provinces.
Germany
Automotive tier-one supply chains in Baden-Württemberg and Bavaria demand IATF 16949-certified UV adhesive production with full material traceability. ECHA's REACH substance restrictions tighten permissible thresholds for mercury-free photoinitiator systems, compressing development timelines for formulators. The Rhine-Ruhr chemical corridor anchors specialty photoinitiator manufacturing for European electronics and medical device OEMs.
United States
North American medical device cleanrooms in Minnesota and Massachusetts drive LED-optimized adhesive procurement for catheter and diagnostic cartridge bonding. EPA regulations on volatile organic compound emissions constrain solvent-based formulations in domestic manufacturing facilities. The I-95 corridor from Boston to Philadelphia concentrates precision electronics assembly demanding sub-second UV cure cycles.
South Korea
Seoul Capital Area display manufacturers consolidate qualified adhesive supplier lists from twelve sources to four, concentrating procurement power for optical-grade formulations. MFDS biocompatibility requirements parallel FDA standards for medical device adhesives, creating dual-certification pathways. Gyeonggi Province panel fabrication corridors drive rigid adhesive demand for glass-to-glass bonding in OLED production.
Japan
Kansai region electronics OEMs reorganize procurement priorities toward UV-curable platforms that eliminate thermal damage on temperature-sensitive substrates. METI industrial standards influence photoinitiator toxicity classification protocols affecting import formulations. The Nagoya automotive manufacturing belt sustains demand for certified supply chains in sensor and interior display bonding applications.
UV Adhesives Market Vendor Landscape
Concentration sits with diversified chemical conglomerates and specialized adhesive formulators competing across certification-tiered market segments. Three to five multinational suppliers anchor premium-grade electronics and medical device applications, while mid-scale regional formulators serve automotive and industrial bonding requirements. Strategic archetypes include European R&D-centric innovators, Asian manufacturing-scale specialists, and North American application-engineering focused providers. Competitive moves center on mercury-free photoinitiator reformulation partnerships and LED curing equipment compatibility certification.
Among diversified chemical conglomerates, Henkel AG and Sika AG exemplify the European R&D-centric archetype, leveraging formulation infrastructure for optical-grade and industrial platform development. Dymax Corporation represents the North American application-engineering focus, occupying a position in LED-optimized systems for precision bonding segments. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Dymax Corporation |
| Arkema |
| Sika AG |
| Permabond Engineering Adhesives |
| DELO Industrial Adhesives |
| Panacol-Elosol GmbH |
| Others |
Supply Flow & Price Mechanics
Mercury-free photoinitiator substitution simultaneously redistributes supply geography toward German and Swiss specialty chemical corridors while compressing margin structures for Asian formulators facing single-source dependencies. Electronics OEM procurement consolidation from twelve qualified suppliers to four concentrates volume leverage, amplifying price pressure on non-specialized grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from IATF 16949 automotive tiers and uncertified industrial commodities. Price differentiation hinges on biocompatibility certification status and LED curing equipment compatibility validation. Cost compression in standard-grade electronics bonding intensifies as Chinese display manufacturers consolidate procurement around multi-substrate platforms. Tier-one automotive and medical device buyers exhibit lowest price sensitivity due to recertification friction, while commodity industrial users drive aggressive volume negotiations.
Supply Chain Analysis
Germany and Switzerland anchor specialty photoinitiator manufacturing for mercury-free formulations, while China dominates domestic LED curing equipment production and downstream adhesive formulation. Raw material flows draw from acrylate oligomer production in the Rhine-Ruhr corridor, urethane precursors from BASF Ludwigshafen complexes, and photoinitiator active ingredients from Swiss fine chemical specialists. Single-source vulnerability concentrates in mercury-free photoinitiator alternatives where patent-protected molecules limit qualified suppliers. Distribution runs through regional chemical distributors serving electronics clusters in Shenzhen, Suzhou, and Gyeonggi Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise scarcity—particularly photochemistry specialization for mercury-free photoinitiator integration—creates defensive moats for incumbents while raising entry barriers for Asian manufacturing centers lacking technical training pipelines.
For Market Incumbents: Secure backward integration into photoinitiator active ingredient production to eliminate single-source exposure as REACH substance restrictions tighten. Deepen LED curing equipment compatibility certification partnerships with dominant equipment OEMs to lock in specification advantages. Defensive consolidation around multi-substrate platform development counters electronics OEM supplier list compression from twelve sources to four. For New Entrants and Emerging Players: Lead with SAMR GB standards compliance and Mandarin-language hazard documentation to capture import substitution opportunities in Chinese electronics manufacturing corridors. Target temporary semiconductor wafer bonding applications where pressure-sensitive UV adhesive variants command premium positioning and established players maintain lighter presence. Pursue joint development agreements with domestic LED curing equipment manufacturers to accelerate qualification timelines. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors formulators with existing mercury-free photoinitiator portfolios and ECHA pre-registration documentation. Long-term viability centers on platforms spanning medical device biocompatibility and automotive IATF certification tiers. Watch ECHA substance restriction expansion timelines as the inflection signal for accelerated raw material substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Active Ingredients | Eliminates single-source vulnerability as REACH tightens mercury-free thresholds. |
| LED Curing Equipment Compatibility Certification | Locks in specification advantages with Shenzhen and Suzhou electronics clusters. |
| SAMR GB Standards Documentation Alignment | Secures import eligibility for non-domestic suppliers in Chinese manufacturing corridors. |
| Multi-Substrate Platform Development | Matches electronics OEM procurement consolidation toward consolidated supplier relationships. |
| Biocompatibility Certification Investment | Sustains margin premiums in healthcare applications facing ISO 10993 and FDA Device Master File barriers. |
Methodological Framework
Operator-level perspectives from adhesive formulators, LED curing equipment manufacturers, electronics OEM procurement directors, and medical device regulatory affairs specialists anchored the qualitative base. Secondary validation drew from ECHA REACH substance registration databases, SAMR GB standards documentation, SEC 10-K filings from listed chemical conglomerates, and customs trade data tracking photoinitiator raw material flows. Bottom-up segment sizing triangulated against top-down market construction across formulation chemistry, end-use certification tiers, and curing technology platforms.
Sensitivity analysis tested forecast outputs against alternative scenarios for REACH substance restriction enforcement timing and Chinese LED curing equipment deployment acceleration. Segmentation dimensions modeled include product type chemistry, end-use certification grade, application function, and curing technology platform. CAGRs derived from segment-level volume trajectories weighted by regional production cluster growth differentials. Industry-specific inputs incorporated photoinitiator substitution elasticity and electronics OEM supplier consolidation velocity.
Forecasts assume regulatory continuity in ECHA REACH and SAMR GB standards regimes; material policy shifts would require re-modeling. Specific risk factors include photoinitiator toxicity reclassification timelines and bisphenol A-derived oligomer phase-out acceleration. Recalibration cycles align with material shifts in regulatory enforcement dates and LED curing equipment penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market