
 EMEA Epoxy Adhesives Market | 2026-2036
EMEA Epoxy Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Epoxy Adhesives Market Analytics
Automotive OEMs is rotating toward structural bonding solutions as electric vehicle platforms demand lighter, corrosion-resistant joining methods. Henkel AG & Co. KGaA anchors its position through deep vertical integration in resin synthesis and applicator equipment. Sika AG differentiates via specialized two-part systems for composite-to-metal bonding in aerospace and rail applications. Mapei S.p.A. dominates construction-grade formulations across Mediterranean infrastructure projects.
Epoxy adhesives are thermosetting polymers formed from epoxide resin and polyamine hardener, curing through exothermic cross-linking to achieve shear strengths exceeding 20 MPa and chemical resistance across temperatures from -40°C to 150°C. These properties make them essential for load-bearing structural assemblies where mechanical fasteners add weight or create stress concentrations. Two-part systems lead volume consumption due to tunable cure rates and superior bond durability in harsh environments. Structural adhesives within this category command premium positioning as they replace welding in automotive body-in-white and wind turbine blade manufacturing. Liquid formulations remain the standard for automated dispensing in high-throughput electronics and automotive plants.
REACH registration requirements and the EU F-Gas Regulation constrain formulation chemistry, while CE marking mandates performance disclosure for construction applications. EMA guidelines on medical device adhesives and ECHA restrictions on bisphenol-A derivatives are redirecting R&D toward non-toxic hardener alternatives. Stakeholders must monitor regulatory divergence between EU member states and Middle Eastern import standards as Gulf states develop localized construction codes. Procurement teams face decisions on whether to qualify multiple regional formulations or pursue unified product platforms that satisfy the strictest jurisdiction.
Market Dynamics
Automotive OEMs across Germany and France are dismantling welded body-in-white architectures in favor of bonded structural assemblies, compressing cure cycles and forcing hardener suppliers to co-locate near assembly plants.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding fleet emission targets push French and German automakers toward adhesive-intensive multi-material designs that shed kilograms from electric vehicle platforms.
- Wind turbine blade manufacturing:EMEA offshore wind installation targets exceeding 100 GW by 2030 require epoxy-bonded composite spar caps and root joints that withstand cyclonic loading.
- Rhine-Ruhr industrial corridor concentration:Chemical formulators cluster near BASF and Covestro feedstock facilities, shortening hardener logistics loops and enabling just-in-time resin blending.
Market Restraints
- Epichlorohydrin feedstock volatility:Propylene-derived raw material costs swing with European naphtha cracking economics, squeezing formulation margins unpredictably.
- ECHA bisphenol-A derivative restrictions:Candidate list classifications threaten standard diglycidyl ether formulations, forcing expensive toxicological dossier updates.
- Polyurethane structural adhesive substitution:Sika and Huntsman promote moisture-curing PU systems for automotive panel bonding with faster green strength development.
Strategic Opportunities
- Saudi Arabia and UAE construction codes:Gulf states are localizing infrastructure standards, creating openings for European formulators to certify products under emerging MOHAP and SFDA pathways.
- Bio-based epoxide feedstocks:Epichlorohydrin from glycerol rather than propylene qualifies for EU taxonomy-aligned project finance, attracting sustainability-linked capital.
- Two-part cartridge dispensing automation:Robotics integrators in northern Italy are bundling adhesive metering with vision-guided application for small-batch aerospace components.
Industry Challenges
- REACH registration data gap:SME formulators lack toxicology departments to complete substance volume dossiers for novel hardener chemistries, delaying commercialization.
- Multi-material bonding certification:OEMs demand 15-year durability warranties on aluminum-to-carbon-fiber joints without standardized accelerated aging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Epoxy Adhesives Market |
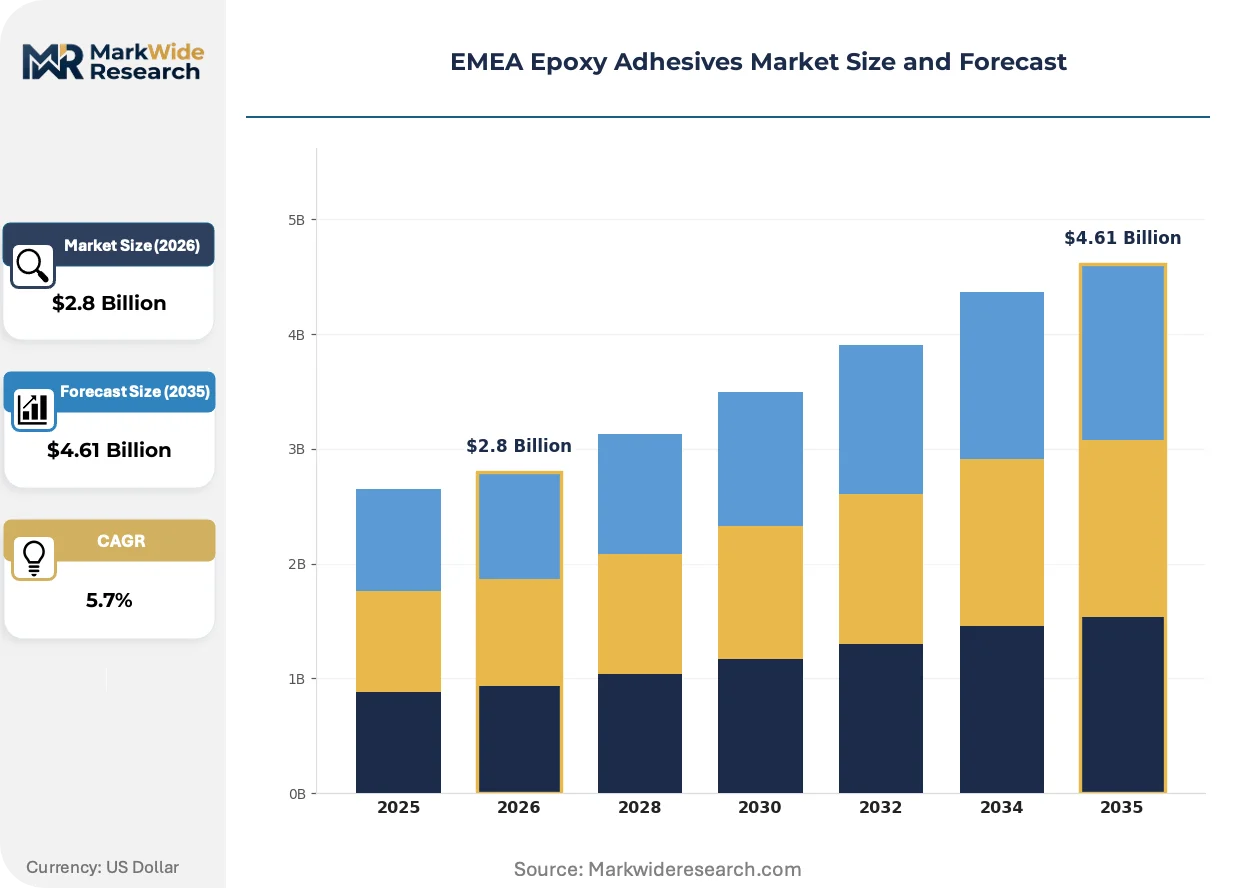
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-Part, Two-Part, Hot Melt, Structural End Use Industry: Aerospace, Automotive, Electronics, Construction Application: Bonding, Coating, Sealing, Potting Form: Liquid, Paste, Foam, Solid |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, 3M Company, Dow Inc., Arkema Group, Parker Hannifin Corp., Mapei S.p.A., Permabond LLC, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Epoxy Adhesives Market Evolving Landscape
Formulation chemistry and application hardware are converging to enable thinner bondlines and faster throughput in automated assembly environments.
Fast-cure anhydride hardener systems are miniaturizing automotive body shop footprints by enabling 90-second fixture times at 120°C, permitting BMW and Mercedes-Benz plants to eliminate large welding stations. Tier-1 suppliers are retrofitting existing lines rather than building greenfield capacity, compressing capital deployment cycles from 18 months to 6 months.
REACH authorization requirements for cycloaliphatic amines are redirecting R&D toward non-toxic alternatives, with ECHA's SVHC candidate list expansion forcing formulators to pre-register replacement chemistries before 2027 sunset dates. Construction-grade epoxies face heightened disclosure obligations under CE marking Annex ZA, pushing Mapei and similar suppliers to publish environmental product declarations for Mediterranean infrastructure tenders.
Buyers in the EMEA aerospace supply chain are consolidating adhesive specifications across Airbus A320 and A350 programs, eliminating qualified supplier lists in favor of single-source platform agreements. Tier-2 converters must now maintain dual certifications under EN 9100 and customer-specific bonding process specifications, raising barriers for smaller compounders serving the Toulouse and Hamburg assembly clusters.
EMEA Epoxy Adhesives Market Segmentation
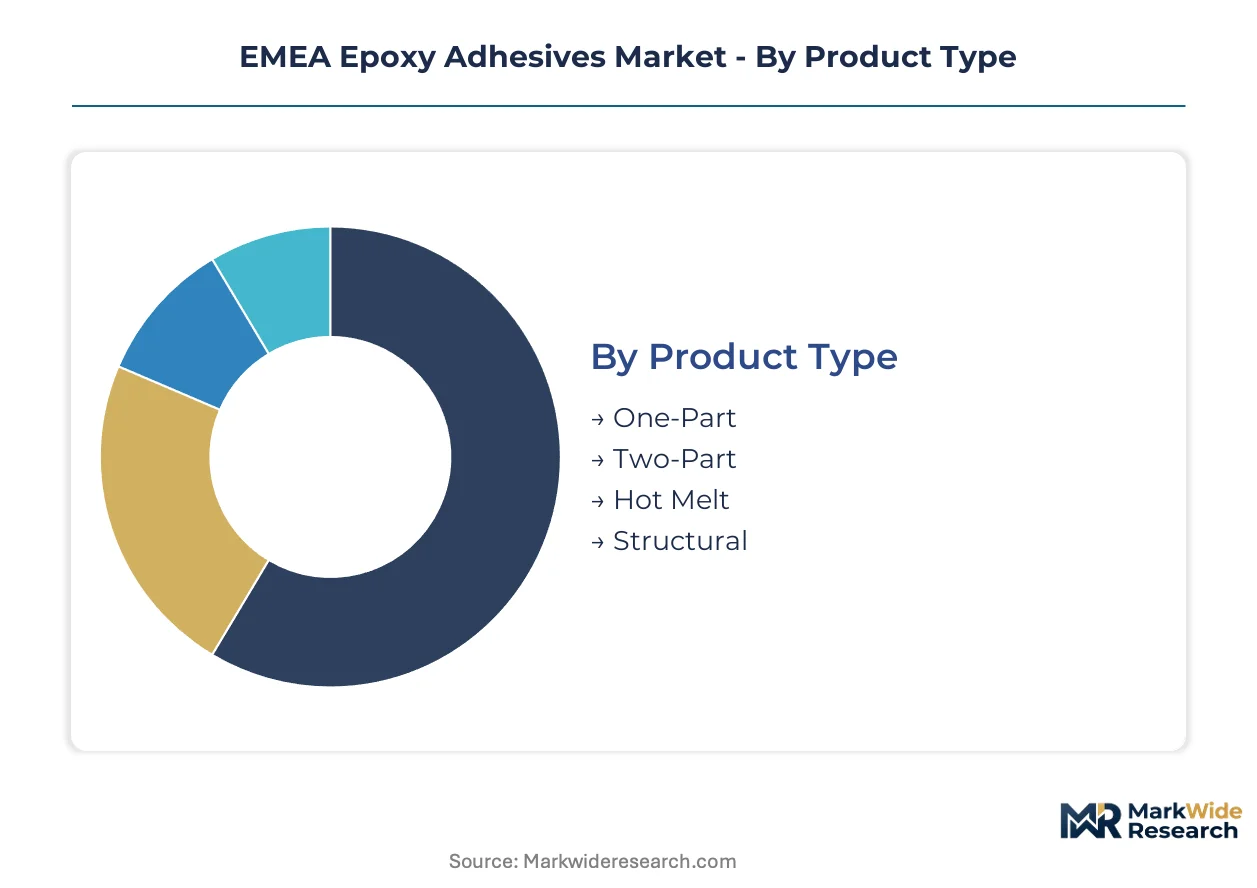
Epoxy adhesive specifications diverge sharply across EMEA regulatory jurisdictions, with REACH substance restrictions and CE marking performance tiers forcing formulators to maintain parallel product architectures. Segmentation discipline separates commodity construction grades from aerospace-qualified systems that command certification premiums.
Product Type:
REACH authorization timelines and cure chemistry determine which product architectures qualify for high-volume automotive and aerospace contracts.
- Two-Part:Epoxide resin and polyamine hardener cure through exothermic cross-linking, delivering shear strengths above 20 MPa. German automotive OEMs specify these systems for aluminum-to-carbon-fiber bonding in electric vehicle platforms, driven by EU Green Deal weight reduction mandates. Two-Part handles the majority of throughput; Structural is the fastest mover on share.
- Structural:Load-bearing formulations replace welding in body-in-white assemblies and wind turbine blade manufacturing. French and German OEMs demand 15-year durability warranties on bonded joints, pushing qualification cycles beyond 24 months. Structural commands premium positioning as OEMs dismantle welded architectures.
- One-Part:Pre-catalyzed systems eliminate mixing errors in high-throughput electronics plants across the Rhine-Ruhr corridor.
- Hot Melt:Thermoplastic formulations serve temporary fixturing applications in northern Italian automotive supply chains.
Formulators optimize cure kinetics around specific hardener chemistries to satisfy ECHA SVHC compliance deadlines.
End Use Industry:
Customer procurement patterns split between long-term aerospace platform agreements and spot-market construction purchasing.
- Automotive:BMW and Mercedes-Benz plants compress cure cycles to 90 seconds at 120°C, eliminating welding stations in favor of bonded multi-material designs. EMEA OEMs face binding fleet emission targets that kilogram-for-kilogram favor adhesive-intensive electric vehicle architectures. Automotive concentrates the highest formulation R&D investment.
- Construction:Mediterranean infrastructure tenders under CE marking Annex ZA require environmental product disclosures from suppliers like Mapei. Italian and Spanish public works projects specify epoxy systems for concrete repair and structural reinforcement. Construction offers the broadest geographic diversification.
- Aerospace:Airbus A320 and A350 programs consolidate adhesive specifications, forcing Tier-2 converters to maintain dual EN 9100 and customer-specific certifications.
- Electronics:Automated dispensing lines in Netherlands and Germany semiconductor packaging favor low-viscosity liquid formulations with precise pot life control.
Automotive procurement dominates volume commitments; aerospace specifications are climbing the fastest on qualification rigor.
Application:
Functional requirements dictate hardener selection and cure protocols across manufacturing environments.
- Bonding:Structural assembly of dissimilar materials—aluminum, carbon fiber, composites—demands tailored surface preparation and primer systems. German wind turbine manufacturers bond composite spar caps and root joints for offshore installations exceeding 100 GW targets. Bonding anchors the largest installed base.
- Potting:Electronics encapsulation protects sensitive components from thermal cycling and moisture ingress. Dutch and German semiconductor packaging operations specify low-stress formulations that minimize warpage during cure. Potting exhibits the steepest expansion trajectory.
- Sealing:Fluid containment applications in automotive powertrains and industrial equipment favor flexible modified epoxies.
- Coating:Protective layers for concrete and metal substrates concentrate in Mediterranean infrastructure rehabilitation projects.
Bonding commands the deepest formulation expertise; potting is gaining share fastest in electronics verticals.
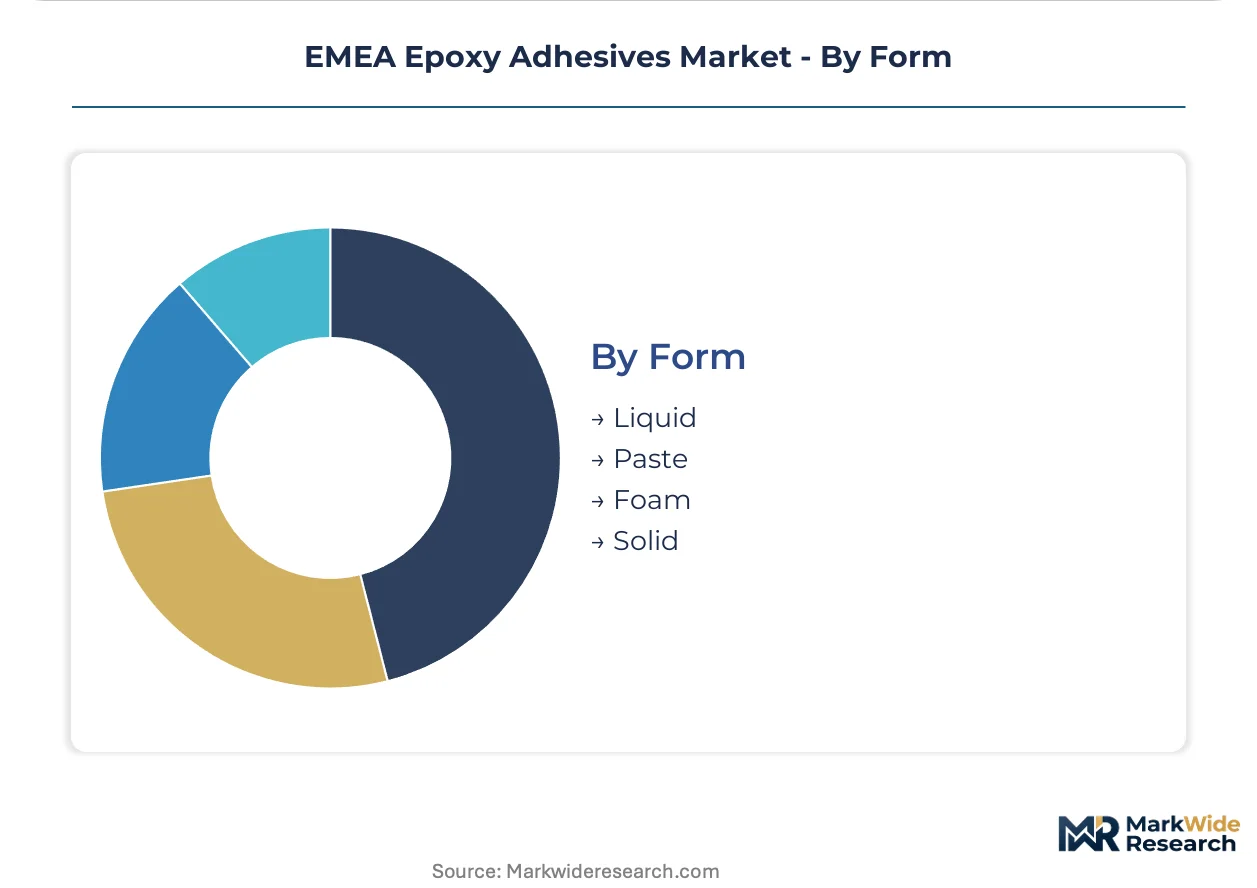
Form:
Physical state determines dispensing equipment requirements and automation compatibility.
- Liquid:Low-viscosity systems enable automated meter-mix-dispense in high-throughput automotive and electronics plants. Northern Italian robotics integrators bundle liquid adhesive metering with vision-guided application for small-batch aerospace components. Liquid dominates automated production lines.
- Paste:Thixotropic formulations maintain position on vertical surfaces in construction and marine applications. Mediterranean contractors specify pastes for overhead concrete repairs and structural reinforcement. Paste offers the most versatile manual application.
- Foam:Expandable systems fill voids and provide structural reinforcement in composite manufacturing.
- Solid:Film adhesives serve pre-impregnated composite layups in aerospace and wind energy applications.
Liquid formulations handle the highest throughput volumes; paste grades are expanding most quickly in infrastructure rehabilitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in epoxy adhesive formulation, connecting BASF's Ludwigshafen complex to industrial consumers across the continent.
Germany
BMW and Mercedes-Benz plants in Bavaria and Baden-Württemberg specify 90-second cure cycles for aluminum-to-carbon-fiber bonding in electric vehicle platforms. The KBA enforces type approval standards for structural adhesives in automotive crash structures. The Rhine-Ruhr manufacturing cluster hosts Covestro and Henkel facilities that blend resins and hardeners for just-in-time delivery to Stuttgart and Munich assembly lines.
France
Airbus A320 and A350 programs in Toulouse consolidate adhesive specifications, forcing Tier-2 converters to maintain dual EN 9100 and customer-specific certifications. ANSM monitors chemical substance registrations under REACH implementation timelines. The Hauts-de-France region anchors wind turbine blade manufacturing for offshore installations targeting capacity additions through 2030.
Italy
Mediterranean infrastructure tenders under CE marking Annex ZA require environmental product disclosures from construction-grade suppliers. The Ministry of Infrastructure and Transport mandates performance testing for structural reinforcement applications. Northern Italian robotics integrators in Emilia-Romagna bundle adhesive metering with vision-guided application systems for small-batch aerospace components.
United Arab Emirates
MOHAP and SFDA are localizing construction and medical device standards, creating certification pathways for European formulators. Dubai's logistics free zones offer bonded warehousing for epoxy systems destined for Saudi infrastructure projects. The Jebel Ali port complex handles bulk resin imports that supply Gulf Cooperation Council fabrication facilities.
Saudi Arabia
NEOM and Red Sea Project developments specify imported epoxy systems for concrete repair and structural bonding in coastal environments. The Saudi Standards, Metrology and Quality Organization is drafting localized construction codes that reference European performance benchmarks. Eastern Province industrial cities host joint ventures that blend European formulations for regional infrastructure deployment.
EMEA Epoxy Adhesives Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and application equipment integration. The vendor base clusters around three tiers: diversified chemical conglomerates with captive resin supply, adhesive-focused specialists with deep vertical integration into hardener synthesis, and regional compounders serving construction spot markets. Strategic moves concentrate on co-location near automotive assembly plants and qualification for Airbus platform agreements.
Within the diversified chemical tier, Henkel AG & Co. KGaA and Dow Inc. exemplify scale-driven positions that span resin production through automated dispensing systems. Sika AG occupies a specialist position emphasizing two-part systems for demanding structural applications. These three entities represent distinct competitive archetypes: full-value-chain control, application-technology bundling, and formulation specialization for premium certification tiers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| 3M Company |
| Dow Inc. |
| Arkema Group |
| Parker Hannifin Corp. |
| Mapei S.p.A. |
| Permabond LLC |
| Others |
Value Network & Pricing Analysis
REACH substance authorization timelines gate both supplier qualification windows and price tier eligibility, compressing commercialization cycles for novel hardener chemistries while stratifying premiums for pre-registered formulations. Automotive OEMs in Stuttgart and Munich pay certification premiums for systems with completed toxicology dossiers, whereas construction buyers in Mediterranean markets face disclosure-driven cost adders under CE marking Annex ZA.
Pricing Analysis
Three-tier pricing structure across aerospace-qualified, automotive-performance, and construction-commodity levels governs transaction terms. Price differentiation hinges on EN 9100 certification status and volume scale, with Airbus platform agreements commanding double-digit premiums over spot construction purchases. Cost compression in construction-grade segments is intensifying because Mapei and regional compounders compete on environmental product declaration transparency. Tier-1 automotive buyers exhibit lowest price sensitivity due to 15-year warranty requirements, while Mediterranean infrastructure contractors negotiate aggressively on per-kilogram metrics.
Supply Chain Analysis
Just-in-time resin blending dominates automotive supply relationships, whereas wind turbine manufacturers maintain strategic stockpiles of cycloaliphatic amines against ECHA authorization uncertainty. Geographic supply concentration centers on Germany, Belgium, and the Netherlands, where BASF and Covestro facilities feed the Rhine-Ruhr manufacturing cluster. Raw material dependencies draw from propylene-derived epichlorohydrin and bisphenol-A feedstocks, with glycerol-based bio-epoxies emerging as taxonomy-aligned alternatives. Single-source vulnerability around cycloaliphatic amine hardeners poses structural risk as sunset dates approach. Distribution runs through chemical distributor networks for construction spot markets and direct mill-to-plant pipelines for automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal decarbonization mandates are accelerating adhesive substitution for welded assemblies faster than hardener suppliers can qualify replacement chemistries, creating a supply-constrained expansion window. This regulatory-technology inflection compresses competitive response times across formulation and equipment integration.
For Market Incumbents: Consolidate captive resin supply positions through backward integration into epichlorohydrin production or long-term offtake agreements with Ludwigshafen and Antwerp feedstock facilities. Lock in Airbus platform exclusivity before Tier-2 converters achieve dual EN 9100 certification. Defend against polyurethane substitution by co-locating technical service teams at BMW and Mercedes-Benz body shops to compress cure cycle optimization feedback loops. For New Entrants and Emerging Players: Lead with bio-based epoxide formulations qualifying for EU taxonomy-aligned project finance, targeting sustainability-linked infrastructure tenders in Italy and Spain. Penetrate the Gulf Cooperation Council construction vertical through MOHAP and SFDA certification partnerships with Dubai logistics free zone operators. Deploy cartridge dispensing automation bundles for small-batch aerospace components in Emilia-Romagna as the go-to-market wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates divesting non-core adhesive divisions lacking aerospace qualification depth. Long-term viability favors specialists with captive hardener synthesis and applicator equipment integration. Monitor ECHA SVHC candidate list expansion velocity as the inflection signal—accelerated classifications would strand toxicological dossier investments and revalue compliant formulation platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Secures propylene-derived feedstock supply against European naphtha cracking volatility for German formulators. |
| Aerospace Platform Exclusivity Agreement | Locks in Airbus A350 specification consolidation before Tier-2 competitors complete EN 9100 certification cycles. |
| Bio-Based Formulation Certification | Qualifies glycerol-derived epoxies for EU taxonomy project finance in Mediterranean infrastructure tenders. |
| Gulf Regulatory Certification Pathway | Establishes MOHAP and SFDA compliance for European suppliers targeting NEOM and Red Sea Project developments. |
| Automotive Co-Location Partnership | Positions technical service teams at BMW and Mercedes-Benz plants to optimize 90-second cure cycle parameters. |
Research Methodology
Desk research of ECHA substance registration databases, CE marking technical files, and customs trade flows preceded structured interviews with automotive platform engineers, wind turbine blade manufacturing directors, construction procurement leads at Mediterranean infrastructure contractors, and adhesive R&D directors at German chemical conglomerates. Secondary validation drew from SEC 10-K chemical segment disclosures, Cefic industry reports, and EN 9100 certification registries. Bottom-up volume estimates from end-use industry consumption patterns triangulated against top-down formulation capacity assessments across the Rhine-Ruhr corridor.
Variance decomposition across product type, end-use industry, application method, and regional regulatory cluster informed the analytical framework over the projection horizon. Segmentation dimensions modeled include cure chemistry architecture, certification tier, and automation compatibility. CAGRs were derived from regression analysis of historical consumption against electric vehicle production forecasts and offshore wind installation targets. Industry-specific forecast inputs incorporated ECHA authorization timeline probabilities and EU taxonomy alignment scoring for bio-based feedstock alternatives.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated ECHA sunset schedules would require recalibration. Forecasts assume stable propylene cracking economics and no abrupt bisphenol-A derivative prohibitions. Revision becomes warranted when REACH authorization delays for novel hardener chemistries cross 24-month qualification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market