
 Middle East and Africa Rigid Plastic Packaging Market | 2026-2036
Middle East and Africa Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Rigid Plastic Packaging Market Insights
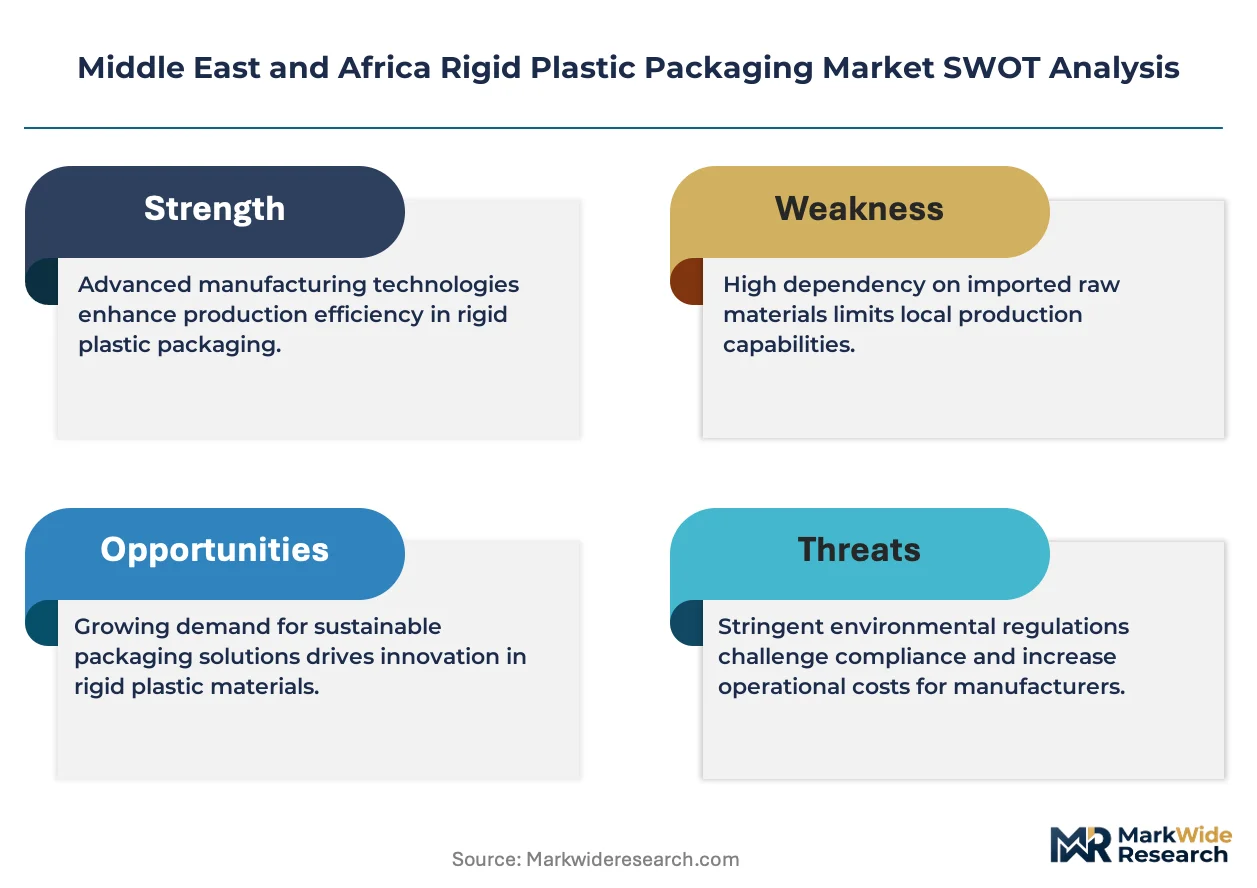
Saudi Arabia's petrochemical downstream expansion is rewriting regional supply dynamics for rigid plastic packaging feedstocks. SABIC leverages its integrated polyethylene and polypropylene production to anchor container supply across Gulf markets. ALPLA Group sustains manufacturing scale through dedicated blow-molding operations in Egypt and South Africa. Amcor Group GmbH competes on pharmaceutical-grade barrier technology for healthcare applications.
Middle East and Africa rigid plastic packaging comprises thermoformed or injection-molded containers, bottles, jars, and trays engineered from polyethylene, polypropylene, PVC, or PET with wall thicknesses typically exceeding 0.25 millimeters to provide structural integrity during filling, transport, and retail display. PET bottles dominate beverage applications due to clarity, barrier performance, and recyclability alignment with Gulf sustainability mandates. Polypropylene containers lead food packaging margins through microwave-safe temperature resistance and growing ready-meal penetration in urban Egyptian and Nigerian markets. Pharmaceutical jars and blister trays command premium positioning as healthcare infrastructure expands across sub-Saharan Africa.
Saudi Arabia's SFDA and South Africa's NRCS enforce pharmaceutical packaging integrity standards that elevate barrier specifications and traceability requirements. Egypt's Ministry of Environment implements extended producer responsibility frameworks affecting post-consumer PET collection targets for bottling operations. The EU Green Deal's extraterritorial influence on North African export-oriented manufacturers accelerates recycled content verification protocols. Stakeholders must monitor diverging national implementation timelines for circular economy legislation while calibrating capital allocation between virgin resin integration and mechanical recycling infrastructure.
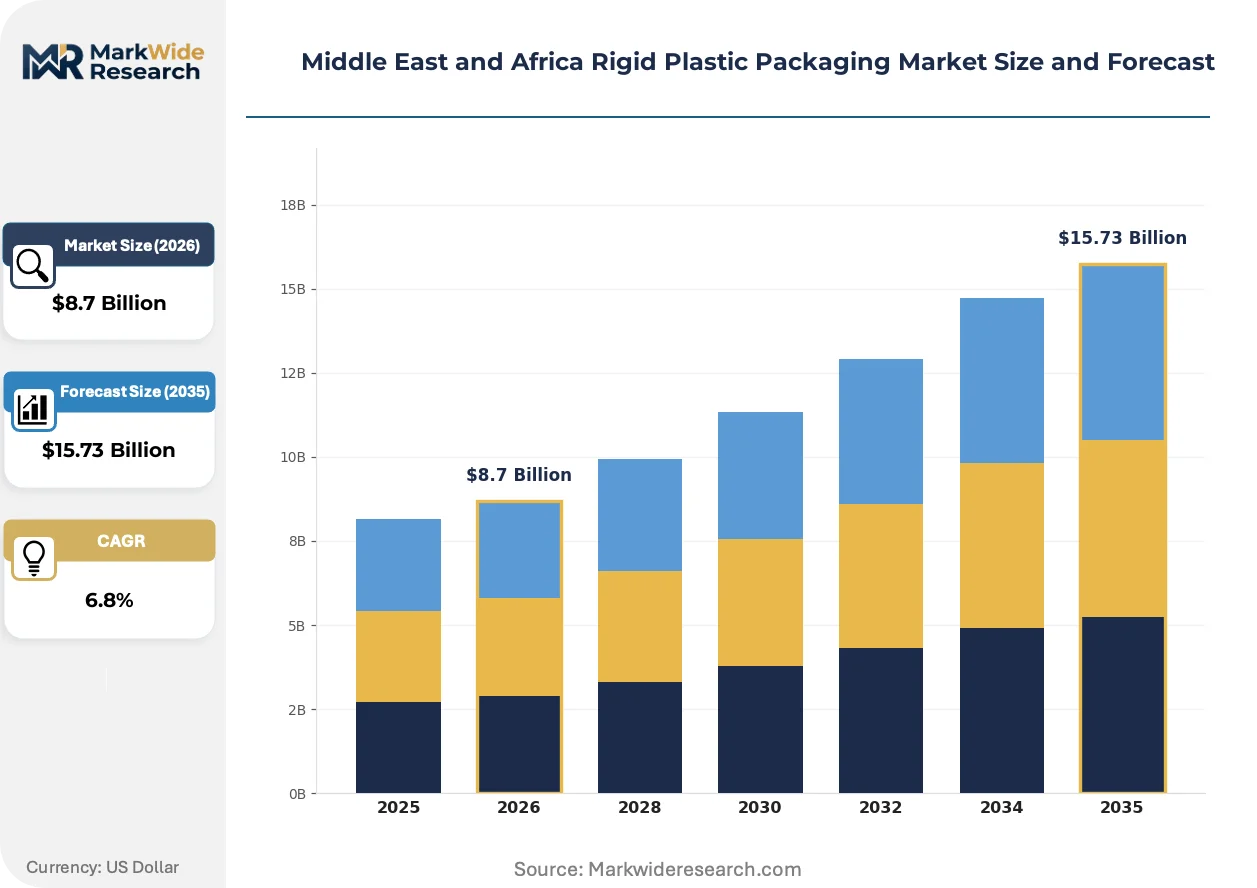
Market Dynamics
Saudi petrochemical capacity expansion is restructuring feedstock economics across Gulf rigid plastic packaging supply chains. SABIC's integrated polyethylene and polypropylene complexes now supply container-grade resins at cost positions unattainable by import-dependent African converters.
Growth Catalysts
- Egypt's Extended Producer Responsibility mandates:Post-consumer PET collection targets are forcing bottling operations to invest in mechanical recycling infrastructure, creating captive recycled flake supply.
- Pharmaceutical packaging demand:South Africa's healthcare infrastructure expansion is elevating barrier specifications for blister trays and jars across sub-Saharan distribution networks.
- Polypropylene microwave-safe containers:Ready-meal penetration in urban Nigerian and Egyptian markets is displacing traditional packaging formats through temperature-resistant food service applications.
Market Restraints
- Crude-linked resin volatility:Polyethylene and polypropylene pricing tied to naphtha cracking economics exposes converters to input cost swings that compress margin visibility.
- Gulf feedstock concentration:SABIC and regional petrochemical majors control virgin resin supply, limiting bargaining power for independent blow-molding operations in Egypt and South Africa.
- Mechanical recycling yield limitations:Contamination rates in post-consumer PET collection streams restrict food-grade recycled content incorporation below pharmaceutical and beverage sector thresholds.
Strategic Opportunities
- Nigeria's underpenetrated food service channel:Quick-service restaurant expansion in Lagos and Abuja is creating demand for standardized polypropylene takeaway containers with lid-sealing reliability.
- EU Green Deal extraterritorial compliance:North African export-oriented manufacturers serving European beverage brands must verify recycled content, opening technical consulting and certification service revenue.
- Digital printing convergence with barrier coating:Sleeve labeling technology combined with oxygen-scavenging PET formulations enables premium dairy and juice differentiation without aluminum foil lamination.
Industry Challenges
- SFDA pharmaceutical traceability compliance:Saudi Arabia's serialization requirements for blister packaging demand capital investment in vision inspection and aggregation systems that strain mid-cap converter balance sheets.
- Collection infrastructure fragmentation:Egypt's informal waste sector dominates post-consumer PET recovery, creating quality inconsistency that complicates food-grade mechanical recycling scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Rigid Plastic Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays End User: Food, Beverage, Personal Care, Pharmaceutical Material: Polyethylene, Polypropylene, PVC, PET Application: Food Packaging, Industrial Packaging, Healthcare Packaging, Retail Packaging |
| Companies Covered | SABIC, ALPLA Group, Amcor Group GmbH, Berry Global, Sealed Air, Plastipak Holdings, Greiner Packaging, Nampak Ltd., Al Jabri Plastics, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Rigid Plastic Packaging Market Trends and Innovations
Lightweighting and mono-material design are converging with circular economy mandates to redefine rigid plastic packaging specifications across Middle East and African manufacturing bases.
Mono-material PET bottle structures incorporating tethered caps and full-body sleeve labels are collapsing separation complexity at mechanical recycling facilities. European beverage brands sourcing from North African contract manufacturers are mandating these designs to meet EU Green Deal recyclability verification protocols. Gulf-based converters are retrofitting blow-molding lines to accommodate these specifications ahead of anticipated Saudi regulatory alignment.
Egypt's Ministry of Environment extended producer responsibility frameworks are accelerating post-consumer collection target enforcement with 2025 compliance windows. Bottling operations must now integrate recycled PET at specified thresholds or face market access restrictions. Pharmaceutical packaging remains exempt, creating a two-tier regulatory environment that favors healthcare-focused converters.
Quick-service restaurant procurement consolidation in urban Egyptian and Nigerian markets is compressing supplier qualification timelines. National chains are unbundling packaging specification from equipment supply, forcing rigid plastic container manufacturers to certify directly with franchise operators rather than through distributor intermediaries. This disintermediation is most visible in Cairo and Lagos metropolitan procurement offices where technical audits now precede volume commitments.
Middle East and Africa Rigid Plastic Packaging Market Segmentation
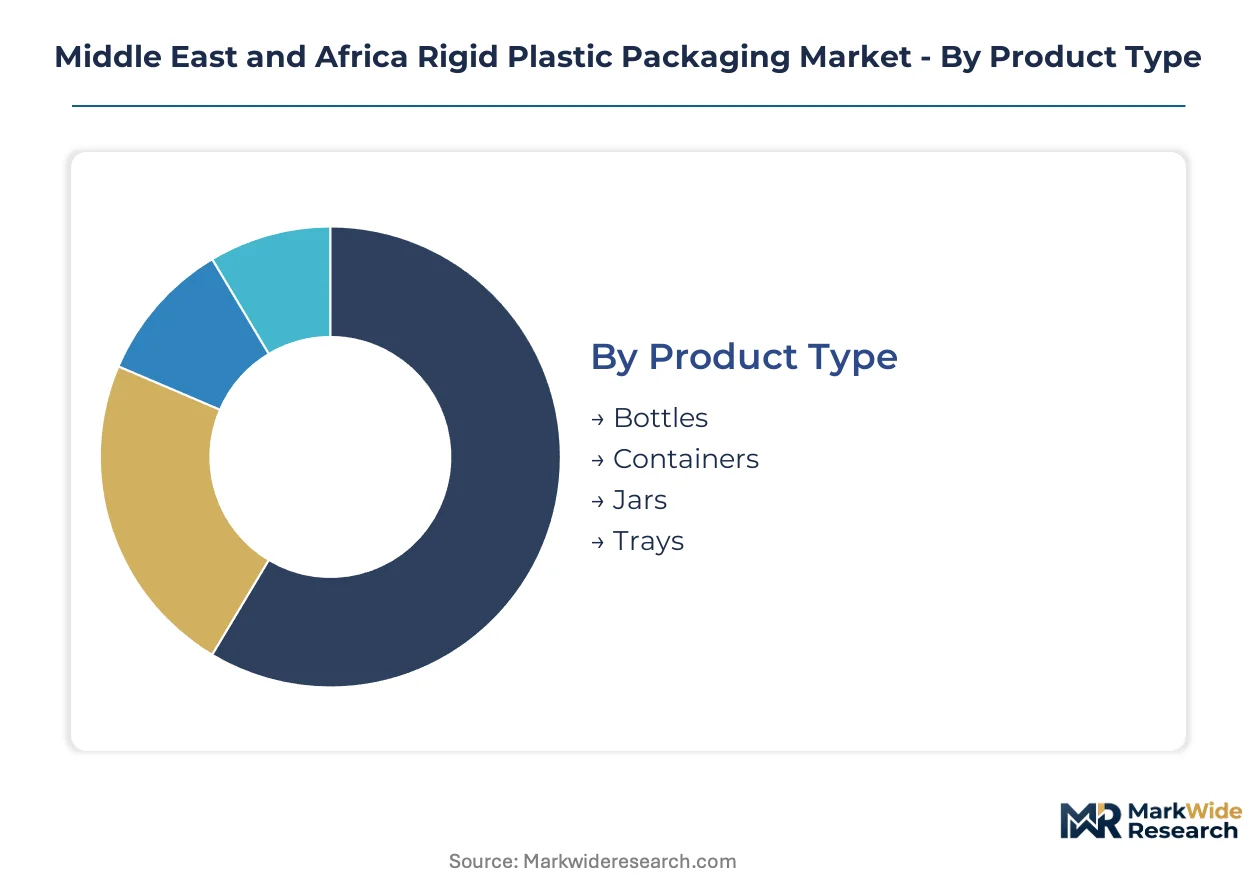
Rigid plastic packaging demand across the Middle East and Africa fragments along material specifications, container geometry, and end-use compliance requirements. Each dimension carries distinct margin profiles and capital intensity thresholds that reshape converter positioning.
Product Type:
Container geometry determines blow-molding versus thermoforming capital allocation and line flexibility across converter footprints.
- Bottles:PET beverage bottles with tethered cap designs dominate volume throughput at Gulf-based operations serving carbonated soft drink and bottled water brands. Egyptian and Nigerian bottling corridors are retrofitting lines for mono-material structures to meet EU Green Deal recyclability verification for export-bound production.
- Containers:Polypropylene microwave-safe tubs command premium positioning in Egyptian and Nigerian ready-meal channels where temperature resistance and lid-sealing reliability determine supplier qualification. Quick-service restaurant procurement consolidation in Lagos and Cairo is compressing technical audit timelines for container manufacturers.
- Jars:Wide-mouth PET and polypropylene jars serve pharmaceutical and personal care applications across South African healthcare distribution networks with barrier specifications elevated by SFDA and national pharmaceutical regulator mandates.
- Trays:Thermoformed PET and PVC blister trays concentrate in South African pharmaceutical packaging expansion, with barrier coating requirements for moisture-sensitive drug formulations driving specification differentiation.
Bottles hold installed capacity. Containers are rotating up the share rankings.
End User:
Customer compliance requirements split the market between commodity beverage throughput and regulated healthcare barrier specifications.
- Food:Polypropylene containers and PET trays serve ready-meal and fresh produce segments across Egyptian and Nigerian urban retail expansion, with microwave-safe temperature resistance displacing traditional packaging formats in Lagos and Cairo metropolitan procurement.
- Beverage:PET bottles capture carbonated soft drink, bottled water, and juice applications through clarity and recyclability alignment with Gulf sustainability mandates; Egyptian extended producer responsibility frameworks are forcing recycled content integration at specified thresholds.
- Personal Care:PET jars and bottles with decorative sleeve labeling serve shampoo, lotion, and cosmetic applications where digital printing convergence enables premium differentiation without aluminum foil lamination.
- Pharmaceutical:Blister trays, jars, and bottles with oxygen-scavenging and moisture-barrier specifications command premium positioning as South African healthcare infrastructure expands across sub-Saharan distribution networks; SFDA serialization requirements strain mid-cap converter balance sheets.
Beverage maintains volume leadership. Pharmaceutical is climbing the fastest.
Material:
Resin selection ties directly to Saudi petrochemical feedstock economics and mechanical recycling yield constraints across collection infrastructure.
- Polyethylene:HDPE and LDPE grades serve industrial pails, caps, and closures with cost positions anchored by SABIC integrated production; crude-linked naphtha cracking economics expose converters to input cost volatility.
- Polypropylene:Homopolymer and copolymer grades lead food packaging margins through microwave-safe temperature resistance and growing ready-meal penetration in urban Egyptian and Nigerian markets; Gulf feedstock concentration limits bargaining power for independent African converters.
- PVC:Rigid PVC concentrates in pharmaceutical blister tray applications with clarity and formability characteristics; regulatory scrutiny on chlorine content is compressing share in beverage and food contact segments.
- PET:Bottle-grade and sheet-grade PET dominates beverage clarity requirements and thermoformed tray applications; contamination rates in Egyptian informal waste collection streams restrict food-grade recycled content incorporation below pharmaceutical and beverage sector thresholds.
PET holds installed capacity. Polypropylene is gaining share fastest.
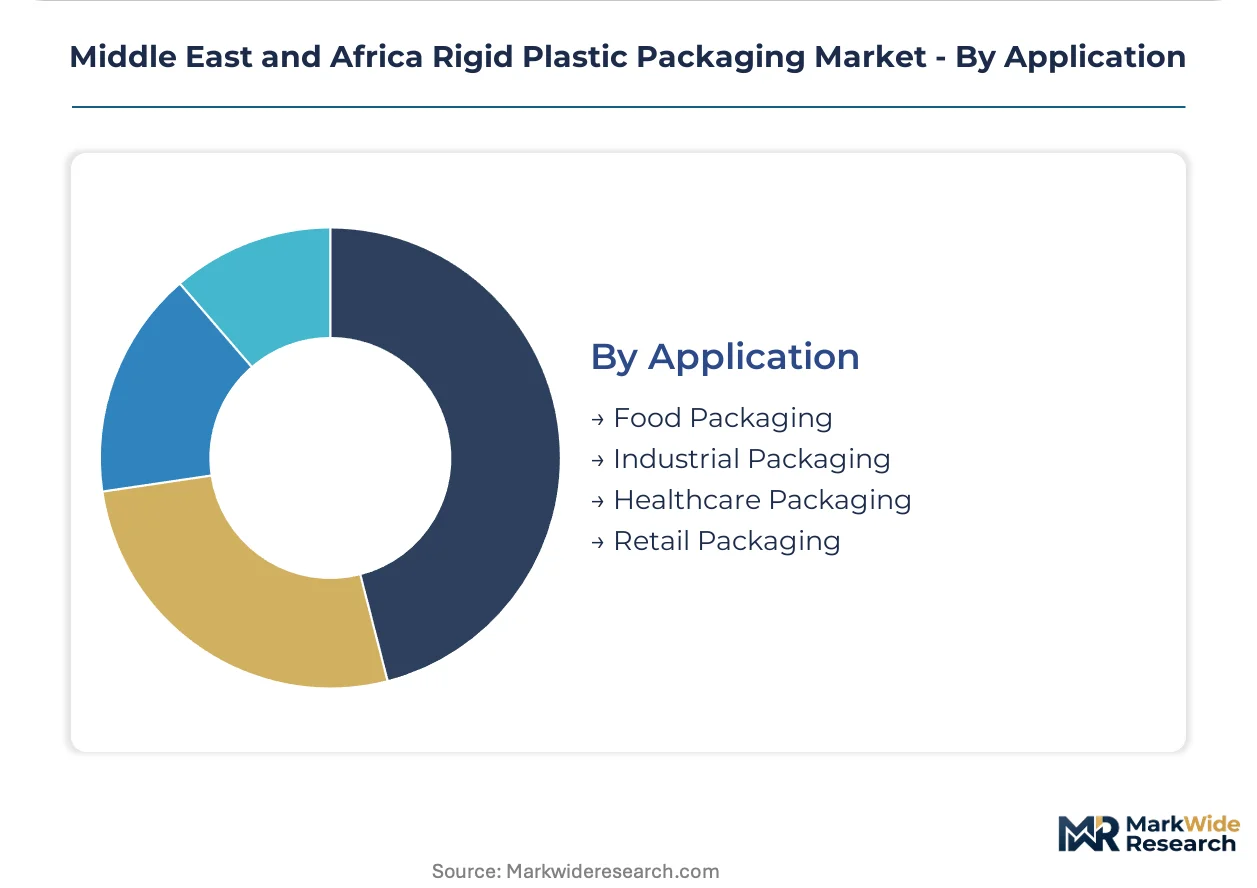
Application:
Use-case specifications determine barrier coating requirements, sterilization compatibility, and retail display structural integrity.
- Food Packaging:Polypropylene containers and PET trays serve fresh, chilled, and ready-meal segments with temperature resistance and clarity specifications; quick-service restaurant expansion in Lagos and Abuja is creating demand for standardized takeaway container formats.
- Industrial Packaging:HDPE pails, drums, and intermediate bulk containers serve chemical and lubricant applications with UN certification requirements for hazardous material transport across Middle East logistics corridors.
- Healthcare Packaging:Blister trays, pharmaceutical jars, and diagnostic containers demand barrier coatings and traceability systems; South Africa's healthcare infrastructure expansion is elevating specifications across sub-Saharan distribution networks.
- Retail Packaging:PET clamshells and display trays serve electronics and consumer goods with clarity and theft-deterrent structural designs; EU Green Deal extraterritorial influence accelerates recycled content verification for North African export-oriented manufacturers.
Food Packaging holds installed capacity. Healthcare Packaging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi petrochemical complexes anchor feedstock supply for Gulf rigid plastic packaging converters, while Egyptian and South African manufacturing corridors absorb resin flows into finished containers for domestic and export markets.
Saudi Arabia
SABIC's integrated polyethylene and polypropylene production supplies container-grade resins at cost positions unattainable by import-dependent African converters. SFDA pharmaceutical traceability mandates are forcing serialization investment across blister packaging operations. Riyadh and the Eastern Province host blow-molding facilities serving carbonated soft drink and bottled water brands with tethered-cap mono-material designs.
Egypt
Extended producer responsibility frameworks from the Ministry of Environment are mandating post-consumer PET collection targets with 2025 compliance windows. Bottling operations must integrate recycled content or face market access restrictions. Cairo metropolitan procurement offices are compressing supplier qualification timelines as quick-service restaurant chains unbundle packaging from equipment supply.
South Africa
Healthcare infrastructure expansion is elevating barrier specifications for pharmaceutical jars and blister trays across sub-Saharan distribution networks. NRCS pharmaceutical packaging integrity standards enforce traceability requirements that strain mid-cap converter balance sheets. Johannesburg and Durban corridors concentrate thermoforming operations serving regional healthcare supply chains.
Nigeria
Quick-service restaurant expansion in Lagos and Abuja is creating demand for standardized polypropylene takeaway containers with lid-sealing reliability. Ready-meal penetration in urban markets is displacing traditional packaging formats through microwave-safe temperature resistance. Local converters face feedstock cost volatility tied to naphtha cracking economics and import-dependent resin supply.
UAE
Dubai and Abu Dhabi logistics hubs facilitate re-export of rigid plastic packaging materials to African markets with underdeveloped domestic manufacturing bases. MOHAP pharmaceutical regulations align with Gulf harmonization initiatives, elevating barrier specifications for healthcare applications. Free zone manufacturing facilities serve European beverage brands requiring EU Green Deal recyclability verification.
Middle East and Africa Rigid Plastic Packaging Market Competitive Landscape
Petrochemical-integrated majors and independent converters split the market between feedstock-captive supply and flexible manufacturing scale. Saudi SABIC controls virgin resin economics through backward integration into naphtha cracking, limiting bargaining power for Egyptian and South African blow-molding operations. Three archetypes dominate: integrated petrochemical producers, regional multi-site converters, and healthcare-specialized barrier technology providers. Competitive moves center on mechanical recycling infrastructure investment and pharmaceutical-grade certification acquisition.
Within the petrochemical-integrated tier, SABIC anchors feedstock supply across Gulf markets. Among regional multi-site converters, ALPLA Group and Amcor Group GmbH exemplify scale-driven positioning. ALPLA's Egyptian and South African manufacturing footprint captures beverage and food service demand, while Amcor occupies a position in pharmaceutical-grade barrier technology for healthcare applications.
| Leading Market Players |
|---|
| SABIC |
| ALPLA Group |
| Amcor Group GmbH |
| Berry Global |
| Sealed Air |
| Plastipak Holdings |
| Greiner Packaging |
| Nampak Ltd. |
| Al Jabri Plastics |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Egyptian blow-molding corridors is compressing contract margins for import-dependent converters while Gulf-based operations leverage captive resin supply to maintain pricing discipline. This utilization asymmetry between Saudi-integrated and African-independent manufacturing bases is forcing procurement consolidation among beverage bottlers and quick-service restaurant chains.
Pricing Analysis
Egypt's extended producer responsibility mandates dictate the pricing tier structure across rigid plastic packaging procurement. Three-tier pricing separates pharmaceutical-grade barrier specifications from food-contact recycled content tiers and industrial commodity grades. Price differentiation rests on SFDA certification status and Gulf petrochemical feedstock access. Cost compression in standard-grade beverage containers is intensifying because Egyptian bottlers must fund mechanical recycling infrastructure to meet collection targets. Quick-service restaurant chains in Lagos and Cairo exhibit highest price sensitivity, while pharmaceutical distributors across sub-Saharan Africa accept premium positioning for serialization-compliant blister packaging.
Supply Chain Analysis
Upstream naphtha cracking economics in Saudi Arabia, Qatar, and Kuwait anchor polyethylene and polypropylene resin supply for regional converters. Raw material dependencies center on container-grade PET flake, homopolymer polypropylene, and pharmaceutical-barrier coating chemistries. Single-source vulnerability concentrates in SABIC-controlled virgin resin allocation, limiting bargaining leverage for Egyptian and South African blow-molding operations. Distribution runs through Dubai and Abu Dhabi logistics hubs for re-export to African markets with underdeveloped domestic manufacturing bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated quick-service restaurant procurement offices in Cairo and Lagos, where national chains now unbundle packaging specification from equipment supply and demand direct technical audits.
For Market Incumbents: Harden pharmaceutical-grade certification moats against mid-cap converters struggling with SFDA serialization investment requirements. Deepen captive recycled flake supply through mechanical recycling infrastructure in Egyptian bottling corridors before extended producer responsibility thresholds tighten. Anchor barrier technology leadership in South African healthcare distribution networks where NRCS standards are elevating specifications faster than regional competitors can adapt. For New Entrants and Emerging Players: Establish a beachhead in Nigerian polypropylene takeaway container supply by certifying lid-sealing reliability with quick-service restaurant procurement offices in Lagos and Abuja. Target underpenetrated ready-meal channels in urban Egyptian markets where microwave-safe temperature resistance commands premium positioning. Pursue EU Green Deal compliance consulting for North African export-oriented manufacturers serving European beverage brands. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among healthcare-specialized barrier technology providers with pharmaceutical serialization capabilities. Long-term viability over the next decade favors converters with integrated mechanical recycling infrastructure and Gulf petrochemical feedstock access. Monitor Egyptian Ministry of Environment enforcement timelines as the inflection signal for recycled content mandate stringency.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Infrastructure Investment | Egyptian bottling operations secure captive recycled PET flake supply ahead of extended producer responsibility deadlines. |
| Pharmaceutical Serialization Certification | SFDA compliance enables premium positioning in Saudi healthcare packaging procurement with elevated barrier specifications. |
| Mono-Material Design Retrofit | Gulf-based converters align blow-molding lines with EU Green Deal recyclability verification for European beverage brand contracts. |
| Quick-Service Restaurant Direct Certification | Container manufacturers bypass distributor intermediaries in Cairo and Lagos procurement offices to capture volume commitments. |
| Backward Integration into Virgin Resin Supply | Independent African converters reduce exposure to SABIC pricing power through upstream petrochemical partnerships. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this study. Plant managers at Egyptian and South African blow-molding operations, procurement leads at quick-service restaurant chains in Lagos and Cairo, technical R&D directors at Gulf petrochemical complexes, and distribution channel partners in Dubai free zones provided operational perspective. Secondary validation drew from customs and trade data, SEC filings of listed packaging converters, SABIC capacity disclosures, and Egyptian Ministry of Environment regulatory filings. Bottom-up volume modeling across material grades and container geometries was triangulated against top-down macroeconomic indicators.
Calibration against historical capacity utilization rates and resin price volatility patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material specification, container geometry, end-use compliance tier, and regional manufacturing corridor. CAGRs were derived from elasticity-adjusted demand curves and substitution dynamics between rigid plastic formats. Feedstock cost trajectories tied to naphtha cracking economics and recycled content mandate enforcement timelines served as industry-specific forecast inputs.
Stress conditions across crude-linked resin volatility, Egyptian collection infrastructure development, and SFDA regulatory stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about extended producer responsibility implementation timelines and Gulf petrochemical capacity expansion. Cross-checking against regional customs data and petrochemical producer disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Gable Top Packaging Market