
 Tray Sleeve Market | 2026-2036
Tray Sleeve Market Size, Share, and Industry Trends Forecast 2026-2036
Tray Sleeve Market Analytics
Pharmaceutical packaging is decoupling from food and beverage as the dominant demand anchor for tray sleeves, driven by serialization mandates and tamper-evident secondary containment requirements. DASE-SING Packaging Technology Co., LTD. leverages its automation expertise to dominate high-speed pharmaceutical line integrations across Asia-Pacific. Harikrushna Machines Pvt. Ltd. anchors its position through specialized equipment for Indian domestic contract packagers serving CDSCO-regulated facilities. Allen Plastic Industries Co., Ltd. competes on PET and polypropylene material science leadership for moisture-sensitive drug applications.
A tray sleeve is a pre-formed or roll-fed secondary packaging component that slides over or shrinks around rigid trays to secure, brand, or protect primary contents, typically manufactured through thermoforming, extrusion, or gravure printing processes with thicknesses ranging from 0.2 to 0.8 millimeters depending on barrier requirements. Paper-based sleeves are capturing share from PVC alternatives as ECHA REACH restrictions and EU Green Deal packaging waste directives tighten polymer acceptance criteria in European pharmaceutical channels. Shrink sleeves sustain premium positioning in cosmetic packaging due to 360-degree surface decoration capability and compatibility with irregular tray geometries. Standard sleeves occupy the volume base in food packaging, where cost minimization overrides customization needs.
FDA 21 CFR Part 211 cGMP requirements and EU MDR labeling mandates are forcing pharmaceutical packagers toward validated sleeve-to-tray adhesion systems with full batch traceability. China's SAMR and NMPA are aligning domestic pharmaceutical packaging standards with ICH Q9 quality risk management principles, creating compliance-driven replacement cycles for legacy sleeve formats. Stakeholders must monitor divergence between FDA serialization requirements and emerging EU AI Act supply chain transparency rules to avoid dual-certification cost burdens.
Market Dynamics
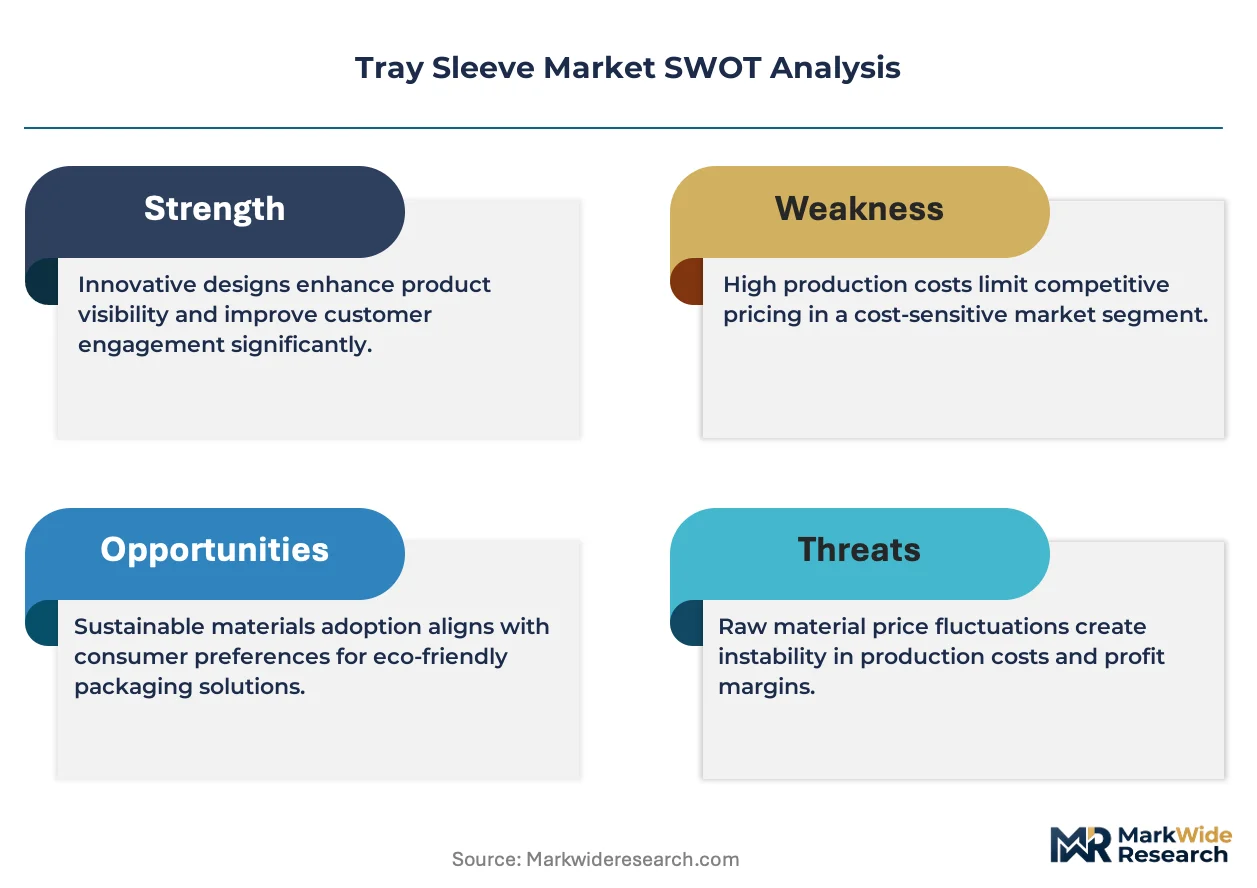
Pharmaceutical serialization mandates and ECHA REACH polymer restrictions are structurally bifurcating demand between validated paper-based sleeves for regulated drug packaging and commodity plastic formats for food logistics.
Growth Catalysts
- EU MDR labeling mandates:European medical device manufacturers are retrofitting packaging lines with tamper-evident sleeve systems to satisfy traceability requirements for Class II and III products.
- India PLI scheme incentives:Domestic contract packaging facilities are expanding printed sleeve capacity to capture government-backed pharmaceutical manufacturing subsidies.
- Paper barrier coatings:Water-based polymer treatments are extending moisture protection to cellulose substrates, enabling substitution of PVC in humidity-critical applications.
Market Restraints
- Petrochemical input volatility:Polypropylene and PET resin prices fluctuate with crude oil benchmarks, compressing margins for shrink sleeve converters serving cost-sensitive food channels.
- Equipment supplier concentration:High-speed pharmaceutical sleeve applicator production clusters in Taiwan and Germany, creating lead time vulnerability for emerging market packagers.
- Aluminum-laminate substitution:Cold-form blister foils retain dominance in ultra-high-barrier drug packaging, limiting sleeve penetration in oncology and biologic segments.
Strategic Opportunities
- Indonesia pharmaceutical packaging:ASEAN harmonization of medical device regulations is opening contract manufacturing demand for CDSCO-compliant sleeve formats.
- Shrink sleeve cosmetics:Premium personal care brands are adopting 360-degree printed sleeves for irregular tray geometries in gift sets and travel retail.
- China dual carbon goals:Provincial carbon intensity targets are accelerating paper sleeve adoption in domestic food e-commerce fulfillment networks.
Industry Challenges
- Validation engineering scarcity:Pharmaceutical packagers face shortages of technicians qualified to execute FDA 21 CFR Part 211 equipment qualification protocols for integrated sleeve-tray systems.
- Legacy gravure retooling:Converters with sunk capital in solvent-based printing infrastructure must navigate multi-year payback periods for water-based ink system conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray Sleeve Market |
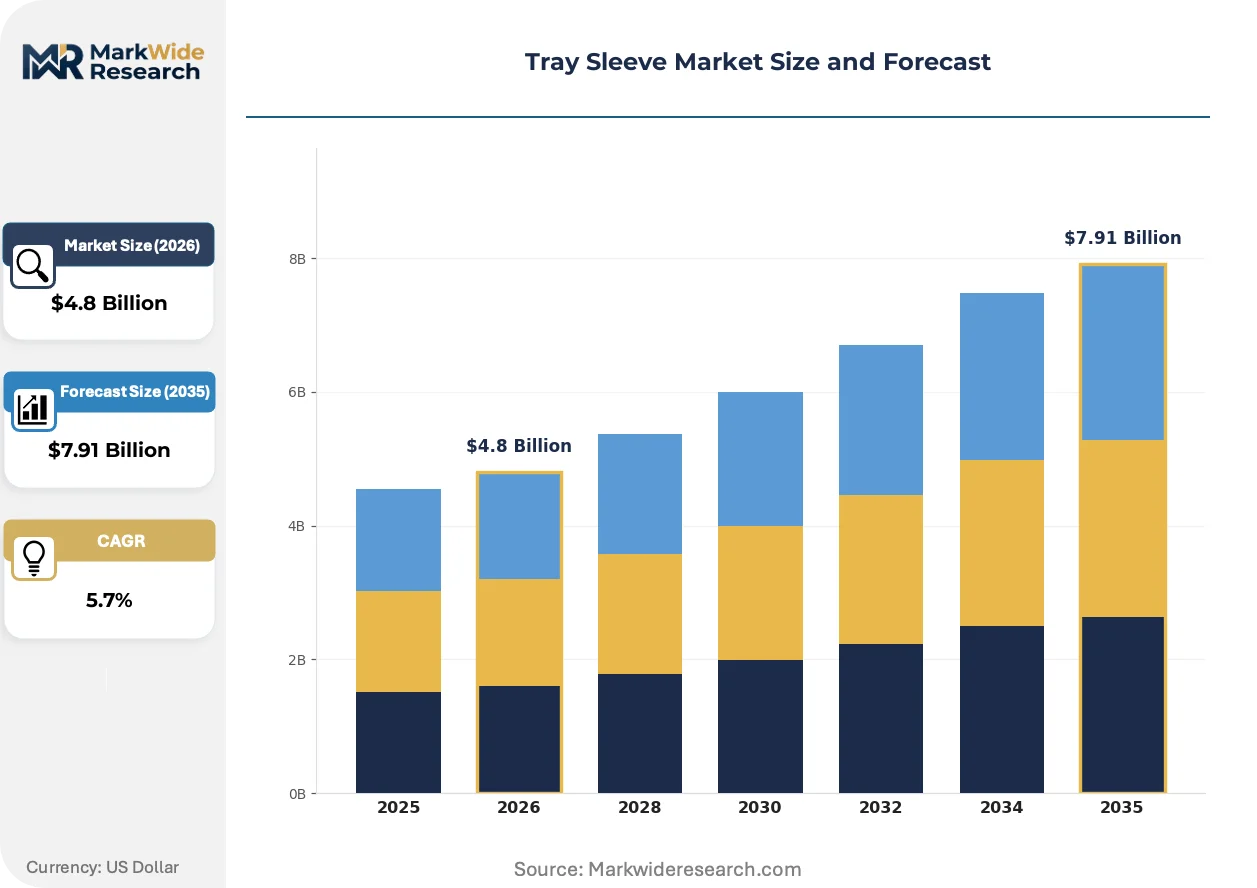
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, PET, Polypropylene, Paper Product Type: Standard Sleeves, Custom Sleeves, Printed Sleeves, Shrink Sleeves End Use: Food Packaging, Beverage Packaging, Cosmetic Packaging, Pharmaceutical Packaging Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | DASE-SING Packaging Technology Co., LTD., Harikrushna Machines Pvt. Ltd., Allen Plastic Industries Co., Ltd., Jet Container, World Centric, Cama Group, Brothers Pharmamach (India) Pvt. Ltd., Tycoon Packaging, Accutek Packaging Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray Sleeve Market Evolving Landscape
Digital printing and smart packaging integration are compressing production batch sizes while expanding variable data capabilities, forcing sleeve converters to reconfigure around shorter runs and mass customization.
Water-based flexographic printing is overtaking solvent gravure for medium-run pharmaceutical sleeves. European generic drug packagers are adopting these systems to reduce volatile organic compound emissions and enable rapid artwork changes for parallel trade requirements. This shift is compressing minimum order quantities from hundreds of thousands to tens of thousands of units.
EU AI Act supply chain transparency rules are mandating machine-readable packaging identifiers for high-risk product categories. Pharmaceutical sleeve producers must integrate QR codes and RFID inlays that link to batch-level provenance databases. German and French packagers are piloting combined serialization-smart sleeve systems to preempt dual-certification burdens.
Contract packaging organizations are consolidating sleeve procurement under outcome-based total cost of ownership frameworks. Indian CDSCO-regulated facilities now specify adhesion performance and line efficiency guarantees rather than unit pricing alone. This behavioral shift favors integrated equipment-material suppliers capable of validating complete sleeve-to-tray systems.
Tray Sleeve Market Segmentation
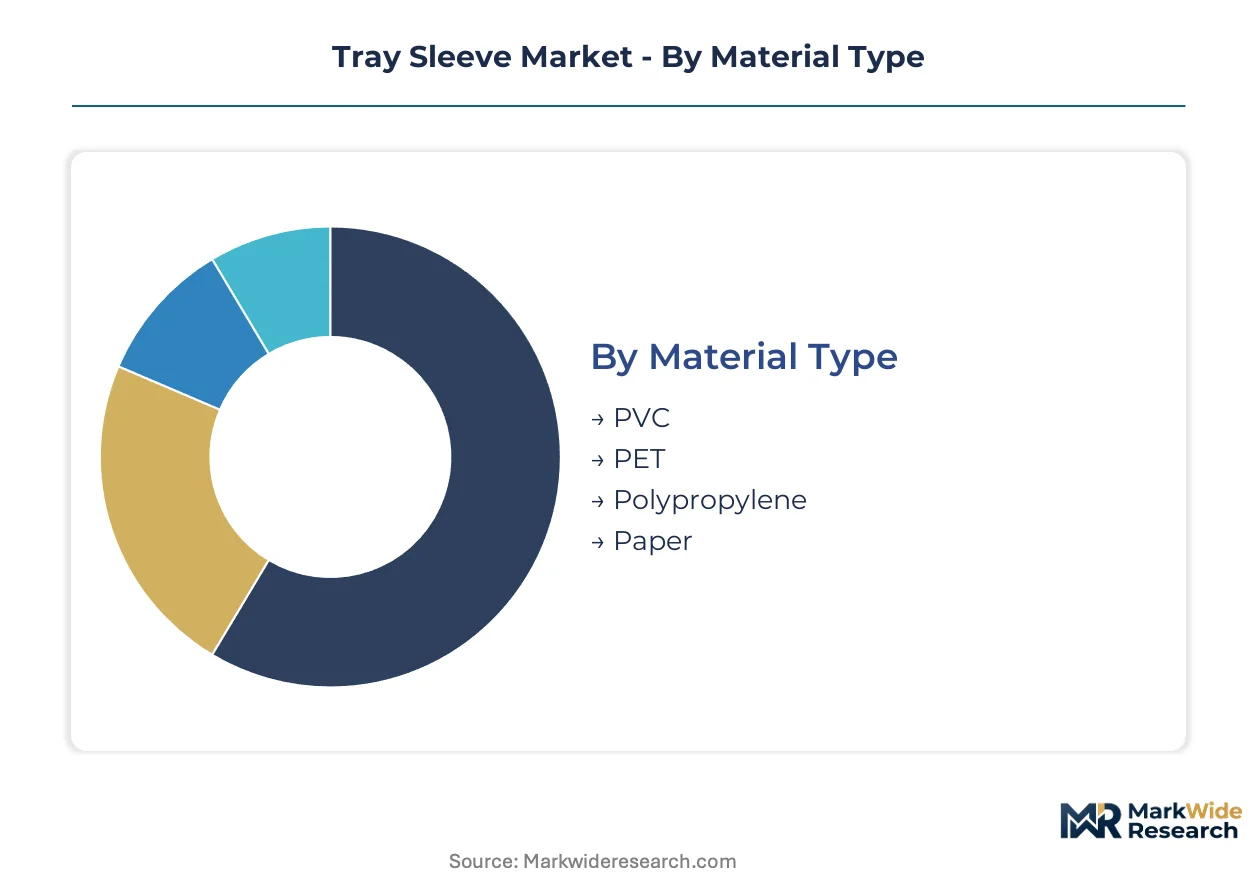
Tray sleeve procurement patterns diverge sharply across material grades and regulatory contexts. Pharmaceutical serialization mandates and EU polymer restrictions are fragmenting demand into validated premium formats versus commodity logistics applications.
Material Type:
Paper-based substrates demand the heaviest capital commitment for barrier coating R&D and water-based printing infrastructure.
- PVC:Legacy thermoplastic offering dimensional stability and heat-seal reliability. Food logistics channels in India and Southeast Asia retain PVC for cost-sensitive secondary containment despite ECHA REACH phase-down timelines in Europe.
- PET:Polyester resin provides clarity and moisture barrier performance for humidity-critical pharmaceutical applications. CDSCO-regulated facilities in India specify PET for oral solid dosage tray formats where visual inspection matters.
- Polypropylene:Olefin polymer balances chemical resistance with recyclability credentials. China's GB standards-compliant food e-commerce networks are substituting polypropylene for PVC in provincial carbon intensity reduction programs.
- Paper:Cellulose substrates with water-based polymer treatments enable circular packaging claims. EU MDR labeling mandates are accelerating paper sleeve validation for European medical device secondary packaging.
PVC absorbs the bulk of installed capacity; paper-based alternatives are expanding most quickly.
Product Type:
Volume concentration separates high-throughput standard formats from engineered solutions requiring application-specific tooling.
- Standard Sleeves:Pre-formed dimensions for commodity tray geometries. Indian contract packagers serving FSSAI-regulated food channels deploy standard sleeves for cost minimization at million-unit scale.
- Custom Sleeves:Bespoke dimensions and aperture patterns for irregular tray designs. Cosmetic gift set manufacturers in South Korea specify custom formats for travel retail presentation requirements.
- Printed Sleeves:Gravure or flexographic decoration for brand differentiation and regulatory labeling. PLI scheme beneficiaries in India are expanding printed capacity to capture pharmaceutical manufacturing subsidies.
- Shrink Sleeves:Heat-activated polyester or polyolefin films conforming to complex tray topologies. Premium personal care brands in Japan adopt shrink formats for 360-degree surface decoration on irregular geometries.
Standard sleeves dominate unit economics; shrink sleeves command the steepest expansion trajectory in premium channels.
End Use:
Regulatory intensity stratifies end-use segments between validated pharmaceutical systems and self-certified food applications.
- Food Packaging:Secondary containment for fresh, frozen, and shelf-stable products. China's SAMR-aligned food e-commerce fulfillment networks are retrofitting paper sleeve lines to meet provincial dual carbon targets.
- Beverage Packaging:Tray stabilization for multi-unit drink configurations. German retail consolidation is standardizing sleeve formats across private-label beverage portfolios to reduce SKU complexity.
- Cosmetic Packaging:Premium presentation and tamper evidence for personal care products. French and Italian beauty brands specify shrink sleeves for gift set configurations in duty-free retail channels.
- Pharmaceutical Packaging:Serialization-ready secondary containment with batch traceability. FDA 21 CFR Part 211 cGMP requirements are forcing validated sleeve-to-tray adhesion systems with full equipment qualification protocols.
Food packaging retains volume leadership; pharmaceutical applications are climbing the fastest on compliance-driven replacement cycles.
Distribution Channel:
Customer scale and technical support requirements determine channel selection between self-service procurement and engineered system sales.
- Online Retail:Catalog-based ordering for standardized sleeve dimensions. Small-batch cosmetic brands in Brazil access printed sleeves through digital procurement platforms without minimum quantity constraints.
- Offline Retail:Physical distributor networks for immediate availability. Mexican food processors source standard sleeves through regional packaging supply houses for just-in-time production schedules.
- Wholesale:Volume aggregation across multiple converter sources. ASEAN contract packagers leverage wholesale channels to balance price exposure across resin grade fluctuations.
- Direct Sales:Integrated equipment-material partnerships with validation support. CDSCO-regulated Indian facilities specify direct sales relationships for FDA-compliant sleeve-to-tray system qualification.
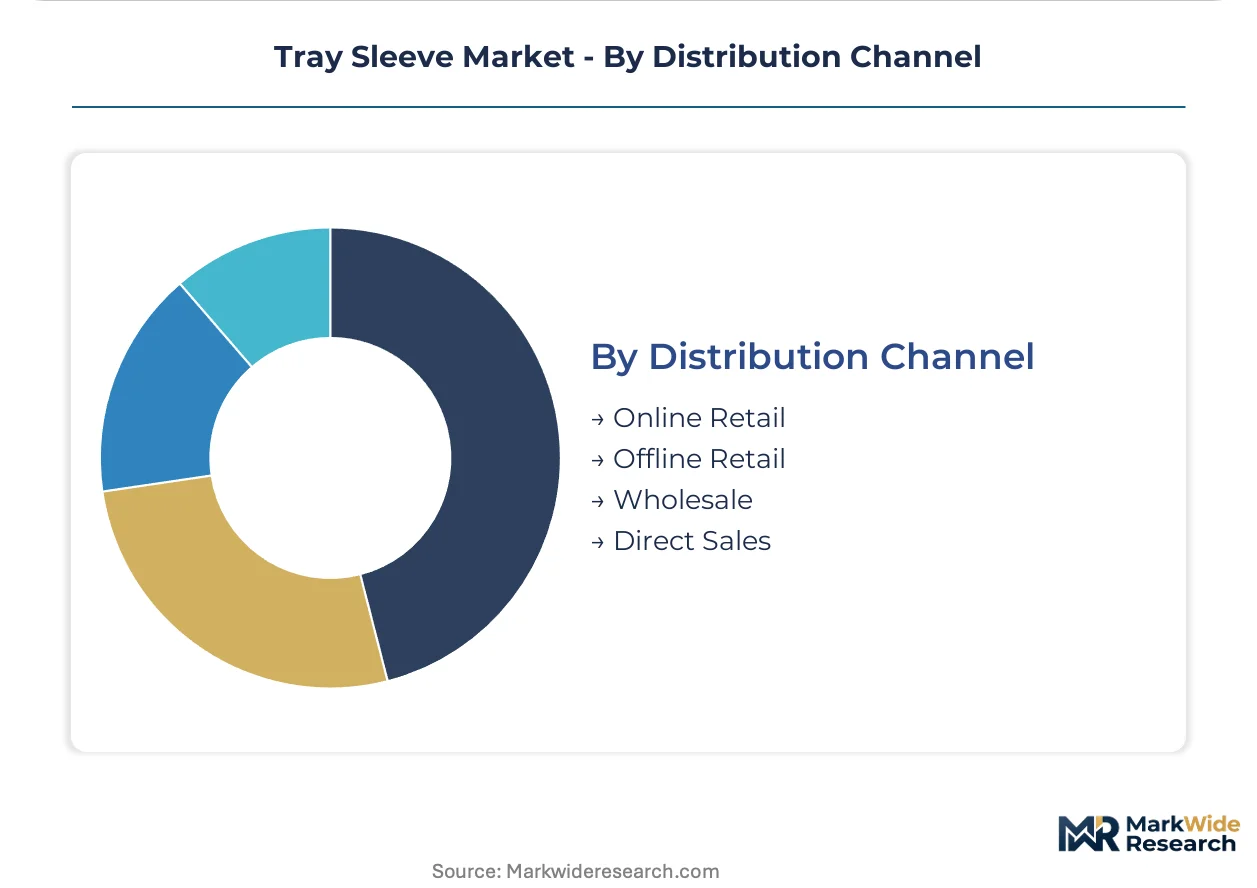
Wholesale channels handle the greatest throughput; direct sales relationships are gaining share fastest in regulated pharmaceutical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian manufacturing clusters while consumption splits between European pharmaceutical compliance markets and Indian contract packaging expansion. Taiwan and Germany dominate high-speed equipment supply, creating lead time bottlenecks for emerging market packagers.
China
Provincial dual carbon targets are accelerating paper sleeve substitution in domestic food e-commerce networks. SAMR and NMPA alignment with ICH Q9 principles is forcing pharmaceutical packagers toward validated sleeve-to-tray systems. The Yangtze River Delta hosts the densest concentration of barrier coating R&D facilities for cellulose substrates.
Germany
EU MDR labeling mandates are retrofitting medical device packaging lines with tamper-evident sleeve systems. ECHA REACH polymer restrictions are structurally bifurcating demand toward validated paper formats. The Baden-Württemberg industrial corridor anchors high-speed pharmaceutical sleeve applicator manufacturing.
India
CDSCO compliance requirements and PLI scheme incentives are reshaping procurement patterns for printed and shrink sleeve formats. Domestic contract packaging facilities are expanding capacity to capture government-backed pharmaceutical manufacturing subsidies. Maharashtra and Gujarat host the fastest-growing clusters of FDA-compliant sleeve validation operations.
United States
FDA 21 CFR Part 211 cGMP requirements are forcing validated sleeve-to-tray adhesion systems with full batch traceability. Serialization mandates are decoupling pharmaceutical packaging demand from traditional food applications. The Midwest packaging belt concentrates shrink sleeve capacity for multi-unit beverage configurations.
Japan
PMDA serialization standards are aligning with FDA traceability requirements, creating dual-certification pressures for export-oriented packagers. Premium personal care brands are adopting 360-degree printed sleeves for irregular tray geometries in duty-free retail. The Kansai region maintains specialized capacity for cosmetic gift set sleeve formats.
Tray Sleeve Market Competitive Landscape
Top-tier vendors anchor pharmaceutical validation services and integrated equipment-material partnerships, while mid-tier converters compete on regional logistics and commodity resin conversion. The vendor base stratifies across three archetypes: automation-integrated system suppliers, specialized pharmaceutical equipment fabricators, and material-science-focused polymer converters. Consolidation pressures favor backward integration into barrier coating R&D and geographic expansion into ASEAN contract manufacturing zones.
Within the automation-integrated tier, DASE-SING Packaging Technology Co., LTD. and Cama Group represent archetypes of high-speed line integration capability. Among India-based pharmaceutical specialists, Harikrushna Machines Pvt. Ltd. and Brothers Pharmamach (India) Pvt. Ltd. occupy positions serving CDSCO-regulated domestic contract packagers. At the material-science end, Allen Plastic Industries Co., Ltd. exemplifies polymer substrate leadership for moisture-sensitive applications.
| Leading Market Players |
|---|
| DASE-SING Packaging Technology Co., LTD. |
| Harikrushna Machines Pvt. Ltd. |
| Allen Plastic Industries Co., Ltd. |
| Jet Container |
| World Centric |
| Cama Group |
| Brothers Pharmamach (India) Pvt. Ltd. |
| Tycoon Packaging |
| Accutek Packaging Companies |
| Others |
Value Network & Pricing Analysis
Polypropylene resin futures on the Dalian Commodity Exchange cascade through tray sleeve converter margins into three distinct pricing tiers, with pharmaceutical-grade PET formats commanding certification premiums while food-channel PVC sleeves absorb crude oil volatility through volume scale.
Pricing Analysis
Margin tightening in commodity shrink sleeves reflects polypropylene and PET resin price swings tied to crude benchmarks, compressing converter returns in cost-sensitive food logistics channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical formats from FSSAI-compliant food sleeves and generic PVC logistics grades. Price differentiation hinges on certification tier and vertical integration depth, with integrated equipment-material suppliers capturing adhesion-performance premiums. Indian contract packagers exhibit highest price sensitivity, while European medical device manufacturers prioritize validated system guarantees over unit economics.
Supply Chain Analysis
Freight cost differentials between Taiwan-Germany equipment corridors and Indian end-markets amplify landed costs for high-speed pharmaceutical sleeve applicators, extending lead times for CDSCO-regulated facilities. Raw material supply concentrates in China, Taiwan, and Germany, with barrier coating R&D clustering in the Yangtze River Delta and precision applicator fabrication anchoring Baden-Württemberg. Converter operations draw from petrochemical resin feedstocks, water-based polymer treatments, and gravure printing infrastructure. Single-source vulnerability concentrates in Taiwanese automation-integrated system suppliers. Distribution runs through wholesale channels for commodity formats and direct sales relationships for validated pharmaceutical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tray sleeve market functions as a vertical-integration race, with winners capturing barrier coating R&D upstream and equipment-material validation partnerships downstream.
For Market Incumbents: Hedge against paper-based substitution by securing water-based polymer treatment patents and retrofitting solvent gravure capacity for flexographic conversion. ECHA REACH phase-down timelines for PVC threaten legacy resin converters lacking cellulose substrate expertise. Backward integration into barrier coating R&D protects margin position in European pharmaceutical channels.
For New Entrants and Emerging Players: The premium-economy price gap in Indian contract packaging creates entry latitude for CDSCO-compliant printed sleeve specialists. Target Maharashtra and Gujarat clusters where PLI scheme beneficiaries expand capacity without integrated validation capabilities. Lead with outcome-based adhesion guarantees rather than unit pricing to displace wholesale channel relationships.
For Investors and Strategic Acquirers: The window for entry favors mid-tier converters with captive barrier coating technology and ASEAN geographic optionality. Long-term viability rests on paper substrate validation capabilities and pharmaceutical equipment integration expertise. Watch EU AI Act supply chain transparency implementation as inflection signal for smart sleeve RFID integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Investment | Water-based polymer treatments enable PVC substitution in EU MDR-compliant medical device packaging. |
| Equipment-Material Integration Partnership | CDSCO-regulated Indian facilities demand validated sleeve-to-tray system guarantees from single-source suppliers. |
| Water-Based Flexographic Conversion | Reduces VOC emissions and compresses minimum order quantities for European generic drug parallel trade. |
| ASEAN Geographic Expansion | Indonesia pharmaceutical packaging demand opens as ASEAN medical device regulations harmonize. |
| Smart Packaging RFID Integration | EU AI Act machine-readable identifiers mandate batch-level provenance database connectivity. |
Research Methodology
Multi-period observation of resin price benchmarks, regulatory filing timelines, and capacity expansion announcements anchored the trend analysis, supplemented by interviews with pharmaceutical packaging line engineers, CDSCO compliance officers, flexographic printing specialists, and contract packaging procurement directors. Secondary validation drew from ECHA REACH substance restriction updates, FDA 21 CFR Part 211 guidance documents, CDSCO manufacturing facility inspection reports, and Indian PLI scheme beneficiary disclosures. Bottom-up capacity modeling and top-down demand segmentation were triangulated against trade flow data.
Input-output matrices mapped material-grade supply elasticity against end-use demand growth across pharmaceutical, food, cosmetic, and beverage packaging segments over the projection horizon. Segmentation dimensions included material type, product format, regulatory compliance tier, and distribution channel intensity. CAGRs were derived from installed base replacement cycles, greenfield capacity announcements, and substitution elasticity parameters. Forecast inputs incorporated provincial dual carbon target implementation rates in China and PLI scheme disbursement velocity in India.
Inputs from primary stakeholder interviews and disclosed regulatory filings were available through the study window; gaps in real-time resin inventory positioning and unannounced equipment qualification timelines introduce uncertainty bands around near-term capacity utilization assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market