
 Multistage Pump Market | 2026-2036
Multistage Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Multistage Pump Market Foresight
Capital-intensity divergence between foundry-capable incumbents and assembly-only challengers is redrawing competitive boundaries in the multistage pump sector. Grundfos leverages its in-house stainless-steel casting network to control lead times for high-pressure vertical units. Xylem Inc. anchors its position through digital twin integration across water utility deployments. KSB SE & Co. KGaA differentiates via segmented diffuser designs that cut energy draw in chemical processing loops.
A multistage pump contains multiple impellers mounted on a common shaft within a single casing, with each stage boosting discharge pressure sequentially to achieve heads exceeding 1000 meters. The equipment serves critical fluid transport in water distribution, hydrocarbon extraction, and thermal power generation where single-stage designs cannot overcome system resistance. Horizontal centrifugal configurations dominate mature water supply infrastructure due to established maintenance protocols and accessible bearing assemblies. Submersible installations in offshore oil and gas represent the fastest-growing segment as platform electrification reduces topside footprint. Solar-driven technology remains niche but captures margin pools in remote agricultural and mining dewatering applications where grid extension proves uneconomical.
The US Department of Energy enforces minimum efficiency performance standards under its Pump Energy Conservation Program, compelling OEMs to redesign hydraulic sections or exit federal procurement channels. China's MIIT mandates GB standard compliance for multistage pumps deployed in state-backed water conservancy projects, creating a dual-track certification burden for exporters. India's Bureau of Energy Efficiency operates a star-labeling scheme that directs public-sector buyers toward IE3 motor pairings. Stakeholders must monitor how carbon border adjustment mechanisms reshape sourcing logic for cast components and wound stators across competing manufacturing bases.
Market Dynamics
Energy efficiency mandates are compressing equipment replacement cycles across water utilities and industrial processing facilities, forcing capital redeployment toward higher-efficiency hydraulic architectures before physical end-of-life.
Growth Catalysts
- EU Ecodesign framework:Minimum efficiency requirements under the EU's ecodesign directive are accelerating equipment turnover in German and French chemical processing plants.
- Thermal power expansion:India's Central Electricity Authority is driving procurement for feedwater booster systems in supercritical coal and combined-cycle gas installations.
- Stainless steel casting networks:In-house foundry capabilities among Nordic OEMs are shortening lead times for corrosion-resistant vertical turbine configurations.
Market Restraints
- Copper and rare-earth magnet costs:IE3 and IE4 motor specifications depend on neodymium-iron-boron magnets whose price volatility compresses margin predictability for wound stator suppliers.
- Foundry concentration in East Asia:Gray iron and stainless steel casting capacity clusters in China's Hebei and Shandong provinces, creating single-source vulnerability for European pump assemblers.
- Mechanical seal limitations:Conventional face seal designs fail above 150°C in geothermal and solar thermal applications, restricting addressable market scope.
Strategic Opportunities
- Subsea electrification:Offshore platform power-from-shore projects in Norway's North Sea fields are displacing hydraulic drive systems with submersible multistage electric pumps.
- Solar PV irrigation:DC-powered surface pump sets paired with photovoltaic arrays are penetrating Rajasthan and Gujarat agricultural districts beyond grid reach.
- Digital twin integration:Predictive maintenance platforms combining vibration sensors with cloud-based hydraulic modeling are opening recurring revenue streams in Danish and Dutch water utility contracts.
Industry Challenges
- Hydraulic engineer scarcity:Computational fluid dynamics expertise for impeller optimization is concentrating among aging specialists in German and Italian engineering consultancies.
- Dual certification burden:Exporters to China must secure both GB standard compliance and IEC certification, extending product validation timelines by eight to fourteen months.
- Legacy control system integration:Modbus and Profibus protocols in existing SCADA architectures resist seamless connection to IoT-enabled pump monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multistage Pump Market |
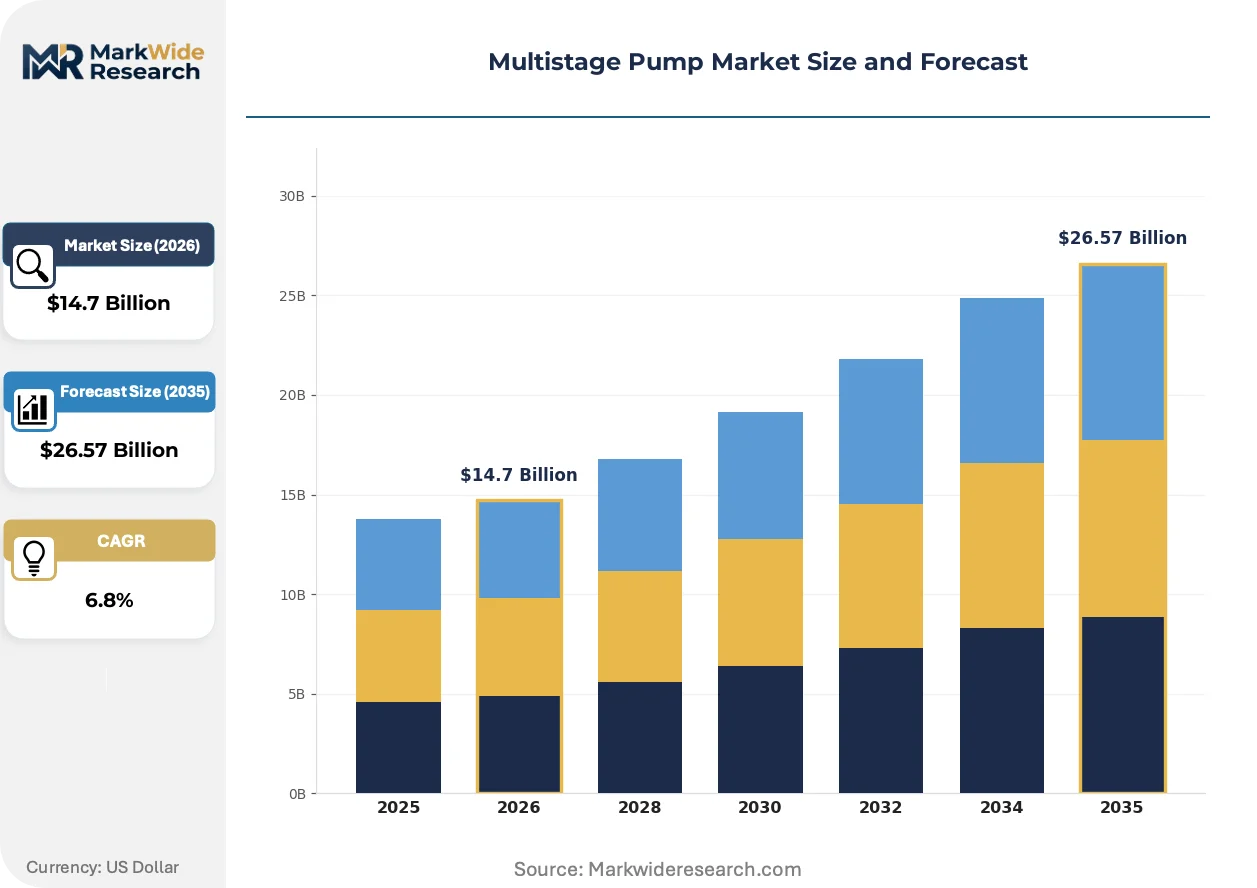
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Submersible, Vertical, Horizontal End User: Water Supply, Oil & Gas, Chemical Processing, HVAC Installation: Onshore, Offshore, Underground, Surface Technology: Electric, Solar, Diesel, Gear-driven |
| Companies Covered | Grundfos, Xylem Inc., KSB SE & Co. KGaA, Sulzer Ltd., Wilo SE, Ebara Corporation, Flowserve Corporation, Pentair plc, Kirloskar Brothers Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multistage Pump Market Shifts & Advancements
Additive manufacturing is penetrating impeller prototyping and short-run production, collapsing design-to-test cycles while enabling geometry optimization impossible with conventional five-axis machining.
Computational fluid dynamics coupled with topology optimization software is decomposing traditional radial impeller vane geometries into asymmetric, biomimetic flow paths. Water utilities in Singapore and Copenhagen are specifying these optimized hydraulic sections for energy recovery applications. The technology is decomposing the historical trade-off between peak efficiency and operating range flexibility.
China's MIIT enforcement of GB 19762 efficiency grades for multistage pumps deployed in state water conservancy projects is disqualifying lower-tier domestic manufacturers from central government tenders. Provincial procurement bureaus in Jiangsu and Guangdong are now requiring third-party test-stand certification for all bids above 75 kW. Foreign OEMs with established Shanghai testing facilities are capturing premium positioning in these tenders.
Water utilities are unbundling aftermarket service contracts from initial equipment supply, separating spare parts logistics from warranty obligations. Danish and Dutch municipal operators now run competitive tender processes for five-year maintenance agreements independent of pump purchase decisions. Equipment vendors with localized parts depots in Rotterdam and Aarhus are securing recurring revenue streams that offset compressed upfront margins.
Multistage Pump Market Segmentation
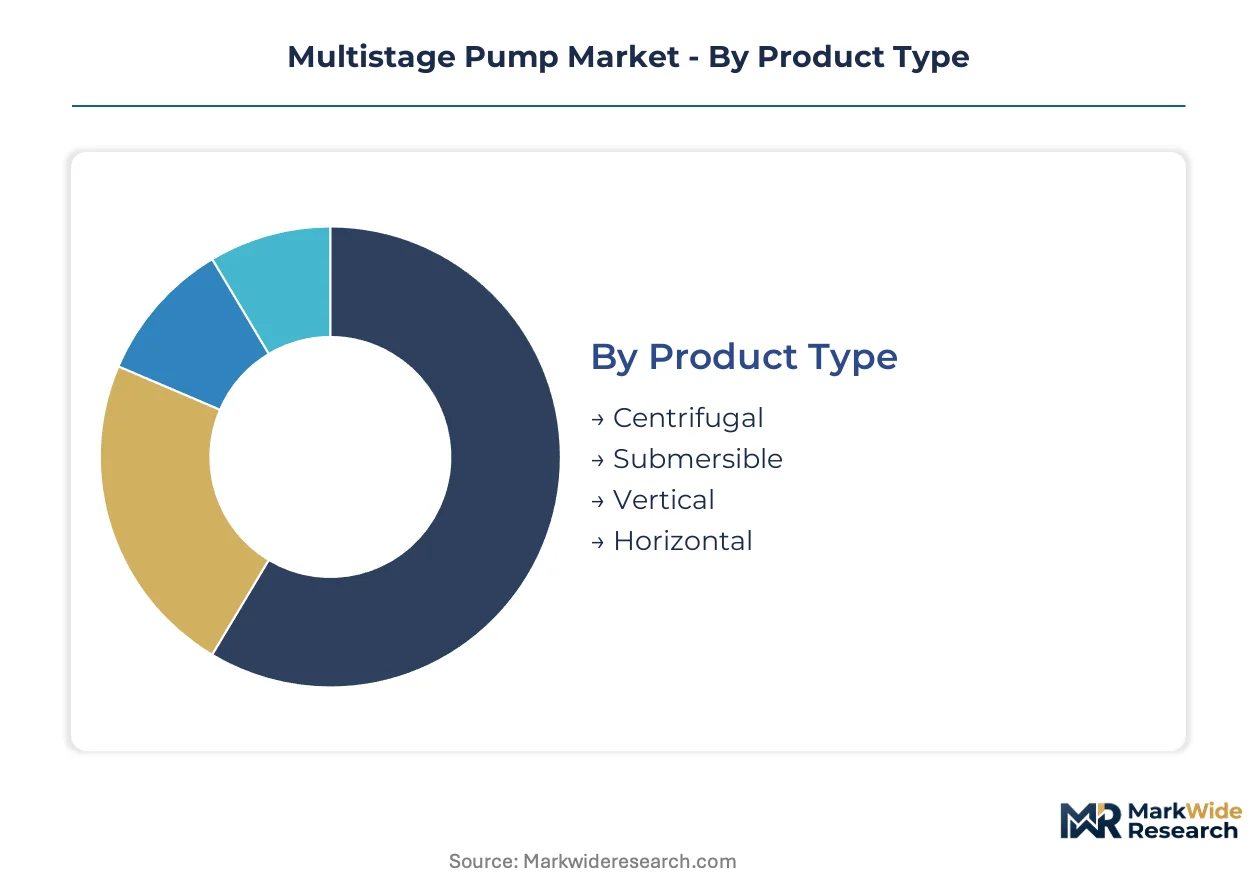
Segmentation in the multistage pump market reveals how regulatory pressure and energy mandates split procurement behavior across equipment types and power sources. Buyers now segment decisions by efficiency tier before considering hydraulic configuration.
Product Type:
EU Ecodesign efficiency grades and China's GB 19762 standards enforce divergent certification paths for each hydraulic architecture, reshaping competitive positioning among foundry-capable and assembly-only suppliers.
- Centrifugal:Radial flow impellers arranged in series within a volute casing generate heads exceeding 800 meters through kinetic energy conversion. Water supply utilities in Germany and France specify these for municipal distribution networks under tightening EU efficiency mandates.
- Submersible:Motor and pump stages operate fully immersed, eliminating suction lift limitations and reducing noise signatures. Offshore platform operators in Norway's North Sea fields are displacing hydraulic drive systems with electric submersible configurations as power-from-shore projects expand.
- Vertical:Space-efficient configurations suit deep well applications with limited surface footprint. Stainless steel casting networks among Nordic OEMs shorten lead times for corrosion-resistant turbine designs.
- Horizontal:Accessible bearing assemblies and established maintenance protocols dominate mature water infrastructure. India's Central Electricity Authority specifies these for thermal power feedwater systems.
Centrifugal units handle the majority of throughput; submersible configurations are gaining share fastest as offshore electrification accelerates.
End User:
Capital intensity and energy recovery timelines vary sharply across process industries, with chemical processing demanding corrosion-resistant metallurgy and water utilities prioritizing lifecycle operating cost.
- Water Supply:Municipal distribution networks and irrigation systems require 24/7 reliability with minimal maintenance windows. Southeast Asian utilities are expanding procurement for distribution modernization.
- Oil & Gas:Hydrocarbon extraction and refining operations demand API-compliant metallurgy for sour service conditions. Platform electrification in Norwegian fields drives specification changes.
- Chemical Processing:Segmented diffuser designs cut energy draw in continuous process loops. German and French plants face accelerated replacement cycles under EU Ecodesign directives.
- HVAC:Building services applications prioritize compact footprint and variable speed compatibility. District heating networks in Copenhagen specify optimized hydraulic sections for energy recovery.
Water supply accounts for the largest installed base; chemical processing shows the steepest replacement trajectory as efficiency mandates compress equipment cycles.
Installation:
Site constraints and maintenance access determine total cost of ownership, with subsea and buried installations commanding premium service contracts over surface-mounted alternatives.
- Onshore:Industrial processing facilities and power plants favor accessible configurations for scheduled maintenance. India's thermal power expansion drives feedwater booster procurement.
- Offshore:Topside weight restrictions and platform electrification reshape pump specification. Norway's North Sea operators lead submersible adoption.
- Underground:Mining dewatering and geothermal applications face temperature limitations from conventional face seal designs. Rajasthan and Gujarat agricultural districts deploy DC-powered units beyond grid reach.
- Surface:Solar PV irrigation sets paired with photovoltaic arrays penetrate remote mining and agricultural sites where grid extension proves uneconomical.
Onshore installations retain the dominant share; underground configurations are expanding most quickly as solar-driven technology captures remote applications.
Technology:
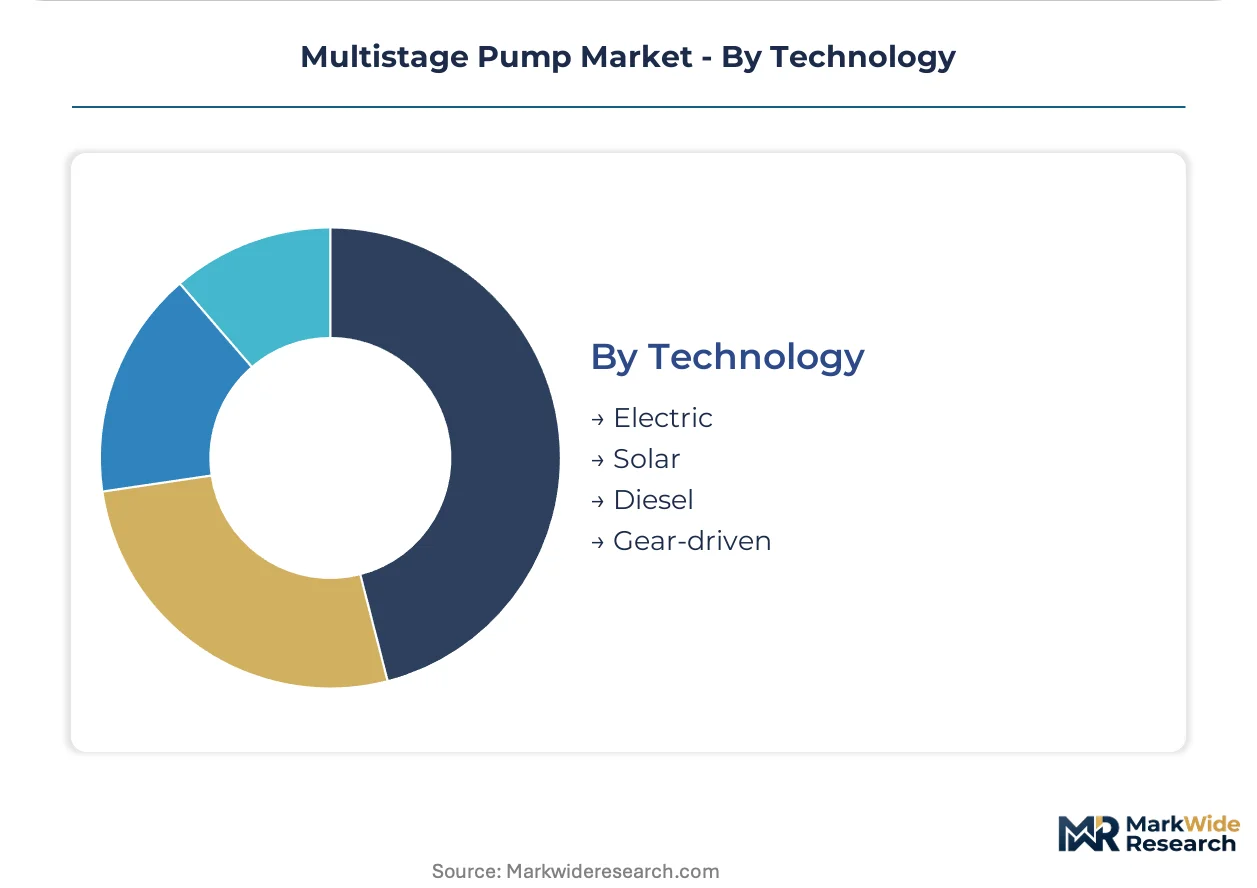
Power source selection increasingly hinges on grid availability and carbon accounting, with electric drives facing rare-earth magnet cost volatility and solar options constrained by intermittency.
- Electric:IE3 and IE4 motor pairings with wound stators or permanent magnet rotors dominate industrial specifications. India's Bureau of Energy Efficiency star-labeling directs public-sector buyers toward premium efficiency tiers.
- Solar:DC-powered surface pump sets with maximum power point tracking suit off-grid extraction and irrigation. Rajasthan and Gujarat agricultural districts lead deployment.
- Diesel:Emergency backup and mobile dewatering applications retain demand where electrical infrastructure is absent or unreliable. Mining contractors specify these for temporary installations.
- Gear-driven:Mechanical speed multiplication suits specific high-torque, low-speed applications in legacy industrial settings. Maintenance complexity limits new specification.
Electric drives command the largest share; solar-powered units are climbing the fastest as photovoltaic costs decline and remote applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Danish OEMs commanding premium positioning for high-pressure vertical units, while Chinese foundries dominate gray iron casting supply for cost-sensitive procurement across Southeast Asian water utilities.
United States
Thermal power plant retrofits and municipal water infrastructure renewal drive procurement volumes. The Department of Energy enforces minimum efficiency performance standards under its Pump Energy Conservation Program, compelling equipment redesigns for federal procurement eligibility. Houston hosts concentrated oilfield services demand as Permian Basin operators electrify artificial lift systems.
Germany
Chemical processing clusters along the Rhine corridor accelerate replacement cycles for feedwater and process loop applications. The EU Ecodesign framework mandates minimum efficiency requirements that disqualify legacy hydraulic architectures from continued operation. Ruhr Valley industrial zones specify segmented diffuser designs that cut energy draw in continuous processing loops.
China
State-backed water conservancy projects and thermal power expansion sustain domestic demand at scale. MIIT enforces GB 19762 efficiency grades that disqualify lower-tier domestic manufacturers from central government tenders. Foundry capacity clusters in Hebei and Shandong provinces supply gray iron and stainless steel castings to European pump assemblers facing single-source vulnerability.
India
Thermal power feedwater systems and irrigation modernization programs concentrate procurement decisions. The Bureau of Energy Efficiency operates a star-labeling scheme that directs public-sector buyers toward IE3 motor pairings. Rajasthan and Gujarat agricultural districts deploy DC-powered surface pump sets paired with photovoltaic arrays beyond grid reach.
Norway
Offshore platform electrification and power-from-shore projects reshape submersible pump specifications. National regulators align with North Sea decarbonization timelines that displace hydraulic drive systems with electric alternatives. Stavanger and Bergen engineering centers anchor subsea technology development for submersible multistage configurations.
Multistage Pump Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the multistage pump sector. Foundry-capable incumbents with in-house stainless steel casting networks command pricing power for corrosion-resistant vertical turbine designs, while assembly-only challengers compete on lead time compression for standardized horizontal configurations. The competitive terrain splits between premium-tier hydraulic optimization specialists and scale-driven volume manufacturers serving utility procurement. Dominant competitive moves include backward integration into captive casting capacity and geographic expansion through localized parts depot networks.
Among Nordic engineering conglomerates, Grundfos and KSB SE & Co. KGaA exemplify the foundry-integrated archetype that controls lead times through upstream metalworking capabilities. Xylem Inc. occupies a position representing the digital-anchored tier where predictive maintenance platforms and utility software integration differentiate positioning. These three entities collectively illustrate how competitive advantage stems from divergent capability investments rather than convergent operational excellence.
| Leading Market Players |
|---|
| Grundfos |
| Xylem Inc. |
| KSB SE & Co. KGaA |
| Sulzer Ltd. |
| Wilo SE |
| Ebara Corporation |
| Flowserve Corporation |
| Pentair plc |
| Kirloskar Brothers Limited |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85 percent in China's Hebei and Shandong provinces compress casting cost floors for gray iron components while elevating bargaining power for stainless steel turbine housings sourced from Nordic captive facilities. This scale asymmetry bifurcates procurement economics between commodity horizontal pump assemblers and corrosion-resistant vertical specialists serving chemical processing loops.
Pricing Analysis
Configured-to-order pricing for API-compliant submersible units commands spreads exceeding 40 percent above catalog horizontal configurations due to metallurgical certification and custom hydraulic section engineering. Three-tier pricing structure across premium, standard, and economy levels stratifies by efficiency grade under EU Ecodesign and China's GB 19762 frameworks, with IE4 motor pairings capturing margin pools unavailable to IE2 alternatives. Cost compression in standard centrifugal tiers intensifies because foundry-capable incumbents leverage captive casting networks to undercut assembly-only challengers on lead time and unit economics. Municipal water utilities in Southeast Asia exhibit highest price sensitivity, prioritizing lifecycle operating cost over upfront capital outlay, while offshore platform operators in Norway's North Sea fields accept premium positioning for subsea-qualified configurations.
Supply Chain Analysis
Strategic stockpiling of neodymium-iron-boron magnets and copper winding wire dominates inventory strategy among wound stator suppliers confronting rare-earth price volatility, whereas just-in-time procurement prevails for standardized gray iron castings from high-utilization Chinese foundries. Raw material dependencies center on gray iron and stainless steel castings from China, copper rod from Chile and Peru, and rare-earth magnet alloys processed in China and Japan. Single-source vulnerability concentrates in Hebei and Shandong foundry clusters, where capacity constraints or export licensing shifts would cascade through European pump assembler production schedules. Distribution runs through OEM-direct contracting for large industrial projects and authorized distributor networks for aftermarket spare parts, with localized parts depots in Rotterdam and Aarhus securing recurring service revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational fluid dynamics expertise for impeller optimization concentrates among aging specialist cohorts in German and Italian engineering consultancies, constraining hydraulic innovation velocity and amplifying acquisition premiums for captive design capabilities.
For Market Incumbents: Secure captive stainless steel casting capacity or long-term offtake agreements with Nordic foundry networks to defend margin position against assembly-only challengers compressing lead times for standardized horizontal configurations. Accelerate digital twin platform deployment across Danish and Dutch water utility installed bases to convert equipment sales into recurring predictive maintenance revenue, offsetting upfront pricing softness in municipal procurement tenders. For New Entrants and Emerging Players: Aftermarket service unbundling from initial equipment supply creates entry space for independent maintenance specialists targeting five-year competitive tender processes now run separately from pump purchase decisions by Rotterdam and Aarhus municipal operators. Solar PV irrigation beyond grid reach in Rajasthan and Gujarat agricultural districts offers the most penetrable white-space target, with DC-powered surface pump sets paired with photovoltaic arrays requiring minimal foundry investment and enabling distributed assembly models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundry-integrated OEMs with localized parts depot networks and digital twin platform penetration in utility contracts, positioning these archetypes for superior cash flow quality across the analysis window. Target acquisition profiles should emphasize in-house CFD capability and established Shanghai testing facilities for GB 19762 certification, with inflection signaled by provincial procurement bureaus in Jiangsu and Guangdong tightening third-party test-stand requirements above 75 kW thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Casting | In-house stainless steel foundry capacity controls lead times for corrosion-resistant vertical turbine configurations serving chemical processing loops. |
| Digital Twin Platform Deployment | Predictive maintenance integration with Danish and Dutch water utility SCADA architectures opens recurring revenue streams independent of equipment sales cycles. |
| GB 19762 Certification Investment | Third-party test-stand validation in Shanghai secures eligibility for central government tenders in China's state-backed water conservancy projects. |
| Localized Parts Depot Expansion | Rotterdam and Aarhus logistics hubs capture aftermarket service contracts unbundled from initial municipal procurement decisions. |
| Solar PV Irrigation Partnership | DC-powered surface pump integration with Rajasthan and Gujarat photovoltaic arrays penetrates agricultural districts beyond grid extension economics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at thermal power facilities, plant engineers in chemical processing clusters, OEM procurement teams specifying feedwater booster systems, and aftermarket service heads managing unbundled utility contracts. Secondary validation drew from customs and trade data tracking gray iron and stainless steel casting flows, SEC 10-K filings disclosing foundry capacity investments, Bureau of Energy Efficiency star-labeling databases, and EU Ecodesign directive implementation reports. Bottom-up unit economics triangulated against top-down sectoral spending estimates produced convergent market sizing across the projection horizon.
Across the modeling period, volume and value outputs segmented by hydraulic architecture, power source technology, installation environment, and end-use application intensity. CAGRs derived from regression analysis against energy efficiency mandate enforcement timelines and thermal power capacity addition schedules in India. Industry-specific forecast inputs incorporated rare-earth magnet price volatility indices and provincial procurement bureau tender award patterns in China's Jiangsu and Guangdong regions.
Forecasts assume regulatory continuity in EU Ecodesign efficiency grades, China's GB 19762 enforcement, and India's Bureau of Energy Efficiency star-labeling scheme; material policy shifts accelerating replacement cycles or relaxing certification burdens would require re-modeling. Revision becomes warranted when foundry utilization rates in Hebei and Shandong provinces cross thresholds triggering export restriction responses or when subsea electrification project sanctioning in Norway's North Sea fields deviates materially from power-from-shore deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Global Piston Pumps Market