
 Fuel Transfer Pump Market | 2026-2036
Fuel Transfer Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Transfer Pump Market Intelligence
Transport operators is collapsing as the dominant buyer archetype as fuel distributors and equipment manufacturers capture larger procurement volumes. Graco Inc. leverages its fluid handling specialization to anchor premium electric pump lines for construction and marine applications. Tuthill Corporation competes through rotary vane technology leadership and captive supply of precision-machined components. Piusi S.p.A. dominates European fuel logistics with ATEX-certified dispensing systems and channel control across Mediterranean distributor networks.
A fuel transfer pump is a mechanical or electromechanical device engineered to move liquid fuels between storage vessels, vehicles, or machinery, typically achieving flow rates from 15 to 400 liters per minute and operating pressures up to 4 bar depending on power rating and impeller design. Its primary commercial purpose is to enable safe, metered, and efficient fuel distribution in environments ranging from remote agricultural sites to high-throughput marine bunkering operations. Electric pumps lead product type demand due to automation compatibility and reduced operator fatigue, while pneumatic variants gain share in explosive atmospheres where spark mitigation governs specification. Medium power ratings occupy the largest margin pool by balancing portability with throughput across construction equipment and agricultural machinery applications.
The United States EPA enforces vapor recovery and spill containment standards that shape pump sealing architectures and materials selection for domestic manufacturers. OSHA workplace safety regulations mandate explosion-proof motor housings and grounding protocols for pumps deployed in hazardous location classifications. China's MEE implements dual carbon goals that pressure fuel logistics operators toward higher-efficiency transfer equipment with reduced fugitive emissions. Stakeholders must monitor how evolving carbon accounting rules across these jurisdictions reshape certification requirements and procurement criteria for cross-border equipment sales.
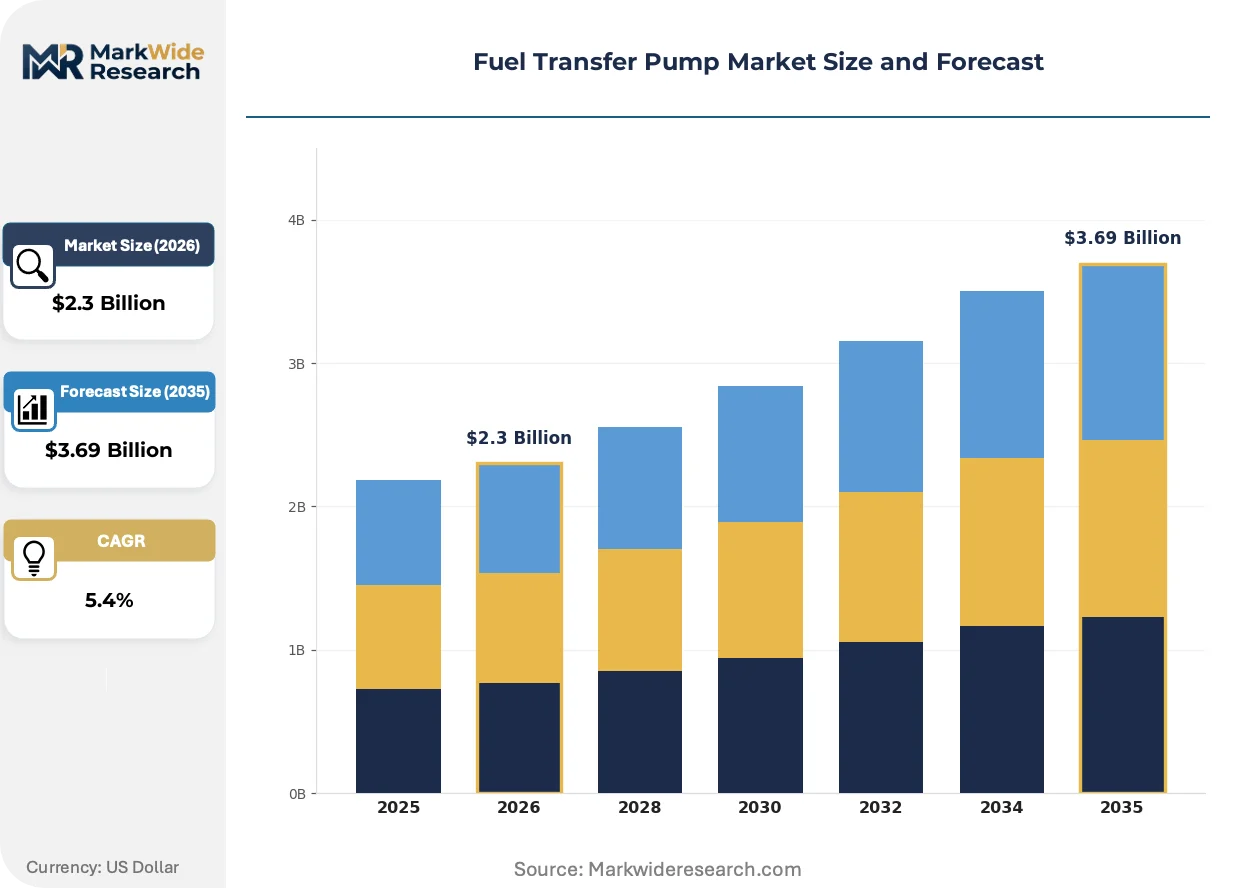
Market Dynamics
Electric pump architectures are compressing maintenance intervals and reshaping buyer specifications across construction, marine, and agricultural deployments. EPA vapor recovery mandates and OSHA hazardous location classifications are accelerating sealed-system designs while Chinese inland logistics expansion concentrates procurement volumes in state-backed fuel distribution networks.
Growth Catalysts
- EPA Emissions Standards:Vapor recovery and spill containment rules are mandating upgraded pump sealing architectures and fluoropolymer material selection for domestic manufacturers serving US transport fleets.
- Remote Mining Logistics:China's western industrial corridors and Mongolian border zones are driving demand for portable high-throughput pumps capable of operating at altitude with minimal infrastructure.
- Electric Automation Compatibility:Construction equipment lessors are specifying brushless DC pump motors to integrate with telematics platforms and reduce operator fatigue during extended refueling cycles.
Market Restraints
- Aluminum Casting Supply Concentration:Precision-machined pump housings depend on concentrated foundry capacity in Zhejiang and Guangdong provinces, exposing lead times to regional power rationing.
- REACH Chemical Compliance:European substance restrictions on perfluorinated compounds are forcing reformulation of legacy gasket materials and extending certification timelines for ATEX-certified systems.
- Pneumatic Substitution Ceiling:Compressed-air pump variants face throughput limitations above 200 liters per minute, constraining adoption in high-volume marine bunkering despite intrinsic safety advantages.
Strategic Opportunities
- Hydrogen Fueling Infrastructure:Dual-fuel pump designs compatible with liquid hydrogen and conventional diesel are capturing early specification wins at European port authorities piloting alternative marine fuels.
- Indian Agricultural Mechanization:Tractor-mounted transfer pumps represent underpenetrated demand as the country's PLI scheme for farm equipment expands distribution networks into Bihar and Uttar Pradesh.
- IoT-Enabled Predictive Maintenance:Sensor-integrated pump systems transmitting vibration and flow data to cloud platforms are creating recurring revenue streams through subscription diagnostics.
Industry Challenges
- ATEX Certification Backlogs:European notified bodies are extending review timelines for explosion-proof motor housings, delaying product launches for manufacturers targeting North Sea offshore platforms.
- Legacy System Integration:Retrofitting smart pump controllers into existing tank farm automation architectures requires custom protocol bridging, inflating deployment costs for mid-size fuel terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Transfer Pump Market |
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $3.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Pneumatic, Hydraulic Application: Construction Equipment, Marine Vessels, Agricultural Machinery, Mining Operations End User: Fuel Distributors, Equipment Manufacturers, Transport Operators, Maintenance Services Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Piusi S.p.A., Graco Inc., Great Plains Industries, Tuthill Corporation, Fill-Rite, INTRADIN, Groz Engineering Tools (P) Ltd., Gespasa, MALHAR CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Transfer Pump Market Strategic Shifts & Innovations
Permanent magnet synchronous motor technology is compressing energy consumption benchmarks while digital flow metering is enabling real-time consumption tracking. These shifts are restructuring supplier value propositions around total cost of ownership rather than upfront equipment pricing.
Brushless DC pump architectures are supplanting brushed motor designs in medium-duty construction applications. Fleet operators in the US Southwest are specifying sealed-for-life bearing systems to eliminate maintenance intervals in dusty environments. This technology is supplanting traditional rebuildable pump platforms and compressing aftermarket parts revenue for legacy service networks.
China's MEE dual carbon goals are tightening fugitive emission limits for fuel logistics equipment nationwide. Domestic pump manufacturers are accelerating dry-seal magnetic drive designs to eliminate mechanical seal leakage paths. State-owned petroleum distributors are responding by pre-qualifying only MEE-certified suppliers for corridor infrastructure tenders.
Buying committees at large transport operators are unbundling pump procurement from integrated fueling system contracts. Independent pump specialists are capturing direct specification authority previously held by tank and dispenser OEMs. This pattern is most visible in German freight logistics, where fleet managers are negotiating separate maintenance agreements with component suppliers.
Fuel Transfer Pump Market Segmentation
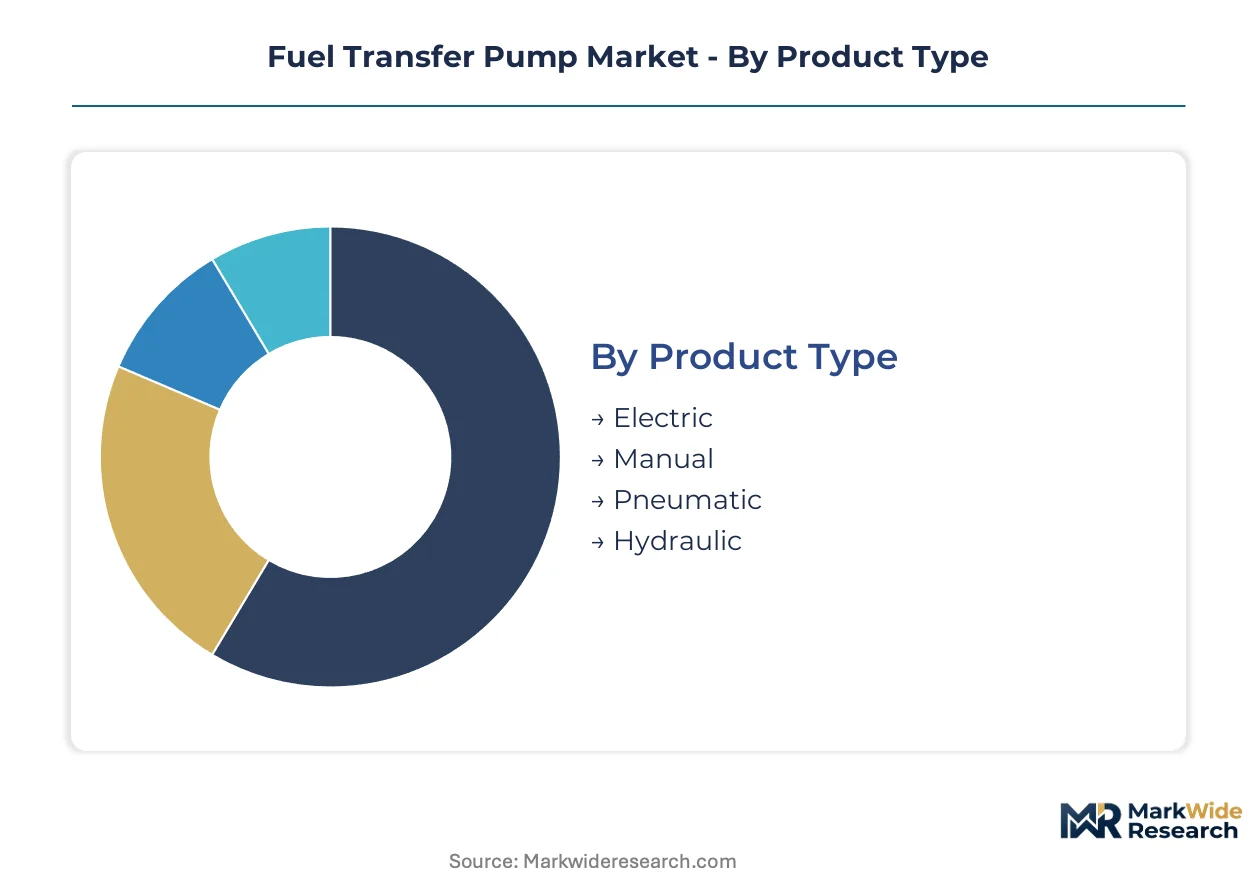
Segmentation in fuel transfer pumps reveals how regulatory pressure, automation requirements, and operational intensity reshape procurement across construction, marine, and agricultural verticals. Understanding these divisions exposes where margin pools concentrate and which specifications command premium positioning.
Product Type:
EPA vapor recovery mandates and OSHA hazardous location classifications create divergent certification pathways that segment electric, pneumatic, and manual architectures into distinct compliance tiers.
- Electric:Brushless DC motor designs integrate with telematics platforms for automated flow control and remote monitoring. Construction equipment lessors in the US Southwest specify sealed-for-life bearing systems to eliminate maintenance in dusty environments, compressing total cost of ownership calculations against pneumatic alternatives.
- Pneumatic:Compressed-air drive systems eliminate ignition risk in explosive atmospheres without explosion-proof motor housings. Throughput limitations above 200 liters per minute constrain adoption in high-volume marine bunkering despite intrinsic safety advantages for offshore platform fueling.
- Manual:Hand-cranked diaphragm pumps serve remote agricultural sites lacking electrical infrastructure or compressed air supply. Portable units dominate small-scale refueling of stationary generators and backup power systems in developing logistics corridors.
- Hydraulic:Power-take-off driven pumps leverage existing machinery hydraulics for high-flow transfer without separate power sources. Mining operators in high-altitude zones deploy these for compatibility with heavy equipment hydraulic circuits.
Established volume favors electric architectures; emerging adoption favors pneumatic systems in hazardous location classifications.
Application:
Operational intensity and fuel throughput requirements segment demand across equipment types, with automation compatibility and environmental exposure driving specification divergence.
- Construction Equipment:Fleet lessors prioritize brushless DC pump integration with equipment telematics for usage tracking and predictive maintenance scheduling. Dust-sealed bearing systems eliminate field service intervals in arid climate operations.
- Marine Vessels:Dual-fuel pump architectures compatible with liquid hydrogen and conventional diesel capture early specification at European port authorities piloting alternative marine fuels. High-throughput bunkering demands exceed pneumatic substitution ceilings.
- Agricultural Machinery:Tractor-mounted transfer pumps represent expanding demand as India's PLI scheme for farm equipment extends distribution networks into Bihar and Uttar Pradesh. Manual and low-power electric units dominate smallholder operations.
- Mining Operations:Portable high-throughput pumps operate at altitude with minimal infrastructure in China's western industrial corridors and Mongolian border zones. Hydraulic drive compatibility with existing equipment reduces capital deployment.
Marine applications command the steepest expansion trajectory for dual-fuel architectures; agricultural machinery offers the deepest penetration runway in emerging mechanization markets.
End User:
Procurement authority is shifting from integrated system vendors toward component specialists as buying committees unbundle pump specifications from tank and dispenser contracts.
- Fuel Distributors:State-backed petroleum networks in China pre-qualify MEE-certified suppliers for corridor infrastructure tenders, concentrating procurement volumes. Dry-seal magnetic drive designs eliminate mechanical seal leakage paths to meet dual carbon goals.
- Equipment Manufacturers:OEM integration of pumps into original fueling systems requires custom protocol bridging for smart controller compatibility. Mid-size fuel terminals face inflated deployment costs from legacy automation architecture retrofit requirements.
- Transport Operators:German freight logistics fleet managers negotiate separate maintenance agreements with component suppliers, bypassing tank OEM specification authority. Telematics integration demands reshape vendor selection criteria.
- Maintenance Services:Independent service networks face compressed aftermarket parts revenue as sealed-for-life bearing systems displace rebuildable pump platforms. Predictive maintenance subscriptions create recurring revenue through sensor-integrated diagnostics.
Equipment manufacturers retain the largest current procurement volumes; maintenance services are gaining specification fastest through outcome-based service contracts.
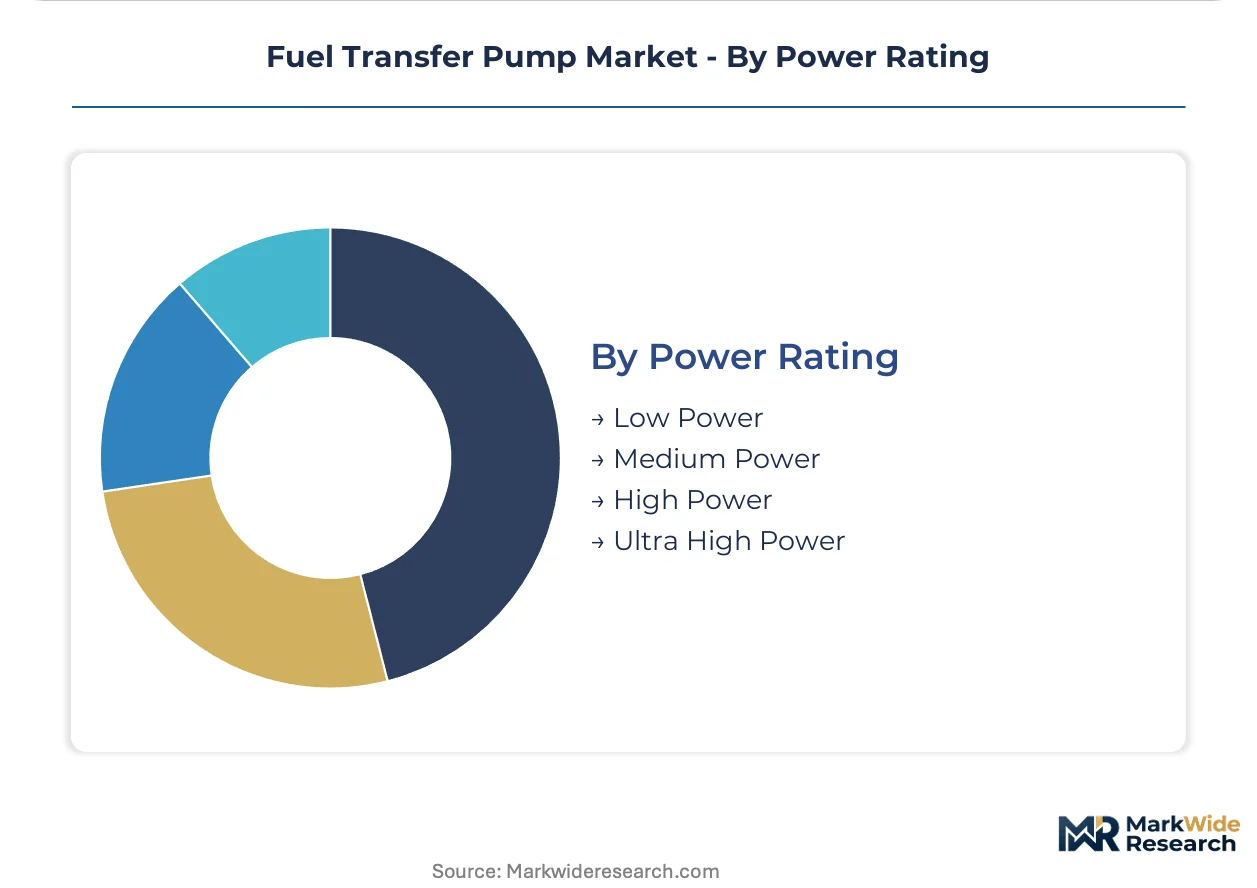
Power Rating:
Portability-throughput tradeoffs concentrate margin pools where specifications balance mobility with flow rate for specific equipment classes.
- Medium Power:Balances portability with throughput across construction equipment and agricultural machinery applications, occupying the largest margin pool. Electric architectures dominate with brushless DC motor efficiency.
- Low Power:Manual and small electric units serve stationary generators and smallholder agricultural operations. Cost sensitivity limits feature integration and smart controller adoption.
- High Power:Sustained flow rates for marine bunkering and mining fleet refueling require robust sealing architectures under EPA vapor recovery mandates. Fluoropolymer material selection extends certification timelines.
- Ultra High Power:Specialized deployment for high-volume terminal operations and pipeline transfer stations. Concentrated procurement volumes in state-backed fuel distribution networks.
Medium power ratings anchor current revenue concentration; ultra high power systems are expanding most quickly in corridor infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for precision-machined pump housings clusters in Zhejiang and Guangdong provinces, exposing lead times to regional power rationing. Demand fragmentation across regulatory jurisdictions creates divergent certification pathways for sealing architectures and motor housings.
United States
Transport fleet operators are expanding dedicated refueling infrastructure to compress downtime across interstate corridors. EPA vapor recovery mandates and OSHA hazardous location classifications enforce fluoropolymer seal selection and explosion-proof motor specifications. Dallas-Fort Worth logistics clusters concentrate procurement volumes for construction equipment lessors integrating brushless DC pumps with telematics platforms.
China
State-backed petroleum distributors are pre-qualifying MEE-certified suppliers for western industrial corridor tenders serving remote mining zones. The Ministry of Ecology and Environment dual carbon goals pressure dry-seal magnetic drive adoption to eliminate mechanical seal leakage paths. Xinjiang and Inner Mongolia border zones deploy portable high-throughput pumps at altitude with minimal fixed infrastructure.
Germany
German freight logistics buying committees unbundle pump procurement from integrated tank and dispenser contracts, shifting specification authority toward component specialists. REACH chemical restrictions on perfluorinated compounds force gasket material reformulation and extend ATEX certification timelines. Hamburg port authorities pilot dual-fuel pump architectures compatible with liquid hydrogen bunkering.
India
Tractor-mounted transfer pumps penetrate agricultural mechanization markets as the PLI scheme for farm equipment extends distribution into Bihar and Uttar Pradesh. The Bureau of Indian Standards implements progressive efficiency benchmarks for fuel logistics equipment. Punjab and Haryana farming cooperatives drive smallholder demand for manual and low-power electric refueling units.
Brazil
Mining operators in the Carajás mineral province specify hydraulic drive pumps leveraging existing heavy equipment circuits for high-flow transfer without separate power sources. ANVISA workplace safety protocols govern explosion-risk environments in remote extraction sites. São Paulo industrial corridors concentrate maintenance service networks facing compressed aftermarket revenue from sealed-for-life bearing systems.
Fuel Transfer Pump Market Key Industry Players
Concentration sits with fluid handling specialists and precision component fabricators rather than diversified industrial conglomerates. The vendor base separates into three strategic archetypes: premium electric pump specialists leveraging telematics integration, rotary vane technology leaders with captive machining capacity, and regional ATEX-certified system providers controlling Mediterranean distributor networks. Competitive moves center on backward integration into precision foundry operations and technology licensing for hydrogen-compatible sealing architectures.
Among North American fluid handling specialists, Graco Inc. and Tuthill Corporation occupy positions reflecting divergent technical specializations. Graco anchors the premium electric pump tier through brushless DC motor integration with construction and marine telematics platforms. Tuthill exemplifies rotary vane technology leadership with in-house production of precision-machined components insulating against Zhejiang and Guangdong foundry concentration risk. European logistics equipment provider Piusi S.p.A. represents the ATEX-certified system archetype with channel control across Mediterranean fuel distribution networks. Great Plains Industries and Fill-Rite sit within the mid-scale agricultural and transport operator segment, while INTRADIN and Groz Engineering Tools (P) Ltd. reflect Asia-Pacific fabrication positions serving cost-sensitive manual and pneumatic pump demand.
| Leading Market Players |
|---|
| Piusi S.p.A. |
| Graco Inc. |
| Great Plains Industries |
| Tuthill Corporation |
| Fill-Rite |
| INTRADIN |
| Groz Engineering Tools (P) Ltd. |
| Gespasa |
| MALHAR CORPORATION |
| Others |
Cost & Logistics Intelligence
Foundry scale economies in Zhejiang and Guangdong provinces compress unit costs for precision-machined pump housings while simultaneously anchoring price floors through regional power rationing exposure. This concentration grants dominant suppliers pricing leverage over mid-tier fabricators dependent on outsourced casting capacity.
Pricing Analysis
Volume-discount tiering structures separate MEE-certified premium systems from standard ATEX-compliant units and economy-grade manual pumps. Price differentiation rests on certification grade and smart controller integration, with construction fleet operators showing lowest sensitivity due to telematics compatibility requirements. Cost compression in economy tiers is intensifying because Indian agricultural distributors negotiate aggressively on tractor-mounted units. Fuel distributors pre-qualifying for Chinese state corridor tenders accept premium positioning with minimal price resistance.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and transpacific container availability constraints are elevating landed costs for North American distributors sourcing complete pump assemblies. Precision-machined housings draw from concentrated foundry capacity in China, while fluoropolymer seal materials feed from German and Japanese specialty chemical producers. Single-source vulnerability sits with Zhejiang aluminum casting networks exposed to regional energy rationing. Distribution runs through Mediterranean fuel equipment specialists and North American fluid handling distributors serving construction and marine end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
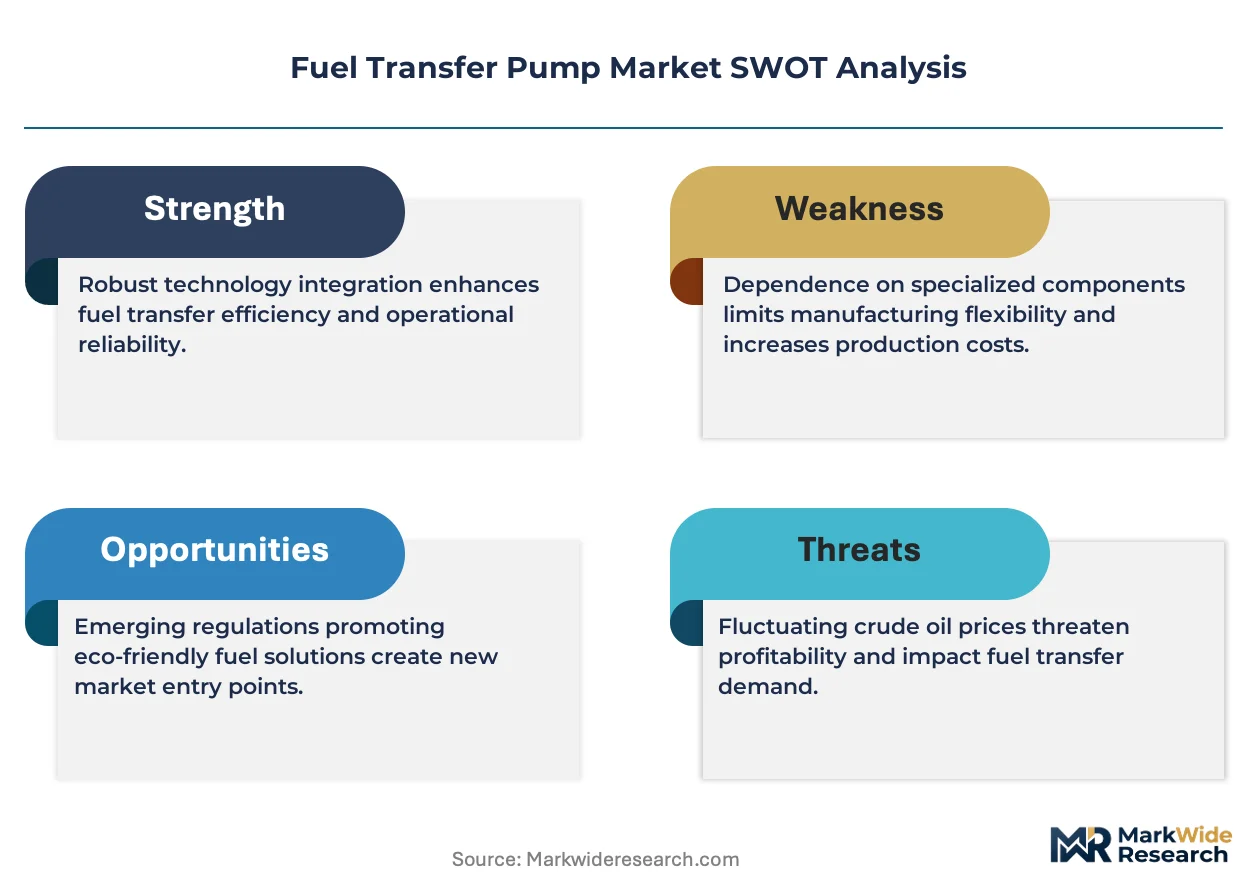
Electric pump architectures and hydrogen-compatible sealing technologies are disrupting procurement specifications faster than legacy vendors can retool, compressing response windows for established positions.
For Market Incumbents: Consolidate backward into captive foundry operations to insulate margin structures from Zhejiang power rationing volatility. Lock ATEX certification capacity at European notified bodies before review timelines extend further. Sealed-for-life bearing platforms are displacing rebuildable service revenue streams and threatening aftermarket-dependent business models. For New Entrants and Emerging Players: Differentiate on IoT-enabled predictive maintenance subscriptions targeting mid-size fuel terminals struggling with legacy automation integration costs. White-space concentration sits with Indian agricultural mechanization corridors in Bihar and Uttar Pradesh where PLI scheme distribution expansion outruns established vendor coverage. Partner with domestic tractor OEMs for original equipment specification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-machining specialists with in-house casting capacity and hydrogen-sealing R&D pipelines. Long-term viability hinges on dual-fuel architecture readiness as European port authorities advance liquid hydrogen bunkering pilots. Monitor MEE certification pre-qualification lists as signal for Chinese state procurement favoritism consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Foundry Operations | Captive aluminum casting capacity insulates Graco and Tuthill from Zhejiang supply disruptions. |
| Hydrogen-Compatible Sealing Architecture Development | Dual-fuel pump designs capture Hamburg and Rotterdam port authority alternative fuel pilot specifications. |
| IoT Platform Integration for Predictive Maintenance | Sensor-integrated systems create recurring revenue from vibration diagnostics subscriptions at US construction fleets. |
| MEE Certification Pre-Qualification Investment | Dry-seal magnetic drive approval opens Chinese western corridor infrastructure tenders to qualified suppliers. |
| Channel Control Expansion in Mediterranean Networks | Piusi's distributor relationships defend European fuel logistics positioning against electric pump specialists. |
Research Approach
The analysis maps electric, pneumatic, manual, and hydraulic pump architectures, each validated through maintenance directors at construction fleets, OEM procurement teams, fuel distributor operations managers, and aftermarket service heads. Primary interviews triangulate with customs data on aluminum casting trade flows, EPA vapor recovery enforcement records, MEE certification registries, and SEC filings from fluid handling specialists. Bottom-up unit economics and top-down sector sizing cross-validate volume estimates.
Consistency checks against external benchmarks confirm segmentation outputs across power rating tiers, application verticals, and end-user procurement authority shifts. The modeling framework incorporates flow rate specifications, automation compatibility indices, and regional regulatory cluster intensity throughout the projection horizon. CAGRs derive from equipment replacement cycles, fleet expansion trajectories, and corridor infrastructure buildout schedules without year-specific anchoring.
Material uncertainties — regulatory acceleration on fugitive emissions, hydrogen infrastructure deployment pacing, and foundry capacity rebalancing — sit outside the modeled envelope. Forecasts reflect assumptions on certification timeline stability and telematics platform standardization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Air Breathing Hose Market