
 Solar Pump Inverter Market | 2026-2036
Solar Pump Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Pump Inverter Market Analysis
The product tier split in solar pump inverters is recalibrating around MPPT precision and remote monitoring capability versus basic voltage-frequency conversion. Sungrow leverages its power electronics heritage to dominate utility-scale agricultural installations across Asia. Grundfos anchors its position through captive pump-inverter system integration that reduces field mismatch losses. SMA competes in premium European markets with extended warranty architectures and grid-forming functionality.
A solar pump inverter converts variable DC output from photovoltaic arrays into frequency-controlled AC power matched to pump motor torque-speed requirements, typically spanning 0.75 kW to 75 kW with IP65 enclosure ratings for outdoor deployment. Its primary commercial purpose is displacing diesel or grid-dependent irrigation in off-grid and weak-grid agricultural zones. MPPT-based systems command the dominant value share as farmers prioritize water yield per installed kilowatt. Off-grid inverters represent the fastest-expanding category where rural electrification gaps persist. Digital controller integration is reshaping margin pools by enabling predictive maintenance and remote flow optimization.
India's Ministry of New and Renewable Energy and the Bureau of Indian Standards shape product certification through mandatory efficiency testing and solar pump component localization rules under the PLI scheme. REACH and RoHS compliance in Europe restricts certain semiconductor packaging materials, elevating design costs for exporters. China's GB standards and MIIT efficiency tiers dictate domestic market access thresholds. Stakeholders must monitor how subsidy phase-out schedules and inverter efficiency mandates interact to determine viable price-performance positioning in each major procurement zone.
Market Dynamics
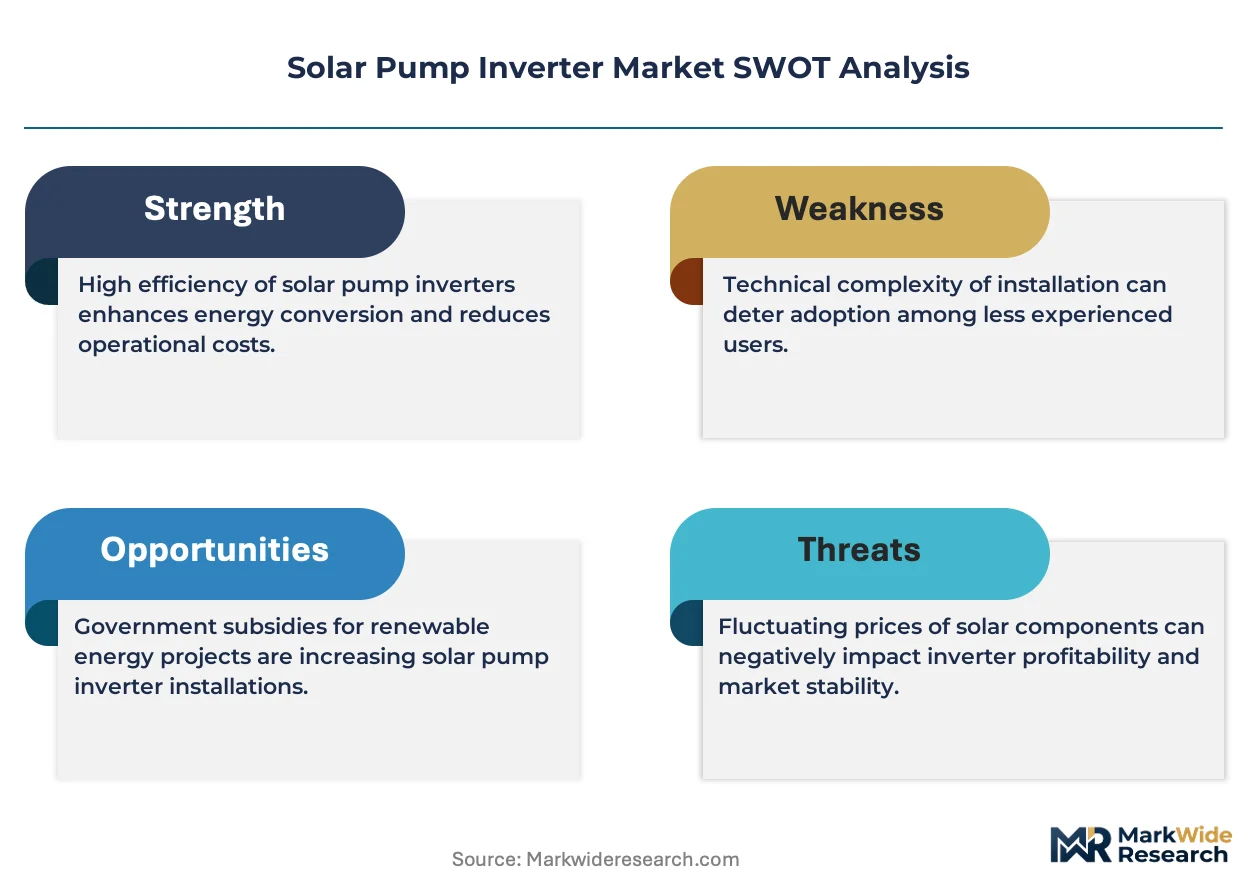
MPPT efficiency gains and subsidy phase-out schedules are forcing manufacturers to recalibrate price-performance positioning around water yield per installed kilowatt rather than upfront hardware cost.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for solar component localization are accelerating domestic manufacturing scale and reducing import dependency for critical power electronics.
- Agricultural groundwater depletion:Western and southern Indian states now mandate solar-powered extraction, creating procurement pull for off-grid pump inverters in arid irrigation zones.
- MPPT algorithm advancement:Precision maximum power point tracking is improving water yield per kilowatt, shifting farmer preference toward digitally controlled systems over basic voltage-frequency converters.
Market Restraints
- Semiconductor packaging costs:REACH and RoHS compliance in Europe restricts certain materials, elevating design expenses for exporters serving premium markets.
- Weak-grid infrastructure:Rural electrification gaps in target agricultural zones limit grid-tied inverter deployment, constraining addressable market expansion.
- Diesel generator substitution:Backup diesel systems retain cost advantages in intermittent-sunlight regions, delaying full displacement timelines.
Strategic Opportunities
- Remote monitoring convergence:Integration of IoT sensors with pump controllers enables predictive maintenance contracts and recurring revenue streams beyond hardware sales.
- Sub-Saharan Africa irrigation:Off-grid agricultural zones with high solar irradiance and limited diesel supply chains represent underpenetrated deployment territory.
- China's MIIT efficiency tiers:Domestic market access thresholds are tightening, creating first-mover advantage for manufacturers achieving top-tier GB standard certification.
Industry Challenges
- Field mismatch losses:Pump-inverter incompatibility in retrofitted installations demands specialized commissioning expertise that remains scarce in rural deployment zones.
- BIS certification timelines:Mandatory efficiency testing under India's Bureau of Indian Standards creates procurement delays for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Pump Inverter Market |
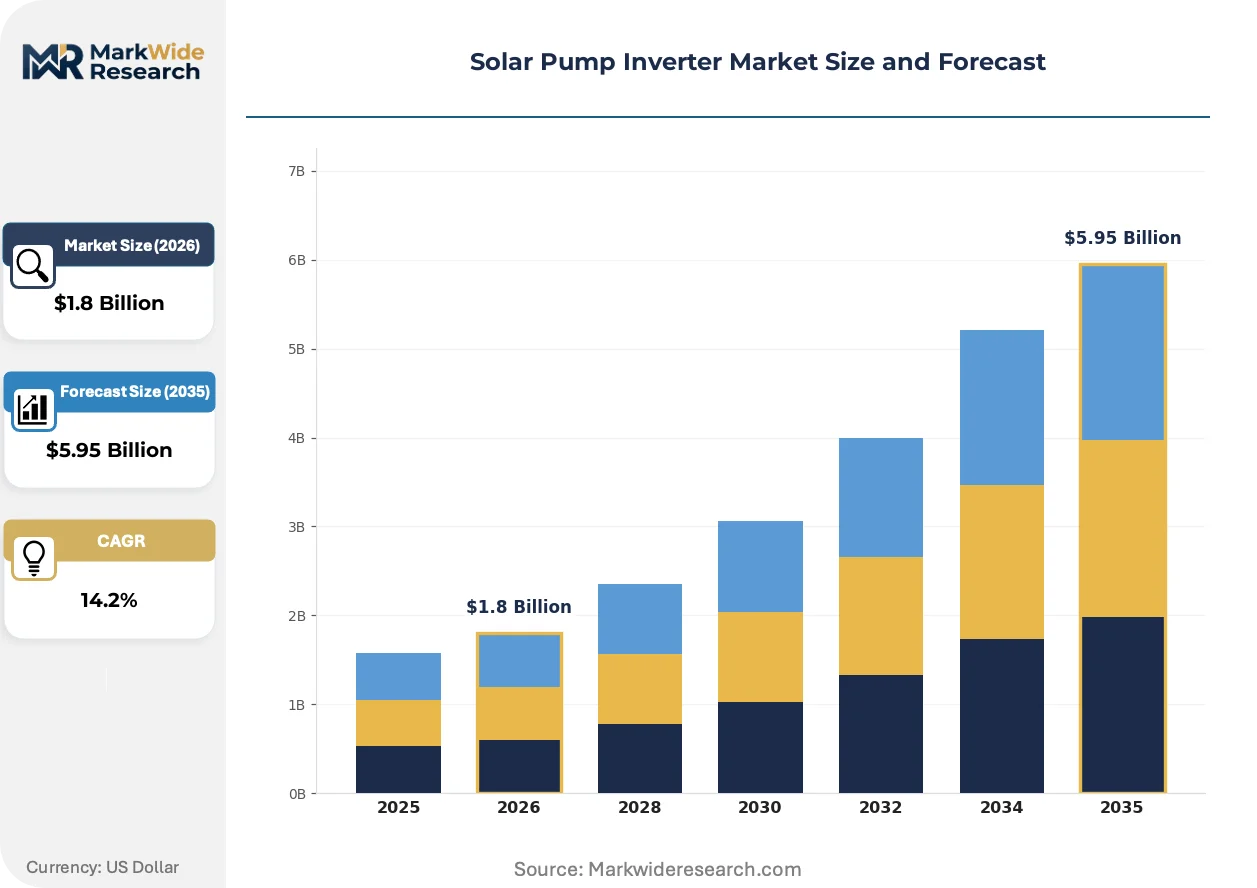
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Inverters, Grid-Tie Inverters, Off-Grid Inverters, Micro Inverters Technology: MPPT, PWM, Hybrid Systems, Digital Controllers End User: Agriculture, Residental, Industrial, Commercial Distribution Channel: Direct Sales, Online Sales, Retail Stores, Distributors |
| Companies Covered | Zhejiang Sandi Electric Co.,Ltd, Sungrow, Lorentz, SMA, Huawei, Grundfos, FOSHAN TOP ONE POWER TECHNOLOGY CO.LTD, Deye, Shenzhen Solartech Renewable Energy Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Pump Inverter Market Emerging Trajectories
Digitization of pump control architectures is redrawing margin pools by enabling remote flow optimization and shifting value capture from hardware toward software-enabled service layers.
String-level MPPT with module-level power electronics is decentralizing array design flexibility, allowing farmers to deploy irregular panel configurations across uneven terrain. Smallholder cooperatives in India's Maharashtra and Gujarat are adopting these architectures fastest. The technology is decentralizing installer specialization requirements, broadening the qualified technician base beyond certified solar electricians.
India's Bureau of Indian Standards efficiency mandates under the PLI scheme are compressing viable product tiers, forcing exit of sub-90% MPPT accuracy hardware. Domestic manufacturers must redesign magnetic components and thermal management to meet tier-one thresholds. Agricultural procurement tenders in Rajasthan and Karnataka now specify BIS-certified inverters exclusively, locking out uncertified imports.
Farmer cooperatives are consolidating purchase decisions through state-level nodal agencies, compressing vendor negotiation cycles and standardizing specification requirements. Equipment distributors serving these channels must now maintain BIS certification documentation and localized spare parts inventory. This pattern is most visible in India's western irrigation corridors where groundwater regulation enforcement is strictest.
Solar Pump Inverter Market Segmentation
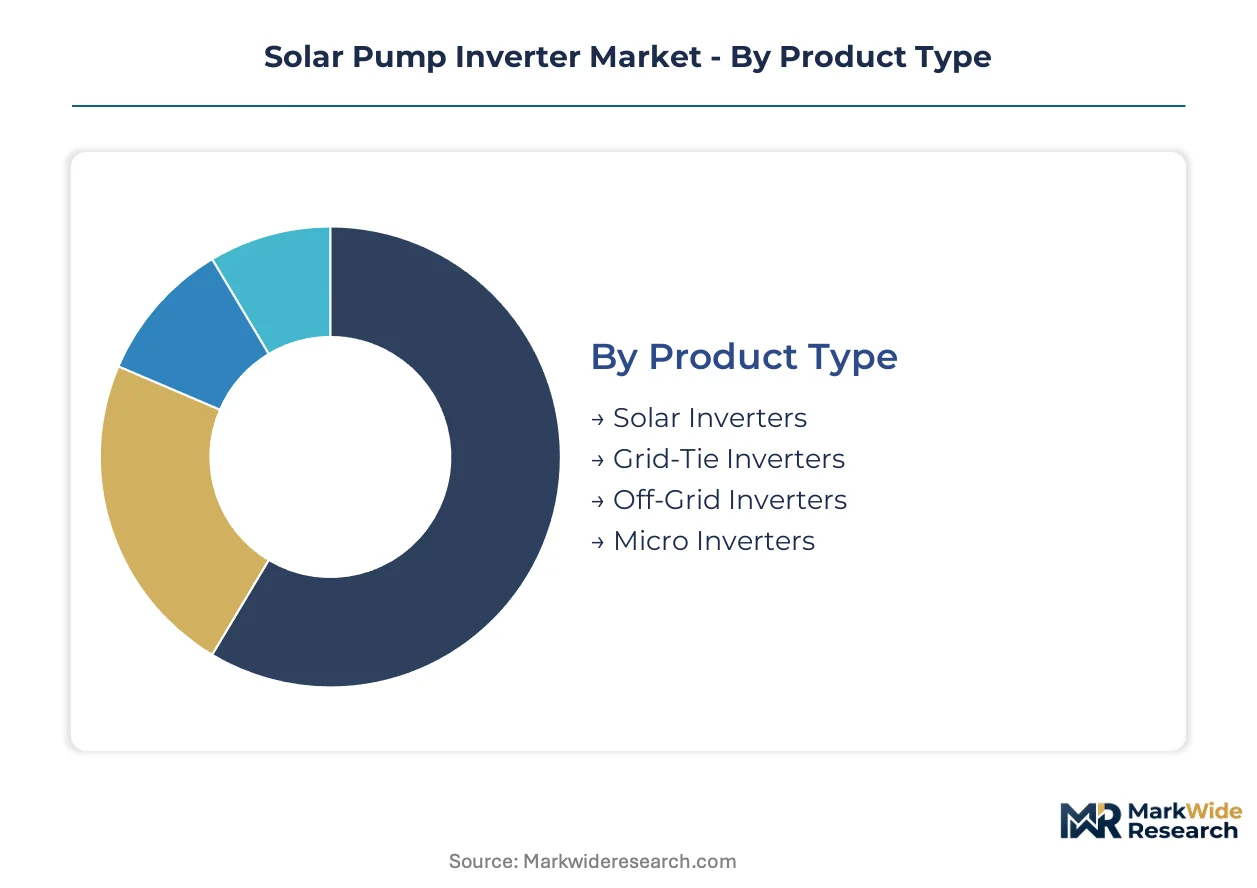
Solar pump inverter procurement splits sharply between integrated pump-controller systems and standalone retrofit units. Farmers in water-stressed districts prioritize MPPT precision and remote monitoring over basic voltage conversion, reshaping how manufacturers tier their product portfolios.
Product Type:
Standalone inverters dominate retrofit installations where existing pumps are retained, while embedded pump-inverter systems capture new deployment contracts.
- Solar Inverters:Purpose-built DC-to-AC converters optimized for photovoltaic array output, typically rated 0.75 kW to 75 kW with IP65 enclosures. Demand concentrates in India's western groundwater regulation zones where BIS-certified units are now mandatory for subsidy eligibility.
- Off-Grid Inverters:Battery-independent designs with integrated MPPT controllers for weak-grid or unelectrified agricultural zones. Sub-Saharan African irrigation cooperatives are deploying these fastest where diesel supply chains remain unreliable.
- Grid-Tie Inverters:Synchronous connection equipment for net-metering installations with export capability to distribution networks.
- Micro Inverters:Module-level power electronics enabling string-level MPPT across irregular terrain configurations.
Solar inverters lead volumes today; off-grid inverters are gaining share fastest.
Technology:
Cost tiers separate precision-controlled digital architectures from analog voltage-frequency converters, with efficiency thresholds dictating viable positioning.
- MPPT:Maximum power point tracking algorithms continuously adjust electrical load to extract peak photovoltaic output. Rajasthan and Karnataka agricultural tenders now specify sub-90% accuracy exclusion, compressing viable supplier tiers.
- Digital Controllers:Embedded microprocessors enabling predictive maintenance, remote flow optimization, and IoT sensor integration. Maharashtra farmer cooperatives are adopting these architectures to reduce technician dispatch costs.
- PWM:Pulse-width modulation converters with fixed switching patterns for basic irrigation applications.
- Hybrid Systems:Dual-source controllers managing solar-diesel or solar-grid input switching.
MPPT commands the dominant value position; digital controllers are climbing the fastest.
End User:
Customer type determines specification complexity, with large-scale agricultural procurement driving standardization while residential installations fragment across custom requirements.
- Agriculture:Irrigation pumping for groundwater extraction, surface water lifting, and drip distribution networks. India's PLI scheme and state-level nodal agency consolidation are concentrating demand through standardized tenders in Gujarat and Maharashtra.
- Industrial:Process water systems, cooling circuits, and wastewater management with continuous-duty requirements.
- Commercial:Landscaping, golf course irrigation, and municipal water features with intermittent operation profiles.
- Residential:Domestic water supply and small-scale gardening applications with sub-5 kW capacity needs.
Agriculture leads volumes today; industrial applications are expanding most quickly.
Distribution Channel:
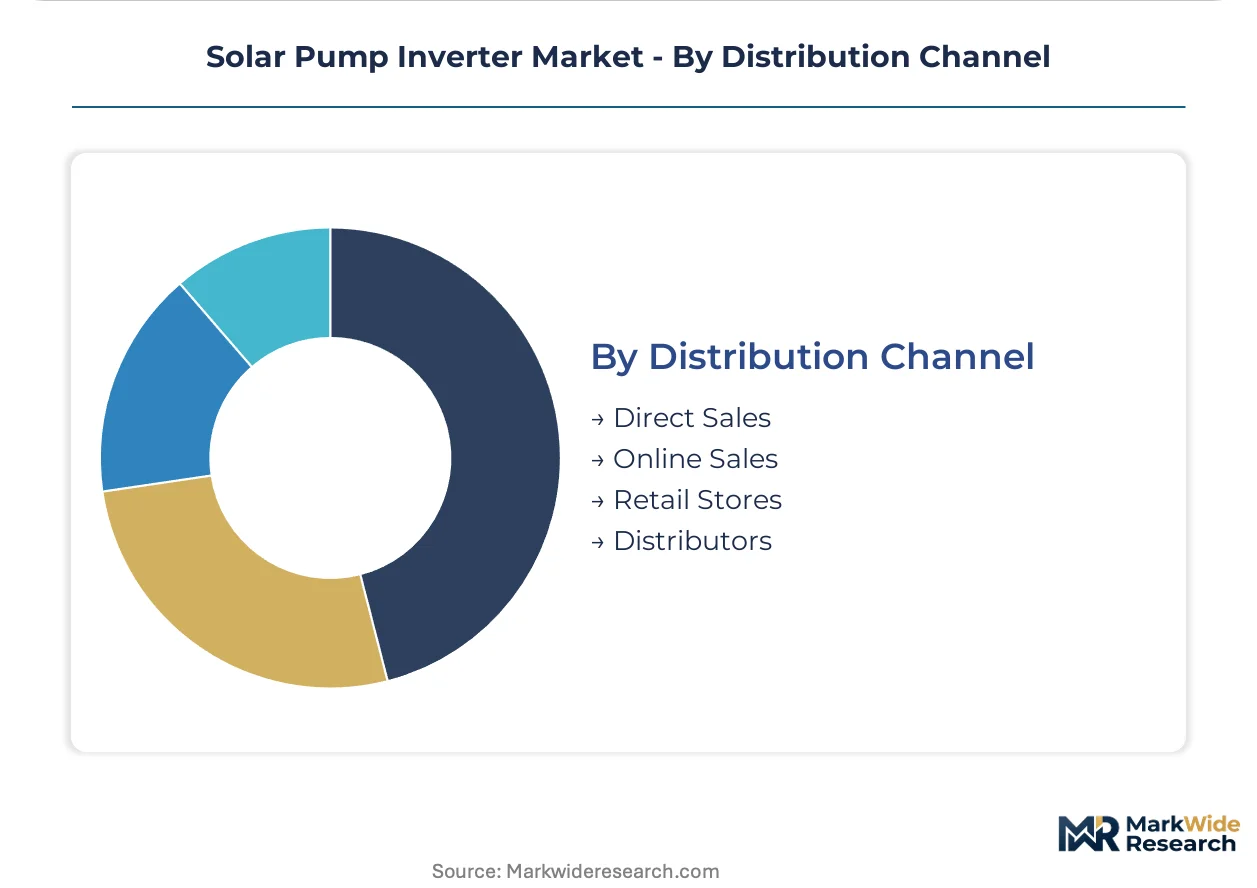
Supply concentration favors distributor networks with localized certification documentation and spare parts inventory over direct manufacturer relationships.
- Distributors:Regional equipment suppliers maintaining BIS certification files, commissioning expertise, and field service capabilities. India's western irrigation corridors depend on these channels where groundwater regulation enforcement is strictest.
- Direct Sales:Manufacturer-to-nodal agency contracts for large-scale agricultural tenders with volume guarantees.
- Online Sales:E-commerce platforms serving replacement part procurement and small-capacity residential buyers.
- Retail Stores:Counter sales for immediate-need accessories and basic voltage-frequency converters.
Distributors lead volumes today; direct sales are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in power electronics and agricultural systems engineering concentrate procurement decisions in jurisdictions with strong technical vocational pipelines and subsidy administration capacity.
India
Groundwater depletion in Rajasthan and Gujarat drives state-mandated solar pump retrofits. MNRE's PM-KUSUM scheme channels subsidies through nodal agencies requiring BIS-certified inverters. Maharashtra's agricultural cooperatives consolidate bulk tenders through Pune-based distribution networks.
China
Domestic irrigation automation and export manufacturing dual demand shapes procurement. MIIT efficiency tiers under GB standards compress viable supplier tiers. Zhejiang and Guangdong provinces host captive production clusters serving both domestic agricultural modernization and overseas solar pump system integration.
Germany
Precision agriculture and viticulture irrigation sustain premium-tier demand. REACH and RoHS compliance elevates design costs for power electronics serving EU markets. Bavaria's agricultural technology corridor anchors R&D concentration for grid-forming inverter architectures.
United States
California's agricultural water stress and federal IRA clean energy incentives accelerate diesel displacement. NHTSA and EPA emissions regulations indirectly favor solar pump adoption in off-grid farming zones. Central Valley irrigation districts pilot remote monitoring integration with existing distribution infrastructure.
Brazil
Cerrado and semi-arid Northeast irrigation expansion targets soybean and fruit export corridors. ANVISA and INMETRO certification requirements structure import competition. São Paulo state's agricultural machinery distributors build localized commissioning capacity for MPPT-based systems.
Solar Pump Inverter Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. The vendor base stratifies between integrated pump-inverter system architects and standalone power electronics specialists. Three archetypes dominate: utility-scale agricultural project integrators, premium European grid-forming technology providers, and cost-optimized Asian component fabricators. Capacity expansion and backward integration into magnetic components represent the primary competitive vectors as efficiency thresholds tighten.
Among Chinese power electronics specialists, Zhejiang Sandi Electric Co.,Ltd and Shenzhen Solartech Renewable Energy Co., Ltd exemplify the scale-driven fabrication archetype serving agricultural retrofit markets. Sungrow occupies a position within the utility-scale integration tier, leveraging power electronics heritage across Asian irrigation corridors. These three entities represent distinct geographic and structural positioning within a market where certification documentation and localized spare parts inventory increasingly determine distributor channel viability.
| Leading Market Players |
|---|
| Zhejiang Sandi Electric Co.,Ltd |
| Sungrow |
| Lorentz |
| SMA |
| Huawei |
| Grundfos |
| FOSHAN TOP ONE POWER TECHNOLOGY CO.LTD |
| Deye |
| Shenzhen Solartech Renewable Energy Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Magnetic core materials and IGBT modules flow from upstream semiconductor foundries through three-tier pricing structures that separate premium MPPT architectures from basic voltage-frequency converters, with BIS certification tiers in India and MIIT efficiency grades in China anchoring price differentiation downstream.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes project-based hardware sales from recurring predictive maintenance contracts. Pricing stratifies across premium, standard, and economy tiers based on MPPT accuracy thresholds and remote monitoring capability. Cost compression in the economy tier intensifies as Indian nodal agencies consolidate bulk tenders. Smallholder cooperatives in Maharashtra exhibit highest price sensitivity, while European viticulture operators accept premium positioning for extended warranty architectures.
Supply Chain Analysis
Refurbishment flows for field-failed inverters concentrate in Zhejiang and Guangdong service hubs, creating secondary parts markets that compete with OEM spare parts pricing. Magnetic components and power semiconductors draw from China, Taiwan, and South Korea fabrication networks. Single-source vulnerability in advanced IGBT sourcing elevates risk exposure for tier-one efficiency designs. Distribution runs through regional equipment distributors maintaining localized BIS certification documentation and commissioning expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as agricultural groundwater regulation spreads across arid irrigation corridors, embedding solar pump infrastructure as mandatory compliance hardware rather than discretionary capital expenditure.
For Market Incumbents: Extend warranty architectures and remote monitoring service layers to capture recurring revenue beyond transactional hardware sales. Deepen backward integration into magnetic component production to defend margin position against cost-optimized Asian fabricators. Prioritize BIS certification maintenance as Indian nodal agencies harden procurement specifications. For New Entrants and Emerging Players: Launch via distributor partnerships in Sub-Saharan African irrigation cooperatives where diesel supply chain unreliability creates white-space demand. Target off-grid agricultural zones in Kenya and Tanzania with battery-independent MPPT designs. Anchor go-to-market positioning on technician training programs that address field mismatch loss mitigation. For Investors and Strategic Acquirers: Consolidation pressure builds where distributor networks hold irreplaceable certification documentation and localized commissioning expertise. The five-to-ten year viability window favors asset-light designers with captive software service revenue over pure hardware fabricators. Monitor PLI scheme subsidy phase-out schedules as inflection indicators for domestic Indian manufacturer competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Components | Captive ferrite core production insulates margin from semiconductor commodity volatility. |
| Remote Monitoring Platform Deployment | IoT sensor integration enables predictive maintenance contracts beyond hardware margins. |
| BIS Certification Acceleration | Mandatory efficiency testing under Indian standards locks out uncertified import competition. |
| Sub-Saharan Distribution Partnership | Localized commissioning capacity addresses field mismatch losses in agricultural retrofits. |
| MPPT Algorithm Licensing | Precision tracking software monetizes R&D investment across OEM pump-controller integrations. |
Methodological Framework
Coverage spans India, China, Germany, Brazil, and the United States, with primary inputs from each market combining interviews with solar EPC contractors, agricultural cooperative procurement managers, power electronics R&D directors, and distributor channel heads. Secondary validation draws from MNRE subsidy disbursement records, BIS certification registries, MIIT efficiency tier announcements, and customs trade data. Bottom-up installation tracking and top-down equipment production estimates triangulate market sizing.
Granularity-level modeling disaggregates volume and value across product type, technology tier, end-use application, and distribution channel dimensions throughout the forecast period. CAGRs derive from segment-specific growth trajectories weighted by installed base evolution and replacement cycle timing. Irrigation water stress indices and subsidy administration capacity serve as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt subsidy phase-out schedules or semiconductor supply disruptions. Practitioners should monitor groundwater regulation enforcement intensity and nodal agency tender consolidation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Rotary Pump Market