
 Biocomposite Materials Market | 2026-2036
Biocomposite Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Biocomposite Materials Market Analytics
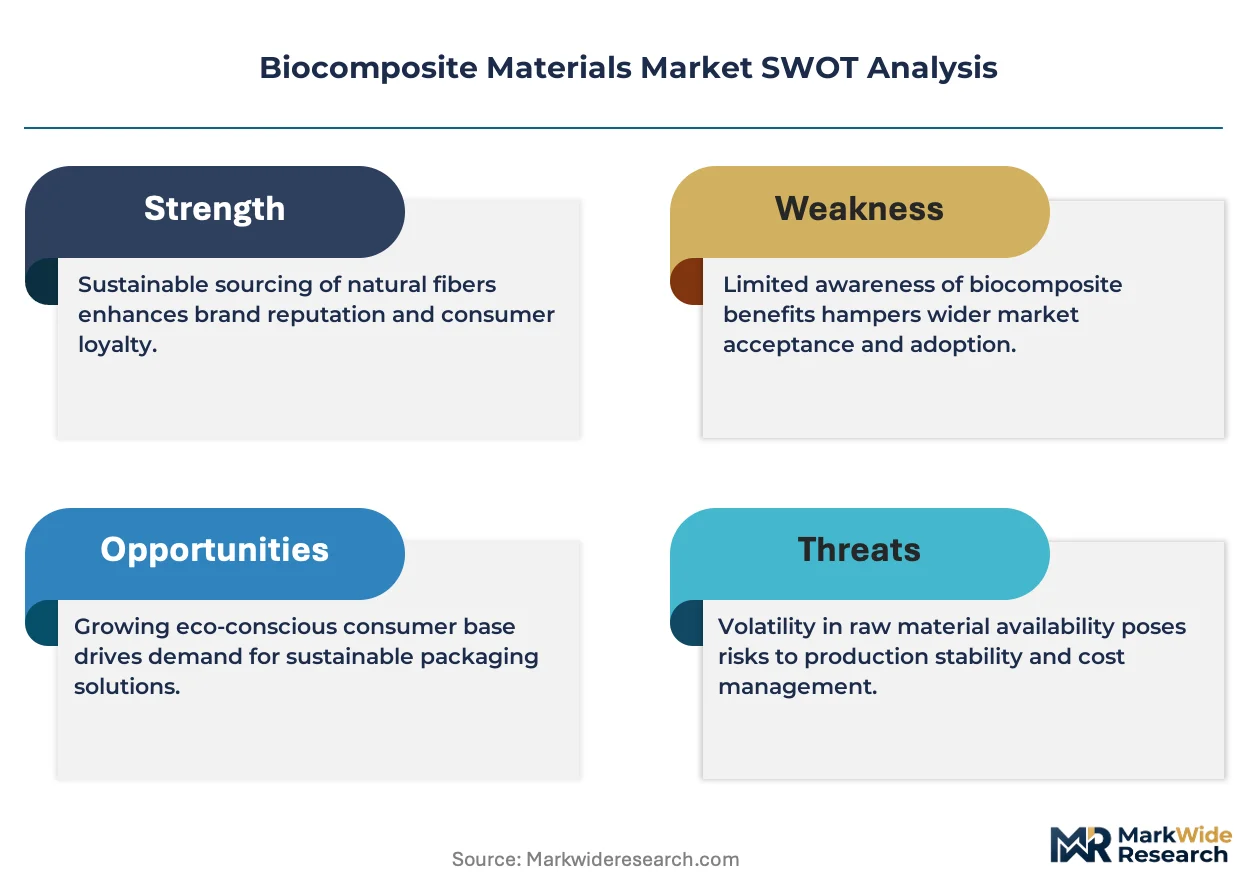
Specialized polymer chemists and natural fiber processing engineers are reorganizing the talent landscape for biocomposite scale-up, with European universities expanding dedicated programs faster than industry hiring cycles can absorb graduates. Trex Company leverages its captive wood-waste supply chain and decades of extrusion expertise to dominate North American decking applications. UPM anchors its position through backward integration into Nordic pulp and tall oil refining, securing consistent bio-based resin feedstock. Bcomp Ltd differentiates through ampliTex flax fiber architectures that compete directly with carbon fiber in motorsport and premium automotive interiors.
Biocomposite materials combine natural fibers—flax, hemp, jute, or wood flour—with bio-based or conventional polymer matrices to yield engineered materials with specific flexural strengths ranging from 30 to 150 MPa depending on fiber loading and orientation. These materials primarily serve industries seeking weight reduction, carbon footprint improvement, or end-of-life biodegradability without sacrificing structural performance. Wood-plastic composites currently occupy the largest value share across construction decking and fencing, though natural fiber composites in automotive door panels and seat backs represent the fastest-expanding margin pool as OEMs pursue scope 3 emission reductions. Bio-based resins derived from lignin and itaconic acid are gaining traction in packaging solutions where FDA and EU food-contact compliance creates premium positioning against petroleum-derived alternatives.
The European Chemicals Agency enforces REACH substance restrictions that limit certain petrochemical additives, indirectly advantaging bio-based formulations with cleaner hazard profiles. The U.S. EPA's growing scrutiny of microplastic release from conventional composites during abrasion and weathering is reshaping product testing protocols for outdoor construction applications. China's Ministry of Ecology and Environment dual carbon targets are channeling provincial subsidies toward hemp and bamboo fiber processing clusters. Stakeholders must monitor how rapidly evolving lifecycle assessment standards from ISO and national regulators will redefine what qualifies as "bio-based" versus merely "bio-filled" across procurement specifications.
Market Dynamics
EU Green Deal embodied carbon rules are compressing demand for conventional fiberglass and petroleum-based plastics across construction and automotive supply chains, redirecting procurement toward certified bio-based alternatives.
Growth Catalysts
- EU Green Deal tightening:Embodied carbon thresholds for construction materials are mandating substitution away from conventional composites in Germany, France, and the Netherlands.
- Automotive lightweighting:OEMs in Japan and Germany are integrating natural fiber composites into door panels and seat backs to reduce scope 3 emissions.
- Flax fiber processing clusters:Zhejiang and Jiangsu provinces in China are consolidating hemp and bamboo fiber supply with automotive and electronics manufacturing corridors.
Market Restraints
- Natural fiber supply volatility:Weather-dependent flax and hemp harvests in France and Belgium create input cost instability for European compounders.
- Bio-resin production concentration:Tall oil refining capacity clusters in Nordic regions, creating geographic supply risk for lignin-based matrix producers.
- Performance ceiling in high-load applications:Natural fiber composites face substitution pressure from carbon fiber in structural automotive components requiring flexural strength above 150 MPa.
Strategic Opportunities
- Underpenetrated US construction:Building code recognition gaps for biocomposite structural lumber present first-mover advantage in multi-family residential framing.
- Packaging regulatory tailwind:FDA and EU food-contact compliance pathways for lignin-derived resins are opening premium positioning against petroleum alternatives in fresh food containers.
- Hybrid material convergence:AmpliTex flax architectures combined with recycled carbon fiber are creating intermediate performance tiers for motorsport interiors.
Industry Challenges
- Polymer chemist scarcity:European universities are expanding dedicated biocomposite programs faster than automotive and construction hiring cycles can absorb graduates.
- ISO lifecycle assessment standardization delays:Evolving definitions of "bio-based" versus "bio-filled" are creating procurement specification ambiguity across OEM tier-1 supplier contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocomposite Materials Market |
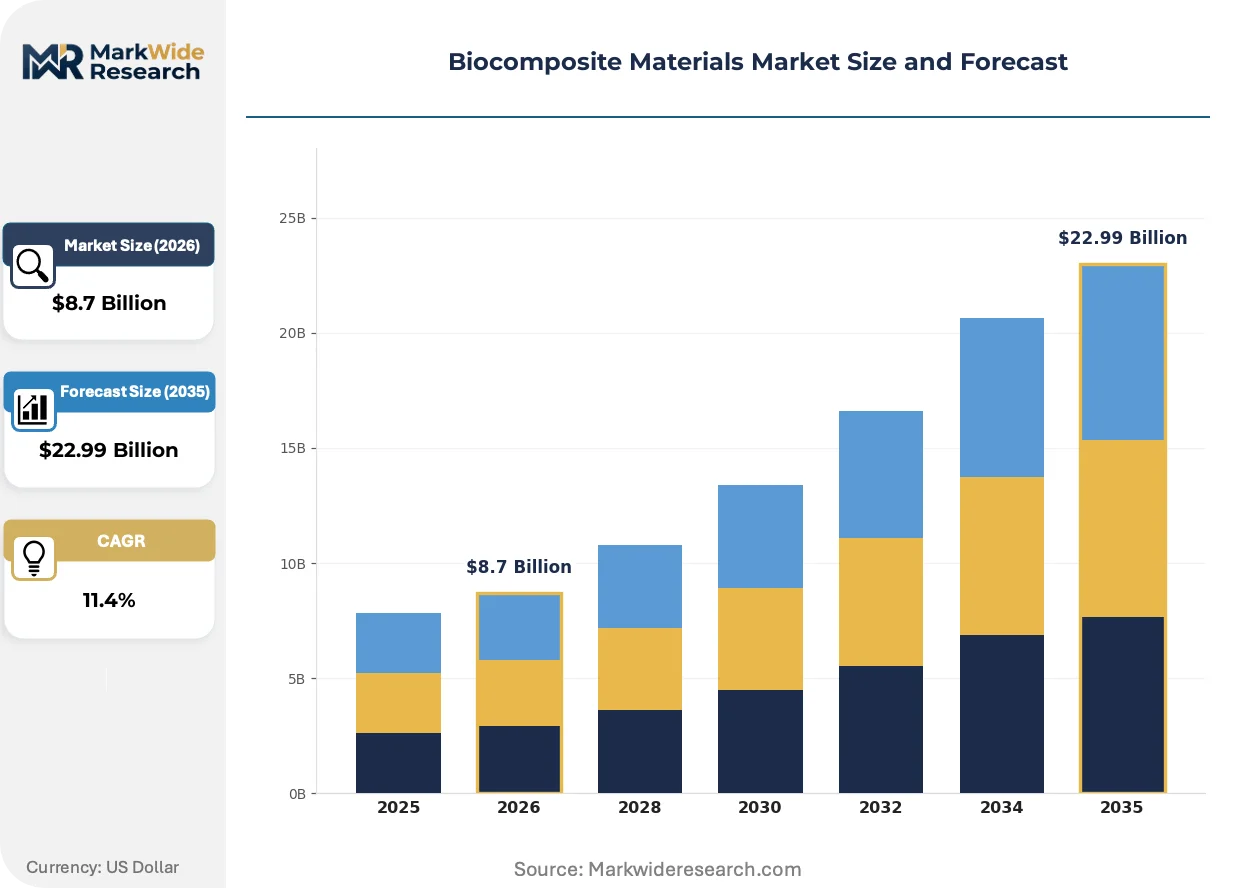
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber Composites, Wood-Plastic Composites, Bio-Based Resins, Biodegradable Plastics Application: Construction, Automotive Parts, Packaging Solutions, Consumer Products End User: Manufacturers, Retailers, Builders, Environmental Agencies Technology: Injection Molding, Extrusion, Compression Molding, 3D Printing |
| Companies Covered | Trex Company, UPM, Fiberon LLC, FlexForm Technologies, Universal Forest Products, Azek Building Products, Stora Enso, Bcomp Ltd, Tecnaro GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocomposite Materials Market Evolving Landscape
Material science advances and regulatory reclassification are compressing development cycles for bio-based alternatives, with processing innovations closing performance gaps against incumbent petroleum-derived composites.
Continuous flax fiber tape systems are supplanting glass fiber in non-structural automotive panels where flexural requirements sit below 80 MPa. BMW and Porsche design teams are specifying these materials for interior trim and seat shells. This substitution is compressing tooling investment requirements while expanding supplier qualification pools beyond traditional composite specialists.
REACH substance restrictions enforced by ECHA are limiting certain petrochemical additives in polymer matrices, indirectly advantaging bio-based formulations with cleaner hazard profiles. Compounders are reformulating to eliminate restricted phthalates and heavy metal catalysts. Construction decking manufacturers serving German and French markets are accelerating testing protocols to demonstrate compliance.
Automotive OEM procurement teams are unbundling material certification from volume commitments, requiring tier-1 suppliers to pre-qualify multiple biocomposite sources before contract award. This fragmentation is displacing sole-source relationships that previously locked in multi-year petroleum-based composite supply. The practice is most visible in German automotive supply chains where scope 3 reporting requirements demand supply chain transparency.
Biocomposite Materials Market Segmentation
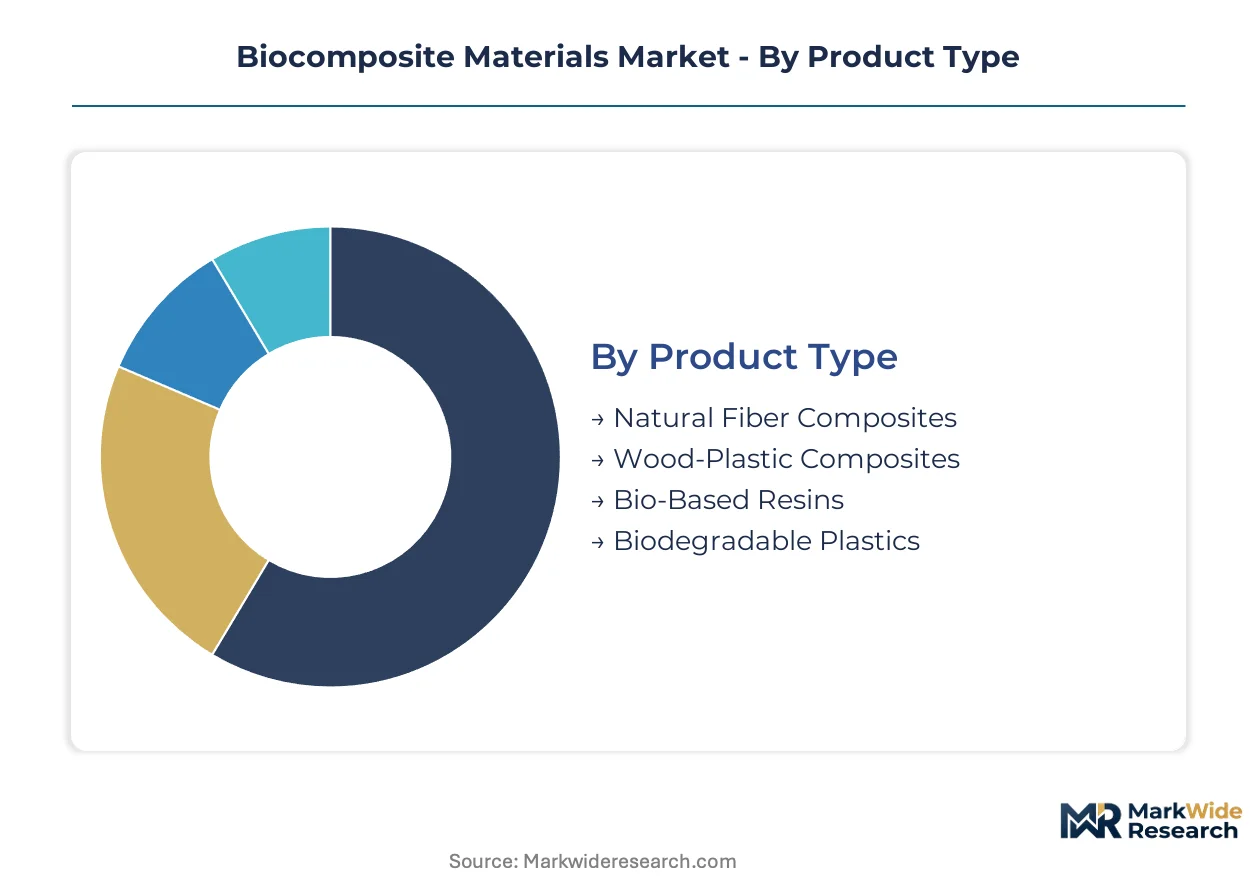
Biocomposite material specifications vary sharply by end-use load requirements and processing economics. Product type selection dictates fiber-matrix combinations, while application and technology choices determine whether formulations serve domestic construction markets or export-oriented automotive supply chains.
Product Type:
Natural fiber composites dominate European domestic consumption, whereas wood-plastic composites anchor North American export volumes to Asian decking distributors.
- Natural Fiber Composites:Flax and hemp fibers embedded in polypropylene or bio-based polyamide matrices deliver flexural strengths of 60-120 MPa. German and French automotive OEMs specify these for interior door panels and seat shells to meet EU Green Deal embodied carbon thresholds. Supply volatility from weather-dependent European harvests constrains compounder margins.
- Wood-Plastic Composites:Wood flour or sawdust blended with polyethylene or polypropylene creates durable exterior building materials. Trex Company and UPM serve North American construction through captive wood-waste supply chains, with excess capacity directed to Japanese and Australian export markets facing microplastic scrutiny from their national environmental regulators.
- Bio-Based Resins:Lignin and itaconic acid derivatives replace petroleum-based thermosets in FDA-compliant food-contact applications. Nordic tall oil refining clusters control upstream feedstock access.
- Biodegradable Plastics:Starch and PLA formulations serve single-use packaging where China's MEE dual carbon targets channel provincial subsidies toward composting infrastructure.
Wood-plastic composites hold the largest share; momentum sits with natural fiber composites as automotive scope 3 reporting tightens.
Application:
Cost tier stratification separates commodity construction materials from premium automotive and regulated packaging segments.
- Construction:Decking, fencing, and structural lumber applications consume the highest biocomposite volumes globally. Building code recognition gaps in US multi-family residential framing create first-mover opportunities for engineered biocomposite lumber producers.
- Automotive Parts:BMW and Porsche design teams specify ampliTex flax fiber architectures for interior trim and seat shells. Japanese OEMs in Toyota City and Nagoya manufacturing corridors are qualifying natural fiber composites for door panels to reduce scope 3 emissions.
- Packaging Solutions:Lignin-derived resins gain premium positioning in fresh food containers where EU EFSA and US FDA food-contact compliance creates regulatory moats against petroleum alternatives.
- Consumer Products:Durable goods and electronics housings in China's Zhejiang and Jiangsu biopolymer parks integrate bamboo fiber processing with regional manufacturing supply chains.
Construction absorbs the highest volume; packaging solutions are climbing the fastest as regulatory tailwinds strengthen.
End User:
Customer type determines procurement sophistication, with environmental agencies and tier-1 automotive suppliers driving certification requirements that commodity builders bypass.
- Manufacturers:Tier-1 automotive suppliers and construction product fabricators dominate volume procurement. German OEM procurement teams now unbundle material certification from volume commitments, requiring pre-qualified multiple biocomposite sources.
- Builders:Residential and commercial contractors specify biocomposite decking and structural materials where local building codes permit. US multi-family developers face fragmented municipal approval processes.
- Retailers:Home improvement chains and industrial distributors stock wood-plastic composite decking and fencing SKUs, with private-label expansion into natural fiber composite garden products.
- Environmental Agencies:Government purchasers and compliance auditors enforce lifecycle assessment standards. ISO definition debates over "bio-based" versus "bio-filled" create procurement specification ambiguity.
Manufacturers command the largest procurement volumes; environmental agencies are gaining share fastest as public sector green procurement mandates expand.
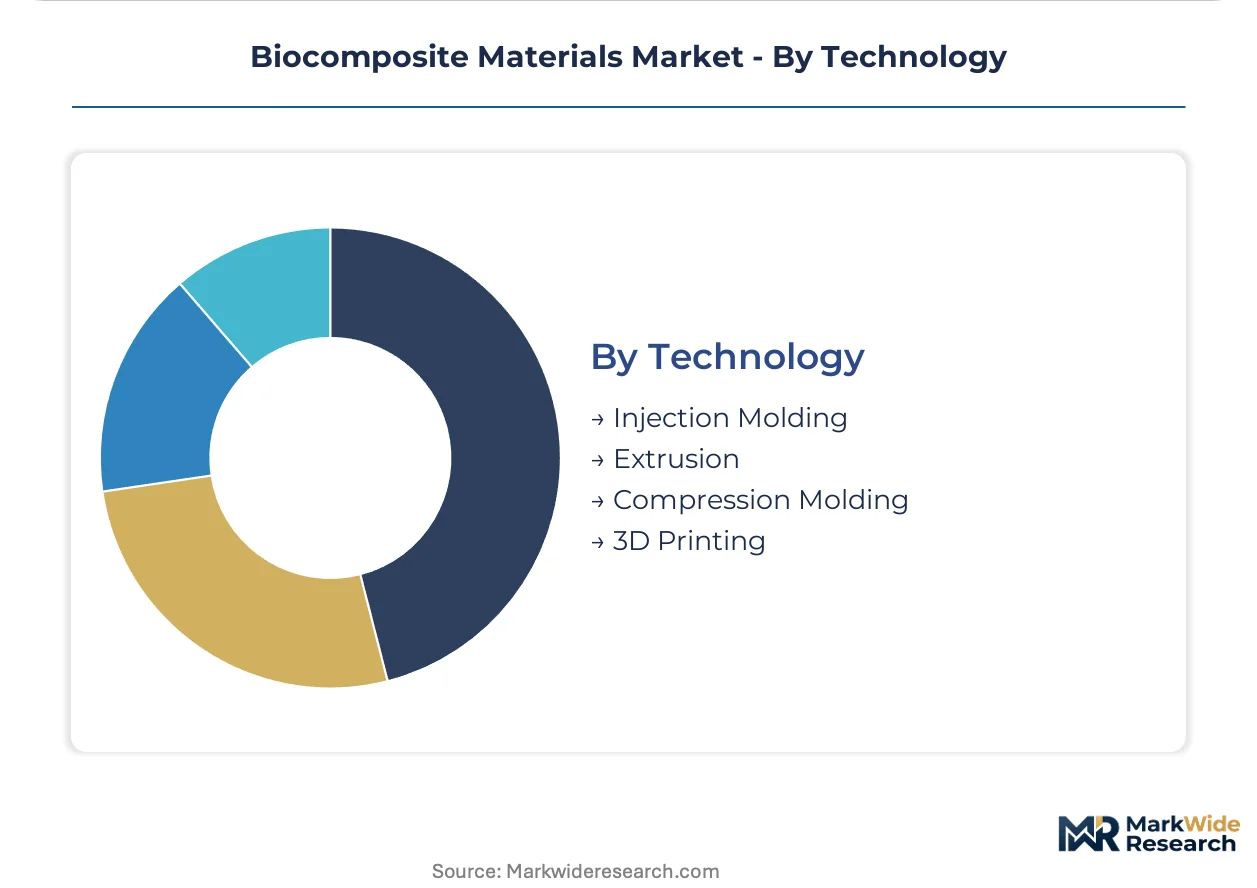
Technology:
Processing maturity separates high-volume extrusion operations from emerging 3D printing applications serving prototyping and custom architectural fabrication.
- Extrusion:Continuous profile production dominates wood-plastic composite decking and fencing manufacturing. Trex Company's decades of extrusion expertise create captive process knowledge barriers.
- Injection Molding:High-volume automotive interior component production relies on natural fiber-reinforced polypropylene compounds. Tooling investments compress as flax fiber tape systems expand supplier qualification pools.
- Compression Molding:Sheet molding compounds serve structural applications requiring higher fiber loadings and complex geometries. Motorsport applications combine ampliTex flax with recycled carbon fiber.
- 3D Printing:Fused deposition modeling with bio-based filaments serves architectural prototyping and custom medical device scaffolding. Processing parameter optimization lags behind petroleum-based feedstocks.
Extrusion holds the largest installed base; 3D printing is expanding most quickly as filament formulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: European automotive OEMs prioritize natural fiber composites for embodied carbon compliance, while North American builders specify wood-plastic composites for exterior construction durability. Asian manufacturing corridors integrate bamboo and hemp processing directly into electronics and automotive supply chains.
Germany
BMW and Porsche design teams specify ampliTex flax fiber architectures for interior trim and seat shells to meet EU Green Deal thresholds. The country's national environmental regulator enforces REACH substance restrictions that limit petrochemical additives in polymer matrices. Stuttgart and Munich automotive clusters are qualifying multiple biocomposite sources before contract award to ensure scope 3 reporting transparency.
United States
Construction decking and fencing applications consume the highest biocomposite volumes, with building code recognition gaps in multi-family residential framing creating first-mover opportunities. The EPA scrutinizes microplastic release from conventional composites during abrasion and weathering, reshaping product testing protocols for outdoor applications. Trex Company leverages its captive wood-waste supply chain and extrusion expertise to dominate North American decking from Virginia manufacturing bases.
China
State-backed biopolymer parks in Zhejiang and Jiangsu provinces integrate flax, hemp, and bamboo fiber processing with automotive and electronics supply chains. The Ministry of Ecology and Environment dual carbon targets channel provincial subsidies toward hemp and bamboo fiber processing clusters. Shanghai and Suzhou manufacturing corridors serve export-oriented OEMs seeking scope 3 emission reductions.
Japan
Toyota City and Nagoya manufacturing corridors are qualifying natural fiber composites for door panels to reduce automotive scope 3 emissions. METI industrial policy supports lightweighting material substitution in domestic vehicle production. Osaka-based compounders reformulate polypropylene matrices to eliminate restricted phthalates for automotive interior specifications.
France
Weather-dependent flax and hemp harvests in northern growing regions create input cost instability for European compounders serving automotive tier-1 suppliers. ECHA REACH enforcement limits certain petrochemical additives, indirectly advantaging bio-based formulations with cleaner hazard profiles. The Hauts-de-France agricultural belt supplies raw fiber to Lille and Paris industrial compounders reformulating for German OEM procurement teams.
Biocomposite Materials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting raw material access and processing expertise rather than scale alone. Captive fiber supply and decades of extrusion know-how create defensive positions in construction applications. Three archetypes dominate: wood-waste-integrated extruders, pulp-and-tall-oil backward integrators, and flax-fiber architecture specialists. Competitive moves center on pre-qualifying multiple biocomposite sources for automotive procurement teams and expanding Nordic tall oil refining capacity for lignin-based matrix production.
Among Nordic pulp-and-tall-oil integrators, UPM anchors upstream resin feedstock control through its position in tall oil refining clusters. Trex Company exemplifies the wood-waste-integrated extruder archetype with decades of captive supply chain expertise in North American decking. Bcomp Ltd occupies the flax-fiber architecture specialist tier, with its ampliTex systems competing in motorsport and premium automotive interior applications.
| Leading Market Players |
|---|
| Trex Company |
| UPM |
| Fiberon LLC |
| FlexForm Technologies |
| Universal Forest Products |
| Azek Building Products |
| Stora Enso |
| Bcomp Ltd |
| Tecnaro GmbH |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German automotive OEMs and Nordic tall oil refiners lock in lignin-based resin supply while capping price volatility for bio-based polyamide matrices. These contracts bundle volume commitments with certification pre-qualification, stripping spot-market exposure from tier-1 compounders serving EU Green Deal compliance timelines.
Pricing Analysis
Contract-based long-term offtake dominates biocomposite procurement, with pricing stratifying across automotive certification grade, volume scale, and geographic delivery cost. Premium tiers command spreads for REACH-compliant formulations with full lifecycle documentation, while standard construction grades compete on wood-waste feedstock proximity. Cost compression in packaging resins is intensifying because Nordic tall oil capacity expansion lags demand from food-contact applications. Builders remain most price-sensitive, deferring to untreated lumber where code recognition gaps persist.
Supply Chain Analysis
Baltic Sea tall oil refining clusters tether European bio-resin production to Nordic pulp mill geography, creating single-source vulnerability for lignin-based matrix producers. Raw material flows draw from French flax harvests, Chinese bamboo fiber processing in Zhejiang, and North American wood-waste streams. Distribution runs through automotive tier-1 supplier hubs in Stuttgart and Toyota City, with construction materials moving via home improvement retail channels. Tariff exposure on hemp fiber imports into Japan compounds regional supply risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European compounders face a polymer chemist bottleneck that outpaces graduate pipeline expansion, compressing development timelines for REACH-compliant formulations and rewarding early certification investments.
For Market Incumbents: Fortify captive fiber supply through backward integration into French flax processing or Nordic tall oil refining, insulating margin structures from harvest volatility. Expand pre-qualified supplier pools ahead of German OEM procurement unbundling requirements. Prioritize ISO lifecycle assessment documentation to defend positioning against emerging bio-filled competitors lacking full bio-based certification. For New Entrants and Emerging Players: Anchor in US multi-family residential framing, where building code recognition gaps create first-mover whitespace absent entrenched competition. Target lignin-derived food-contact packaging, where FDA and EU EFSA compliance pathways erect regulatory moats against petroleum incumbents. Lead with architectural prototyping services using bio-based 3D printing filaments to bypass capital-intensive extrusion scale requirements. For Investors and Strategic Acquirers: Capital is best deployed toward flax-fiber architecture specialists with ampliTex-class material platforms and motorsport qualification credentials, positioned for automotive interior expansion. Monitor German scope 3 reporting enforcement as inflection signal—accelerated tier-1 supplier audits would compress qualification timelines and favor pre-certified acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Tall Oil Refining | Secures lignin-based resin feedstock access for EU Green Deal compliance formulations. |
| REACH-Compliant Formulation Certification | Unlocks German automotive OEM procurement pools under unbundled supplier qualification rules. |
| Flax Fiber Processing Cluster Expansion | Reduces harvest volatility exposure for European natural fiber compounders serving BMW and Porsche. |
| Multi-Family Residential Building Code Engagement | Captures first-mover advantage in underpenetrated US structural lumber applications. |
| Food-Contact Regulatory Pathway Investment | Establishes FDA and EU EFSA compliance moats in fresh food container packaging segments. |
Research Methodology
The analysis maps natural fiber composites, wood-plastic composites, bio-based resins, and biodegradable plastics, each validated through polymer chemists, automotive tier-1 procurement leads, construction product fabricators, and tall oil refinery technical directors. Primary fieldwork combined with secondary validation from ECHA REACH substance databases, EU customs trade flows, SEC 10-K filings of listed compounders, and ISO lifecycle assessment standards enabled bottom-up and top-down triangulation.
Consistency checks against Nordic pulp production statistics and German automotive interior content benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated fiber-matrix combination, end-use load requirement, processing technology, and regional regulatory cluster dimensions. CAGRs derived from production capacity expansion announcements and OEM procurement pipeline visibility, with weather-adjusted fiber yield assumptions and bio-resin feedstock conversion rates as industry-specific inputs.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable Nordic tall oil refining capacity; material deviation in French flax harvest yields or REACH substance list expansion would warrant model refresh. Practitioners should keep alternative scenarios live as China's MEE dual carbon subsidy intensity and US EPA microplastic testing protocol evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Global Bioplastic Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Automotive Bioplastic Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Biopolymers Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Compostable Phone Cases Market