
 China Bioplastics Market | 2026-2036
China Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
China Bioplastics Market Insights
China's dual carbon goals is hardening the regulatory floor for fossil-based polymers across domestic manufacturing. Kingfa Sci. & Tech. Co., Ltd. leverages its Guangzhou R&D base to dominate modified biopolymer compounds for automotive tier suppliers. Sinopec anchors national supply security through pilot PHA facilities integrated with its refinery complexes. Novamont SpA competes via licensed compostable resin technology adapted to Chinese industrial composting infrastructure.
Bioplastics comprise polymers derived from renewable biomass sources including corn starch, sugarcane, and cellulose, engineered to match mechanical properties of conventional plastics while enabling biodegradation under industrial composting conditions with specified temperature and humidity parameters. These materials serve primary industrial purposes in reducing petrochemical dependency and meeting landfill diversion mandates across consumer-facing supply chains. PLA currently occupies the largest production volume share due to mature fermentation infrastructure and lactic acid feedstock availability, while PHA represents the fastest-expanding category driven by marine biodegradability certifications that command premium positioning in export packaging. Starch blends sustain cost-competitive positioning in agricultural mulch films where performance specifications tolerate higher moisture absorption rates.
MIIT's biopolymer industry development guidelines, SAMR's compostable plastics labeling standards, and GB standards for biodegradable shopping bags collectively shape product certification requirements and market access protocols for domestic and imported materials. NMPA oversight of food-contact substances adds compliance layers for packaging applications serving processed food manufacturers. Stakeholders must monitor evolving provincial implementation timelines for single-use plastic bans to align capacity investments with enforcement intensity across municipal markets.
Market Dynamics
China's dual carbon goals are compressing the regulatory timeline for fossil-based packaging, forcing polymer processors in Jiangsu and Zhejiang to reconfigure feedstock sourcing before enforcement intensifies. This structural pressure is redirecting capital toward fermentation-based alternatives.
Growth Catalysts
- MIIT's biopolymer industry development guidelines:These standards accelerate domestic PHA and PLA capacity expansion by mandating biodegradable content thresholds in municipal procurement. Food packaging manufacturers must now certify compostability under GB standards to access state-affiliated buyers.
- Agricultural mulch film demand:Starch-blend formulations are displacing conventional polyethylene in Shandong and Henan farming regions. Provincial soil remediation programs subsidize biodegradable alternatives to reduce microplastic accumulation in arable land.
- Automotive interior applications:Modified biopolymer compounds from Guangzhou R&D clusters are penetrating tier supplier networks. Interior trim specifications now prioritize renewable content to satisfy OEM carbon disclosure requirements.
Market Restraints
- Corn starch feedstock volatility:PLA production costs fluctuate with grain reserve policies and import dependency. Ningxia and Inner Mongolia processing facilities face margin compression when domestic corn prices spike.
- Industrial composting infrastructure gaps:Certified biodegradation requires sustained temperatures above fifty degrees Celsius that most municipal waste facilities cannot maintain. Guangdong and Fujian composting capacity lulls behind material availability.
- Conventional polypropylene substitution:Fossil-based polymers retain cost advantages in non-food contact applications. Price-sensitive agricultural film buyers revert to polyethylene when bioplastic premiums exceed subsidy offsets.
Strategic Opportunities
- Marine biodegradable PHA grades:Export packaging for seafood and aquaculture products commands premium positioning with ocean-degradability certifications. Fujian and Zhejiang coastal processors are piloting PHA-lined containers for frozen shrimp exports.
- Carbon credit monetization:Bioplastic production generates verified emission reductions tradable under provincial pilot schemes. Guangdong and Hubei carbon exchanges accept polymer fermentation projects for offset registration.
- Direct-to-brand supply contracts:Bypassing conventional distributor networks, compounders in Jiangsu are signing volume commitments with multinational food brands. These arrangements lock in offtake before capacity floods the spot market.
Industry Challenges
- Industrial composting certification timelines:SAMR's compostable plastics labeling standards require eighteen-month testing protocols that delay product launches. Manufacturers must sequence R&D investments before final rules crystallize.
- Fermentation scale-up engineering:PHA commercialization demands precise bioreactor control that strains existing chemical engineering talent pools. Universities in Tianjin and Qingdao are expanding bioprocess programs to close this gap.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Bioplastics Market |
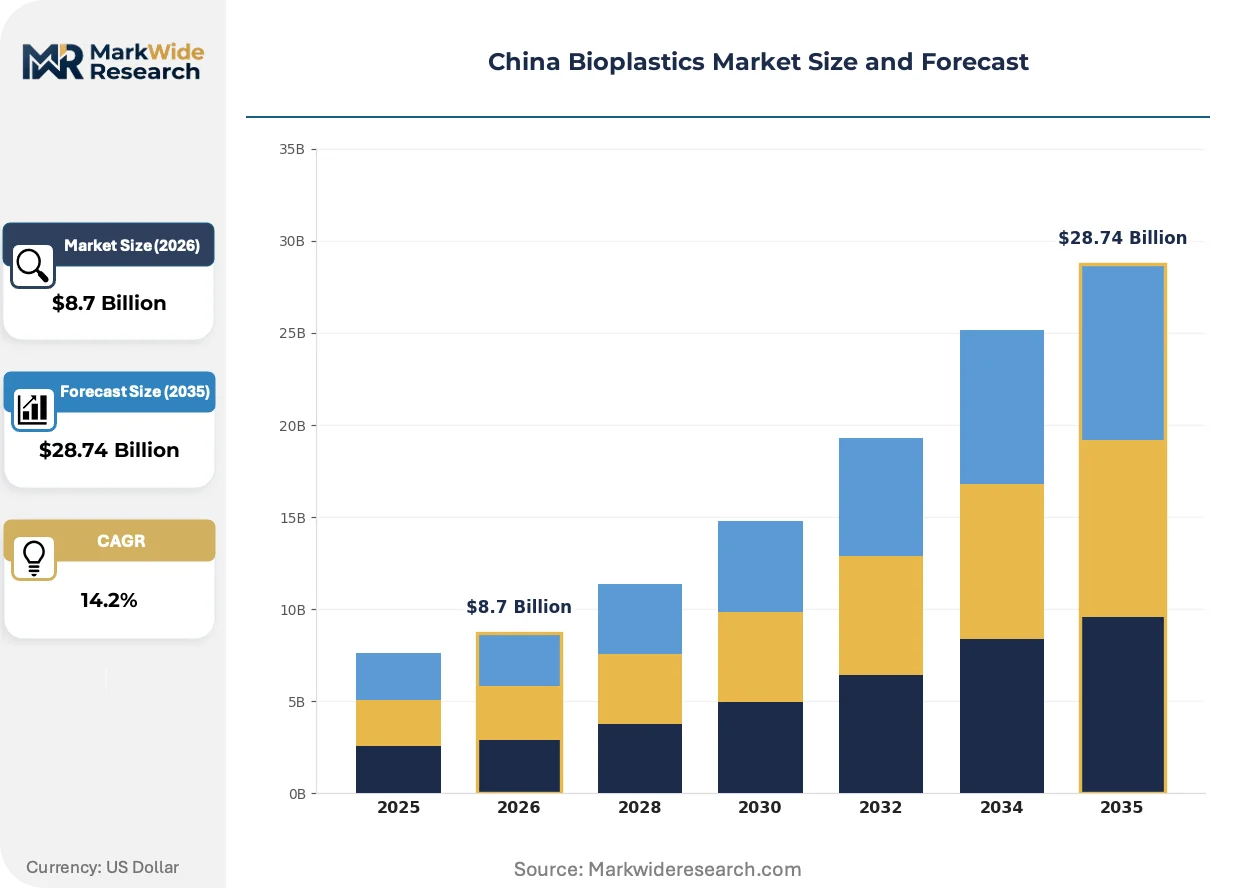
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, Others Application: Packaging, Agriculture, Automotive, Consumer Goods End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Retail Stores, Direct Sales, Wholesalers |
| Companies Covered | Kingfa Sci. & Tech. Co., Ltd., Sinopec, BASF SE, Braskem, Novamont SpA, FUTERRO S.A., China BBCA Group, Eastman Chemical Company, LyondellBasell B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Bioplastics Market Trends and Innovations
Process intensification and regulatory precision are converging to reshape how biopolymers move from fermentation tanks to finished packaging. Technology developers and compounders are racing to match mechanical performance with biodegradation timelines.
PHA production technology is modularizing around consolidated bioprocessing platforms that combine enzyme hydrolysis with microbial fermentation in single-vessel configurations. Specialty chemical engineers in Jiangsu province are adopting these integrated systems to reduce capital intensity for mid-scale facilities. This convergence is modularizing entry barriers, enabling regional compounders to challenge Sinopec's refinery-integrated pilots without billion-yuan investments.
SAMR's compostable plastics labeling standards are tightening disclosure requirements for biodegradation conditions and timeline claims. Manufacturers must now specify industrial versus home composting pathways on product markings, forcing reformulation of materials previously marketed as universally biodegradable. Food-contact applications face the steepest compliance burden, as NMPA overlay requirements add migration testing protocols to existing compostability certifications.
Brand-led specification of certified compostable packaging is consolidating procurement authority among sustainability officers at multinational food manufacturers. These buyers are displacing traditional purchasing managers in polymer selection decisions, introducing lifecycle assessment scorecards that penalize ambiguous biodegradation claims. Shanghai and Shenzhen headquarters of global consumer brands are piloting blockchain-tracked composting verification for premium product lines.
China Bioplastics Market Segmentation
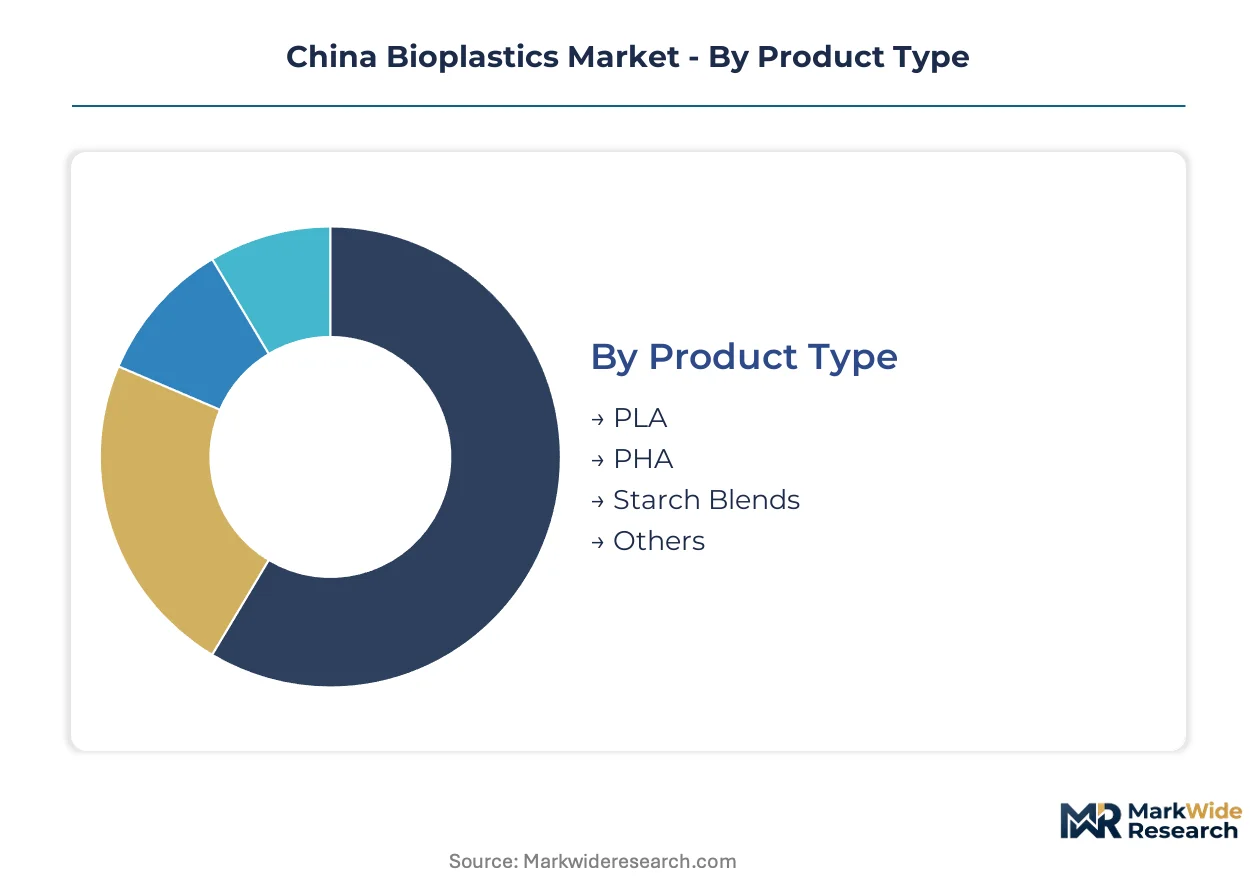
Bioplastics procurement in China fragments across material chemistries, application specifications, and channel economics. Each segmentation axis reveals distinct margin profiles and compliance burdens that shape supplier strategy.
Product Type:
Production gravity concentrates in fermentation corridors where feedstock security and bioreactor engineering talent overlap.
- PLA:Polylactic acid derives from corn starch fermentation with mechanical properties matching conventional polypropylene. Jiangsu compounders dominate food-contact applications where GB standards mandate compostability certification.
- PHA:Polyhydroxyalkanoates achieve marine biodegradability certifications that command premium positioning in export packaging. Zhejiang and Fujian coastal processors pilot PHA-lined containers for frozen seafood shipments.
- Starch Blends:Cost-competitive formulations serve agricultural mulch films where Shandong and Henan provincial subsidies offset performance trade-offs.
- Others:Cellulose-based and protein-derived polymers occupy niche medical and cosmetic applications with limited domestic capacity.
PLA absorbs the bulk of installed capacity; PHA is expanding most quickly.
Application:
End-use specifications diverge sharply between compliance-driven food packaging and performance-critical automotive interiors.
- Packaging:Food-contact films and rigid containers face NMPA migration testing layered atop SAMR compostability requirements. Multinational brand procurement officers now mandate blockchain-tracked biodegradation verification.
- Agriculture:Soil remediation programs in Shandong and Henan displace polyethylene mulch with starch-blend alternatives. Provincial subsidy intensity determines buyer price sensitivity.
- Automotive:Modified biopolymer compounds from Guangzhou R&D clusters penetrate tier supplier networks. OEM carbon disclosure requirements prioritize renewable content in interior trim specifications.
- Consumer Goods:Disposable cutlery and cosmetic containers compete on cost with conventional plastics. Premium positioning depends on home-composting claims that exceed industrial certification standards.
Packaging commands the deepest compliance investment; agriculture shows the steepest volume ramp from subsidy expansion.
End User:
Procurement authority is shifting from traditional purchasing managers to sustainability officers with lifecycle assessment mandates.
- Manufacturers:Food processors and automotive tier suppliers drive specification-grade demand with multi-year volume commitments.
- Retailers:Supermarket chains and e-commerce platforms face municipal single-use plastic bans that accelerate bioplastic bag adoption.
- Distributors:Polymer traders in Yiwu and Guangzhou intermediate spot-market volumes with limited technical service capability.
- Consumers:Direct purchasing remains minimal except for premium cosmetic and baby product segments.
Manufacturers lock in offtake through direct contracts; retailers are gaining procurement influence through private-label specifications.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and certification documentation intensity.
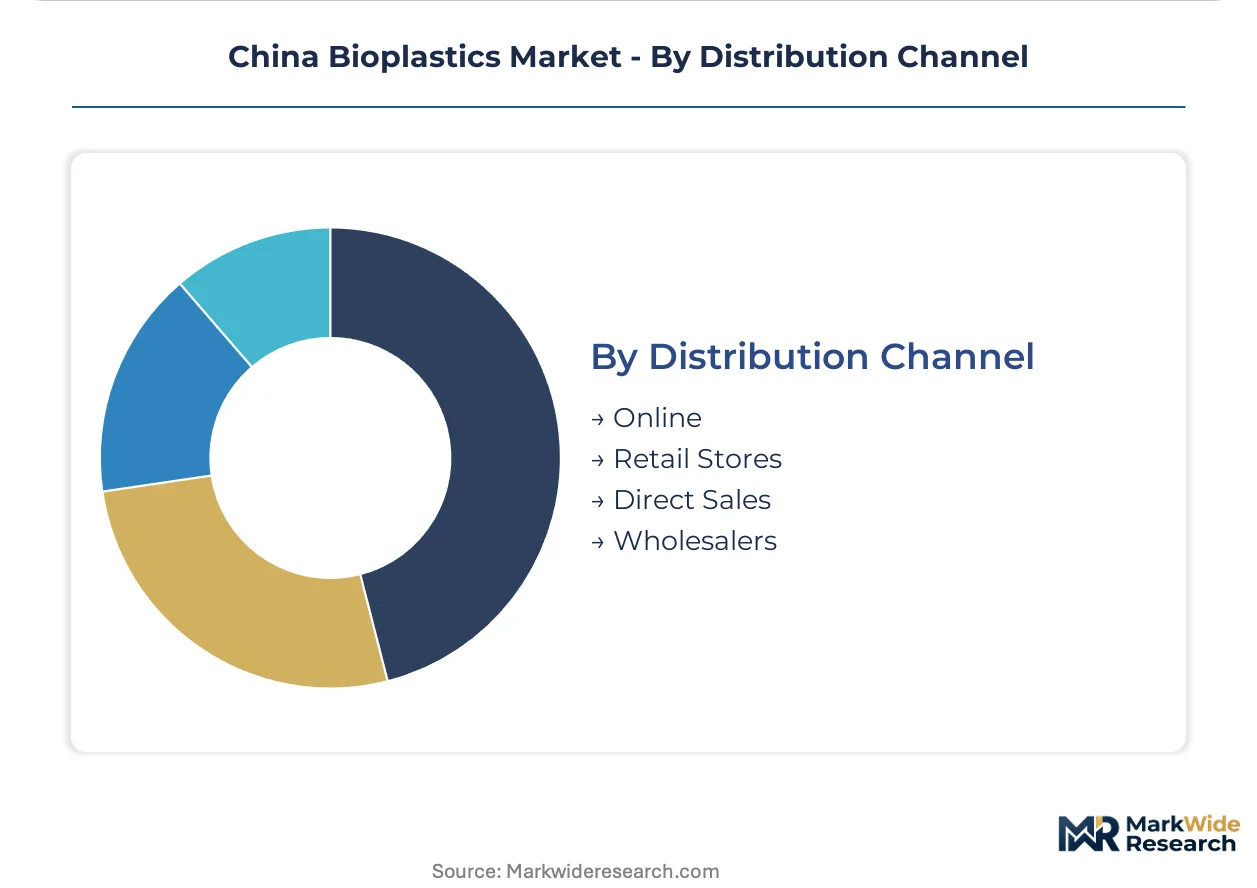
- Online:Alibaba and specialized polymer platforms serve small-batch buyers with limited technical consultation. Documentation gaps complicate compliance verification.
- Retail Stores:Physical distribution concentrates in Yiwu and Guangzhou chemical markets with cash-and-carry convenience for regional processors.
- Direct Sales:Compounders in Jiangsu bypass distributor networks to sign volume commitments with multinational food brands.
- Wholesalers:Regional traders aggregate demand from agricultural film buyers in Shandong and Henan with subsidy application support.
Direct sales capture the highest-margin contracts; wholesalers dominate agricultural volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor China's bioplastics production, with polymer processing clusters in Yangtze River Delta cities reconfiguring feedstock sourcing ahead of enforcement intensification.
Jiangsu Province
Food packaging manufacturers in Suzhou and Nanjing drive PLA compound demand as GB standards mandate compostability certification for state-affiliated buyers. MIIT's biopolymer industry development guidelines accelerate domestic capacity expansion through mandated biodegradable content thresholds. The province's fermentation infrastructure leverages mature lactic acid feedstock availability to dominate food-contact applications.
Zhejiang Province
PHA commercialization gathers momentum in Ningbo and Hangzhou where coastal processors pilot marine-biodegradable containers for frozen seafood exports. SAMR's compostable plastics labeling standards require eighteen-month testing protocols that delay product launches from regional compounders. The province's bioreactor engineering talent pools strain under precise fermentation scale-up demands.
Guangdong Province
Automotive tier suppliers in Guangzhou source modified biopolymer compounds for interior trim specifications prioritizing renewable content. NMPA oversight of food-contact substances adds migration testing layers for packaging applications serving processed food manufacturers. The province's R&D clusters penetrate OEM carbon disclosure requirements through direct-to-brand supply contracts.
Shandong Province
Soil remediation programs in Jinan and Qingdao displace polyethylene mulch with starch-blend alternatives subsidized to reduce microplastic accumulation. Provincial subsidy intensity determines agricultural film buyer price sensitivity when bioplastic premiums exceed offset levels. The region's farming corridors sustain cost-competitive positioning for moisture-tolerant formulations.
Fujian Province
Coastal processors in Xiamen and Fuzhou command premium positioning for ocean-degradability certifications in export packaging for aquaculture products. Industrial composting infrastructure gaps persist as certified biodegradation requires sustained temperatures above fifty degrees Celsius that most municipal waste facilities cannot maintain. The province's composting capacity lulls behind material availability from upstream fermentation facilities.
China Bioplastics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and feedstock integration depth. The vendor base stratifies between refinery-integrated state enterprises, fermentation-specialized compounders, and licensed technology providers. Three archetypes dominate: upstream petrochemical incumbents with pilot biopolymer facilities, regional compounders with modified biopolymer R&D capabilities, and European technology licensors with adapted compostable resin platforms. Capacity expansion and strategic technology licensing constitute the dominant competitive moves.
Within the domestic compounder tier, Kingfa Sci. & Tech. Co., Ltd. and China BBCA Group exemplify regional players with fermentation corridor positioning. Sinopec anchors the state-enterprise archetype through refinery-integrated pilot facilities. Among European technology providers, Novamont SpA and FUTERRO S.A. occupy licensing positions adapted to Chinese industrial composting infrastructure. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Kingfa Sci. & Tech. Co., Ltd. |
| Sinopec |
| BASF SE |
| Braskem |
| Novamont SpA |
| FUTERRO S.A. |
| China BBCA Group |
| Eastman Chemical Company |
| LyondellBasell B.V. |
| Others |
Pricing and Supply Chain Analysis
Multinational food brand procurement officers mandating blockchain-tracked biodegradation verification are compressing acceptable price premiums for compostable packaging. This specification-grade demand forces compounders in Jiangsu and Zhejiang to absorb certification costs or cede volume to refinery-integrated state enterprises with captive fermentation capacity.
Pricing Analysis
Certification-grade biodegradation outcomes anchor value-based pricing for food-contact applications under NMPA and SAMR oversight. Three-tier pricing structure across premium marine-PHA, standard PLA, and economy starch-blend tiers reflects compliance burden differentiation. Cost compression in economy-grade agricultural films intensifies because provincial subsidy delays erode buyer willingness to pay. Agricultural mulch film buyers in Shandong and Henan exhibit highest price sensitivity; automotive tier suppliers sourcing Guangzhou R&D compounds show lowest.
Supply Chain Analysis
GB standards and SAMR compostable plastics labeling standards gate market access before volume procurement can proceed. Feedstock security draws from corn starch processing corridors in Ningxia and Inner Mongolia, lactic acid fermentation clusters in Jiangsu, and coastal PHA pilot facilities in Zhejiang and Fujian. Single-source vulnerability concentrates in domestic corn supply exposed to grain reserve policy shifts. Distribution runs through direct sales contracts with multinational brands for premium tiers, regional wholesalers for agricultural volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's bioplastics sector sits in a technology-transition phase where fermentation-based PHA and PLA platforms displace fossil-derived polypropylene in packaging specifications. This displacement creates asymmetric opportunity across incumbent defense, entrant capture, and investor timing strategies.
For Market Incumbents: Deploy certification stacking as the primary lever. Layer NMPA food-contact approval atop SAMR compostability marks before enforcement timelines crystallize. Anchor state-affiliated procurement relationships through MIIT-mandated biodegradable content thresholds. Defend against Sinopec's refinery-integrated pilots by locking multiyear direct contracts with automotive OEMs seeking carbon disclosure compliance.
For New Entrants and Emerging Players: Capture marine-biodegradable PHA white space in Fujian and Zhejiang coastal export corridors before infrastructure gaps close. Target agricultural mulch film segments in Shandong and Henan where provincial soil remediation subsidies sustain volume offtake despite performance trade-offs. Enter through wholesaler partnerships offering subsidy application support rather than technical service premiums.
For Investors and Strategic Acquirers: The window for entry favors fermentation-specialized compounders with modular bioprocessing platforms over billion-yuan refinery-integrated pilots. Long-term viability rests on feedstock flexibility beyond corn starch dependency. Watch provincial carbon exchange registration protocols as the inflection signal for monetizable emission reduction claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Feedstock | Ningxia and Inner Mongolia corn processing corridors secure margin control against grain reserve volatility. |
| Marine Biodegradability Certification Investment | Ocean-degradability marks from Fujian and Zhejiang coastal facilities unlock premium export packaging positioning. |
| Direct-to-Brand Supply Contracting | Jiangsu compounders bypass distributor networks to lock multinational food manufacturer volume commitments. |
| Carbon Credit Exchange Registration | Guangdong and Hubei pilot schemes monetize verified emission reductions from fermentation-based production. |
| Modular Bioprocessing Platform Deployment | Single-vessel enzyme hydrolysis-fermentation systems reduce capital barriers for mid-scale PHA commercialization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biopolymer plant managers, procurement leads at automotive tier suppliers, distribution channel partners in Yiwu and Guangzhou, and technical R&D directors at Guangzhou fermentation clusters combined with MIIT industry development guidelines, SAMR labeling standards documentation, NMPA food-contact substance filings, and provincial soil remediation program records. Bottom-up capacity installation tracking and top-down end-use demand estimation triangulated volume figures.
Granularity-level modeling disaggregated the analysis window by material chemistry, application specification, and end-user procurement authority. Segmentation dimensions included PLA/PHA/starch-blend product tiers, food packaging versus automotive versus agricultural end-uses, and manufacturer versus retailer versus distributor channel economics. CAGRs derived from feedstock cost trajectory assumptions, enforcement timeline scenarios for single-use plastic bans, and substitution elasticity estimates for polyethylene displacement in mulch films.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to industrial composting infrastructure buildout rates and provincial subsidy sustainability. Forecasts reflect assumptions about MIIT guideline implementation intensity, GB standards enforcement uniformity, and corn starch price volatility under grain reserve policies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Global Bioplastic Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Biodegradable Microbeads Market