
 Stainless Steel Cask Market | 2026-2036
Stainless Steel Cask Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Cask Market Insights
China is narrowing its stainless steel processing cost advantage as European producers automate finishing lines. Blefa GmbH anchors German precision manufacturing for heritage brewers. THIELMANN dominates reusable industrial container standards across chemical and beverage segments. Schafer Container Systems extends its European distribution network into craft brewing cooperatives.
Stainless steel casks are cylindrical vessels fabricated from austenitic or duplex grades, typically featuring welded seams, sanitary interior finishes, and pressure-rated closures designed for liquid containment, carbonation retention, and repeated cleaning cycles. Single-walled casks retain mature volume share in traditional British-style ale service, while insulated casks capture expanding demand from outdoor event catering and mobile dispensing. The 316 stainless steel grade segment commands premium positioning due to superior chloride corrosion resistance in coastal brewery operations and aggressive cleaning regimens.
FDA food-contact substance notifications and EU Regulation 1935/2004 govern material migration limits for beverage applications, compelling suppliers to maintain batch-level composition certificates. Germany's BfR recommendations and REACH substance restrictions further constrain coating and gasket chemistries in European-sold units. Stakeholders must monitor evolving deposit-return legislation across Scandinavian markets, where circular economy mandates are redefining cask lifecycle accountability and refurbishment economics.
Market Dynamics
Brewery procurement departments are consolidating vendor lists around suppliers capable of delivering batch-certified 316-grade casks with full REACH documentation, compressing the addressable supply base for smaller fabricators.
Growth Catalysts
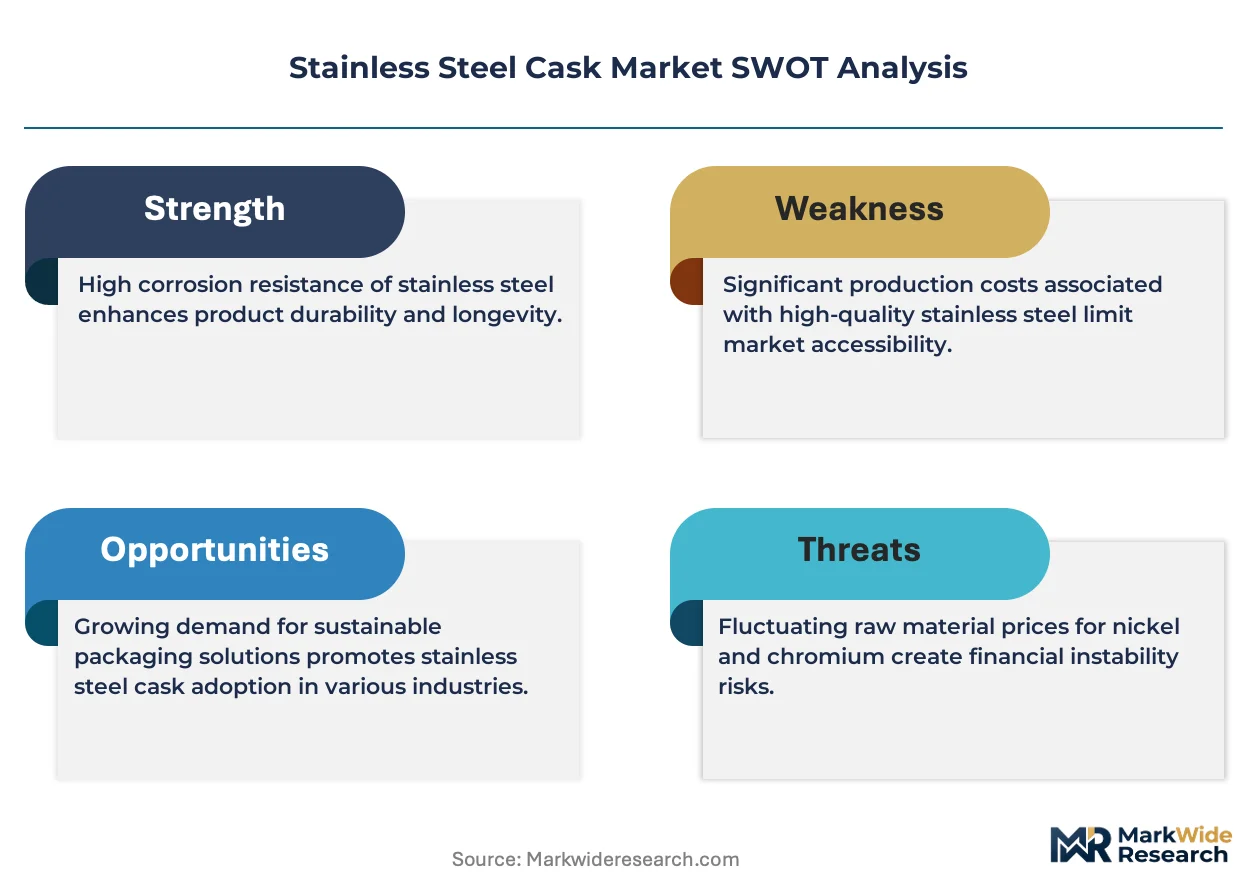
- EU Green Deal circular economy mandates:Scandinavian deposit-return legislation is extending cask lifecycle accountability, creating refurbishment revenue streams for certified service providers.
- Heritage ale conditioning revival:Traditional British-style brewing methods are driving single-walled cask demand among craft breweries in Germany and the UK.
- 316-grade chloride resistance:Coastal brewery operations are specifying this austenitic grade for aggressive cleaning regimens and salt-air exposure.
Market Restraints
- Nickel price volatility:Austenitic grades contain 10-14% nickel, exposing fabricators to London Metal Exchange price swings that compress margin predictability.
- German precision manufacturing concentration:Heritage brewer supply chains cluster around southern German fabricators, creating geographic single-source vulnerability.
- Alternative packaging substitution:KeyKeg and PET keg formats are capturing outdoor event and mobile dispensing volumes from insulated stainless units.
Strategic Opportunities
- US craft brewing cooperatives:Underpenetrated regional brewing associations in the Pacific Northwest represent white-space demand for sanitary-finished casks with FDA food-contact certification.
- Digital traceability integration:Converging RFID tagging with batch-level composition certificates enables lifecycle tracking required by EU Regulation 1935/2004.
- Event catering channel expansion:Insulated cask demand from outdoor festival operators is creating direct-to-venue distribution bypassing traditional beverage wholesalers.
Industry Challenges
- Welding certification timelines:ASME Section IX and EN ISO 9606 welder qualification requirements extend production ramp-up for new fabrication facilities.
- Legacy cask refurbishment integration:Established breweries maintain mixed fleets of decades-old casks with non-standard fittings, complicating sanitation protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Cask Market |
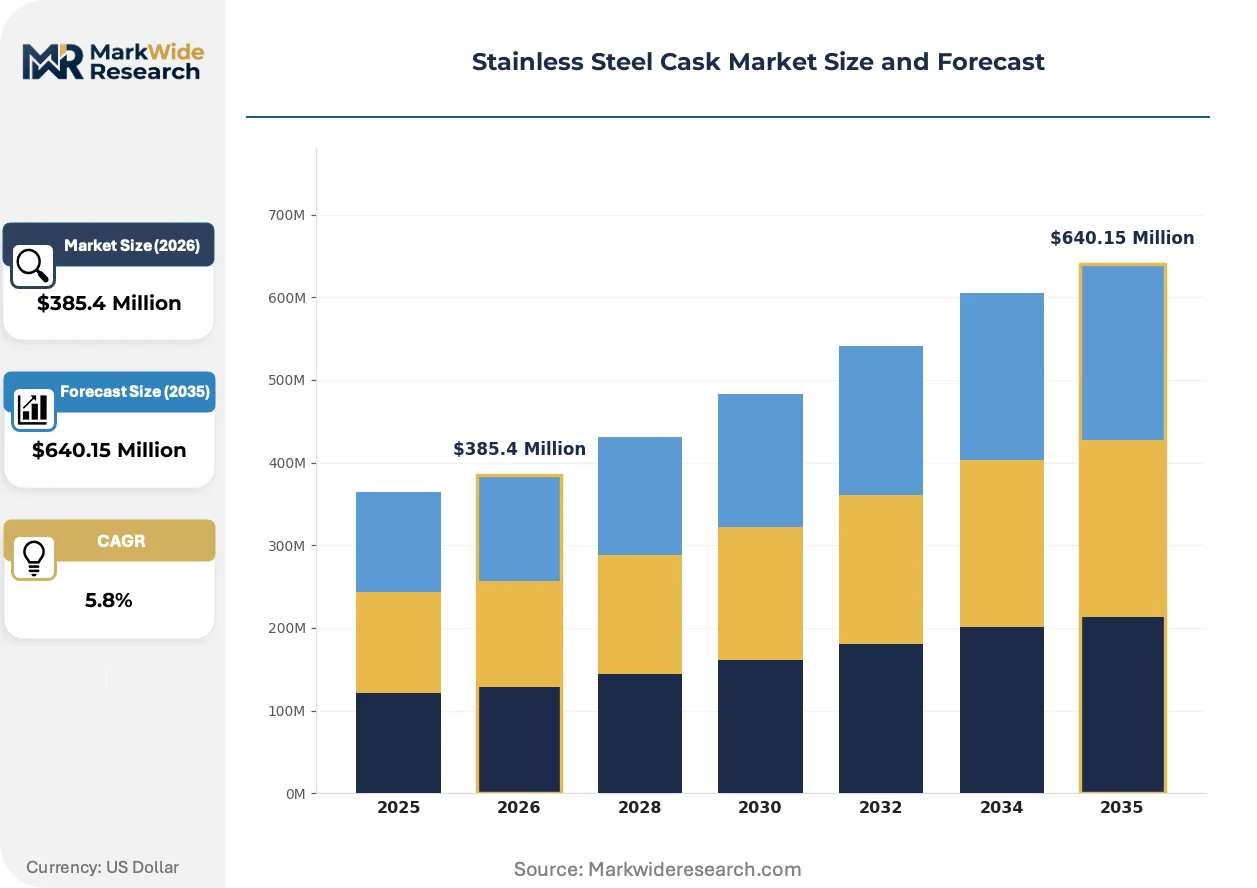
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Walled Cask, Double-Walled Cask, Insulated Cask, Reinforced Cask, Portable Cask Material Grade: 304 Stainless Steel, 316 Stainless Steel, Duplex Stainless Steel, Ferritic Stainless Steel, Martensitic Stainless Steel Application: Pharmaceutical Storage, Chemical Transportation, Food & Beverage, Aerospace Component Handling, Laboratory Sample Management End User: Biotechnology Firms, Petrochemical Plants, Food Processing Units, Aviation Suppliers, Research Institutions |
| Companies Covered | American Keg Company, Blefa GmbH, Schafer Container Systems, NDL Keg, Shinhan Industrial Co., Ltd., THIELMANN, Heritage, Cask Brewing Systems, Crusader Kegs & Casks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Cask Market Trends and Innovations
Automation of interior finishing processes is redrawing competitive boundaries between European and Asian fabricators, while regulatory migration limits are forcing material science investments across the supply chain.
Laser-guided robotic polishing is collapsing the labor cost differential that previously favored manual finishing operations in lower-wage jurisdictions. German and Czech fabricators are deploying these systems to maintain precision surface roughness specifications at throughput rates matching Asian competitors. The technology is collapsing the historical trade-off between sanitary-grade interior finishes and unit production economics.
REACH substance restrictions on coating chemistries are compelling gasket and seal manufacturers to reformulate elastomer compounds for European-sold casks. ECHA candidate list updates are accelerating substitution of traditional nitrile rubber with peroxide-cured EPDM alternatives. Beverage-contact compliance teams at fabricators are absorbing expanded toxicology documentation burdens to maintain CE marking validity.
Direct procurement relationships between craft brewing cooperatives and specialized cask fabricators are displacing traditional beverage equipment distributors in volume transactions. Cooperative buying consortia in Bavaria and Bohemia are negotiating frame contracts with Blefa GmbH and comparable precision manufacturers. This channel compression is most visible in heritage brewing clusters where technical specification knowledge resides within brewery engineering staffs rather than distributor sales teams.
Stainless Steel Cask Market Segmentation
Stainless steel cask segmentation reveals how fabrication complexity, corrosion resistance, and end-use certification requirements fragment procurement decisions across distinct buyer profiles. Each dimension carries regulatory and technical implications that reshape vendor selection criteria.
Product Type:
Mature single-wall designs dominate heritage brewing installations while emerging insulated formats capture outdoor service expansion.
- Single-Walled Cask:Fabricated from continuous welded austenitic sheet with sanitary interior polish, these vessels serve traditional British-style ale conditioning. Heritage brewers in Germany and the UK specify this format for gravity-dispensed cellar service where thermal retention is secondary to authentic presentation.
- Insulated Cask:Double-shell construction with polyurethane foam interlayer maintains beverage temperature across extended outdoor events. Festival operators in coastal Mediterranean markets specify these units for mobile dispensing where ambient heat would compromise carbonation retention in standard single-wall units.
- Double-Walled Cask:Non-insulated dual-shell design provides secondary containment for chemical transport applications requiring spill protection without thermal performance.
- Reinforced Cask:Structural ribbing and thicker gauge walls withstand pressurized filling cycles and rough handling in industrial logistics chains.
- Portable Cask:Reduced capacity with integrated handling hardware serves laboratory and pilot-scale brewing operations requiring frequent repositioning.
Single-Walled Cask handles the majority of throughput; Insulated Cask is expanding most quickly on share.
Material Grade:
Cost tiers separate commodity austenitic grades from premium corrosion-resistant formulations demanded by aggressive service environments.
- 316 Stainless Steel:Molybdenum-alloyed austenitic grade delivers superior chloride pitting resistance for coastal brewery operations and caustic cleaning regimens. EFSA migration testing protocols and FDA food-contact substance notifications prioritize this grade for acidic beverage contact where 304 would exhibit surface degradation.
- 304 Stainless Steel:Standard 18/8 austenitic composition dominates volume production for inland brewing and food processing where chloride exposure remains minimal. Czech and German fabricators maintain batch-level composition certificates for this grade to satisfy REACH Article 33 disclosure requirements.
- Duplex Stainless Steel:Mixed austenitic-ferritic microstructure combines strength and corrosion resistance for high-pressure chemical transport.
- Ferritic Stainless Steel:Lower nickel content reduces raw material cost exposure for non-critical containment applications.
- Martensitic Stainless Steel:Hardenable grade serves specialized aerospace component handling requiring wear resistance.
304 Stainless Steel captures the highest unit volumes; 316 Stainless Steel commands the steepest expansion trajectory.
Application:
Customer type diversity spans regulated pharmaceutical storage through precision aerospace handling, each imposing distinct surface finish and documentation standards.
- Food & Beverage:Sanitary surface roughness specifications and FDA food-contact compliance dominate procurement specifications for brewing and dairy operations.
- Pharmaceutical Storage:Electropolished interiors and full batch traceability satisfy EMA good manufacturing practice requirements for active ingredient containment.
- Chemical Transportation:Pressure vessel certification and hazardous material compatibility testing govern specification for petrochemical logistics.
- Aerospace Component Handling:Precision dimensional tolerances and non-outgassing surface treatments protect sensitive avionics during transport.
- Laboratory Sample Management:Small-format casks with septum access and cryogenic compatibility serve biobanking and clinical research workflows.
Food & Beverage generates the dominant procurement volume; Pharmaceutical Storage is climbing the fastest on share.
End User:
Volume concentration and margin profile diverge sharply between price-sensitive food processors and specification-rigid biotechnology operators.
- Food Processing Units:High-volume buyers with standardized specifications drive competitive pricing for 304-grade sanitary casks.
- Biotechnology Firms:Stringent surface finish and documentation requirements support premium positioning for validated pharmaceutical-grade vessels.
- Petrochemical Plants:Corrosion-resistant duplex and 316-grade specifications dominate for aggressive chemical containment.
- Aviation Suppliers:AS9100 quality system compliance and specialized non-destructive testing requirements constrain the addressable supply base.
- Research Institutions:Fragmented purchasing across diverse laboratory scales limits standardization opportunities.
Food Processing Units account for the majority of throughput; Biotechnology Firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in stainless steel cask distribution across Northern Europe. Rail corridors from Bavaria to Rotterdam connect precision fabricators to Atlantic shipping lanes. This infrastructure anchors continental supply chains for heritage brewing equipment.
Germany
Bavarian brewing cooperatives drive demand for 316-grade single-walled casks with full REACH documentation. BfR recommendations constrain gasket chemistries in beverage-contact applications. The Munich-Upper Bavaria cluster hosts Blefa GmbH and specialized fabricators serving heritage ale conditioning traditions.
United Kingdom
Traditional cask ale revival sustains procurement volumes for gravity-dispensed cellar service. Food Standards Agency enforcement of EU Regulation 1935/2004 migration limits tightens batch certification requirements. Burton-upon-Trent and Yorkshire brewing districts concentrate heritage-format demand among regional craft producers.
United States
Pacific Northwest craft brewing cooperatives represent underpenetrated demand for FDA food-contact certified vessels. FDA food-contact substance notifications govern material composition for acidic beverage applications. The Seattle-Portland corridor anchors emerging direct-procurement relationships bypassing traditional equipment distributors.
China
Coastal brewery expansions in Shandong and Guangdong provinces specify chloride-resistant grades for aggressive cleaning regimens. GB standards for food-contact metals converge with international sanitary specifications. The Yangtze River Delta cluster automates interior finishing to narrow historical cost advantages against European competitors.
Netherlands
Rotterdam port logistics facilitate cask refurbishment services for Scandinavian circular economy mandates. EU Green Deal deposit-return legislation extends lifecycle accountability across Benelux markets. The Randstad industrial corridor hosts service providers certifying refurbished units for re-entry into beverage supply chains.
Stainless Steel Cask Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fabrication and finishing. The vendor base organizes around three structural tiers: precision manufacturers with heritage brewing relationships, scale-driven container standard-setters, and regional fabricators serving price-sensitive procurement. German and Czech producers occupy the premium tier through automated polishing investments. Competitive dynamics center on welding certification timelines and batch-level documentation capabilities rather than pure unit economics.
Among German fabricators, Blefa GmbH and THIELMANN occupy distinct archetype positions. Blefa GmbH anchors the precision-manufacturing tier for heritage brewers requiring sanitary interior finishes and full regulatory documentation. THIELMANN represents the standard-setting segment across reusable industrial container categories. Schafer Container Systems sits within the distribution-network tier, extending European reach into craft brewing cooperatives through consolidated logistics relationships.
| Leading Market Players |
|---|
| American Keg Company |
| Blefa GmbH |
| Schafer Container Systems |
| NDL Keg |
| Shinhan Industrial Co., Ltd. |
| THIELMANN |
| Heritage |
| Cask Brewing Systems |
| Crusader Kegs & Casks |
| Others |
Pricing and Supply Chain Analysis
Nickel price volatility on the London Metal Exchange determines both the spread between 304-grade and 316-grade cask tiers and the geographic clustering of fabrication capacity around German and Czech automated finishing lines. Buyers facing aggressive cleaning regimens in coastal breweries absorb premium positioning for chloride-resistant grades, while inland food processors negotiate volume discounts on standard austenitic compositions.
Pricing Analysis
Volume-discount tiering structures separate heritage brewing cooperatives purchasing frame-contracted 316-grade vessels from price-sensitive food processors sourcing commodity 304-grade units. Certification level differentiation—REACH-compliant versus basic sanitary finish—creates the primary price spread, with full batch-traceability documentation commanding substantial premiums. Cost compression in the standard-grade tier is intensifying because Yangtze River Delta fabricators have automated interior polishing to match European throughput rates. Food processing units exhibit highest price sensitivity due to standardized specifications and competitive bidding, while biotechnology firms show lowest sensitivity given validation requirements and documentation burdens.
Supply Chain Analysis
Contract manufacturing concentration rests with Blefa GmbH and THIELMANN in Germany, alongside automated fabricators in China's Yangtze River Delta. Raw material dependencies draw from nickel ore processing in Indonesia, ferrochrome production in South Africa, and cold-rolled stainless sheet mills in Germany and Japan. Single-source vulnerability concentrates in southern German precision manufacturers serving heritage brewing clusters. Distribution runs through direct procurement relationships between craft cooperatives and specialized fabricators, displacing traditional beverage equipment distributors in volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal circular economy mandates are accelerating cask lifecycle accountability and refurbishment service expansion, creating a high-growth disruption as deposit-return legislation redefines asset economics across Scandinavian markets.
For Market Incumbents: Harden defensive positioning by deepening backward integration into nickel alloy supply and securing ASME Section IX welding certifications ahead of capacity expansion timelines. Threat substitution from KeyKeg and PET formats in outdoor event channels demands premium insulation performance claims and direct venue distribution control. Priority investment in laser-guided robotic polishing maintains precision surface specifications against Asian cost convergence. For New Entrants and Emerging Players: US Pacific Northwest craft brewing cooperatives represent the most penetrable entry point for FDA food-contact certified vessels with sanitary interior finishes. Bavarian cooperative buying consortia negotiating frame contracts with established precision manufacturers reveal channel compression opportunities for specialized fabricators offering digital traceability integration. Go-to-market execution should target direct procurement relationships bypassing traditional equipment distributors through technical specification partnerships with brewery engineering staffs. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors certified refurbishment service providers and automated finishing technology owners. Long-term viability across the five-to-ten year window rests on circular economy mandate compliance capabilities and batch-level documentation infrastructure. Acquisition focus should center on European fabricators with REACH certification depth and RFID-enabled lifecycle tracking systems. The signal to watch is ECHA candidate list updates accelerating elastomer compound substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Mitigates LME price volatility exposure for austenitic grade fabricators serving heritage brewers. |
| Automated Interior Finishing Deployment | Laser-guided robotic polishing collapses labor cost differentials against Yangtze River Delta competitors. |
| Digital Traceability Integration | RFID tagging with batch certificates satisfies EU Regulation 1935/2004 lifecycle accountability requirements. |
| Refurbishment Service Network Expansion | Scandinavian deposit-return legislation creates recurring revenue streams for certified reconditioning providers. |
| Direct Cooperative Procurement Channels | Bypassing traditional distributors captures margin from Bavarian and Bohemian brewing consortium frame contracts. |
Research Methodology
Initial hypotheses were tested against primary input from brewery procurement directors, cask fabrication plant managers, beverage equipment distributors, and regulatory compliance officers at fabricators, then refined against secondary validation from EU Regulation 1935/2004 migration limit documentation, FDA food-contact substance notification filings, ECHA REACH candidate list updates, and trade customs data for stainless steel vessel imports. Bottom-up demand modeling across end-use segments was triangulated with top-down supply capacity assessments from precision manufacturers and automated fabricators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material grade, application, and end-user category. CAGRs were derived from volume trajectory modeling incorporating heritage ale conditioning revival rates, coastal brewery expansion patterns, and circular economy mandate implementation timelines. Industry-specific forecast inputs included nickel price band assumptions and welding certification pipeline constraints for new fabrication facilities.
Stress conditions across nickel price volatility bands, tariff exposure scenarios, and regulatory chokepoint delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and automated finishing technology adoption curves. Quarterly review of ECHA substance restriction updates and Scandinavian deposit-return legislation rollout metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Container Stacking Machine Market
Containers
Acrylic Container Market
Containers
Kuwait Container Glass Market
Containers
Thermoformed Shallow Trays Market
Containers
Oblong Tub Lids Market
Containers
Flexible Water Tanks Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Stackable Plastic Trays Market
Containers
Snap Secure Containers Market
Containers
Container Mouth Inner Seal Market
Containers
Global Cardboard Box and Container Market
Containers
ISO Ocean Containers Market
Containers
Wet Wipes Canister Market
Containers
Feeder Containers Market
Containers
Injection Molding Containers Market
Containers
Dispensing Jug Market