
 Middle East and Africa Coated Paper Market | 2026-2036
Middle East and Africa Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Coated Paper Market Foresight
Specialized pulp chemistry expertise is reorganizing competitive dynamics across the Middle East and Africa coated paper supply base. Mondi Plc leverages its integrated kraft pulp network to secure raw material continuity for Gulf-based converting customers. Sappi Limited anchors premium coated fine paper supply through its South African manufacturing footprint, while International Paper Company competes via extensive distributor relationships spanning Nigerian and Kenyan print markets.
Coated paper consists of base paper substrate layered with mineral pigments such as kaolin clay and calcium carbonate bound with synthetic latex, yielding surface smoothness measured in Bekk seconds for high-resolution printing applications. Coated fine paper dominates margin pools across publication and commercial printing applications due to superior ink holdout and brightness metrics. Specialty coated paper segments sustain faster expansion through barrier properties tailored to food-contact packaging requirements, while coated groundwood paper occupies cost-sensitive mass circulation newspaper inserts where optical performance thresholds remain lower.
South Africa's Department of Forestry, Fisheries and the Environment pulp sourcing mandates intersect with Egypt's environmental compliance protocols for imported paper stocks, creating dual certification burdens for cross-regional suppliers. The EU Green Deal's embedded carbon border adjustments on imported finished paper goods indirectly reshape export economics for Middle Eastern mills serving European print buyers. Stakeholders must monitor evolving polymer coating restrictions under REACH-aligned regulatory proposals gaining traction among Gulf standardization bodies.
Market Dynamics
Premium packaging converters across the Gulf Cooperation Council are consolidating coated paper procurement around suppliers with captive kraft pulp networks, compressing margins for merchant-market players dependent on spot pulp purchases.
Growth Catalysts
- Egypt's Print Media Expansion:Educational publishers in Cairo and Alexandria are scaling coated fine paper orders for textbook modernization programs, creating sustained volume anchors for regional mills.
- EU Green Deal Border Adjustments:Carbon-intensity documentation requirements for finished paper exports to Europe are accelerating certification investments among Saudi and UAE producers seeking premium market access.
- Barrier Coating Chemistry Advances:Mineral-polymer hybrid formulations with oxygen-scavenging properties are opening food-contact packaging applications previously served by plastic films.
Market Restraints
- Hardwood Pulp Price Volatility:Eucalyptus pulp spot markets in Brazil and Chile transmit cost shocks to MEA converters within 60-90 day lags, eroding contract margin predictability.
- South African Supply Concentration:Sappi's dominance in premium coated fine paper creates single-source vulnerability for Nigerian and Kenyan print buyers during port congestion events.
- Groundwood Substitution Ceiling:Mechanical pulp-based alternatives hit brightness and ink holdout thresholds that exclude them from high-end commercial printing specifications.
Strategic Opportunities
- Kenyan Print Market Formalization:Nairobi's commercial printing sector is transitioning from informal sheet-fed operations to web-offset facilities requiring reel-fed coated paper supply contracts.
- Biopolymer Coating Convergence:Starch-latex hybrid binders combined with calcium carbonate pre-coating layers are enabling compostable packaging claims for quick-service restaurant chains.
- Gulf Standardization Body REACH Alignment:Proposed polymer coating restrictions under GSO technical regulations will advantage early-compliant suppliers with existing EU certification infrastructure.
Industry Challenges
- Specialized Coating Technician Scarcity:Blade coating and film transfer expertise concentrates in South African and Egyptian mill workforces, constraining technology transfer to newer Gulf facilities.
- Dual Certification Timeline Compression:Suppliers serving both South African DFFE pulp sourcing mandates and Egyptian import compliance must maintain parallel audit cycles with non-harmonized documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Coated Paper Market |
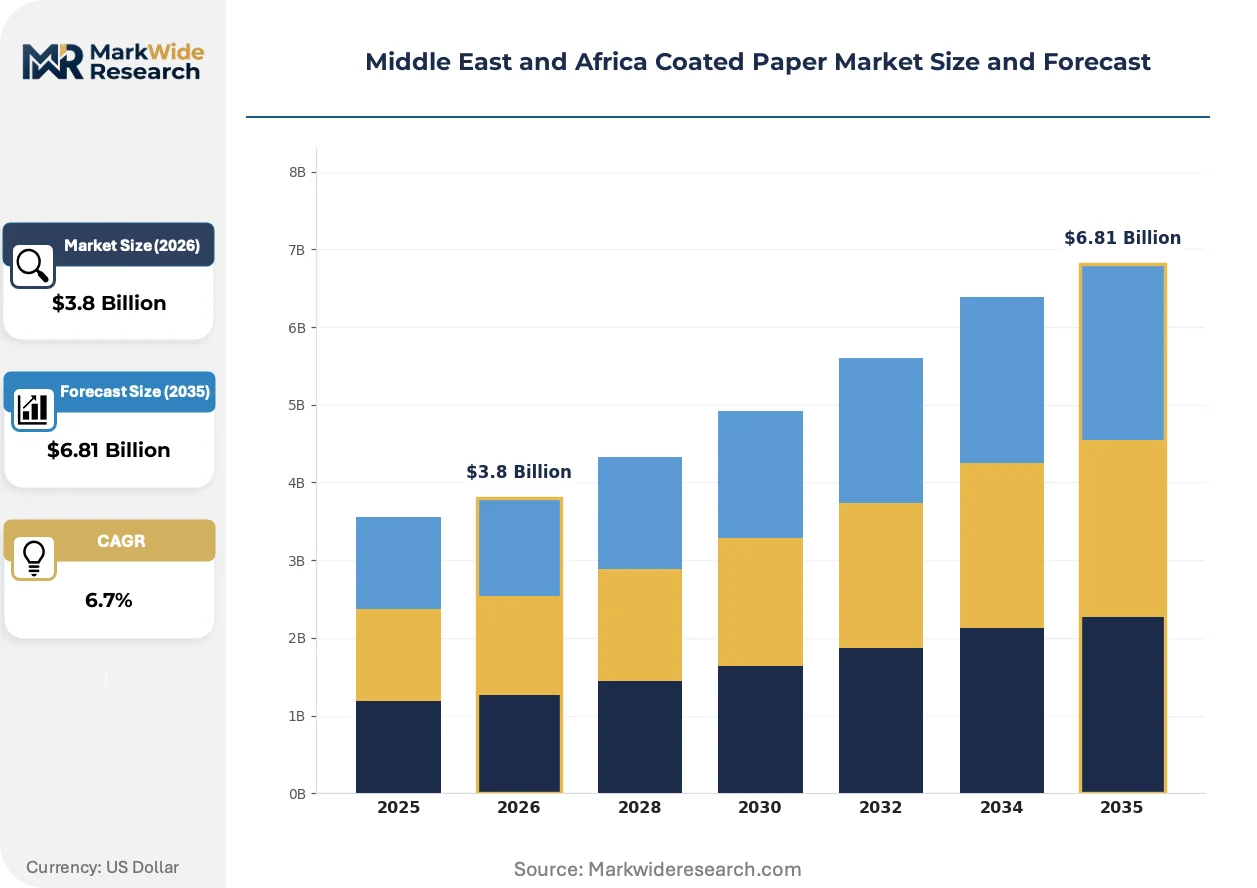
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Fine Paper, Coated Groundwood Paper, Coated Woodfree Paper, Specialty Coated Paper Application: Printing, Packaging, Stationery, Publication End User: Publishing Houses, Advertising Agencies, Educational Institutions, Commercial Printers Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | International Paper Company, Sappi Limited, Mondi Plc, Smurfit Kappa, Billerud, UPM-Kymmene Corporation, Stora Enso Oyj, Asia Pulp & Paper, Oji Holdings Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Coated Paper Market Shifts & Advancements
Digital printing compatibility requirements are forcing coated paper producers to recalibrate surface chemistry for variable ink absorption rates, disrupting legacy formulations optimized for conventional offset processes.
Mineral coating formulations incorporating engineered calcium carbonate with controlled particle size distribution are fragmenting the traditional kaolin-dominated premium segment. High-end commercial printers in Dubai and Riyadh are adopting these substrates for shorter-run, faster-turnaround jobs. The technology is fragmenting established supplier relationships as converters trial multiple coating chemistries to match specific digital press configurations.
South Africa's Department of Forestry, Fisheries and the Environment pulp sourcing mandates now require chain-of-custody documentation extending to plantation-level geolocation data. Integrated producers with captive forestry assets are capturing qualification advantages over merchant pulp buyers. Specialty coated paper segments targeting food-contact applications face the steepest compliance burden as auditors scrutinize latex additive provenance alongside fiber sourcing.
Consolidated procurement desks at multinational consumer goods headquarters are compressing supplier rosters across Middle East and Africa operations. Regional distributors serving Nigerian and Kenyan print markets are losing volume to direct mill relationships negotiated at Dubai or Johannesburg corporate levels. The shift is most visible in Egypt's educational publishing cluster, where ministry-level tenders now specify single-source accountability for multi-year textbook supply contracts.
Middle East and Africa Coated Paper Market Segmentation
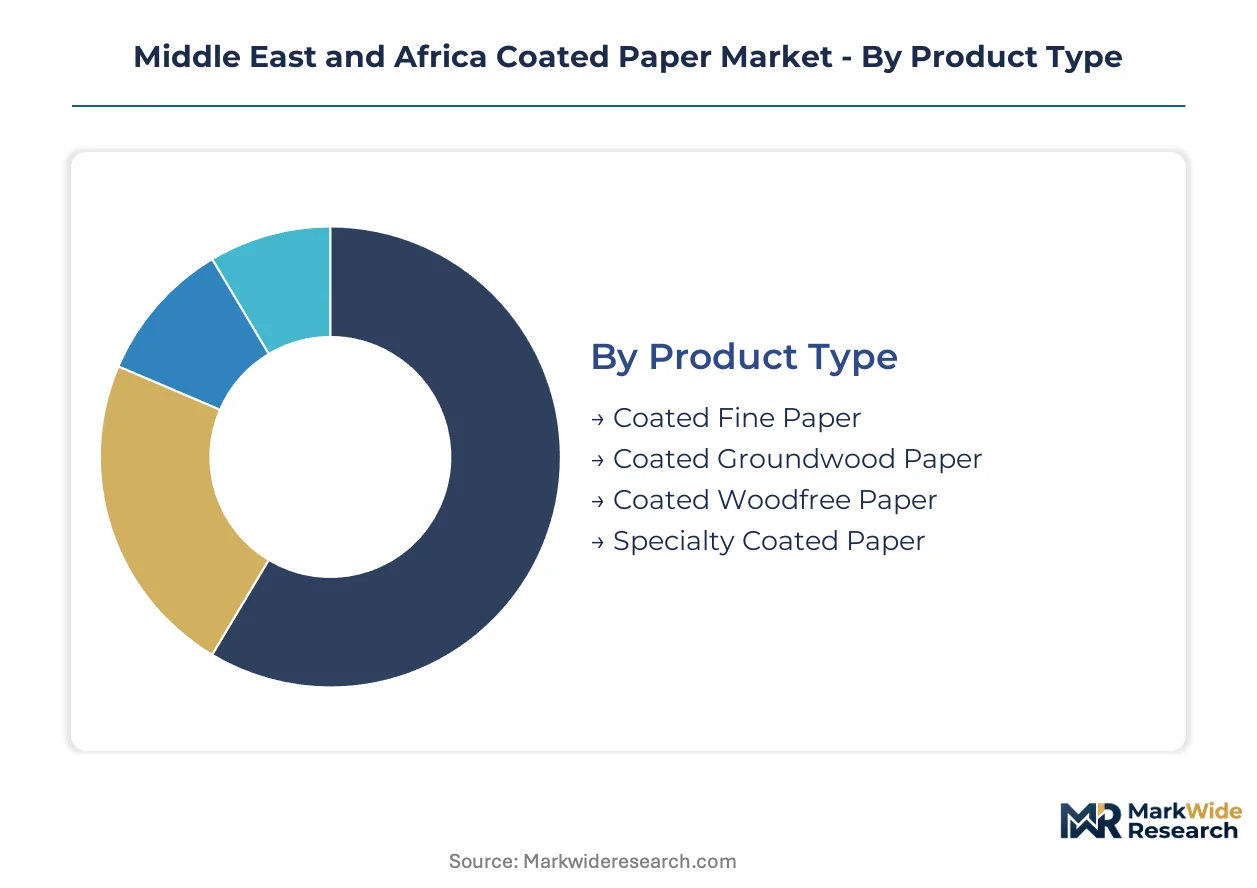
Coated paper segmentation across the Middle East and Africa reflects divergent substitution pressures from digital media, plastic films, and uncoated alternatives. Each dimension—product chemistry, application requirements, end-user procurement patterns, and channel configuration—shapes margin pools and supplier qualification thresholds differently across Gulf and sub-Saharan markets.
Product Type:
Coated groundwood paper faces the most acute substitution threat as digital news consumption and electronic document distribution erode its core newspaper insert and mass-circulation magazine applications.
- Coated Fine Paper:Mineral-pigment surface layers bound with synthetic latex deliver superior brightness and ink holdout measured in Bekk seconds. Cairo and Alexandria educational publishers are scaling orders for textbook modernization programs, creating volume anchors for regional mills despite hardwood pulp price volatility.
- Specialty Coated Paper:Barrier-formulated substrates incorporate oxygen-scavenging mineral-polymer hybrids for food-contact compliance. Quick-service restaurant chains across Dubai and Riyadh are adopting compostable coating claims to meet evolving Gulf standardization body technical regulations.
- Coated Groundwood Paper:Mechanical pulp base limits brightness thresholds, constraining use to cost-sensitive newspaper inserts where optical performance requirements remain minimal.
- Coated Woodfree Paper:Chemical pulp substrate eliminates lignin content for archival stability in premium stationery and corporate documentation applications.
Coated fine paper anchors the volume base while specialty coated paper gains share at the steepest rate.
Application:
Margin stratification across applications follows the technical specification intensity required by each end-use, with packaging converters commanding premium pricing for barrier-certified substrates.
- Packaging:Barrier coating chemistry advances with calcium carbonate pre-coating layers enable compostable claims for food-contact applications. Gulf Cooperation Council premium packaging converters are consolidating procurement around suppliers with captive kraft pulp networks.
- Printing:Digital printing compatibility requirements are forcing surface chemistry recalibration for variable ink absorption rates. High-end commercial printers in Dubai and Riyadh are trialing engineered calcium carbonate formulations for shorter-run, faster-turnaround jobs.
- Publication:Educational publishing clusters in Egypt specify single-source accountability for multi-year textbook supply contracts, compressing distributor margins.
- Stationery:Corporate documentation and premium writing paper demand concentrates in South African and Nigerian formal sector procurement.
Packaging commands the steepest margin expansion trajectory while printing retains the largest absolute volume position.
End User:
Procurement formalization divides end users between consolidated multinational desks and fragmented local buyers, reshaping channel economics across the region.
- Educational Institutions:Egypt's ministry-level tenders for textbook supply are transitioning from distributor-mediated to direct mill relationships negotiated at Dubai corporate levels. Compliance documentation requirements now extend to plantation-level geolocation data under South African DFFE mandates.
- Commercial Printers:Nairobi's sector is transitioning from informal sheet-fed operations to web-offset facilities requiring reel-fed coated paper supply contracts. Kenyan print market formalization is opening multi-year volume commitments for regional mills.
- Publishing Houses:Cairo and Alexandria educational publishers are modernizing textbook programs, driving coated fine paper demand despite digital substitution pressures in consumer magazines.
- Advertising Agencies:Premium collateral and point-of-sale material production concentrates in Dubai and Johannesburg creative hubs.
Educational institutions anchor procurement volume stability while commercial printers present the most rapid formalization-driven expansion opportunity.
Distribution Channel:
Channel restructuring follows mill direct-selling investments and procurement desk consolidation at multinational consumer goods headquarters.
- Direct Sales:Consolidated procurement desks are compressing supplier rosters across Middle East and Africa operations. Mondi Plc leverages integrated kraft pulp networks to secure raw material continuity for Gulf-based converting customers through direct mill relationships.
- Distributors:Regional distributors serving Nigerian and Kenyan print markets are losing volume to direct relationships. Sappi Limited anchors premium coated fine paper supply through South African manufacturing footprint with extensive distributor coverage.
- Wholesale:Spot market access for merchant-market players dependent on pulp purchases faces margin compression from captive network competitors.
- Online Retail:Small-format stationery and specialty paper segments see emerging e-commerce penetration in urban South African and UAE markets.
Direct sales channels capture the steepest share growth while distributor networks retain the broadest geographic coverage for fragmented print markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Middle East and Africa diverge sharply: Gulf Cooperation Council states prioritize barrier-coated packaging for premium consumer goods, while sub-Saharan markets concentrate coated fine paper demand in educational publishing and formal sector documentation.
Saudi Arabia
Packaging converters in Riyadh and Jeddah are scaling procurement of mineral-polymer hybrid coated papers for quick-service restaurant chains and luxury retail. The Saudi Standards, Metrology and Quality Organization (SASO) is advancing REACH-aligned technical regulations for polymer coating restrictions. Eastern Province industrial zones host expanding converting capacity serving both domestic food-contact applications and re-export markets.
United Arab Emirates
Dubai's commercial printing hub is transitioning to digital-press-compatible coated paper formulations for shorter-run collateral production. The UAE's Ministry of Industry and Advanced Technology enforces embedded carbon documentation for paper imports under EU Green Deal alignment pressures. Jebel Ali free zone concentration of multinational procurement desks is compressing regional distributor margins through direct mill contracting.
South Africa
Premium coated fine paper production anchors export supply to Nigerian and Kenyan print markets despite hardwood pulp cost volatility. The Department of Forestry, Fisheries and the Environment mandates plantation-level geolocation chain-of-custody documentation reshaping supplier qualification. KwaZulu-Natal and Mpumalanga forestry assets provide captive pulp continuity for integrated producers.
Egypt
Cairo and Alexandria educational publishers are driving coated fine paper volume through ministry-level textbook modernization tenders. Egyptian environmental compliance protocols for imported paper stocks require dual certification alongside South African DFFE mandates for cross-regional suppliers. Giza and 6th of October industrial zones concentrate web-offset capacity transitioning from informal sheet-fed operations.
Nigeria
Lagos and Kano commercial printing sectors are formalizing procurement through reel-fed supply contracts for expanding web-offset facilities. The country's national standards body is developing technical regulations for food-contact paper coatings. Apapa port congestion events expose single-source vulnerability for premium coated fine paper dependent on South African mill supply.
Middle East and Africa Coated Paper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East and Africa coated paper supply base. Captive kraft pulp networks distinguish the upper tier from merchant-market players exposed to spot pulp volatility. Three archetypes dominate: integrated forestry-to-paper producers with regional manufacturing footprints, specialty barrier-coating specialists serving food-contact packaging, and merchant converters dependent on distributor relationships. Competitive moves concentrate on backward integration into pulp supply and direct mill contracting with multinational procurement desks.
Among integrated producers with African manufacturing presence, Sappi Limited and Mondi Plc exemplify the captive-pulp archetype securing raw material continuity for Gulf-based customers. International Paper Company occupies a position within the distributor-dependent tier serving Nigerian and Kenyan print markets through extensive third-party relationships. These three entities represent distinct strategic postures: regional production anchoring, integrated supply chain control, and market coverage through channel partnerships.
| Leading Market Players |
|---|
| International Paper Company |
| Sappi Limited |
| Mondi Plc |
| Smurfit Kappa |
| Billerud |
| UPM-Kymmene Corporation |
| Stora Enso Oyj |
| Asia Pulp & Paper |
| Oji Holdings Corporation |
| Others |
Supply & Pricing Matrix
Engineered calcium carbonate substitution for traditional kaolin clay is simultaneously fragmenting premium supplier relationships and compressing pricing premiums for legacy coating chemistries across Gulf converting markets. This mineral-pigment shift redraws procurement geography as Dubai and Riyadh commercial printers trial multiple substrate sources to match specific digital press configurations.
Pricing Analysis
Long-term offtake contracts dominate coated fine paper procurement for Egyptian educational publishers and GCC premium packaging converters, insulating integrated producers from spot pulp volatility while exposing merchant-market players to 60-90 day cost transmission lags from Brazilian eucalyptus markets. Price differentiation rests on captive kraft pulp network access and REACH-aligned certification tier. Cost compression in standard-grade segments is intensifying as hardwood pulp spot markets transmit volatility through non-integrated supply chains. Educational institutions exhibit the highest price sensitivity due to ministry tender structures, while luxury retail packaging buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites raw material continuity for Gulf-based converting customers sourcing from South African and Egyptian mill networks. Supply concentration centers on South Africa, Saudi Arabia, and Egypt as primary production hubs. The chain draws from Brazilian eucalyptus pulp, synthetic latex binders, and engineered calcium carbonate feedstocks. Single-source vulnerability from Sappi's dominance in premium coated fine paper creates disruption exposure during Apapa port congestion events. Distribution runs through direct mill relationships with multinational procurement desks in Dubai and Johannesburg, compressing traditional distributor margins across Nigerian and Kenyan print markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa coated paper market functions as a defensive-moat arena where regulatory entrenchment through dual DFFE and Egyptian compliance certification creates switching costs that protect qualified supplier positions.
For Market Incumbents: Compound captive pulp advantages by securing plantation-level geolocation documentation ahead of evolving South African chain-of-custody mandates. Anchor GCC market share through direct procurement desk relationships with multinational consumer goods headquarters, neutralizing distributor-dependent competitors exposed to spot pulp volatility and margin compression from integrated network rivals.
For New Entrants and Emerging Players: Anchor in Kenyan commercial printing formalization as Nairobi's web-offset transition creates reel-fed supply contract openings underserved by incumbent distributor networks. Target barrier-coated specialty segments for quick-service restaurant chains as Gulf standardization bodies advance REACH-aligned polymer restrictions. Pursue biopolymer coating chemistry partnerships with compostable packaging claims to bypass established latex supply relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated forestry-to-paper producers with captive KwaZulu-Natal and Mpumalanga pulp assets over merchant-market converters. Long-term viability across the projection horizon hinges on backward integration depth and certification infrastructure readiness. Monitor SASO technical regulation advancement as the inflection signal for compliance-premium capture opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pulp Network Expansion | KwaZulu-Natal forestry asset control secures raw material continuity for GCC converting customers. |
| REACH-Aligned Certification Investment | Early SASO compliance creates qualification advantages for Dubai luxury retail packaging tenders. |
| Direct Procurement Desk Relationships | Johannesburg and Dubai corporate-level contracting compresses distributor margins in fragmented markets. |
| Biopolymer Coating R&D Partnership | Starch-latex hybrid development enables compostable claims for quick-service restaurant chains. |
| Kenyan Market Formalization Entry | Reel-fed supply contracts capture Nairobi's web-offset transition from informal sheet-fed operations. |
Research Methodology
Desk research of trade flow databases, customs records, and forestry certification registries preceded structured interviews with mill coating technicians, GCC packaging procurement directors, Egyptian educational publisher supply managers, and South African DFFE compliance auditors. Primary fieldwork with blade coating specialists and film transfer engineers in Cairo and Johannesburg informed technology transfer constraint assessments. Secondary validation drew from pulp futures market data, EU Green Deal border adjustment documentation, and Gulf standardization body technical regulation drafts. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Variance decomposition across product chemistry, application requirements, end-user procurement patterns, and channel configuration anchored the analytical framework over the projection horizon. Segmentation dimensions included coating mineralogy tier, barrier certification status, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves incorporating hardwood pulp price transmission coefficients and digital printing adoption trajectories. Industry-specific inputs encompassed Bekk smoothness specification thresholds and oxygen-scavenging mineral-polymer hybrid formulation penetration rates.
Material uncertainties — hardwood pulp spot market volatility, SASO regulatory timeline acceleration, and Apapa port congestion recurrence — sit outside the modeled envelope. Forecasts reflect assumptions regarding educational publishing tender continuity and GCC quick-service restaurant expansion trajectories. Practitioners should keep alternative scenarios live as EU Green Deal carbon border adjustment stringency and Egyptian import compliance protocol harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Retail Paper Bags Market