
 Middle East and Africa Aerosol Cans Market | 2026-2036
Middle East and Africa Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aerosol Cans Market Foresight
Modern trade channels across the Middle East and Africa are rewriting how aerosol can manufacturers reach end buyers. Can-Pack SA leverages its Polish parent company's European technical standards to supply North African markets with aluminum beverage and aerosol formats. Crown Holdings Inc. anchors its regional position through a Jeddah manufacturing facility that serves Saudi Arabia's domestic personal care sector. Nampak Ltd competes from its South African base, sustaining long-standing supply relationships with multinational fast-moving consumer goods brands operating across Sub-Saharan Africa.
Aerosol cans are sealed pressurized metal or plastic containers designed to dispense products through a valve system, typically constructed from aluminum or steel with internal coatings resistant to propellant corrosion and product chemical interaction. These containers serve the primary commercial purpose of delivering controlled, metered sprays for personal care, household, industrial, and automotive applications across consumer and professional markets. Aluminum material dominates value capture in the Middle East and Africa due to its lightweight properties and recyclability appeal, while steel sustains volume share in industrial paints and automotive segments where structural rigidity matters. The personal care application leads consumption across the region, though cleaning agents show structural momentum as hygiene awareness campaigns expand in urban Egyptian and Nigerian markets.
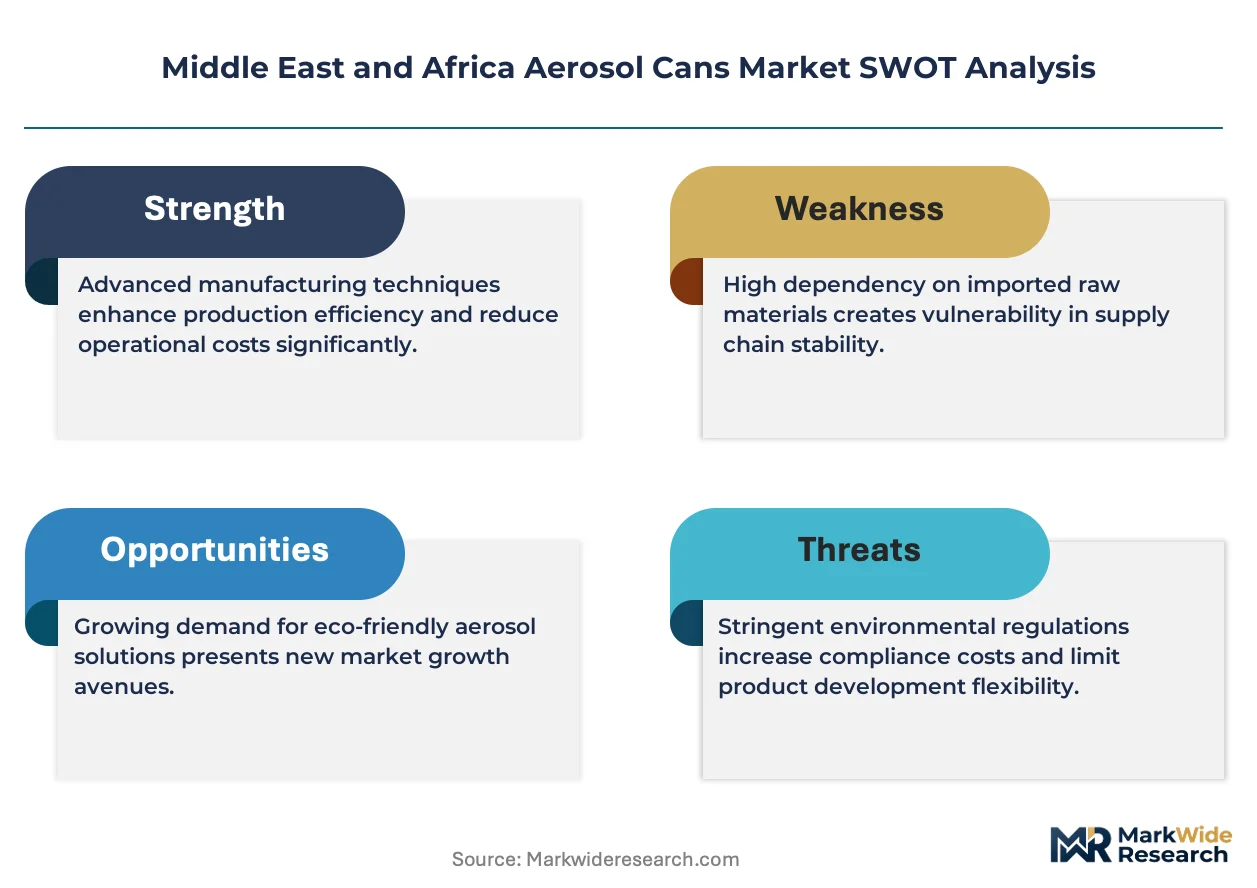
Saudi Arabia's SASO standards, South Africa's NRCS compulsory specifications, and Egypt's EOS quality certifications collectively shape product compliance requirements for aerosol can imports and local production across the region. These frameworks mandate pressure testing, material thickness minimums, and labeling in Arabic or local languages, effectively filtering market access for non-compliant suppliers. Stakeholders must monitor evolving extended producer responsibility proposals in Gulf Cooperation Council jurisdictions, as these policies will reshape recycling infrastructure investments and packaging cost structures.
Market Dynamics
Saudi Arabia's SASO quality mark requirements are compressing compliance timelines for metal packaging suppliers across Gulf manufacturing zones, forcing regional producers to accelerate laboratory certification investments or exit import channels entirely.
Growth Catalysts
- Propellant technology migration:Hydrocarbon and compressed gas systems are displacing traditional chlorofluorocarbon formulations in personal care applications, aligning with Egypt's EOS environmental certification pathways and reducing import barriers for European formulations.
- Urban hygiene campaigns:Cleaning agent demand is accelerating in Lagos and Cairo metropolitan corridors, where aerosol disinfectants and surface sprays are penetrating informal retail networks previously dominated by bulk liquid alternatives.
- SASO standard harmonization:Saudi Arabia's technical regulations for pressure vessel integrity are creating a unified compliance baseline across GCC states, reducing fragmentation costs for manufacturers serving multiple Gulf markets from single production facilities.
Market Restraints
- Aluminum ingot cost volatility:Raw material price swings for primary aluminum are compressing margin stability for can producers, particularly those without long-term smelter offtake agreements or backward integration into billet casting.
- Steel supply concentration:Flat-rolled steel for industrial paint cans remains dependent on Turkish and Indian mill imports, exposing regional converters to freight cost spikes and currency mismatch risks during Egyptian pound or Nigerian naira depreciation cycles.
- Propellant import licensing:Nigeria's petroleum regulator maintains tight controls on liquefied petroleum gas derivatives used in aerosol systems, creating clearance delays that extend working capital cycles for Lagos-based filling operations.
Strategic Opportunities
- Moroccan export platform:Can-Pack SA's North African production hub offers tariff-advantaged access to West African Economic and Monetary Union markets, where local filling capacity remains underdeveloped for personal care and household segments.
- Extended producer responsibility frameworks:Draft GCC regulations on packaging waste recovery are positioning early investors in aluminum collection infrastructure to capture compliance premiums from multinational brand owners facing scope 3 emissions targets.
- Digital printing convergence:Direct-to-can decoration technologies are collapsing minimum order quantities for seasonal and promotional aerosol SKUs, enabling regional brands to test localized fragrance variants without plate changeover costs.
Industry Challenges
- Coating chemist scarcity:Internal lining formulation expertise for corrosive product compatibility remains concentrated in European technical centers, forcing regional producers to rely on imported epoxy and polyester systems with extended lead times.
- Pressure testing certification backlog:SASO-accredited laboratories in Jeddah and Dammam face queue delays exceeding eight weeks for new can design approvals, compressing product launch windows for personal care brands targeting Ramadan seasonal cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aerosol Cans Market |
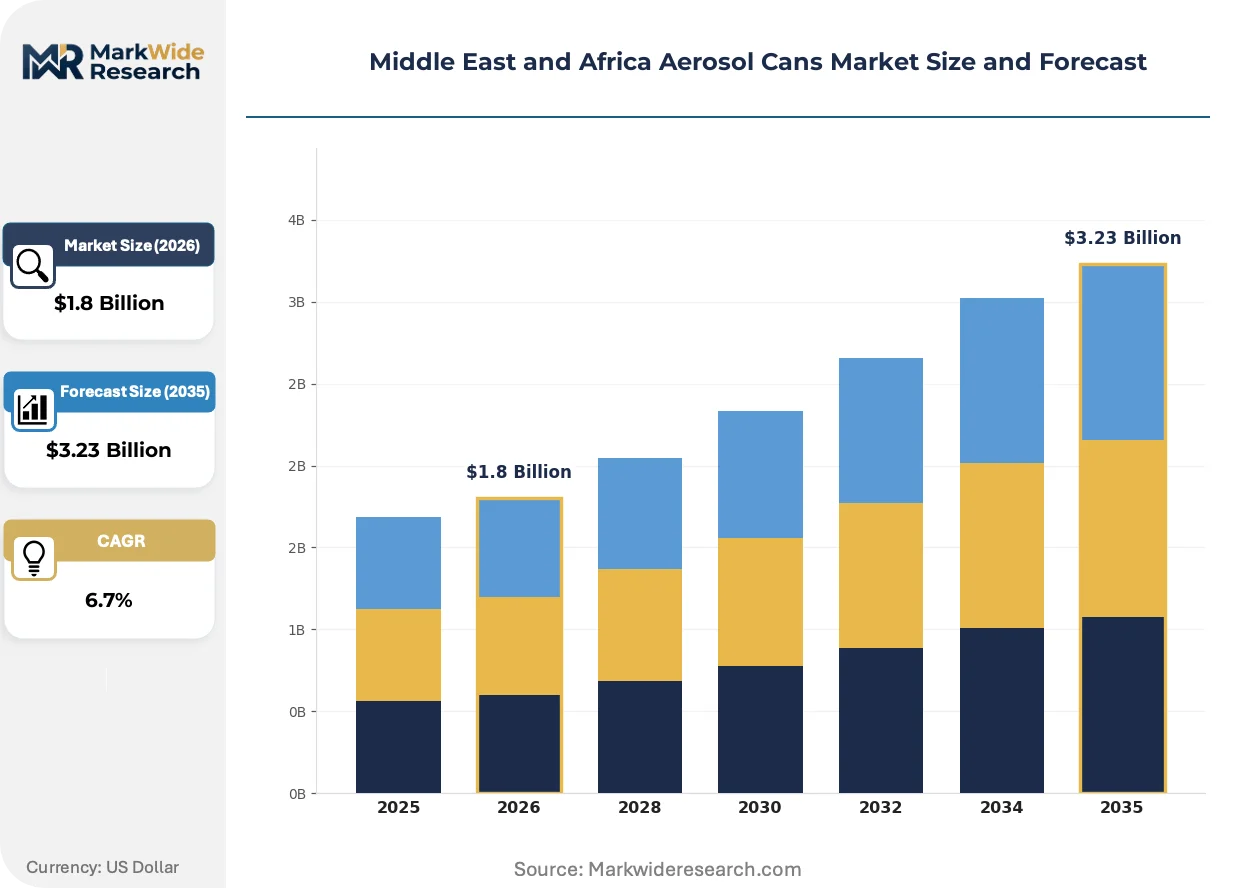
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Personal Care, Household, Industrial Material: Aluminum, Steel, Plastic, Glass Application: Cosmetics, Cleaning Agents, Paints, Automotive End User: Retailers, Manufacturers, Distributors, Wholesalers |
| Companies Covered | Can-Pack SA, Mauser Packaging Solutions, Crown Holdings Inc., Tecnocap SpA, Saudi Can Co. Ltd., Ball Corporation, Nampak Ltd, Saudi Arabian Packaging Industry WLL (SAPIN), CCL Industries, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aerosol Cans Market Shifts & Advancements
Material science advances and regulatory stringency are restructuring how aerosol containers are specified, sourced, and recovered across Middle Eastern and African supply chains.
Aluminum monobloc cans with integrated shoulder and dome structures are collapsing the cost gap between two-piece steel assemblies and premium seamless formats. South African personal care brands are adopting these designs for deodorant and dry shampoo lines, eliminating separate component inventory and reducing leak-test failure rates at filling lines. The technology is compressing supplier consolidation incentives as converters with deep-drawing capabilities capture volume from legacy three-piece assemblers.
Saudi Arabia's SASO technical regulations for pressure vessel safety are tightening material thickness minimums and mandating Arabic-language hazard labeling for all imported aerosol formats. These requirements are filtering market access for Southeast Asian suppliers lacking Gulf-specific certification infrastructure, while rewarding regional producers with established Jeddah and Dammam testing relationships. Personal care applications face the steepest compliance ramp due to higher consumer exposure frequencies and retail shelf visibility.
Modern trade consolidation across Cairo and Lagos is compressing procurement cycles for aerosol can specifications. Hypermarket chains operating Egyptian and Nigerian retail networks are unbundling after-sales technical support from container supply agreements, instead demanding direct quality accountability from can manufacturers rather than through distributor intermediaries. This pattern concentrates specification influence with multinational fast-moving consumer goods procurement teams based in Johannesburg and Dubai trading hubs.
Middle East and Africa Aerosol Cans Market Segmentation
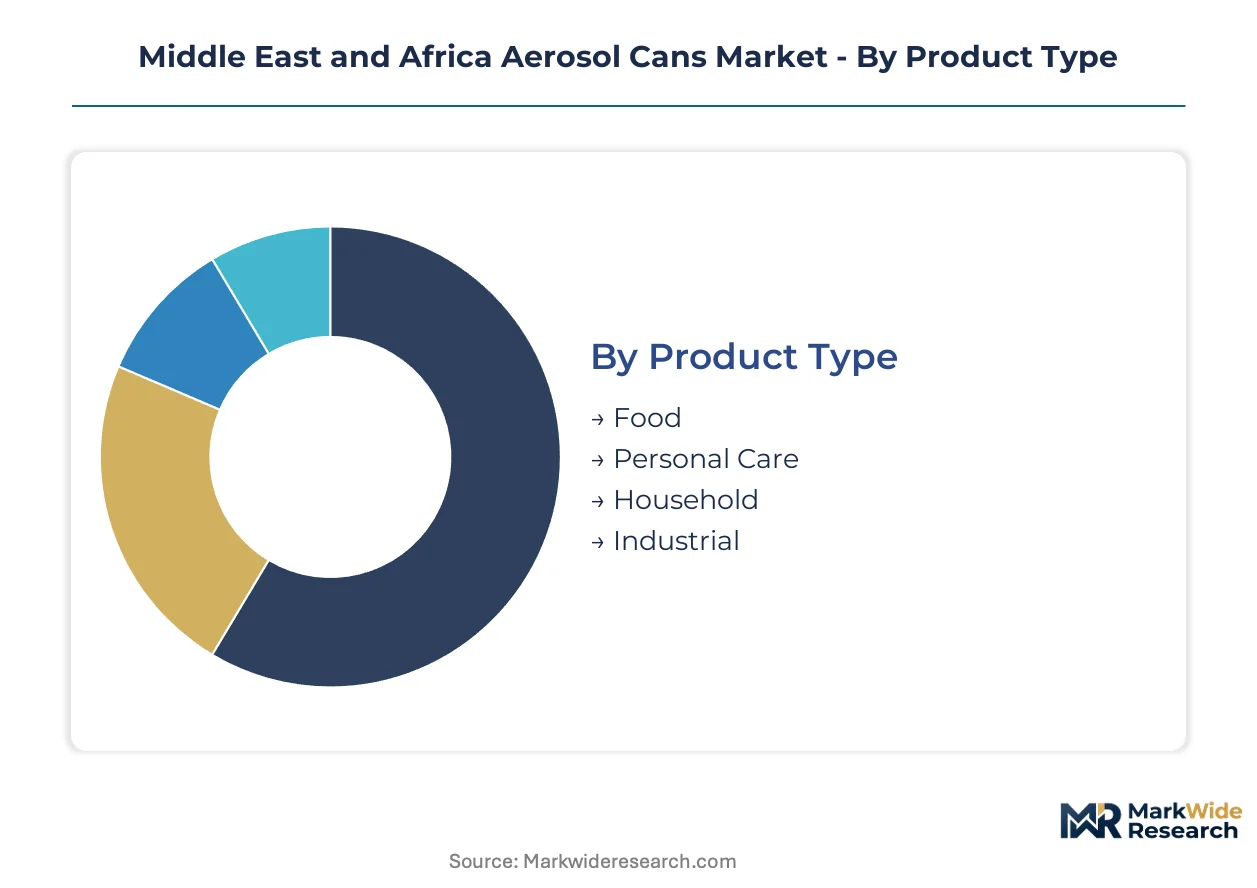
Aerosol can specifications across the Middle East and Africa diverge sharply by pressure rating, lining chemistry, and valve compatibility. Understanding these segment boundaries clarifies why Saudi filling lines reject Nigerian-sourced steel formats, and why Moroccan aluminum monobloc designs command premium placement in Cairo hypermarkets.
Product Type:
Application use case dictates pressure vessel design, propellant compatibility, and coating specifications across regional production facilities.
- Personal Care:Deodorant and hair spray formulations require seamless aluminum monobloc construction with epoxy-phenolic internal linings resistant to ethanol-based propellants. Demand concentrates in South Africa's Gauteng manufacturing belt, where Unilever and Procter & Gamble filling operations specify Crown Holdings Jeddah-sourced two-piece aluminum for fragrance stability.
- Household:Insecticide and surface disinfectant cans utilize steel three-piece assemblies with tinplate or chrome-plated substrates for cost containment. Lagos industrial corridor filling plants favor this format for price-competitive distribution through Nigerian informal retail networks, though SASO pressure testing requirements are compressing import windows for non-certified suppliers.
- Food:Cooking spray and whipped cream applications demand food-grade epoxy linings and nitrogen propellant systems. Egyptian canners serving Gulf export markets face extended EOS certification queues for dairy-contact surface approvals.
- Industrial:Paint and lubricant aerosols require heavy-gauge steel with solvent-resistant polyester linings. Turkish mill dependency for flat-rolled substrate exposes regional converters to freight volatility during lira depreciation cycles.
Personal Care commands the established base. The steepest expansion runs through Household.
Material:
Raw material selection determines weight economics, recyclability positioning, and compliance pathway complexity across Gulf and Sub-Saharan supply chains.
- Aluminum:Lightweight, corrosion-resistant, and infinitely recyclable, aluminum dominates personal care and cosmetic applications. Deep-drawn monobloc designs from Can-Pack SA's Moroccan facility capture volume from legacy steel assemblers by eliminating separate dome inventory and reducing leak-test failures.
- Steel:Structural rigidity and lower raw material cost sustain steel's position in industrial paints and automotive applications. Nigerian filling operations depend on Indian and Turkish flat-rolled imports, exposing margin stability to naira depreciation and freight cost spikes.
- Plastic:PET and nylon barrier formats serve niche pharmaceutical and veterinary spray applications where metal incompatibility risks product degradation. Limited regional production capacity forces reliance on European converter relationships.
- Glass:Fragile but chemically inert, glass aerosols preserve high-value fragrance formulations for Gulf luxury retail channels. Jeddah and Dubai duty-free operations specify this format for premium positioning despite higher logistics breakage rates.
Aluminum captures the value concentration. Steel retains the volume foundation.
Application:
End-use environment shapes pressure specifications, valve actuator design, and labeling compliance requirements.
- Cosmetics:Fine-mist actuators and crimped valve assemblies deliver controlled fragrance dispersion for deodorant and hair care products. Saudi Arabia's SASO Arabic-labeling mandates filter non-compliant Southeast Asian imports from personal care shelf sets.
- Cleaning Agents:Disinfectant and surface spray demand accelerates in Cairo and Lagos metropolitan corridors, where aerosol formats penetrate informal retail networks previously dominated by bulk liquid alternatives. Hydrocarbon propellant migration aligns with Egypt's EOS environmental certification pathways.
- Paints:High-pressure steel construction withstands solvent-based formulation chemistry for automotive touch-up and industrial coating applications. Coating chemist scarcity in regional technical centers forces reliance on imported epoxy systems with extended lead times.
- Automotive:Brake cleaner and lubricant sprays require chemical-resistant linings compatible with petroleum distillate propellants. Dubai-based distributors consolidate procurement for GCC aftermarket channels, compressing specification influence to Johannesburg and Dubai trading hubs.
Cosmetics anchors current procurement volumes. Cleaning Agents are climbing the fastest.
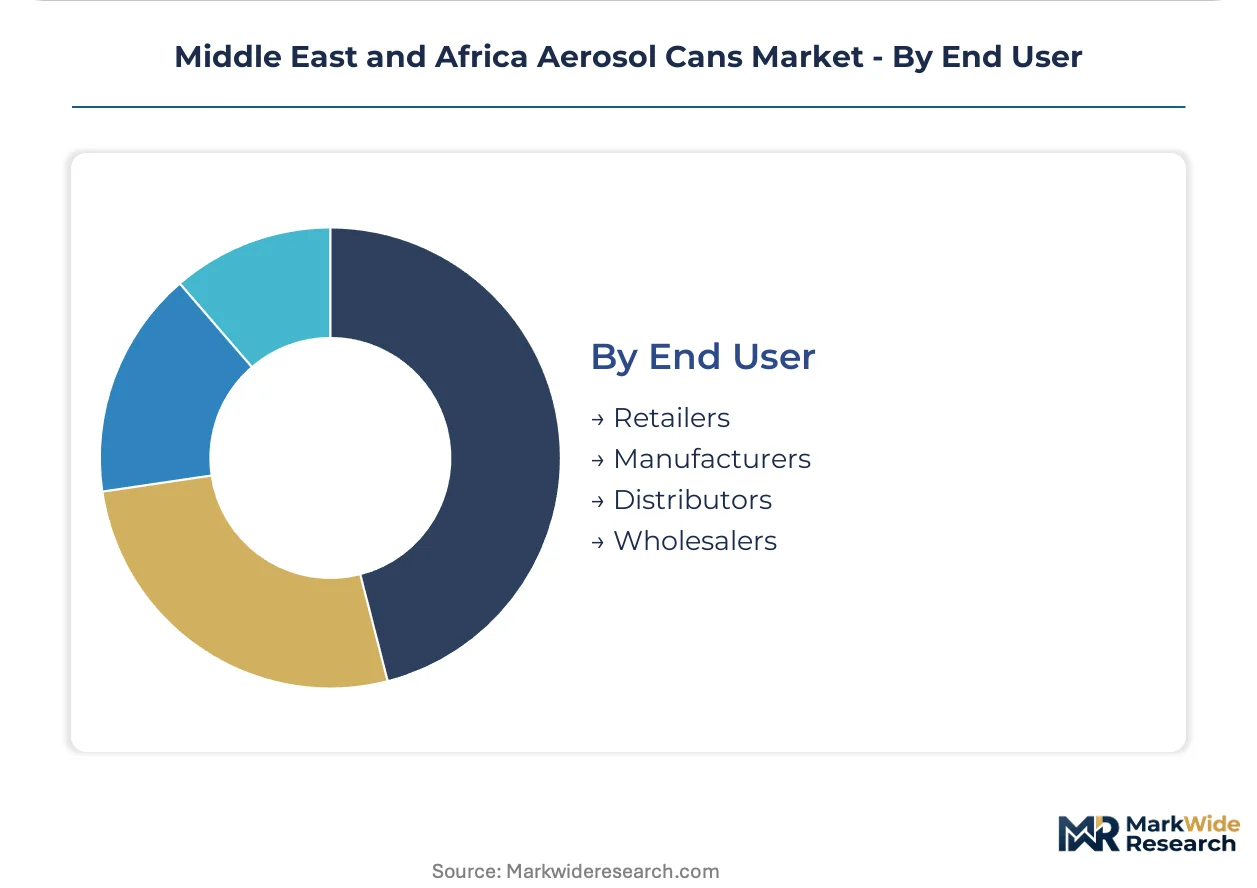
End User:
Channel position determines order scale, technical support expectations, and quality accountability structures.
- Retailers:Hypermarket chains in Cairo and Lagos unbundle after-sales support from container supply agreements, demanding direct manufacturer accountability rather than distributor intermediation. This pattern concentrates specification influence with multinational FMCG procurement teams.
- Manufacturers:Brand-owning filling operations in Saudi Arabia and South Africa specify can designs concurrent with formulation development, integrating pressure testing and lining compatibility into product launch timelines.
- Distributors:Regional trading houses stock standardized can formats for resale to smaller filling operations, absorbing inventory risk in exchange for margin compression.
- Wholesalers:Volume aggregators serving fragmented Nigerian and Egyptian retail networks prioritize price-competitive steel formats over aluminum premium positioning.
Manufacturers retain specification control. Retailers are gaining procurement leverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SASO standards anchor regional compliance architecture, filtering market access across Gulf manufacturing zones and compressing certification timelines for metal packaging suppliers serving personal care and household segments.
Saudi Arabia
Jeddah and Dammam industrial corridors concentrate aluminum aerosol production for domestic personal care brands and GCC export channels. SASO pressure vessel regulations mandate Arabic-language hazard labeling and material thickness minimums that filter non-compliant Southeast Asian imports. Crown Holdings Inc. operates a manufacturing facility serving Saudi Arabia's domestic filling operations.
South Africa
Gauteng manufacturing belt hosts Unilever and Procter & Gamble filling operations specifying aluminum monobloc formats for deodorant and hair spray lines. NRCS compulsory specifications govern pressure testing protocols and coating compatibility standards. Nampak Ltd sustains supply relationships with multinational FMCG brands operating across Sub-Saharan Africa from its South African base.
Egypt
Cairo metropolitan corridor drives cleaning agent demand acceleration as aerosol disinfectants penetrate informal retail networks. EOS quality certifications create extended queues for dairy-contact surface approvals on food-grade aerosol formats. Local canners serving Gulf export markets face compressed product launch windows during Ramadan seasonal cycles.
Nigeria
Lagos industrial corridor anchors West African filling operations for price-competitive household segments. The country's petroleum regulator maintains tight liquefied petroleum gas derivative licensing controls, extending working capital cycles for local aerosol producers. Steel three-piece can formats dominate informal retail distribution networks.
Morocco
Can-Pack SA's North African production hub supplies tariff-advantaged aluminum formats to West African Economic and Monetary Union markets. Local filling capacity remains underdeveloped for personal care and household segments, creating procurement dependency on Moroccan converter relationships. Deep-drawn monobloc designs capture volume from legacy steel assemblers.
Middle East and Africa Aerosol Cans Market Competitive Landscape
Pan-regional converters and national specialists split the market along compliance capability and geographic coverage vectors. Consolidation pressures concentrate among aluminum monobloc producers with deep-drawing technical capabilities, while steel three-piece assemblers face margin compression from Turkish and Indian mill import dependency. Two archetypes dominate: European-headquartered multinationals with Gulf certification infrastructure, and African-based regional suppliers with Sub-Saharan distribution relationships. Competitive moves center on SASO laboratory accreditation investments and Moroccan export platform utilization for West African market access.
Among European-headquartered fabricators, Can-Pack SA and Crown Holdings Inc. exemplify the compliance-anchored archetype, leveraging parent-company technical standards and Jeddah manufacturing presence to serve GCC personal care demand. Tecnocap SpA occupies a parallel position with Italian-origin metal packaging specialization. Nampak Ltd anchors the African-regional vector from its South African base, sustaining multinational FMCG supply relationships across Sub-Saharan markets without Gulf manufacturing footprint. Mauser Packaging Solutions and Ball Corporation represent North American-origin diversified packaging conglomerates with regional presence through distribution rather than dedicated Middle East and Africa production assets.
| Leading Market Players |
|---|
| Can-Pack SA |
| Mauser Packaging Solutions |
| Crown Holdings Inc. |
| Tecnocap SpA |
| Saudi Can Co. Ltd. |
| Ball Corporation |
| Nampak Ltd |
| Saudi Arabian Packaging Industry WLL (SAPIN) |
| CCL Industries |
| Others |
Supply & Pricing Matrix
Jeddah-Dammam freight corridors channel aluminum billet imports from European smelters, concentrating inbound logistics costs on Gulf converters and compressing margin buffers for non-integrated producers serving price-sensitive Nigerian distributors. This corridor dynamic amplifies cost differentiation between SASO-certified regional suppliers and import-dependent filling operations.
Pricing Analysis
The customization-premium spread separates deep-drawn aluminum monobloc formats from standard steel three-piece assemblies, with epoxy-lining specification and Arabic-label compliance commanding substantial uplifts. Price differentiation rests on certification grade and volume scale, with household segment buyers in Lagos informal retail networks exhibiting acute price sensitivity while Saudi personal care brands absorb premium positioning for fragrance stability. Cost compression in steel formats is intensifying because Turkish mill import dependency exposes converters to lira depreciation cycles.
Supply Chain Analysis
Tariff exposure between Morocco and West African Economic and Monetary Union markets dominates supply chain risk calculus for regional converters. Primary aluminum feeds from South African and European smelters, while flat-rolled steel draws from Turkish and Indian mills. Single-source vulnerability in coating chemist expertise forces reliance on European epoxy system imports. Distribution runs through Dubai and Johannesburg trading hubs that consolidate procurement for multinational FMCG procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as hydrocarbon propellant migration and urban hygiene campaigns penetrate informal retail networks across Cairo and Lagos metropolitan corridors.
For Market Incumbents: Pre-empt coating chemist scarcity by anchoring technical service capabilities in Jeddah and Gauteng manufacturing belts before European suppliers consolidate regional formulation control. Invest in SASO laboratory accreditation to compress certification queues that currently extend beyond Ramadan seasonal launch windows. Crown Holdings and Can-Pack SA should deepen backward integration into aluminum billet casting to buffer margin volatility from LME price swings. For New Entrants and Emerging Players: Build out Moroccan export platform relationships to capture tariff-advantaged access to underdeveloped West African filling capacity for personal care and household segments. Target Nigerian LPG derivative licensing navigation as a differentiated service offering for Lagos-based aerosol producers facing petroleum regulator clearance delays. Establish direct quality accountability contracts with Cairo hypermarket chains that are unbundling distributor intermediation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underutilized Middle East and Africa aerosol assets and weak Gulf certification infrastructure. Long-term viability hinges on aluminum collection infrastructure positioning ahead of draft GCC extended producer responsibility implementation. Watch for SASO laboratory queue length compression as an inflection signal indicating regulatory capacity expansion and accelerated product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Laboratory Accreditation Investment | Jeddah and Dammam testing relationships filter market access for personal care brands. |
| Moroccan Export Platform Utilization | Can-Pack SA's hub captures West African Economic and Monetary Union volume from steel assemblers. |
| Aluminum Collection Infrastructure Buildout | Early positioning captures compliance premiums from multinational brand scope 3 targets. |
| Direct-to-Hypermarket Quality Contracts | Cairo and Lagos chains demand manufacturer accountability bypassing distributor intermediation. |
| Hydrocarbon Propellant Formulation Migration | Egypt's EOS environmental certification pathways reduce import barriers for European formulations. |
Research Methodology
The analysis maps personal care, household, food, and industrial aerosol segments, each validated through filling line engineers, coating specification chemists, hypermarket procurement managers, and petroleum regulator licensing officers. Primary interview insights triangulate with customs/trade data, SASO technical regulation filings, SEC 10-K disclosures from packaging conglomerates, and aluminum smelter offtake announcements. Bottom-up volume builds from identified filling operations across Jeddah, Gauteng, Cairo, and Lagos corridors reconcile with top-down material flow estimates.
Assumptions hold SASO standard harmonization trajectory, propellant technology migration pace, and urban hygiene campaign penetration rates within observed patterns across the analysis window. Segmentation dimensions include material type, application use case, pressure vessel specification, and regional regulatory cluster. CAGRs derive from trend extrapolation of filling line capacity additions, import license issuance rates, and retail channel modernization indices. Model inputs incorporate aluminum ingot price volatility bands and coating system lead time distributions.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by European-headquartered multinationals or rapid GCC extended producer responsibility implementation would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Bottles Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Non-Corrugated Boxes Market