
 Double Seam Bowl Market | 2026-2036
Double Seam Bowl Market Size, Share, and Industry Trends Forecast 2026-2036
Double Seam Bowl Market Foresight
Foodservice distribution is fragmenting as regional co-packers and direct-to-processor channels erode the dominance of traditional broadline distributors. Silgan Holdings Inc. leverages its captive container manufacturing network to secure long-term supply agreements with national brands. Ball Corporation anchors North American volume through its integrated aluminum sheet-to-bowl operations. Crown Holdings competes on lightweighting technology, sustaining margin advantages in beverage-adjacent food packaging conversions.
A double seam bowl is a rigid metal container formed from steel or aluminum sheet, joined by interlocking five-layer seams created through rolling and compression dies, designed to achieve hermetic sealing for thermal-processed or shelf-stable contents. The double seam structure withstands internal vacuum or pressure differentials during retort sterilization, making it essential for ready meals, pet foods, and nutritional products. Steel and aluminum material types dominate commercial volume, with aluminum capturing faster growth due to its superior recyclability profile under EU Packaging and Packaging Waste Regulation targets. Catering and restaurant applications lead absolute demand, while industrial-scale food processing drives the largest per-account contract values and longest equipment lock-in cycles.
The FDA enforces 21 CFR Part 113 regulations for low-acid canned foods, mandating hermetic seal validation that directly specifies double seam dimensional tolerances and testing protocols. EPA hazardous waste rules and state-level extended producer responsibility frameworks in California and Oregon are reshaping post-consumer collection infrastructure for steel and aluminum bowl recovery. Ball Corporation and Crown Holdings both maintain dedicated regulatory affairs teams focused on preemptive compliance with anticipated state-level packaging fee structures. Stakeholders must monitor whether proposed federal packaging fee legislation accelerates converter consolidation or spurs captive recycling investments among large food processors.
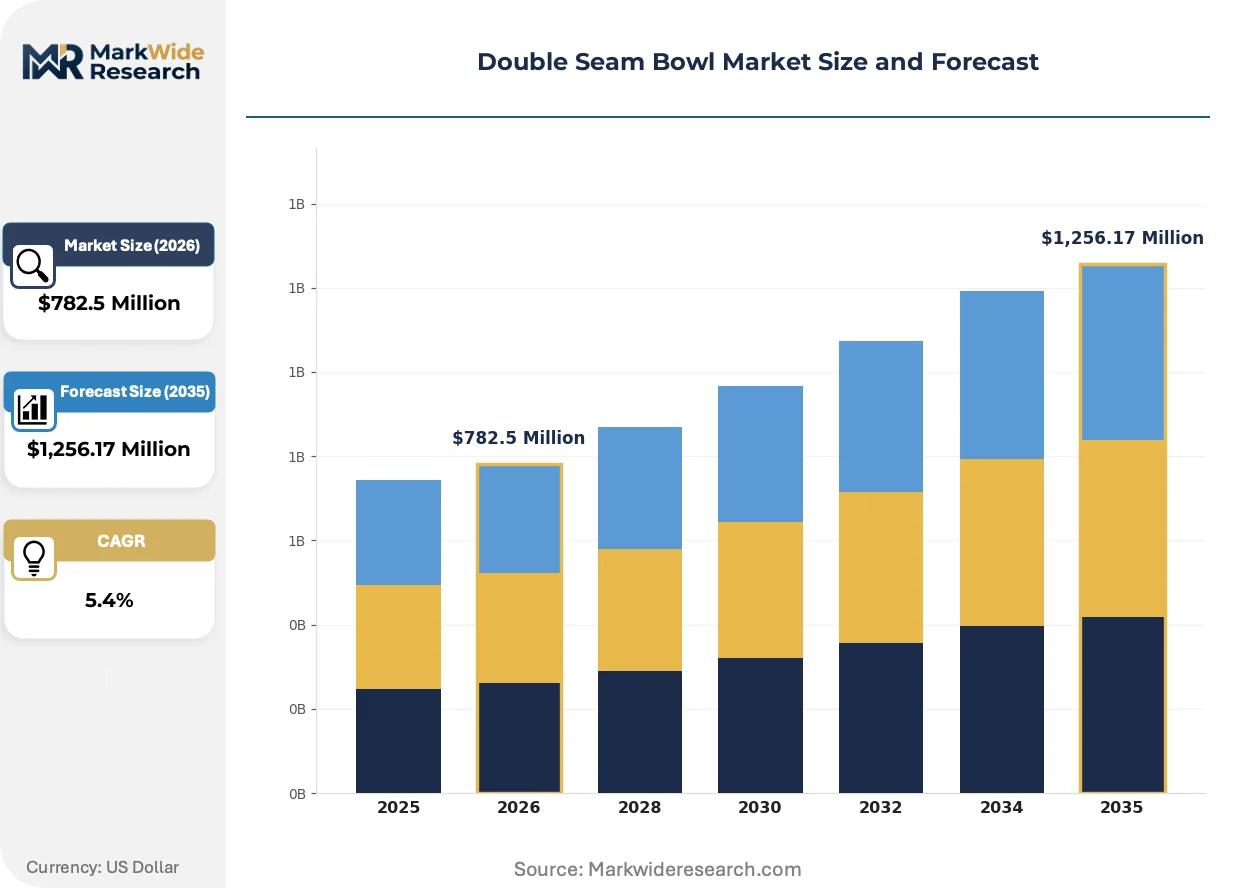
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing converter margins while forcing rapid material transitions toward mono-material aluminum designs, fundamentally restructuring supplier-processor power dynamics across European ready-meal supply chains.
Growth Catalysts
- Retort sterilization compatibility:Double seam bowls withstand extreme pressure differentials during thermal processing, making them irreplaceable for shelf-stable prepared foods and nutritional products requiring extended ambient storage.
- EU material recovery targets:The EU Packaging and Packaging Waste Regulation's tightening recovery thresholds accelerate aluminum adoption due to its established closed-loop recycling infrastructure versus multi-layer alternatives.
- Germany premium food processing concentration:German food processors favor hermetic sealing for high-margin prepared foods, creating concentrated demand pull for advanced double seam specifications.
Market Restraints
- Aluminum sheet price volatility:Input cost swings for primary aluminum directly compress converter margins, with limited pass-through power against locked long-term supply agreements with national brands.
- Equipment lock-in cycles:Industrial-scale food processing customers face 10-15 year capital equipment cycles, slowing adoption of next-generation lightweighting technologies and seam inspection systems.
- Flexible pouch substitution:Retortable flexible packaging captures share in lower-acid, shorter-shelf-life applications where hermetic metal containment offers marginal functional advantage.
Strategic Opportunities
- Mono-material steel innovation:Advanced coating technologies enable full steel bowl recyclability without polymer barrier layers, aligning with EU Green Deal circular economy objectives.
- Direct-to-processor channels:Regional co-packers bypass traditional broadline distributors, offering converters shorter sales cycles and higher-margin custom specification contracts.
- Pet food premiumization:Human-grade pet food processors adopt double seam bowls for wet food lines, replicating ready-meal shelf stability standards in adjacent categories.
Industry Challenges
- Seam inspection technician scarcity:Specialized expertise in double seam dimensional validation and teardown analysis faces generational attrition, constraining quality assurance scaling.
- 21 CFR Part 113 compliance documentation:FDA low-acid canned food regulations demand extensive hermetic seal validation records, extending new product qualification timelines.
- Legacy retort infrastructure retrofit costs:Existing sterilization equipment requires costly modification to handle next-generation lightweight bowl geometries without deformation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Seam Bowl Market |
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,256.17 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Plastic, Wood Application: Catering, Home Use, Restaurant, Industrial Size: Small, Medium, Large, Extra Large Design Style: Modern, Vintage, Minimalist, Decorative |
| Companies Covered | Silgan Holdings Inc., Truitt Bros. Inc., Golden-Tech International, Inc., Silgan Containers, Rieke Packaging Systems, Aagard Group, Le Creuset, Ball Corporation, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Seam Bowl Market Shifts & Advancements
Active developments across material science, regulatory compliance architecture, and procurement systems are compressing traditional competitive advantages and opening asymmetric opportunities for technology-forward converters.
Digital seam inspection systems integrating machine vision and real-time dimensional feedback are rendering obsolete manual teardown sampling protocols. Ready-to-eat meal manufacturers deploying these systems achieve 100% lot coverage versus statistical sampling, compressing quality assurance labor costs while satisfying retailer traceability mandates. The technology is rendering obsolete traditional third-party laboratory validation dependencies.
REACH substance restriction expansions are accelerating substitution of epoxy-based internal coatings with polyester and oleoresin alternatives across European converter operations. The industrial consequence is reformulation R&D concentration among coating suppliers with EU-established regulatory affairs capabilities. Wet pet food processors face the most acute compliance timeline pressure, with reformulation qualification cycles extending 18-24 months.
Consolidated food processors are unbundling after-sales technical service from equipment supply contracts, creating standalone seam troubleshooting and training revenue streams. Regional co-packers lacking in-house metallurgical expertise purchase these services on subscription, displacing traditional distributor technical support models. This pattern concentrates in Germany and Benelux, where mid-sized processors dominate premium prepared food manufacturing.
Double Seam Bowl Market Segmentation
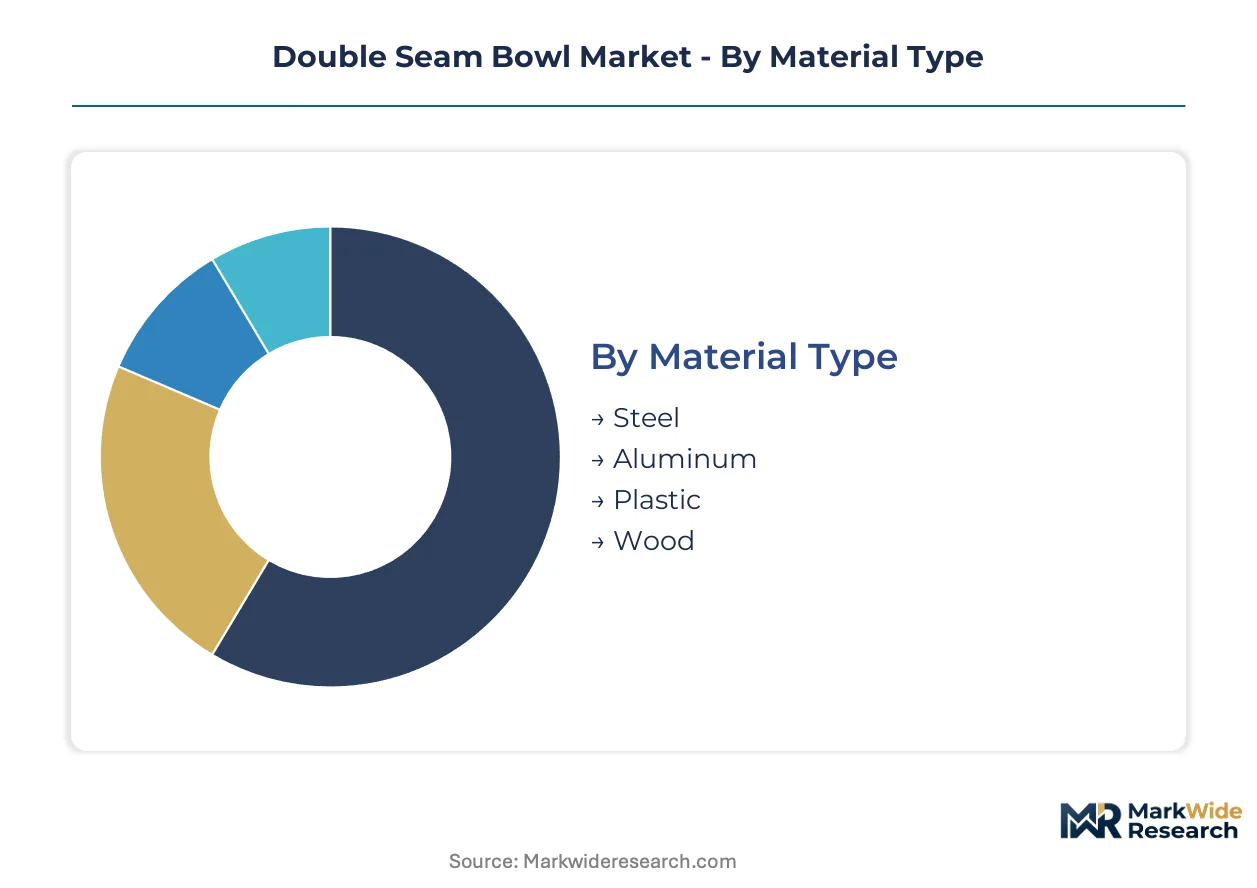
Segmentation in the double seam bowl market reveals how material science, end-use requirements, and design specifications create distinct competitive arenas. Converters must align production capabilities with the technical demands of each segment while navigating divergent regulatory pressures across material categories.
Material Type:
Cost tier differentiation separates commodity-grade inputs from premium recyclable substrates, with regulatory compliance costs reshaping margin structures across the stack.
- Steel:Cold-rolled tinplate and TFS substrates deliver structural rigidity for high-pressure retort applications. German food processors specify steel for premium prepared foods requiring extended shelf stability, though REACH substance restrictions on internal coatings extend reformulation cycles.
- Aluminum:Drawn aluminum sheet offers superior strength-to-weight ratios and established closed-loop recycling infrastructure under EU Packaging and Packaging Waste Regulation targets. Demand concentrates in ready-to-eat meal packaging where lightweighting reduces logistics costs.
- Plastic:Multi-layer polymer constructions serve niche applications requiring microwave compatibility, though limited recyclability constrains adoption under tightening EPR frameworks.
- Wood:Laminated wood composites address specialty gift and promotional segments, lacking hermetic sealing capability for thermal-processed contents.
Steel holds installed capacity. Aluminum is rotating up the share rankings.
Application:
End-use functional requirements dictate seam specification tolerances, with industrial-scale processing demanding the tightest dimensional validation protocols.
- Catering:High-volume institutional foodservice relies on standardized bowl geometries for automated filling lines, with hermetic sealing ensuring safe holding temperatures across distribution networks.
- Restaurant:Premium independent operators and chain concepts specify custom-printed double seam bowls for branded takeout programs, prioritizing visual differentiation over unit cost minimization.
- Home Use:Retail-packaged ready meals drive consumer-facing design requirements including easy-open features and resealability adaptations.
- Industrial:Contract manufacturers and co-packers operate the longest equipment lock-in cycles, creating captive relationships with converters capable of dedicated technical service support.
Industrial commands contract value concentration. Catering is climbing the fastest in absolute volume terms.
Size:
Volume throughput and retort basket optimization create economies of scale that favor standardized dimension sets over custom specifications.
- Small:Single-serve portions for nutritional supplements and pediatric nutrition require precision forming to maintain seam integrity at reduced wall thicknesses.
- Medium:Standard ready-meal portions dominate commercial throughput, with retort equipment calibrated to this dimension range across European processing facilities.
- Large:Family-size formats for ethnic cuisine and stewed products face higher deformation risk during thermal processing, demanding reinforced seam geometries.
- Extra Large:Institutional bulk formats serve catering and foodservice redistribution, with limited SKU proliferation constraining converter tooling investments.
Medium holds baseline capacity utilization. Small is gaining share fastest in premium nutrition segments.
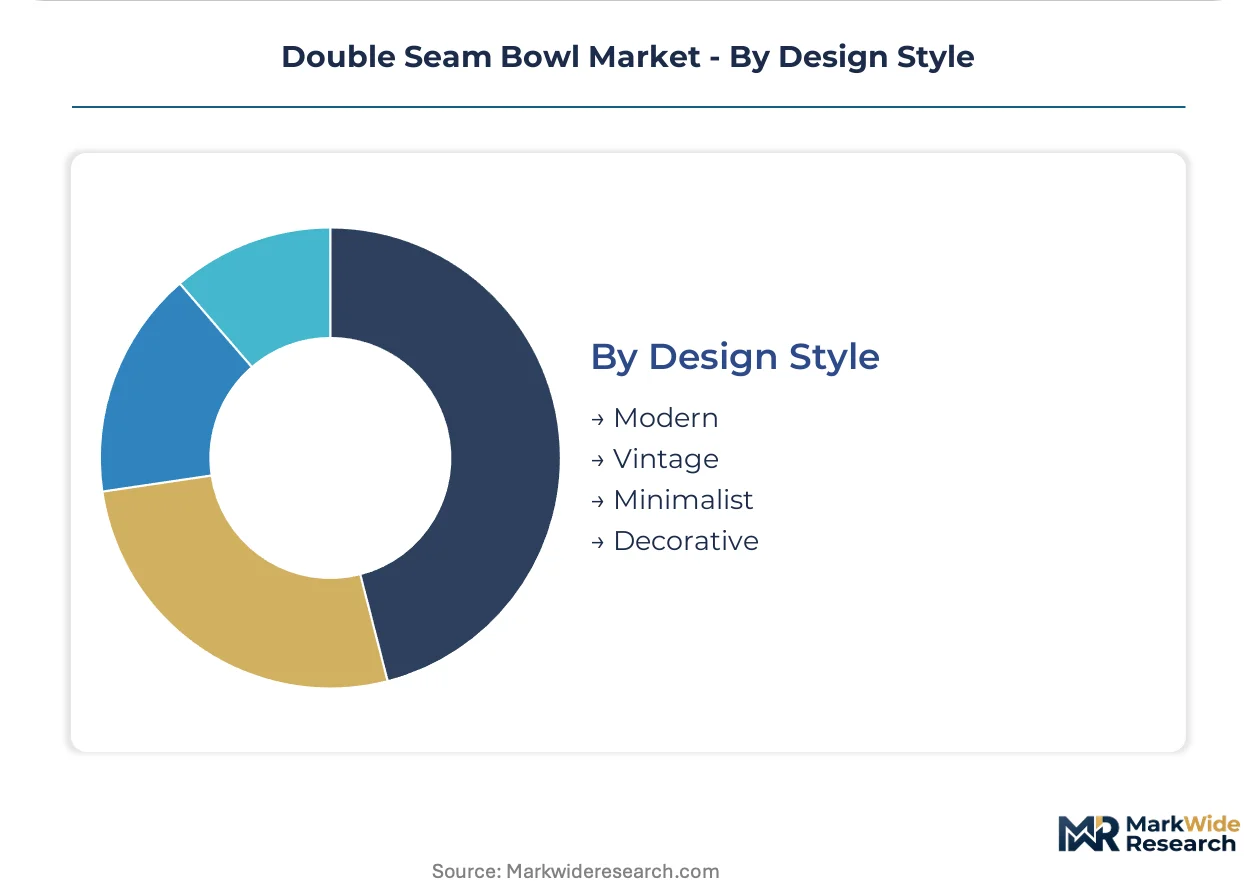
Design Style:
Customer type stratification between private-label retailers and branded manufacturers determines design investment thresholds and print technology requirements.
- Modern:Clean lines and matte finishes align with contemporary ready-meal branding, requiring advanced lithographic coating systems for tonal precision.
- Vintage:Embossed logos and heritage color palettes serve artisanal food positioning, with higher tooling costs amortized across smaller production runs.
- Minimalist:Reduced graphic elements and substrate-forward aesthetics appeal to sustainability-positioned brands, emphasizing material quality over decorative complexity.
- Decorative:Full-bleed imagery and specialty varnishes support seasonal and promotional programs, with shorter lead times demanding flexible converter scheduling.
Modern holds design standardization. Minimalist is rotating up the share rankings amid regulatory pressure on packaging minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European metal packaging logistics, connecting North Sea shipping lanes to the Ruhr industrial corridor's steel and aluminum processing infrastructure.
Germany
German food processors drive premium ready-meal demand requiring hermetic sealing specifications. The EU Packaging and Packaging Waste Regulation mandates aluminum recovery rates that favor mono-material bowl designs. The Stuttgart-Munich corridor concentrates converter technical service operations serving mid-sized prepared food manufacturers.
United States
Retort sterilization infrastructure for shelf-stable pet foods and nutritional products sustains steel bowl demand. FDA 21 CFR Part 113 enforcement mandates hermetic seal validation protocols that lock in double seam specifications. Chicago's food processing belt hosts the densest concentration of industrial-scale co-packers purchasing custom bowl contracts.
China
Domestic ready-to-eat meal manufacturers expand aluminum bowl adoption for export-compliant packaging. GB standards for food contact materials align with EU regulatory benchmarks to maintain market access. The Yangtze River Delta cluster integrates sheet metal forming with coastal export logistics for Southeast Asian food brands.
Japan
Premium convenience store chains specify lightweight aluminum bowls for ambient single-serve meals. METI circular economy guidelines accelerate closed-loop aluminum recovery investments. The Osaka-Kobe manufacturing zone retains specialized retort equipment calibration expertise for thin-wall bowl geometries.
India
Contract manufacturers for international pet food brands import double seam specifications to meet export quality standards. FSSAI packaging safety notifications tighten migration testing for internal coating systems. The Mumbai-Pune industrial corridor develops steel bowl capacity serving Gulf Cooperation Council export markets.
Double Seam Bowl Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The double seam bowl market exhibits consolidated converter capacity with three multinational metal packaging groups controlling integrated sheet-to-bowl operations. Strategic archetypes separate captive container manufacturers securing long-term supply agreements, independent converters competing on lightweighting technology, and regional specialists serving co-packer channels. Dominant competitive moves include backward integration into aluminum sheet production and geographic expansion through dedicated technical service hubs.
Among North American metal packaging groups, Silgan Holdings Inc., Ball Corporation, and Crown Holdings exemplify distinct strategic positions. Silgan Holdings Inc. anchors the captive supply archetype through container manufacturing networks. Ball Corporation occupies the integrated aluminum processing tier with sheet-to-bowl operations. Crown Holdings represents lightweighting technology specialization serving beverage-adjacent food packaging conversions. These three entities collectively illustrate how scale, integration depth, and technical differentiation segment competitive positioning across national brand supply chains.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Truitt Bros. Inc. |
| Golden-Tech International, Inc. |
| Silgan Containers |
| Rieke Packaging Systems |
| Aagard Group |
| Le Creuset |
| Ball Corporation |
| Crown Holdings |
| Others |
Supply & Pricing Matrix
Ruhr industrial corridor steel and aluminum sheet concentration feeds directly into converter margin pools downstream, with German metal processors capturing value through captive supply relationships with ready-meal manufacturers facing EU Packaging and Packaging Waste Regulation compliance costs.
Pricing Analysis
Volume-discount tiering separates national brand long-term supply agreements from spot-market transactions for regional co-packers. Pricing stratifies across premium hermetic specifications, standard retort-compatible grades, and economy single-use catering formats, with aluminum lightweighting premiums widening as logistics costs climb. Cost compression in standard steel grades intensifies because REACH coating reformulation expenses concentrate among mid-tier converters lacking R&D scale. Regional co-packers exhibit highest price sensitivity due to thin operating margins, while premium pet food processors show least sensitivity given human-grade positioning requirements.
Supply Chain Analysis
Export-control restrictions on advanced rolling mill technology limit equipment flows from Germany and Japan to emerging market converters, constraining capacity expansion outside established manufacturing zones. Raw material sourcing draws from Chinese primary aluminum, Russian steel slab, and domestic European scrap recovery networks. Single-source vulnerability concentrates in specialized seam inspection equipment where German and Japanese suppliers dominate. Distribution runs through Port of Hamburg container terminals connecting Ruhr processing infrastructure to North Sea shipping lanes serving ready-meal manufacturers across Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
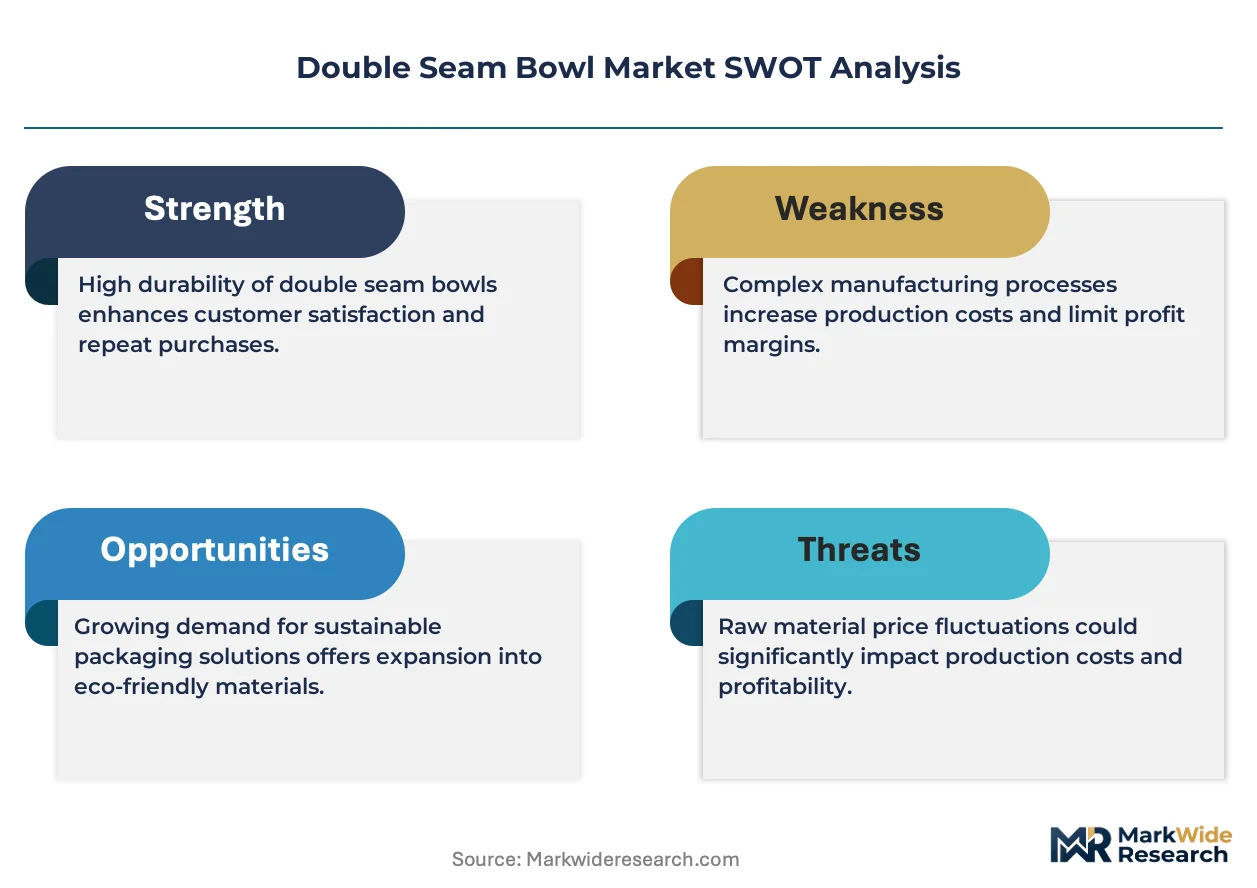
The double seam bowl market is entering a cyclical recovery phase as retort sterilization infrastructure investment rebounds following pandemic-era capital expenditure deferrals, with food processors rebuilding safety stock positions.
For Market Incumbents: Pre-empt flexible pouch substitution threats by accelerating mono-material aluminum lightweighting programs that maintain hermetic performance at reduced material intensity. Deepen backward integration into aluminum sheet production to secure margin control against LME price volatility. Lock regional co-packer channels through dedicated technical service subscriptions that replicate Silgan Holdings Inc.'s captive supply archetype.
For New Entrants and Emerging Players: Pursue wet pet food premiumization segments where human-grade positioning commands specification tolerance and brand loyalty remains undeveloped. Target mid-sized German prepared food manufacturers in the Stuttgart-Munich corridor lacking in-house metallurgical expertise. Lead with digital seam inspection system integration as a bundled service offering that displaces traditional third-party laboratory dependencies.
For Investors and Strategic Acquirers: Capital is best deployed toward coating technology specialists possessing EU-established regulatory affairs capabilities and REACH-compliant polyester or oleoresin formulation portfolios. The five-to-ten year viability window favors converters with demonstrated lightweighting R&D pipelines and established technical service revenue streams. Monitor EU Packaging and Packaging Waste Regulation enforcement intensity as the inflection signal determining aluminum versus steel material transition speed.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Aluminum Transition | Aligns converter output with EU Packaging and Packaging Waste Regulation recovery targets for closed-loop recycling. |
| Digital Seam Inspection Deployment | Replaces manual teardown sampling with machine vision systems satisfying retailer traceability mandates at reduced labor cost. |
| Technical Service Unbundling | Creates standalone subscription revenue from regional co-packers lacking in-house metallurgical expertise in Germany and Benelux. |
| Coating Reformulation Investment | Accelerates epoxy substitution with REACH-compliant polyester alternatives ahead of wet pet food compliance deadlines. |
| Direct-to-Processor Channel Development | Bypasses broadline distributors to capture higher-margin custom specification contracts with shorter sales cycles. |
Research Methodology
Desk research of trade association publications, customs records, and regulatory filings preceded structured interviews with converter operations managers, food processor procurement leads, retort equipment engineers, and coating supplier technical directors. Secondary validation drew from EU Packaging and Packaging Waste Regulation impact assessments, FDA 21 CFR Part 113 guidance documents, and aluminum industry association recycling statistics. Bottom-up capacity estimates triangulated against top-down demand projections from ready-meal and pet food production data.
Assumption sets held EU regulatory enforcement timelines and aluminum LME price bands fixed while varying retort infrastructure investment cycles and regional co-packer channel development rates across the projection horizon. Segmentation modeling incorporated material type, application, size tier, and design style dimensions with regional regulatory cluster overlays. CAGRs derived from historical volume trajectories adjusted for equipment lock-in cycle constraints and substitution elasticity parameters.
Macroeconomic conditions sit as an overlay; deviation in aluminum input costs, energy prices, or ocean freight rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption curves. Material shifts in EU Packaging and Packaging Waste Regulation material recovery thresholds or REACH substance restriction expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
VCI Bags Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Dosage Cups Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Assembly Trays Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Child Resistant Bottles Market