
 Tamper Evident Pots and Tubs Market | 2026-2036
Tamper Evident Pots and Tubs Market Size, Share, and Industry Trends Forecast 2026-2036
Tamper Evident Pots and Tubs Market Analytics
Digital printing and smart labeling integration is reconfiguring how tamper-evident features are authenticated across supply chains. Amcor leverages its global manufacturing footprint to sustain multi-material platform development. Berry Global Group anchors North American capacity through specialized injection-molded tub production. Sealed Air differentiates via active packaging systems that merge tamper evidence with shelf-life extension.
Tamper evident pots and tubs are sealed containers engineered with breakable bands, shrink sleeves, or induction-sealed membranes that visually indicate unauthorized access, typically manufactured through injection molding, thermoforming, or blow-molding processes with tolerances ensuring seal integrity under distribution stress. Their primary commercial purpose is to protect consumer safety, brand reputation, and regulatory compliance across packaged goods supply chains. Plastics dominates product type volume due to cost efficiency and design flexibility, though glass retains premium positioning in pharmaceutical applications where chemical inertness commands higher margin pools. Food Industry end users represent the largest installed base, while Pharmaceuticals is the fastest-growing segment as serialization and anti-counterfeiting regulations tighten closure specifications.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR traceability mandates are compelling pharmaceutical packagers to upgrade closure systems with integrated tamper evidence. The EU F-Gas Regulation and REACH chemical restrictions are additionally shaping material selection for plastic tub formulations, favoring mono-material recyclable designs. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and decide whether to prioritize recyclable mono-material platforms or multi-layer barrier performance.
Market Dynamics
Pharmaceutical serialization mandates and cold-chain integrity requirements are compressing specification cycles for tamper-evident closure systems, forcing converters to integrate track-and-trace layers directly into pot and tub designs.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers must implement tamper-evident features with unique device identification, driving specification upgrades across sterile packaging lines.
- Induction sealing technology:Pharmaceutical packagers are adopting membrane-based tamper evidence for liquid formulations, replacing traditional breakable bands in high-value cold-chain shipments.
- German pharmaceutical clusters:Concentration of contract packaging operations around Frankfurt and Hamburg is creating specification intensity that ripples across European supply chains.
Market Restraints
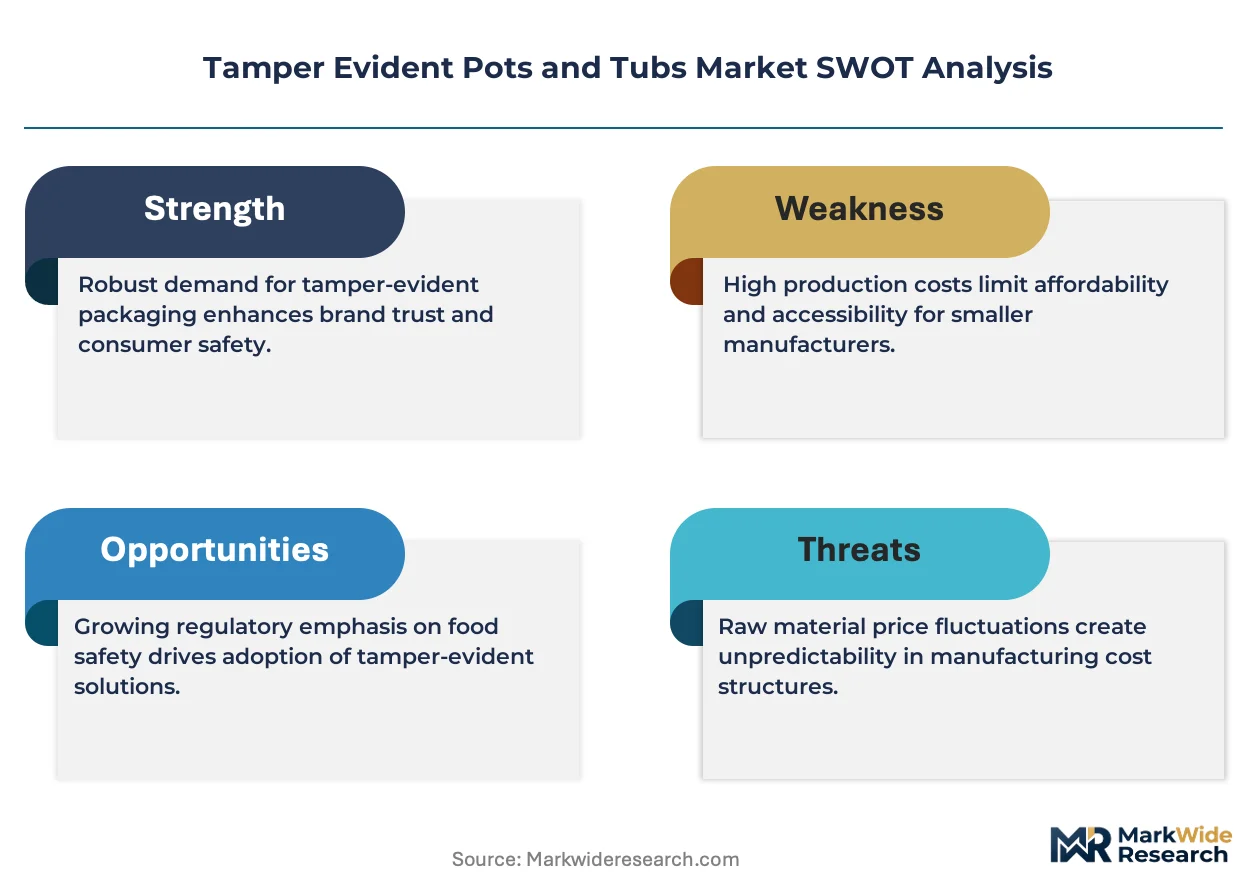
- Polypropylene resin volatility:Feedstock cost swings for injection-molded tubs compress converter margins and deter long-term capacity commitments.
- Multi-layer barrier incompatibility:Complex film structures required for oxygen-sensitive pharmaceuticals conflict with mono-material recyclability targets under EU EPR frameworks.
- REACH chemical restrictions:Phthalate and BPA limitations are forcing reformulation of seal adhesives and shrink sleeve inks, extending qualification timelines.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO serialization requirements for export-bound generics are creating demand for integrated tamper-evident and authentication packaging.
- Smart label convergence:NFC-enabled tamper-evident closures are hybridizing physical breakable bands with digital verification for high-value biologics.
- Direct-to-patient pharmacy channels:E-commerce pharmaceutical distribution is requiring child-resistant and tamper-evident combinations previously specified only for institutional settings.
Industry Challenges
- Serialization equipment integration:Pharmaceutical packagers face downtime risks when retrofitting tamper-evident lines with aggregation and verification hardware.
- Adhesive qualification timelines:FDA container closure integrity testing for new seal formulations extends validation cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamper Evident Pots and Tubs Market |
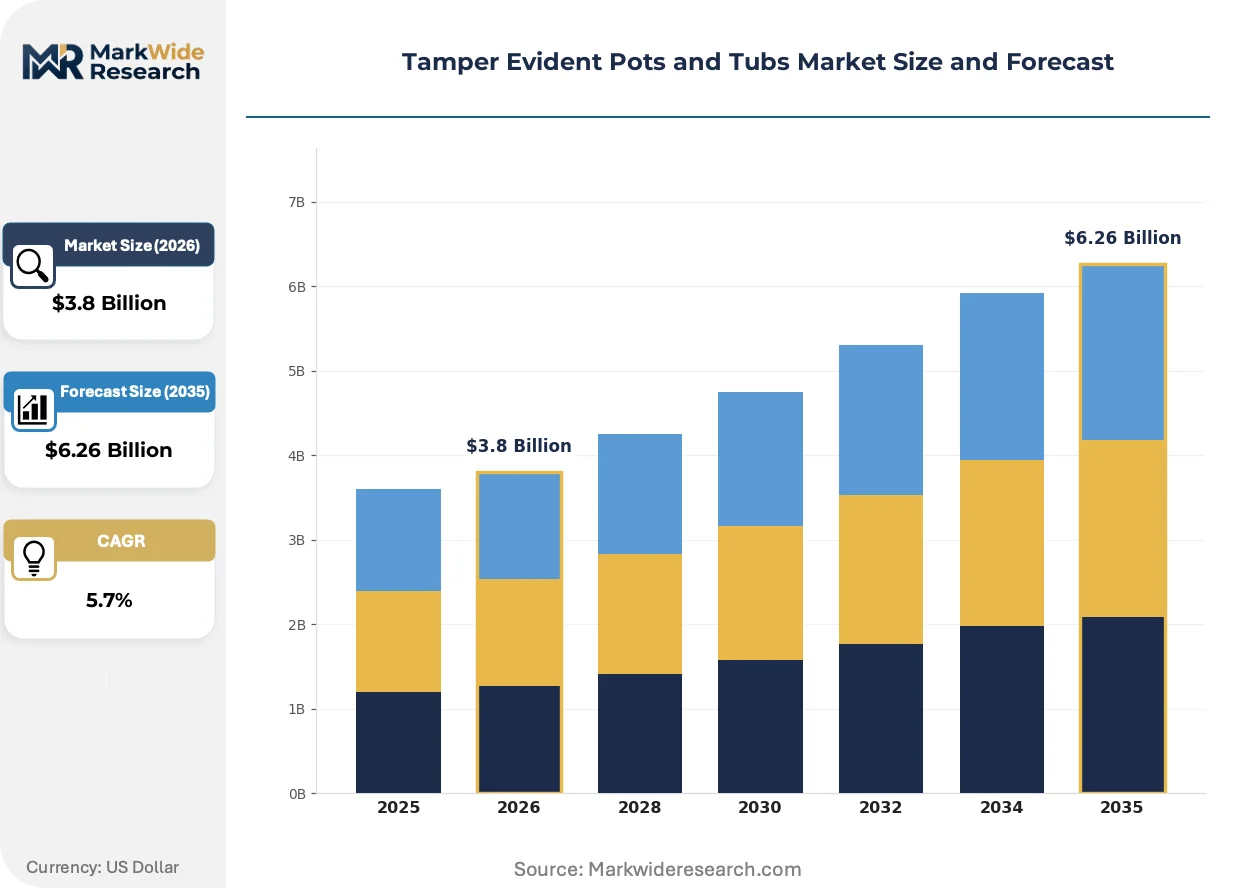
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Glass, Metal, Paperboard End User: Food Industry, Personal Care, Pharmaceuticals, Household Products Closure Type: Screw Cap, Snap-On, Induction Seal, Lift-Off Size: Small, Medium, Large, Jumbo |
| Companies Covered | Amcor, Berry Global Group, Sealed Air, ALPLA Group, CCL Industries, Coveris Holdings, Placon Corporation, WestRock Company, Huhtamaki Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamper Evident Pots and Tubs Market Evolving Landscape
Digital authentication layers are merging with physical tamper-evident mechanisms, creating hybrid closure systems that serve both regulatory compliance and brand protection objectives.
Mono-material polypropylene tubs with integrated breakable bands are hybridizing barrier performance with recyclability. Pharmaceutical packagers in Germany and Switzerland are specifying these platforms for oral solid dose products. The technology is compressing multi-layer alternatives out of premium positioning as EPR fees penalize complex structures.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are accelerating adoption of non-fluorinated barrier coatings for pharmaceutical tubs. converters are reformulating oxygen barrier layers to maintain shelf-life extension without per- and polyfluoroalkyl substances. Cold-chain biologics distribution is most affected, with packagers qualifying alternative barrier chemistries under accelerated stability protocols.
Consolidated buying by national pharmacy chains is compressing supplier rosters and demanding volume-scale price commitments from tamper-evident closure manufacturers. Regional distributors are losing share to direct manufacturer-to-wholesaler arrangements in the United States. Generic pharmaceutical procurement teams are driving this consolidation most aggressively, leveraging specification standardization across multiple dosage forms.
Tamper Evident Pots and Tubs Market Segmentation
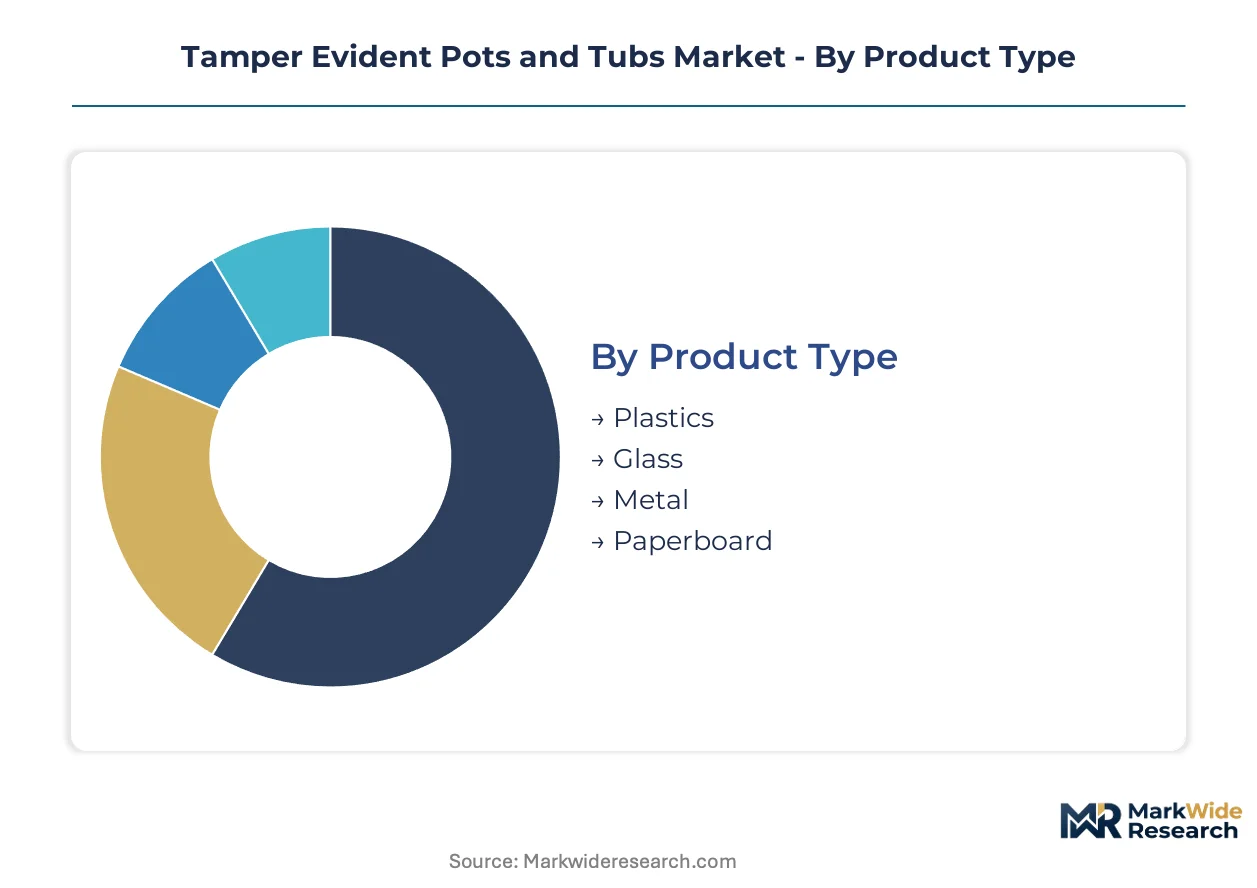
Segmentation in tamper-evident packaging determines specification intensity, with pharmaceutical and food safety regulations driving divergent material and closure requirements across end-use categories. Technical selection criteria vary sharply by product vulnerability, distribution temperature, and authentication needs.
Product Type:
After-sales service intensity concentrates around plastics due to mold maintenance, seal integrity validation, and recyclability compliance support demands from high-volume converters.
- Plastics:Polypropylene and polyethylene formulations dominate injection-molded tub production, with mono-material designs displacing multi-layer structures under EU Extended Producer Responsibility frameworks. German pharmaceutical packagers around Frankfurt specify these platforms for oral solid dose products where barrier performance must reconcile with recyclability mandates.
- Glass:Borosilicate and soda-lime compositions provide chemical inertness for parenteral formulations and high-value biologics. Swissmedic-regulated facilities in Basel and Swiss contract manufacturing clusters specify glass for cold-chain biologics where thermal stability and oxygen impermeability override cost considerations.
- Metal:Tinplate and aluminum tubs serve premium food and industrial applications requiring absolute light and oxygen exclusion.
- Paperboard:Fiber-based tubs with polymer barriers address dry goods and limited-moisture food segments where lightweighting drives logistics economics.
Plastics holds the largest share; momentum sits with glass as serialization requirements tighten.
End User:
Cost tier stratification separates institutional pharmaceutical procurement from retail food and personal care volume plays.
- Food Industry:Dairy, spreads, and ready-to-eat segments drive breakable band and shrink sleeve specifications for shelf-stable and refrigerated distribution. US national pharmacy chains consolidating buying power are compressing supplier rosters and demanding volume-scale commitments from closure manufacturers.
- Pharmaceuticals:FDA Drug Supply Chain Security Act and EU MDR traceability mandates compel integrated tamper-evident and authentication packaging for prescription and over-the-counter products. CDSCO serialization requirements for Indian export-bound generics are expanding addressable demand for hybrid physical-digital closure systems.
- Personal Care:Creams, lotions, and cosmetic formulations require moisture-barrier induction seals with premium aesthetic finishes.
- Household Products:Cleaning and chemical concentrates specify child-resistant tamper-evident combinations for safety-critical applications.
Food Industry maintains volume leadership; Pharmaceuticals climbs the fastest on regulatory compulsion.
Closure Type:
Application severity dictates specification, with liquid pharmaceuticals and cold-chain biologics demanding membrane-based integrity assurance over mechanical alternatives.
- Induction Seal:Aluminum-foil membrane systems bonded to container rims via electromagnetic heating provide hermetic tamper evidence for liquid pharmaceuticals. Packagers qualifying alternative barrier chemistries under accelerated stability protocols are displacing fluorinated coatings under EU F-Gas Regulation restrictions.
- Screw Cap:Threaded closures with integrated breakable bands serve solid dose and semi-solid formulations across food and pharmaceutical segments. Injection molders in North American capacity centers anchor production through specialized multi-cavity tooling for high-speed filling lines.
- Snap-On:Press-fit designs with audible engagement indicators address cost-sensitive food and household segments.
- Lift-Off:Friction-fit lids with tear-tab tamper evidence serve short-shelf-life dairy and deli applications.
Screw Cap dominates installed base; Induction Seal gains share fastest on pharmaceutical cold-chain expansion.
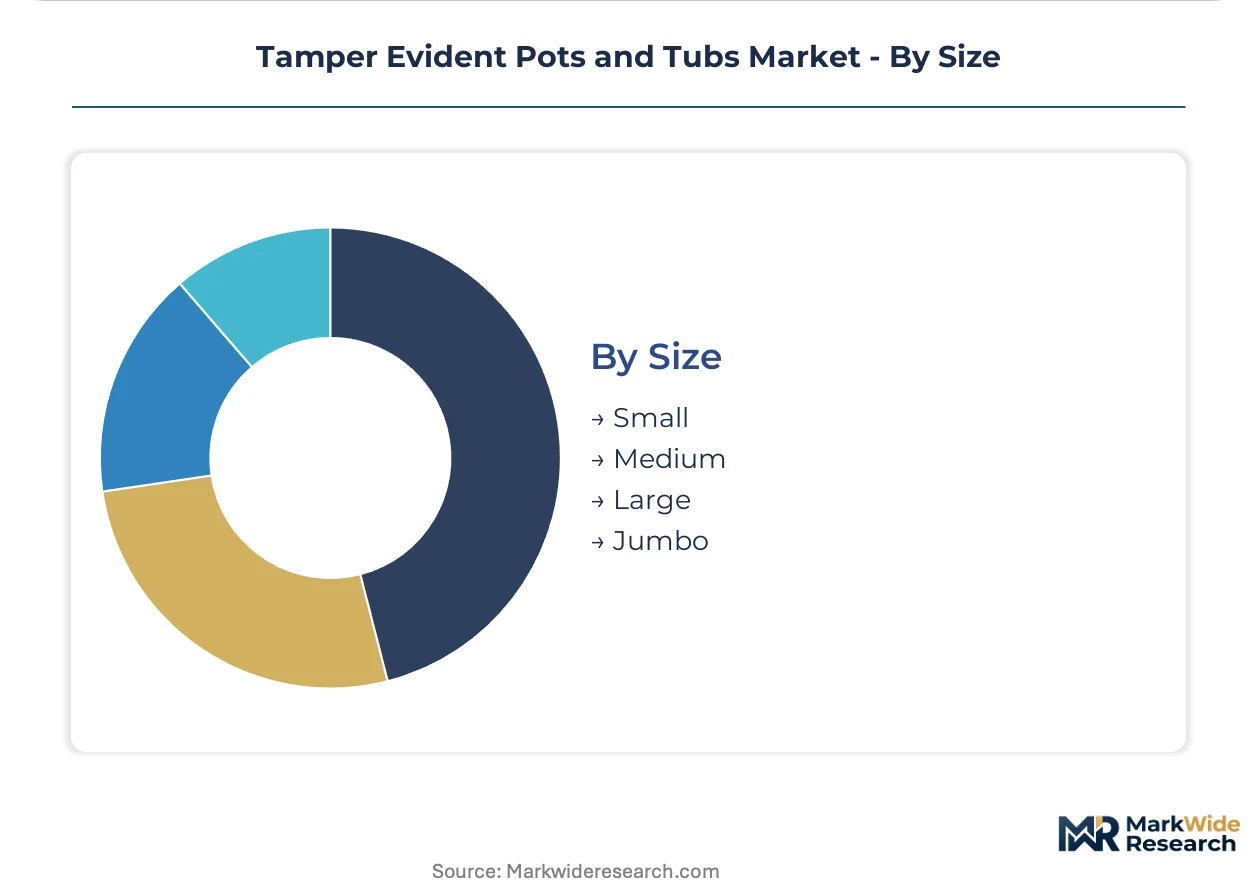
Size:
Volume concentration shapes supply chain configuration, with small-format pharmaceutical and personal care tubs commanding premium positioning against commodity large-format food containers.
- Small:Sub-100ml capacities serve unit-dose pharmaceuticals, travel-size personal care, and sample packaging where authentication features justify per-unit cost premiums.
- Medium:100-500ml range captures oral solid dose bottles, spread tubs, and cosmetic jars with the broadest converter equipment compatibility.
- Large:500ml-2L formats address institutional food service, pharmaceutical bulk packs, and household chemical concentrates.
- Jumbo:Above-2L capacities serve food service bulk, industrial chemical, and pharmaceutical active ingredient storage with specialized handling requirements.
Medium holds the largest share; Small shows steepest expansion trajectory on direct-to-patient pharmacy channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports pharmaceutical packaging to European and North American markets under tightening serialization mandates, while German contract manufacturers supply tamper-evident containers across EU cold-chain networks.
Germany
Frankfurt and Hamburg pharmaceutical packaging clusters drive specification intensity for oral solid dose and biologics containers. The EU MDR traceability mandates compel medical device manufacturers to implement tamper-evident features with unique device identification. Injection molders around these cities are qualifying mono-material polypropylene platforms that reconcile barrier performance with Extended Producer Responsibility recyclability targets.
United States
FDA Drug Supply Chain Security Act serialization requirements compress specification cycles for track-and-trace closure systems. National pharmacy chain consolidation demands volume-scale price commitments from closure manufacturers. Specialized injection-molding capacity centers anchor North American supply through multi-cavity tooling for high-speed pharmaceutical filling lines.
India
CDSCO serialization requirements for export-bound generics expand demand for integrated tamper-evident and authentication packaging. Pharmaceutical export growth to regulated markets drives specification alignment with FDA and EMA standards. Contract packaging operations in Gujarat and Maharashtra are upgrading induction sealing lines for cold-chain liquid formulations.
Switzerland
Swissmedic-regulated facilities in Basel specify glass tamper-evident containers for high-value biologics where thermal stability overrides cost. Cold-chain distribution networks require oxygen-impermeable closures with hermetic membrane seals. The country's precision manufacturing base supports qualification of alternative non-fluorinated barrier chemistries under accelerated stability protocols.
China
NMPA serialization mandates for domestic pharmaceutical distribution are tightening closure integrity requirements across sterile packaging lines. Dual carbon goals and plastic restriction policies favor mono-material recyclable designs over multi-layer barrier structures. Yangtze River Delta converters are developing integrated breakable band platforms for oral solid dose export markets.
Tamper Evident Pots and Tubs Market Competitive Landscape
On the supply side, the industry is moderately consolidated with global packaging conglomerates controlling premium pharmaceutical specifications while regional specialists serve food and household volume segments. Three strategic archetypes dominate: diversified material platforms with global manufacturing footprints, specialized injection-molding operations with regional density, and active packaging integrators combining tamper evidence with shelf-life extension. Competitive moves center on M&A to secure multi-material technology portfolios and capacity expansion in pharmaceutical cluster proximity.
Within the diversified packaging tier, Amcor leverages its global manufacturing footprint to sustain multi-material platform development across pharmaceutical and food segments. Berry Global Group anchors North American capacity through specialized injection-molded tub production with regional equipment compatibility. Sealed Air occupies a position merging tamper-evident physical mechanisms with active packaging systems for shelf-life extension in cold-chain biologics distribution.
| Leading Market Players |
|---|
| Amcor |
| Berry Global Group |
| Sealed Air |
| ALPLA Group |
| CCL Industries |
| Coveris Holdings |
| Placon Corporation |
| WestRock Company |
| Huhtamaki Group |
| Others |
Value Network & Pricing Analysis
Frankfurt's pharmaceutical packaging cluster anchors European capacity for induction-sealed tamper-evident tubs, with converter density there translating directly into pricing power over oral solid dose specifications. Polypropylene resin volatility and REACH-driven adhesive reformulation are compressing margins for regional specialists serving food and household segments, forcing tiered pricing stratification across certification levels.
Pricing Analysis
Current-generation mono-material polypropylene platforms command premium positioning against prior-generation multi-layer barrier structures as EU Extended Producer Responsibility fees penalize complex recyclability profiles. Three-tier pricing structure separates FDA-validated pharmaceutical-grade induction seals from standard food-industry breakable bands and economy household snap-on closures. Cost compression in commodity plastics is intensifying because of propylene feedstock swings, with generic pharmaceutical procurement teams exhibiting highest price sensitivity while Swiss biologics manufacturers show lowest elasticity due to cold-chain integrity requirements.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for converters qualifying non-fluorinated barrier coatings under accelerated stability protocols. Manufacturing concentrates in Germany, China, and the United States, with injection molders in the Yangtze River Delta and North American capacity centers feeding pharmaceutical clusters in Basel and New Jersey. Raw material dependencies rest on polypropylene resin, aluminum foil membranes, and specialized seal adhesives. Distribution runs through direct manufacturer-to-wholesaler arrangements as national pharmacy chain consolidation eliminates regional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tamper-evident packaging sits in early-cycle expansion as pharmaceutical serialization mandates penetrate export markets beyond regulated jurisdictions, with Indian contract manufacturers now upgrading lines for CDSCO-compliant export specifications previously required only for FDA and EMA destinations.
For Market Incumbents: Pre-empt margin erosion in commodity plastics by securing backward integration into polypropylene compounding and qualifying mono-material platforms ahead of EU F-Gas Regulation enforcement. Anchor capacity expansion within 200 kilometers of Frankfurt and Hamburg pharmaceutical clusters to capture specification intensity ripple effects across European cold-chain networks. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical export packaging by aligning induction sealing lines with CDSCO serialization requirements for generics bound for regulated markets. Target Gujarat and Maharashtra contract packaging operations upgrading from basic breakable bands to integrated tamper-evident and authentication systems, leveraging equipment financing partnerships as entry mechanism. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized injection molders with captive pharmaceutical validation capabilities and multi-cavity tooling for high-speed filling lines. Five-to-ten year viability favors acquisition targets combining mono-material platform expertise with active packaging integration for shelf-life extension. Watch for inflection when national pharmacy chains consolidate supplier rosters below five qualified vendors per closure category.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Development | Aligns polypropylene tub production with EU Extended Producer Responsibility recyclability targets and F-Gas Regulation compliance. |
| Induction Sealing Line Upgrades | Enables pharmaceutical packagers to replace breakable bands with hermetic membrane seals for cold-chain liquid formulations. |
| Smart Label Convergence | Hybridizes NFC-enabled closures with physical tamper evidence for high-value biologics authentication requirements. |
| Pharmaceutical Cluster Proximity Expansion | Positions converters within specification influence radius of Frankfurt, Hamburg, and Basel packaging decision centers. |
| Non-Fluorinated Barrier Qualification | Replaces per- and polyfluoroalkyl substances with alternative chemistries under accelerated stability protocols for oxygen-sensitive pharmaceuticals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging engineers, contract manufacturing procurement leads, injection molding plant managers, and cold-chain logistics coordinators. Secondary validation drew from FDA Drug Supply Chain Security Act guidance documents, EMA serialization implementation reports, EU F-Gas Regulation compliance databases, and customs trade data for polypropylene resin flows. Bottom-up capacity assessments at converter facilities were triangulated against top-down demand modeling from pharmaceutical dosage form production statistics.
Calibration anchored volume projections to observed qualification timelines for new seal formulations under FDA container closure integrity testing protocols. Segmentation dimensions modeled include product material type, end-use industry vertical, closure mechanism technology, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical adoption curves for comparable packaging integrity technologies, with inputs weighted toward pharmaceutical cold-chain expansion rates and EPR framework implementation schedules.
Sensitivities concentrate around polypropylene resin price volatility, REACH chemical restriction expansion timelines, and pharmaceutical serialization mandate enforcement intensity in export markets. Forecasts embed assumptions regarding qualification cycle durations and regulatory alignment across jurisdictions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Cluster Packaging Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Telescope Box Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Bottles Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Slide Tray Box Market