
 Otorhinolaryngology Devices Market | 2026-2036
Otorhinolaryngology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Otorhinolaryngology Devices Market Outlook
Market Context
German precision instrument manufacturing is decoupling from generic Asian assembly lines for high-end ENT visualization systems. Olympus Corporation leverages its surgical endoscopy heritage to dominate complex sinus procedure workflows. Cochlear Ltd. anchors the implantable hearing solutions segment through sustained R&D intensity in electrode array miniaturization. Medtronic plc navigates diversified ENT portfolios across powered instruments and intraoperative navigation.
Technical Definition and Segment Structure
Otorhinolaryngology devices encompass diagnostic, surgical, and therapeutic instruments engineered for ear, nose, and throat interventions, typically incorporating optical fiber bundles with 0-120 degree viewing angles, titanium-alloy construction, or biocompatible silicone implant substrates to restore function or enable tissue visualization. Nasal endoscopes and sinus implants capture margin concentration due to procedural volume expansion in ambulatory settings, while audiometers represent a mature replacement-driven category with limited growth elasticity. Robotic-assisted surgery and 3D imaging technologies are displacing conventional approaches in tertiary hospitals, though telemedicine solutions face reimbursement fragmentation across payer systems.
Regulatory Frame and Outlook
The EU MDR and FDA 510(k) pathways impose divergent clinical evidence requirements on sinus implant biocompatibility and active implantable hearing devices, directly shaping product development timelines and market access costs. Japan's PMDA and METI coordinate reimbursement classifications that determine commercial viability for novel ENT robotics. Stakeholders must monitor evolving software-as-medical-device classifications for AI-enabled diagnostic platforms.
Market Dynamics
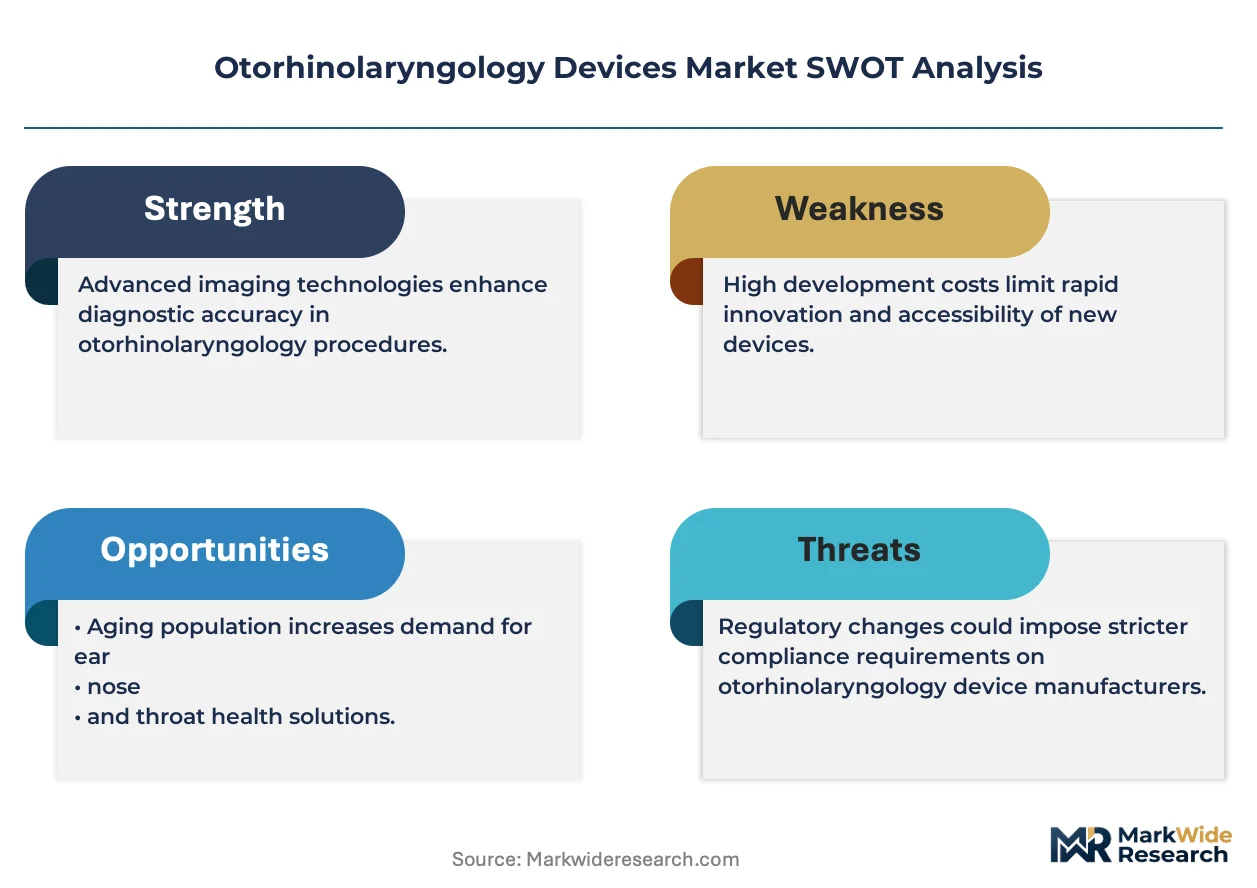
Robotic-assisted surgical platforms are compressing procedure timelines in tertiary ENT centers while simultaneously elevating capital requirements for ambulatory surgical facilities seeking competitive parity.
Growth Catalysts
- EU MDR compliance deadlines:German and French ENT clinics are accelerating equipment refresh cycles to meet enhanced biocompatibility documentation requirements for implantable sinus devices.
- Electrode array miniaturization:Advances in platinum-iridium fabrication enable perimodiolar positioning in cochlear implants, expanding candidacy to residual hearing preservation cases.
- Japan METI reimbursement expansion:Bilateral hearing implant procedures now qualify for parallel reimbursement, eliminating sequential surgery delays that previously constrained volume.
Market Restraints
- Titanium alloy supply concentration:Aerospace and medical device demand competition from Chinese and Russian feedstock processors generates price volatility for endoscope instrument shafts.
- FDA 510(k) clinical evidence inflation:Active implantable hearing devices now require extended follow-up data, extending premarket timelines by 18-24 months versus historical baselines.
- Optical fiber bundle sourcing:Japanese and German specialty glass manufacturers control 70% of high-numerical-aperture fiber production for rigid endoscopes.
Strategic Opportunities
- AI-enabled diagnostic platforms:Machine learning classification of otoscopic images for chronic otitis media screening addresses primary care capacity constraints in rural India.
- Telemedicine-integrated follow-up:Remote programming capabilities for cochlear implant sound processors reduce urban center visit burden for pediatric patients in Australian and Canadian markets.
- Software-as-medical-device pathways:FDA and EU MDR harmonization efforts on standalone diagnostic algorithms create streamlined market access for acoustic analysis applications.
Industry Challenges
- Robotic surgery technician scarcity:Certified training programs for da Vinci SP and Medtronic Hugo ENT applications lag installed base expansion in Nordic hospital systems.
- Legacy EMR integration friction:Surgical navigation systems require custom HL7 FHIR middleware to exchange imaging data with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Otorhinolaryngology Devices Market |
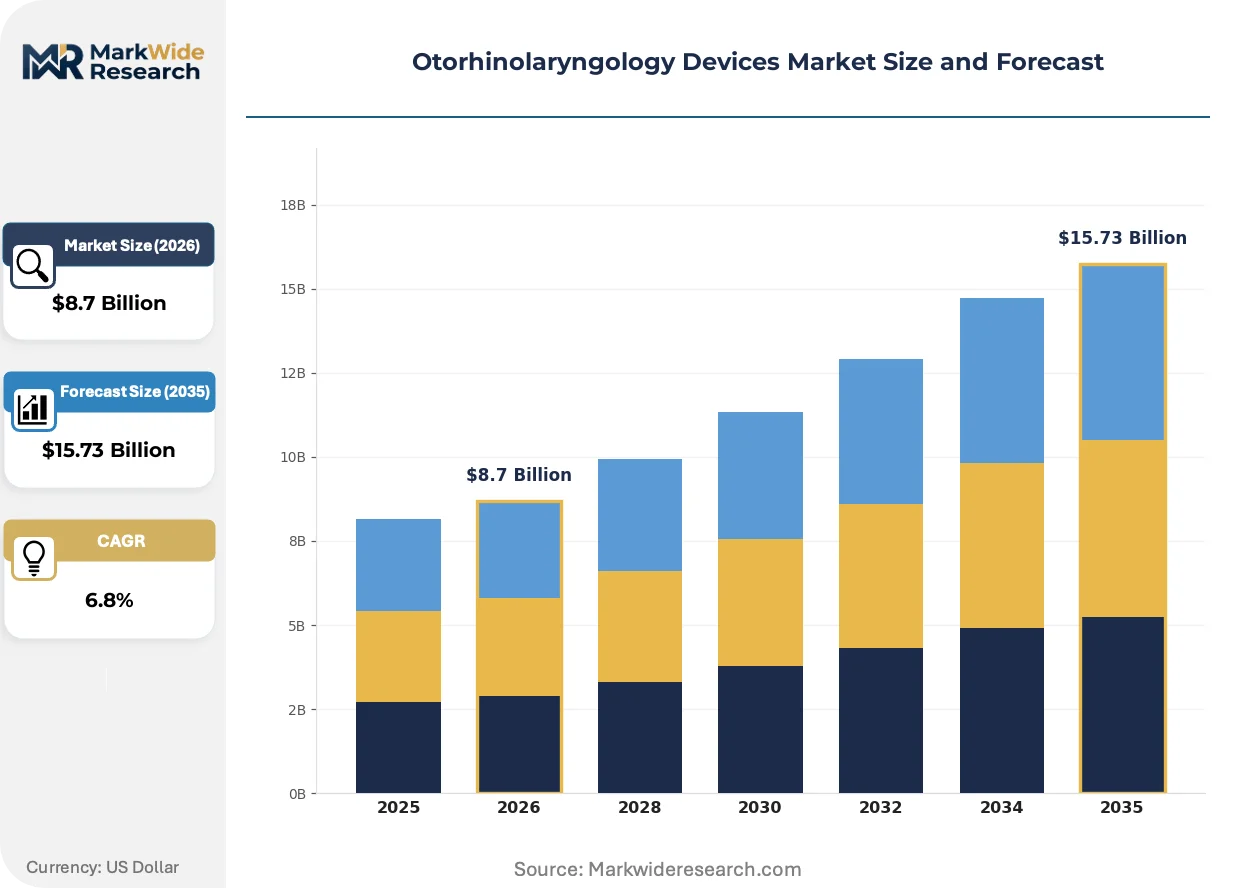
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasal Endoscopes, Audiometers, Rhinometers, Sinus Implants Application: Sinus Surgery, Hearing Loss Treatment, Allergy Management, ENT Diagnostics End User: Hospitals, ENT Clinics, Ambulatory Surgical Centers, Home Care Settings Technology: 3D Imaging, Laser Therapy, Robotic-assisted Surgery, Telemedicine Solutions |
| Companies Covered | Olympus Corporation, Cochlear Ltd., Medtronic plc, Demant A/S, Sonova Holding AG, Stryker Corporation, Karl Storz SE & Co. KG, GN Store Nord A/S, Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Otorhinolaryngology Devices Market Strategic Shifts
Digital twin modeling of sinus anatomy and AI-assisted polyp detection are compressing diagnostic-to-intervention timelines while elevating precision requirements across the ENT device value chain.
Intraoperative navigation systems using electromagnetic tracking and preoperative CT fusion are integrating real-time instrument positioning data with augmented reality overlays. Tertiary hospitals in South Korea and the Netherlands are deploying these platforms for complex skull base approaches. The technology is integrating previously separate diagnostic imaging and surgical instrument workflows into unified procedure environments.
EU MDR Article 10 post-market surveillance mandates now require systematic implant registry participation for sinus stent manufacturers. This industrial consequence forces mid-tier suppliers to outsource clinical follow-up to contract research organizations. Active implantable hearing devices face the steepest compliance cost escalation, with German notified bodies imposing additional biocompatibility testing for electrode contact materials.
Hospital procurement committees are consolidating vendor relationships through integrated capital equipment contracts that bundle endoscopes, powered instruments, and multi-year service agreements. Independent ambulatory surgery centers in Texas and Florida face exclusion from these purchasing cooperatives, forcing reliance on refurbished equipment channels. This concentration is most visible in metropolitan hospital systems where GPO-negotiated pricing now determines 60% of high-value ENT capital acquisitions.
Otorhinolaryngology Devices Market Segmentation
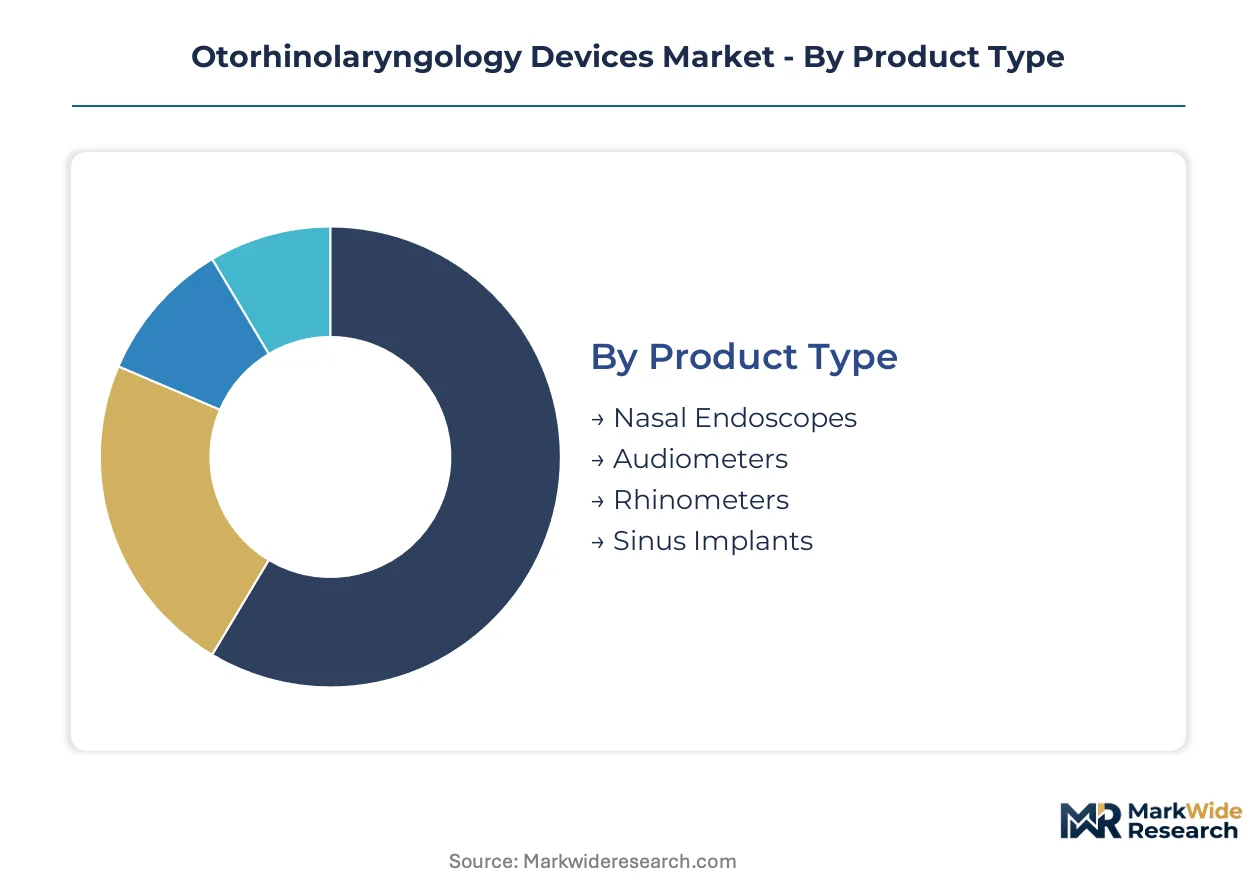
Otorhinolaryngology device purchasing decisions split sharply between capital-intensive surgical platforms and consumable diagnostic tools. Procurement committees weight upfront investment against procedure volume elasticity and reimbursement durability.
Product Type:
Capital equipment segments demand substantial upfront investment in optical engineering and precision manufacturing infrastructure.
- Nasal Endoscopes:Rigid optical systems with 0-70 degree viewing angles and titanium-alloy instrument channels dominate functional endoscopic sinus surgery workflows. German and Japanese specialty glass manufacturers supply high-numerical-aperture fiber bundles that determine image resolution thresholds.
- Sinus Implants:Biocompatible silicone and bioabsorbable polymer stents require extensive biocompatibility documentation under EU MDR Article 10 post-market surveillance mandates. Implant registry participation forces mid-tier suppliers toward contract research organization partnerships.
- Audiometers:Diagnostic tone generators and speech recognition test suites represent mature replacement-driven demand with limited technology differentiation.
- Rhinometers:Acoustic rhinometry and rhinomanometry systems measure nasal airflow resistance and cross-sectional area for preoperative assessment.
Sinus Implants absorb the bulk of installed capacity; Sinus Implants is expanding most quickly among implantable categories.
Application:
Procedure reimbursement codes determine commercial viability across intervention types, with surgical applications commanding premium pricing.
- Sinus Surgery:Functional endoscopic sinus surgery and balloon sinuplasty drive demand for navigation-enabled instrument platforms. South Korean and Dutch tertiary hospitals deploy electromagnetic tracking with preoperative CT fusion for skull base approaches.
- Hearing Loss Treatment:Cochlear implantation and bone-anchored hearing systems require extended FDA 510(k) clinical evidence timelines. Japan METI reimbursement now covers bilateral procedures in parallel, eliminating sequential surgery delays.
- Allergy Management:Immunotherapy delivery systems and nasal corticosteroid administration devices serve chronic rhinitis populations.
- ENT Diagnostics:Otoscopy, laryngoscopy, and audiometric screening form the gateway to intervention decisions in primary care settings.
Sinus Surgery commands the highest equipment expenditure per procedure; Hearing Loss Treatment is climbing the fastest as candidacy criteria broaden.
End User:
Facility type determines capital budget scale and purchasing cooperative access, creating divergent procurement patterns.
- Hospitals:Tertiary medical centers consolidate vendor relationships through integrated capital equipment contracts bundling endoscopes, powered instruments, and multi-year service agreements. GPO-negotiated pricing determines the majority of high-value acquisitions in metropolitan systems.
- ENT Clinics:German and French clinics are accelerating equipment refresh cycles to meet EU MDR enhanced biocompatibility documentation requirements.
- Ambulatory Surgical Centers:Texas and Florida independent ASCs face exclusion from hospital purchasing cooperatives, forcing reliance on refurbished equipment channels.
- Home Care Settings:Remote cochlear implant sound processor programming and telemedicine follow-up reduce urban center visit burden for pediatric patients.
Hospitals deploy the greatest absolute capital; Ambulatory Surgical Centers is gaining share fastest as procedure migration accelerates.
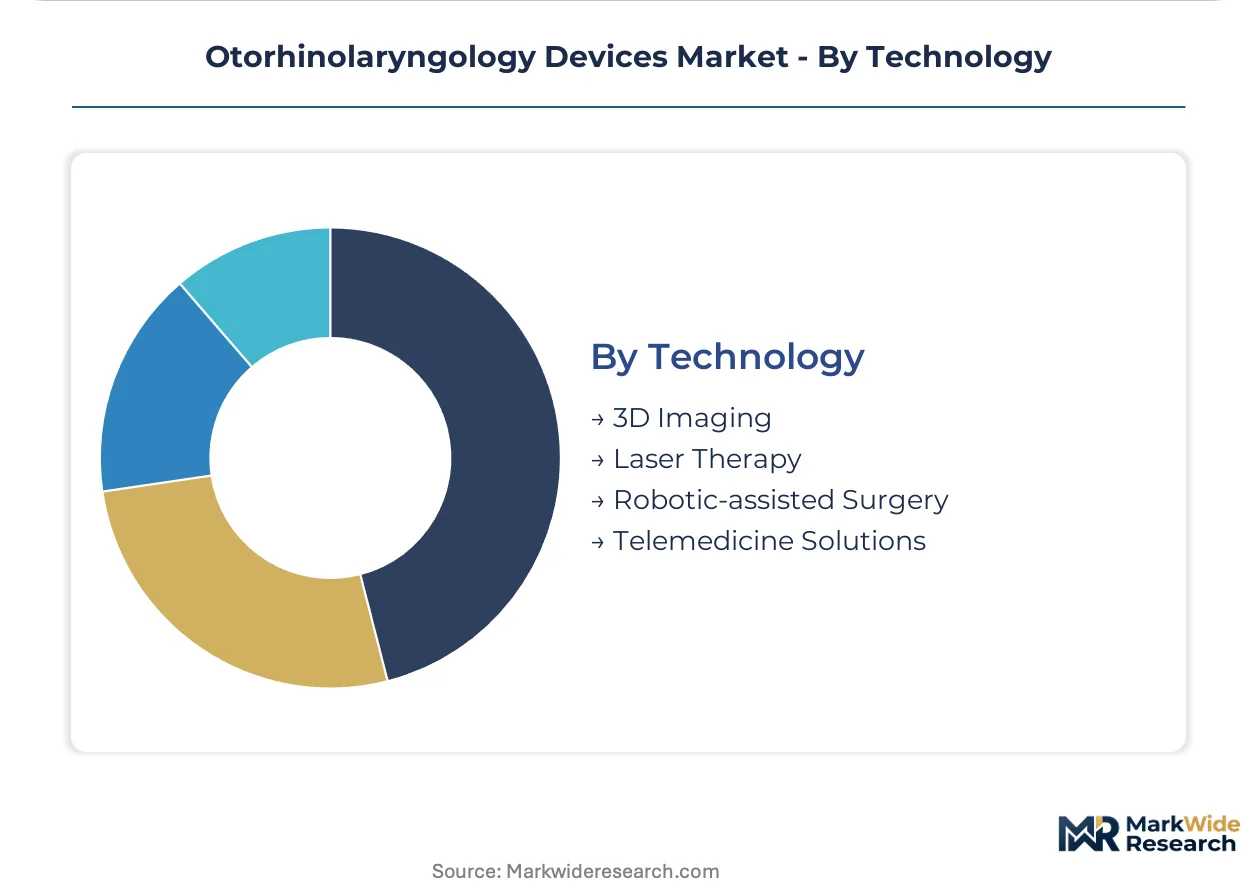
Technology:
Software-enabled capabilities are displacing conventional hardware-centric approaches, though reimbursement fragmentation constrains telemedicine adoption.
- Robotic-assisted Surgery:Platforms compress procedure timelines in tertiary centers while elevating capital requirements for ambulatory facilities seeking competitive parity. Certified training programs lag installed base expansion in Nordic hospital systems.
- 3D Imaging:Digital twin modeling of sinus anatomy and AI-assisted polyp detection compress diagnostic-to-intervention timelines.
- Laser Therapy:Precision tissue ablation systems serve selected otologic and laryngeal applications with controlled thermal damage zones.
- Telemedicine Solutions:Remote diagnostic platforms face reimbursement fragmentation across payer systems, limiting commercial scale.
Robotic-assisted Surgery captures the dominant share of new capital allocation; Telemedicine Solutions is advancing fastest where reimbursement alignment exists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium-alloy feedstock processing in Germany and Japan anchors high-end ENT instrument manufacturing, while platinum-iridium electrode fabrication concentrates in Swiss and Australian refineries serving implantable hearing device producers.
Germany
EU MDR compliance deadlines are accelerating equipment refresh cycles in ENT clinics across Bavaria and North Rhine-Westphalia. The country's national medical device regulator enforces enhanced biocompatibility documentation requirements for implantable sinus devices. The Tuttlingen surgical instrument cluster is decoupling from generic Asian assembly lines for high-end visualization systems.
United States
FDA 510(k) clinical evidence inflation is extending premarket timelines for active implantable hearing devices by 18-24 months. The federal pharmaceutical and medical device regulator now demands extended follow-up data that reshapes product development economics. Metropolitan hospital systems in Texas and Florida are consolidating vendor relationships through GPO-negotiated pricing.
Japan
METI reimbursement expansion for bilateral hearing implant procedures is eliminating sequential surgery delays that previously constrained volume. The Ministry of Economy, Trade and Industry coordinates with PMDA to determine commercial viability classifications for novel ENT robotics. The Nagoya medical device corridor is deploying electromagnetic tracking systems for complex skull base approaches.
South Korea
Digital twin modeling of sinus anatomy is compressing diagnostic-to-intervention timelines in Seoul tertiary hospitals. The Ministry of Food and Drug Safety regulates software-as-medical-device classifications for AI-enabled diagnostic platforms. The Songdo biomedical cluster is integrating augmented reality overlays with intraoperative navigation systems.
Australia
Telemedicine-integrated follow-up for cochlear implant sound processors is reducing urban center visit burden for pediatric patients. The Therapeutic Goods Administration oversees reimbursement alignment for remote programming capabilities. Sydney and Melbourne hospital networks are piloting remote diagnostic platforms for chronic otitis media screening.
Otorhinolaryngology Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-enabled diagnostic platforms and robotic-assisted surgical niches. The vendor base splits between diversified conglomerates with broad ENT portfolios and specialized instrument manufacturers with deep optical engineering heritage. Three archetypes dominate: precision visualization specialists, implantable hearing solution anchors, and diversified surgical platform integrators. M&A activity concentrates on navigation technology acquisitions, while capacity expansion targets electrode array miniaturization capabilities.
Within the precision visualization tier, Olympus Corporation and Karl Storz SE & Co. KG represent the optical fiber bundle engineering tradition. Cochlear Ltd. exemplifies the implantable hearing solution anchor archetype through sustained electrode miniaturization focus. Medtronic plc occupies a position across powered instruments and intraoperative navigation, illustrating the diversified surgical platform integrator model. These three names span Japanese, German, and Irish corporate origins respectively, reflecting the geographic distribution of ENT device engineering expertise.
| Leading Market Players |
|---|
| Olympus Corporation |
| Cochlear Ltd. |
| Medtronic plc |
| Demant A/S |
| Sonova Holding AG |
| Stryker Corporation |
| Karl Storz SE & Co. KG |
| GN Store Nord A/S |
| Smith & Nephew plc |
| Others |
Value Chain & Pricing Dynamics
Hospital purchasing committee consolidation into GPO-negotiated contracts is forcing mid-tier ENT device suppliers to unbundle service agreements and absorb warranty costs directly, compressing margins on capital equipment while elevating aftermarket service pricing as the profit anchor.
Pricing Analysis
Warranty and multi-year service bundling now separates premium-tier Japanese and German manufacturers from economy-tier refurbished equipment channels serving independent ASCs. Three-tier pricing structure across premium, standard, and economy levels reflects optical fiber bundle origin and FDA 510(k) clearance status as primary differentiation drivers. Cost compression in the standard tier is intensifying because EU MDR compliance documentation requirements have elevated fixed regulatory costs. Independent ambulatory surgical centers exhibit the highest price sensitivity, while tertiary hospital systems prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA procurement guidelines and Germany's EU MDR origin documentation requirements are reshaping sourcing patterns for titanium-alloy instrument shafts. High-numerical-aperture optical fiber production concentrates in Japan and Germany, while platinum-iridium electrode fabrication feeds from Swiss and Australian refineries. Single-source vulnerability in specialty glass manufacturing creates chokepoint exposure for rigid endoscope supply. Distribution runs through hospital purchasing cooperatives and direct manufacturer contracts to metropolitan health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty glass fiber and platinum-iridium electrode fabrication capacity constraints are propping pricing power for incumbent manufacturers, creating a supply-constrained market structure that favors established players with captive supplier relationships.
For Market Incumbents: Extend service contract penetration into installed base equipment to lock out refurbished equipment competitors. Backward integration into titanium-alloy instrument shaft production buffers aerospace demand competition. Cochlear implant electrode array miniaturization R&D spending must accelerate to defend against emerging entrants in residual hearing preservation segments. For New Entrants and Emerging Players: Telemedicine-integrated cochlear implant follow-up platforms represent the most penetrable white-space target in Australian and Canadian pediatric markets. AI-enabled otoscopic screening for chronic otitis media in rural India offers a software-as-medical-device entry point with lower capital barriers. Partnership with independent ambulatory surgical centers in Texas and Florida bypasses GPO exclusion. For Investors and Strategic Acquirers: The window for entry favors navigation technology specialists with electromagnetic tracking capabilities. Long-term viability hinges on software-enabled diagnostic platform differentiation rather than hardware commoditization. Watch FDA and EU MDR harmonization progress on standalone algorithm classifications as the inflection signal for AI diagnostic valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Enhanced biocompatibility documentation unlocks German and French clinic procurement channels. |
| Electrode Miniaturization R&D | Perimodiolar positioning capability expands cochlear implant candidacy to residual hearing cases. |
| Hospital System Partnership | GPO-negotiated bundling contracts secure metropolitan tertiary center equipment refresh cycles. |
| Software Companion Development | Remote cochlear implant programming reduces pediatric patient urban visit burden in Australia. |
| Reimbursement Strategy | METI bilateral procedure classification in Japan eliminates sequential surgery volume constraints. |
Study Parameters
Multi-period observation of EU MDR implementation timelines, METI reimbursement classification changes, and FDA 510(k) clearance patterns anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and ENT clinic administrators. Secondary validation drew from FDA 510(k) filings, PMDA approval databases, hospital procurement records, and EU notified body biocompatibility testing disclosures. Bottom-up procedure volume modeling and top-down capital equipment expenditure estimates were triangulated against manufacturer revenue disclosures.
Input-output matrices mapped titanium-alloy feedstock flows, optical fiber bundle manufacturing capacity, and electrode fabrication output to end-use equipment production across the projection horizon. Segmentation dimensions included product type, application, end-user facility category, and technology platform. CAGRs were derived from fitted growth curves applied to procedure volume elasticities and equipment replacement cycles, with electrode array miniaturization adoption curves and robotic surgery penetration rates as key forecast inputs.
Caveats apply where FDA clinical evidence requirement inflation, titanium-alloy aerospace demand spikes, or EU MDR notified body capacity constraints could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Retractors Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Allografts Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Prostate Biopsy Devices Market