
 Anatomic Pathology Track and Trace Solutions Market | 2026-2036
Anatomic Pathology Track and Trace Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Anatomic Pathology Track and Trace Solutions Market Analysis
The gap between premium integrated systems and standalone hardware is rebalancing as mid-size laboratories seek modular software that scales without full infrastructure replacement. Thermo Fisher Scientific leverages its diagnostic instrument installed base to bundle tracking modules, while Leica Biosystems anchors its position through tight integration with slide scanning and imaging workflows. Agilent Technologies differentiates via chromatography-linked specimen provenance tools that serve research-heavy customers.
Anatomic pathology track and trace solutions encompass software platforms, barcode or RFID-enabled hardware, and integrated systems that record specimen identity, location, and handling history across accessioning, processing, staining, and reporting stages. These solutions employ serialized labeling with GS1-compliant barcodes or encrypted RFID tags to maintain chain-of-custody documentation required for clinical diagnostics and biorepository management. Software solutions capture the dominant share of value as laboratories prioritize cloud-based audit trails and interoperability with laboratory information systems. Hardware devices face margin compression from commoditized barcode scanners, though RFID readers command premium pricing in biobank cold-chain applications.
The FDA enforces Unique Device Identification and quality system regulations that mandate specimen traceability in clinical laboratories, while CLIA standards govern test result integrity through documented handling protocols. ISO 15189 accreditation requirements in academic medical centers further tighten documentation expectations for pre-analytical processes. Stakeholders must weigh interoperability investments against the risk of stranded hardware as health systems consolidate vendor relationships and demand unified data architectures.
Market Dynamics
Diagnostic laboratories face mounting pressure to eliminate specimen misidentification errors, with integrated health networks consolidating vendor relationships to enforce unified data architectures that span accessioning through final reporting.
Growth Catalysts
- CLIA chain-of-custody mandates:Documented handling protocols now govern test result integrity, compelling mid-size laboratories to upgrade from paper logs to serialized barcode systems.
- Biorepository cold-chain expansion:Academic medical centers building multi-site tissue banks require RFID-enabled tracking that maintains specimen provenance across temperature-controlled logistics.
- Cloud-based audit trails:Software platforms capturing real-time location data are displacing fragmented spreadsheets as laboratories pursue ISO 15189 accreditation.
Market Restraints
- RFID hardware cost concentration:Encrypted tag readers for ultra-low temperature applications remain priced at premiums that exclude smaller independent pathology practices.
- Legacy LIS interoperability friction:Proprietary data formats in installed laboratory information systems create integration delays that extend deployment timelines.
- Commoditized barcode scanner margins:Generic handheld devices from Asian contract manufacturers are compressing profitability in standalone hardware segments.
Strategic Opportunities
- Research-heavy chromatography linkage:Specimen provenance tools that integrate with analytical instruments serve pharmaceutical toxicology labs pursuing GLP compliance.
- Modular software subscriptions:Mid-size laboratories in Germany and France are adopting scalable tracking modules without full infrastructure replacement.
- GS1 compliance mandates:Healthcare systems in the United Kingdom are standardizing serialized labeling, creating replacement demand for non-compliant legacy systems.
Industry Challenges
- Interoperability engineering talent scarcity:Health systems struggle to hire HL7 FHIR specialists capable of bridging cloud-based audit trails with on-premise laboratory information systems.
- Multi-site standardization complexity:Integrated delivery networks acquiring independent pathology groups face fragmented accessioning workflows that resist rapid unification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anatomic Pathology Track and Trace Solutions Market |
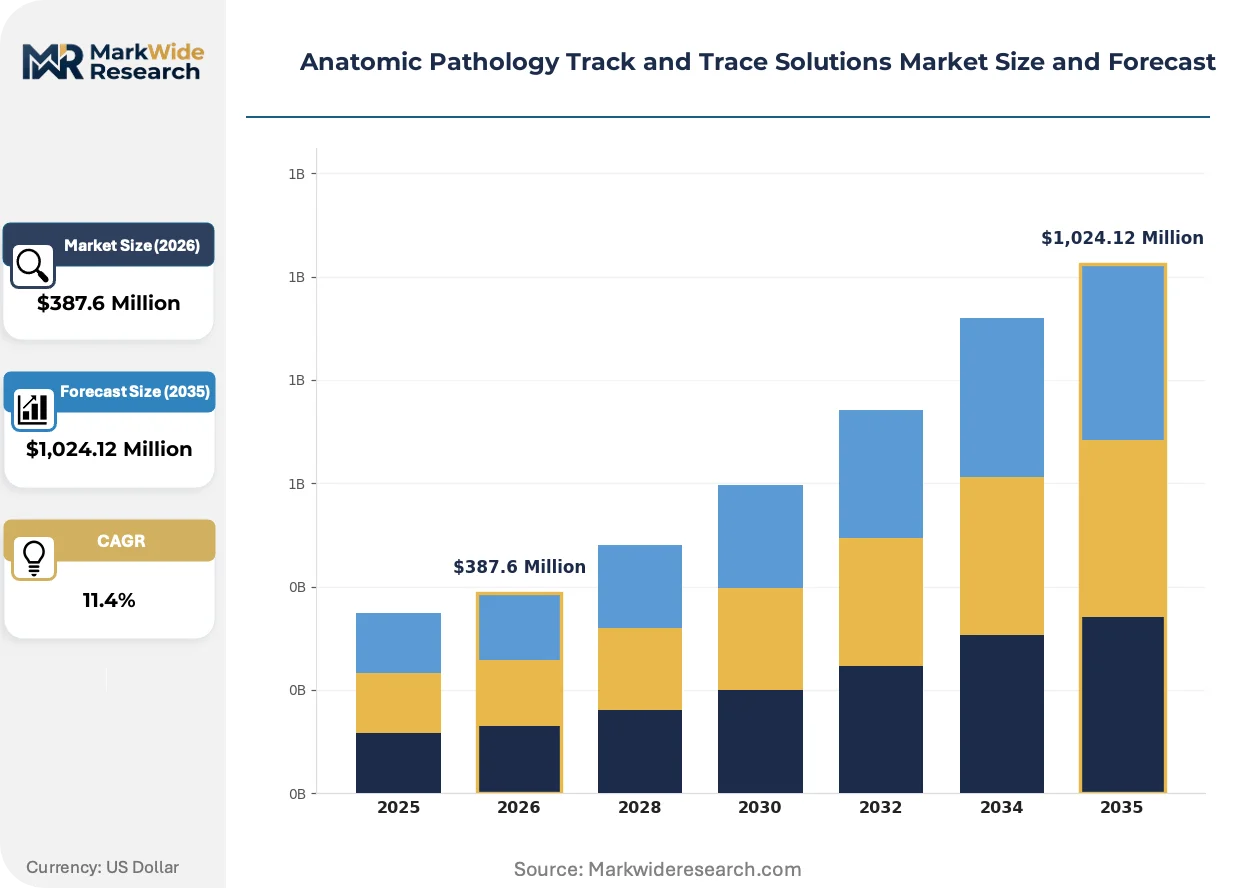
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Integrated Systems, Labeling Tools End User: Hospitals, Diagnostic Laboratories, Research Institutions, Biobanks Technology: RFID, Barcode, QR Code, GPS Tracking Application: Specimen Management, Inventory Control, Regulatory Compliance, Data Analytics |
| Companies Covered | Agilent Technologies, AP Easy Software Solutions, Thermo Fisher Scientific, LigoLab, Sunquest Information Systems, Leica Biosystems, General Data Healthcare, Sakura Finetek, Ventana Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anatomic Pathology Track and Trace Solutions Market Emerging Trajectories
Artificial intelligence and machine learning capabilities are embedding into specimen tracking platforms, transforming passive data logging into predictive workflow optimization that anticipates bottlenecks before they disrupt diagnostic throughput.
RFID-enabled cold-chain monitoring is expanding into biobank applications where encrypted tags maintain chain-of-custody documentation across liquid nitrogen storage and cryogenic transport. Pharmaceutical companies building multi-regional specimen repositories are adopting these systems at accelerated rates. The structural consequence is expanding into premium pricing tiers for hardware vendors capable of certifying tag performance at minus 150 degrees Celsius.
The FDA's Unique Device Identification requirements are tightening traceability standards for in-vitro diagnostic devices, which now encompass specimen containers and transport media. Clinical laboratories must maintain serialized records linking patient identity to every consumable touchpoint. High-volume anatomic pathology labs in the United States are responding by integrating UDI capture into accessioning workstations.
Consolidated procurement by integrated delivery networks is compressing vendor lists, with health systems demanding unified data architectures that span multiple pathology subspecialties. Independent software vendors are being displaced by platform players offering bundled tracking modules. This concentration is most visible in United States metropolitan markets where three-hospital systems dominate regional diagnostic volume.
Anatomic Pathology Track and Trace Solutions Market Segmentation
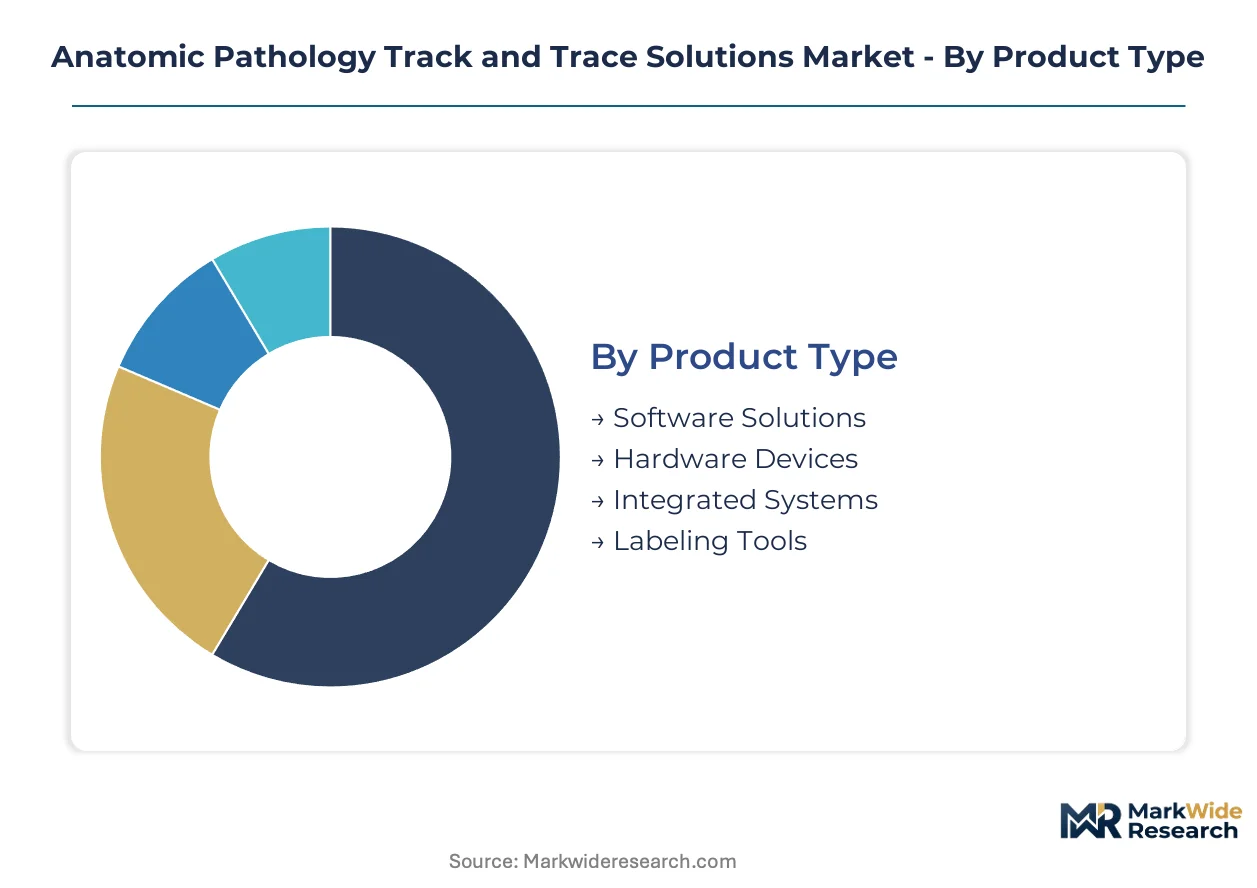
Specimen tracking solutions fragment across hardware intensity, software sophistication, and integration depth. Laboratories select configurations based on throughput volume, regulatory exposure, and existing laboratory information system architecture. The customization spectrum spans modular cloud subscriptions to fully embedded enterprise platforms.
Product Type:
Customization intensity varies sharply across this category, with configurable software modules at one pole and turnkey integrated systems at the other.
- Software Solutions:Cloud-native audit trail platforms with HL7 FHIR interoperability dominate new procurement. Academic medical centers in the United States prioritize these for ISO 15189 accreditation workflows. Expansion is steepest here as mid-size laboratories seek scalable subscriptions without infrastructure replacement.
- Integrated Systems:Bundled hardware-software platforms embed tracking into staining and imaging workflows. Leica Biosystems and Thermo Fisher Scientific anchor demand through diagnostic instrument installed bases. These command premium pricing but reduce interoperability engineering burdens.
- Hardware Devices:Barcode scanners and RFID readers capture serialized data at accessioning and processing stations. Generic handheld devices from Asian contract manufacturers now dominate low-end procurement.
- Labeling Tools:GS1-compliant barcode printers and RFID tag encoders generate serialized specimen identifiers. Demand concentrates in laboratories retrofitting legacy paper-based accessioning workflows.
Most installed capacity flows through Software Solutions. Expansion is steepest in Integrated Systems.
End User:
Procurement sophistication tracks specimen volume and regulatory scrutiny, creating four distinct buying centers with divergent technical requirements.
- Diagnostic Laboratories:High-throughput anatomic pathology labs process thousands of specimens daily. CLIA chain-of-custody mandates drive replacement of paper logs with serialized barcode systems. These facilities represent the deepest penetration of RFID-enabled cold-chain monitoring.
- Hospitals:Integrated delivery networks consolidate vendor relationships across multiple pathology subspecialties. Three-hospital systems in United States metropolitan markets demand unified data architectures spanning accessioning through final reporting.
- Biobanks:Multi-site tissue repositories require encrypted RFID tags that maintain provenance across liquid nitrogen storage. Pharmaceutical companies building multi-regional specimen repositories are adopting these systems at accelerated rates.
- Research Institutions:Academic medical centers pursue ISO 15189 accreditation while building chromatography-linked specimen provenance tools for GLP compliance.
Diagnostic Laboratories host the largest installed base. Biobanks are climbing the fastest as pharmaceutical cold-chain expansion accelerates.
Technology:
Price-performance tradeoffs separate mature barcode infrastructure from emerging RFID deployments across temperature extremes.
- Barcode:Linear and 2D symbologies remain the default for ambient-temperature specimen tracking. GS1 DataMatrix adoption is expanding in United Kingdom health systems standardizing serialized labeling.
- RFID:Encrypted UHF and HF tags operate in cryogenic biobank applications where barcode degradation risks specimen provenance. Tag readers certified for minus 150 degrees Celsius command substantial premiums.
- QR Code:Smartphone-scannable matrix codes serve low-volume independent pathology practices with limited capital budgets.
- GPS Tracking:Location services monitor specimen transport between collection sites and processing laboratories, particularly in rural United States markets with extended logistics chains.
Barcode infrastructure retains the largest footprint. RFID is gaining share fastest in premium cold-chain segments.
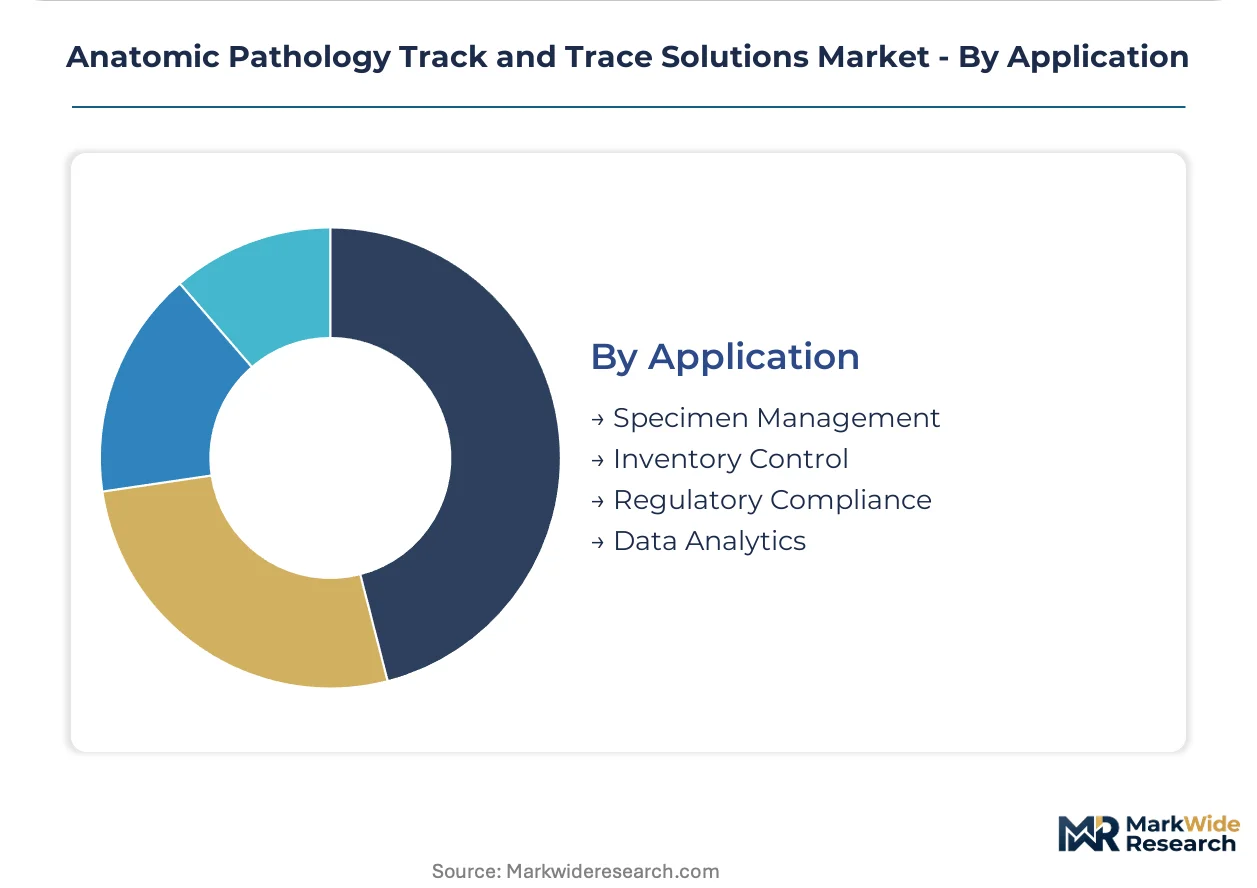
Application:
Functional priorities shift from operational efficiency to risk mitigation as regulatory pressure intensifies.
- Specimen Management:Real-time location tracking across accessioning, processing, staining, and reporting stages eliminates misidentification errors. Cloud-based platforms displace fragmented spreadsheets.
- Regulatory Compliance:FDA Unique Device Identification requirements mandate serialized records linking patient identity to every consumable touchpoint. High-volume laboratories integrate UDI capture into accessioning workstations.
- Inventory Control:Automated reorder triggers for reagents and consumables reduce stockout risks in high-throughput environments.
- Data Analytics:Predictive workflow optimization anticipates bottlenecks before they disrupt diagnostic throughput.
Specimen Management absorbs the majority of deployed capacity. Regulatory Compliance is expanding most quickly as enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pathology informatics specialists cluster in metropolitan medical hubs across five countries where diagnostic laboratory consolidation and biobank expansion concentrate procurement authority.
United States
Integrated delivery networks in metropolitan markets drive vendor consolidation as three-hospital systems demand unified data architectures spanning multiple pathology subspecialties. The FDA enforces Unique Device Identification requirements that mandate serialized specimen traceability across clinical laboratories. Boston and San Diego anchor biotech corridor demand where pharmaceutical companies build multi-regional specimen repositories with RFID-enabled cold-chain monitoring.
Germany
Mid-size laboratories in Bavaria and North Rhine-Westphalia adopt modular software subscriptions that scale without full infrastructure replacement. EMA quality system regulations and ISO 15189 accreditation requirements tighten documentation expectations for pre-analytical processes in academic medical centers. The Munich and Heidelberg clusters concentrate precision medicine initiatives where chromatography-linked specimen provenance tools serve GLP-compliant toxicology labs.
United Kingdom
National Health Service trusts standardize GS1-compliant serialized labeling across pathology networks, creating replacement demand for non-compliant legacy systems. MHRA enforcement of traceability standards accelerates cloud-based audit trail adoption in high-throughput diagnostic facilities. The Cambridge-Oxford-London triangle concentrates biorepository expansion where academic medical centers build multi-site tissue banks requiring encrypted RFID tags.
Japan
PMDA quality regulations and METI industrial standards govern specimen handling documentation in diagnostic laboratories serving aging populations. Tokyo and Osaka metropolitan areas concentrate automated pathology workflow investments where error reduction priorities override capital cost sensitivity. Pharmaceutical toxicology labs in Kanagawa Prefecture pursue GLP compliance through integrated tracking systems linked to analytical instruments.
India
CDSCO regulatory tightening and NABH accreditation expansion drive chain-of-custody upgrades in diagnostic laboratory chains serving tier-one cities. Hyderabad and Bengaluru clusters anchor biobank development where pharmaceutical contract research organizations adopt specimen tracking for international clinical trial compliance. Mid-size pathology groups in Maharashtra transition from paper logs to barcode systems as CLIA-equivalent standards penetrate private laboratory networks.
Anatomic Pathology Track and Trace Solutions Market Vendor Landscape
Capital-heavy diagnostic instrument manufacturers compete with asset-light software specialists for control of laboratory workflow integration. The vendor base organizes around three strategic archetypes: platform conglomerates bundling tracking modules with installed instrument bases, pure-play software vendors offering cloud-native interoperability layers, and precision hardware specialists certifying RFID performance at cryogenic temperatures. Consolidation pressure from integrated delivery networks favors platform breadth over point solutions. Strategic partnerships between software vendors and instrument manufacturers accelerate as health systems demand unified data architectures.
Within the platform conglomerate tier, Thermo Fisher Scientific and Leica Biosystems anchor positions through diagnostic instrument installed bases that enable bundled tracking module distribution. Agilent Technologies occupies a distinct position linking specimen provenance tools to chromatography workflows for pharmaceutical toxicology customers. Among specialized software vendors, LigoLab and Sunquest Information Systems exemplify cloud-native architectures designed for mid-size laboratory scalability without infrastructure replacement.
| Leading Market Players |
|---|
| Agilent Technologies |
| AP Easy Software Solutions |
| Thermo Fisher Scientific |
| LigoLab |
| Sunquest Information Systems |
| Leica Biosystems |
| General Data Healthcare |
| Sakura Finetek |
| Ventana Medical Systems |
| Others |
Supply Flow & Price Mechanics
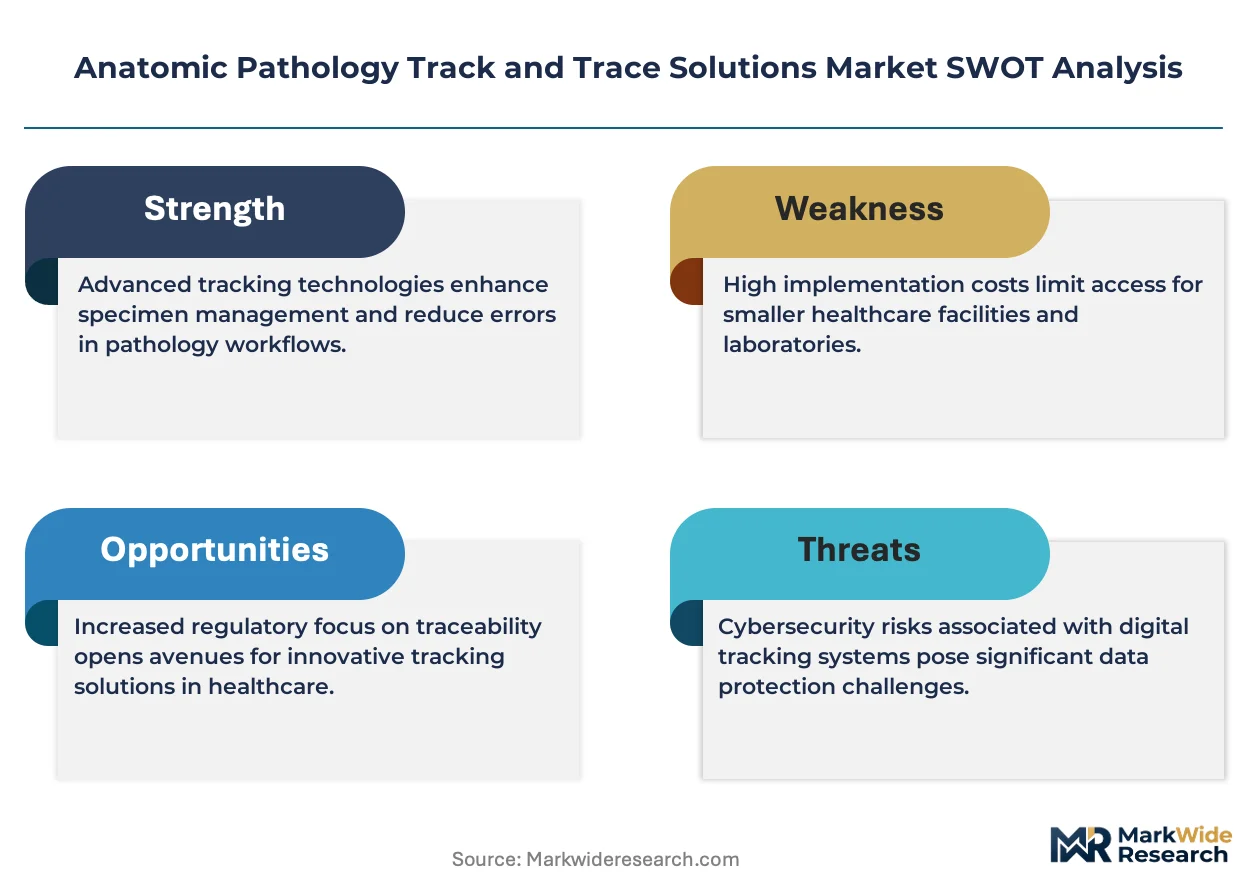
ISO 15189 accreditation requirements in academic medical centers gate qualified supply partnerships and premium-tier pricing access for vendors certifying cryogenic RFID performance. CLIA chain-of-custody mandates simultaneously compress margins for generic barcode hardware while elevating subscription pricing for cloud-native audit trail platforms.
Pricing Analysis
The bundled-versus-unbundled service split separates platform conglomerates from pure-play software vendors. Diagnostic instrument manufacturers command premium-mid-economy pricing differentiation through hardware-software bundles that reduce interoperability engineering burdens. Price differentiation rests on certification grade for cryogenic applications and volume scale for mid-size laboratory subscriptions. Cost compression in standalone barcode scanners is intensifying because Asian contract manufacturers flood low-end procurement. Independent pathology practices exhibit highest price sensitivity, while integrated delivery networks prioritize unified data architectures over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for encrypted RFID tags mandate multi-supplier qualification across semiconductor foundries in Taiwan, South Korea, and Japan. Hardware assembly concentrates in China and Mexico for barcode scanners and label printers. Supply chains draw from specialized substrate materials for cryogenic tags, GS1-compliant encoding chips, and cloud infrastructure services. Single-source vulnerability persists for readers certified at minus 150 degrees Celsius. Distribution runs through diagnostic instrument distributors, GPO contracts, and direct enterprise sales to integrated health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Unique Device Identification enforcement generates replacement demand that compounds across diagnostic laboratory consolidation cycles.
For Market Incumbents: Cement platform positions by embedding tracking modules into staining and imaging instrument installed bases before pure-play software vendors achieve HL7 FHIR interoperability dominance. Acquire cloud-native audit trail specialists to neutralize the threat of modular subscription displacement. Prioritize certification investment for cryogenic RFID performance to defend margin position in biobank cold-chain expansion. For New Entrants and Emerging Players: The price-point gap between premium integrated systems and economy barcode hardware opens white-space targeting for mid-size laboratories in Germany and France seeking scalable modules without infrastructure replacement. Pursue chromatography-linked specimen provenance tools for pharmaceutical toxicology labs as the most penetrable application. Deploy SaaS-native go-to-market angles that bypass capital-intensive hardware sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native software specialists because fragmented independent pathology groups resist rapid unification under integrated delivery networks. Target acquisition of ISO 15189 workflow-certified platforms with proven hospital system integration. Watch for CLIA enforcement acceleration as the inflection signal indicating replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded tracking modules in Leica Biosystems staining workflows reduce customer switching costs. |
| Regulatory Certification Pathway | FDA UDI compliance for specimen containers mandates serialized labeling infrastructure replacement. |
| Strategic Partnership | HL7 FHIR interoperability alliances bridge cloud audit trails with legacy laboratory information systems. |
| Geographic Expansion | GS1 compliance mandates in United Kingdom NHS trusts create standardized labeling procurement windows. |
| Acquisition of Specialist Firm | Cryogenic RFID certification capabilities capture pharmaceutical biobank cold-chain premium pricing. |
Methodological Framework
Direct dialogue with pathology informatics directors, laboratory operations managers, hospital procurement committees, and diagnostic instrument R&D heads grounded qualitative insights in operational reality. Secondary validation drew from FDA UDI guidance documents, CLIA regulatory filings, GS1 healthcare standards, and hospital GPO contract databases. Bottom-up laboratory adoption modeling triangulated against top-down health system IT spending analysis.
Segmentation outputs across product type, end user, technology, and application dimensions calibrated volume and value projections over the analysis window. CAGRs derived from instrument installed base replacement cycles, accreditation mandate enforcement timelines, and cloud subscription adoption curves. Forecast inputs incorporated biobank cold-chain expansion rates and pharmaceutical toxicology lab GLP compliance investments.
Caveats apply where FDA enforcement acceleration or CLIA audit intensity could materially shift the outlook. Deviation in integrated delivery network consolidation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Aged Care Software Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Asia Pacific Healthcare IT Market