
 Veterinary Practice Management Software Market | 2026-2036
Veterinary Practice Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Practice Management Software Market Intelligence
The divergence between comprehensive, integrated practice suites and standalone, single-function tools is consolidating the market around platforms offering extensive API ecosystems. This fundamental shift benefits scalable, cloud-native solutions designed for modern workflows. Provet Cloud leverages its modern architecture to effectively serve multi-site clinic groups. Meanwhile, Covetrus Pulse differentiates by deeply connecting its software to a wider supply chain and integrated pharmacy services network.
Veterinary practice management software comprises digital platforms designed to streamline clinical and administrative operations within an animal care facility. These systems manage functions from patient records, which often must handle diverse species data, to billing and inventory. Cloud-based deployment models dominate new installations, offering superior accessibility and data security over on-premises solutions. The animal hospitals end-user segment drives demand for sophisticated features like integrated laboratory management systems and detailed reporting tools.
Data privacy regulations shape software development, with Europe's GDPR setting a high standard for handling client information. In the United States, principles from HIPAA often inform best practices for securing sensitive pet health data, even without a direct mandate. These compliance requirements influence feature sets for patient records and communication modules. Vendor selection now centers on the strategic choice between a fully integrated suite and the flexibility of connecting specialized third-party applications.
Market Dynamics
The central dynamic shaping the market is the bifurcation between closed, all-in-one software suites and open, API-centric platforms. This tension forces vendors to choose between offering a complete, walled-garden ecosystem or becoming a flexible hub for a network of specialized third-party applications.
Growth Catalysts
- Practice Consolidation:The rise of corporate-owned, multi-site veterinary groups and large animal hospitals necessitates scalable, cloud-based software that can standardize operations, share data, and centralize reporting across numerous locations.
- AI-Driven Diagnostics:The integration of artificial intelligence for tasks like radiographic interpretation and predictive analytics creates a strong pull for modern software platforms capable of handling and processing large, complex datasets from clinical operations.
- Insurance and Compliance Demands:Growing pet insurance penetration and data privacy rules like Europe's GDPR increase the demand for software with detailed, auditable electronic health records and secure client communication modules.
Market Restraints
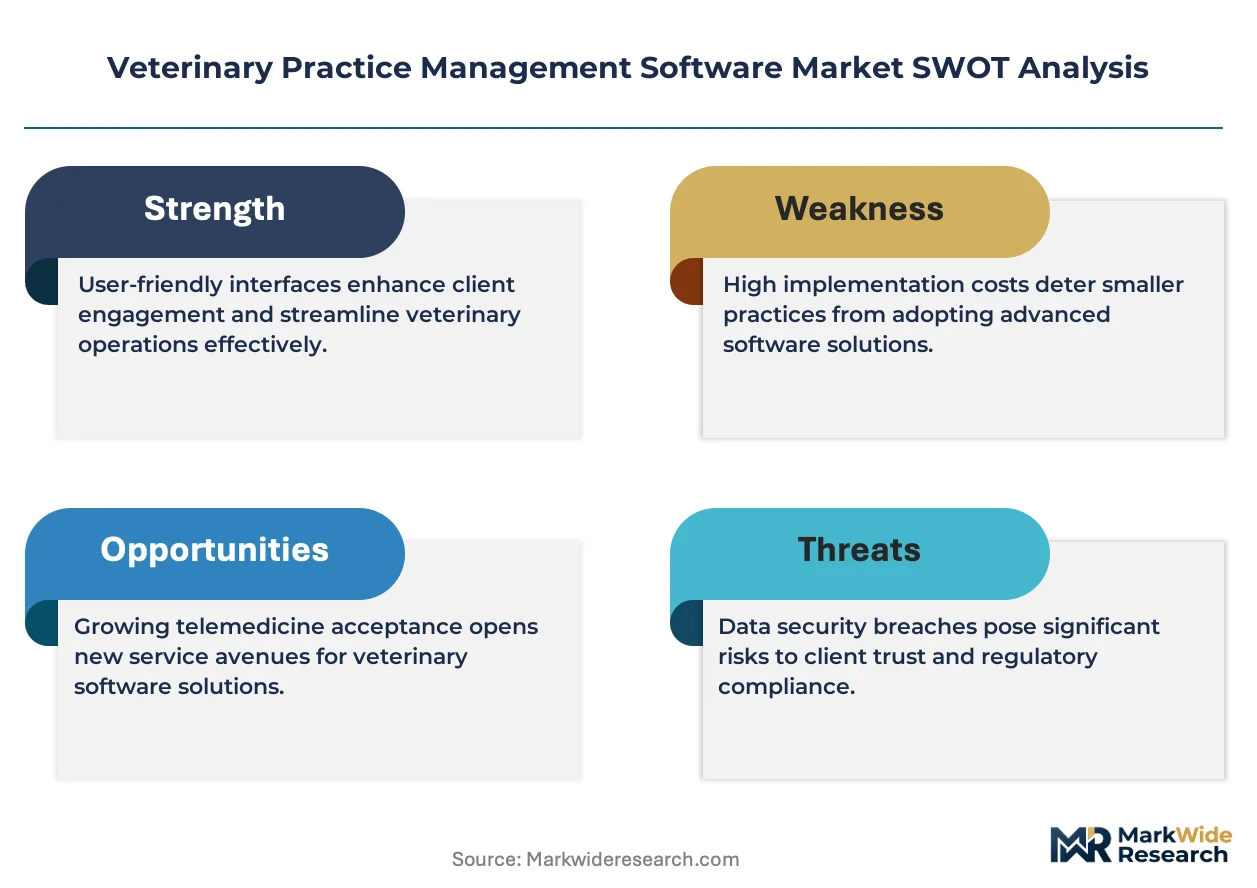
- High Total Cost of Ownership:The combined expense of software subscription fees, data migration, hardware upgrades, and staff training presents a significant financial barrier for small, independent veterinary practices and solo practitioners.
- Data Interoperability Gaps:A lack of universal data exchange standards between practice management systems, diagnostic laboratory equipment, and imaging modalities creates data silos and hinders the creation of a unified patient record.
- Legacy System Inertia:The operational disruption, perceived risk, and significant effort required to migrate years of patient and financial data from older, on-premises systems to new cloud platforms deter many established clinics from switching.
Strategic Opportunities
- Expansion in Emerging Markets:Developing localized, cost-effective software versions for underpenetrated veterinary markets with rising pet populations, such as Brazil and Mexico, offers significant growth potential for vendors.
- IoT and Wearable Integration:Integrating practice management software with data streams from pet health wearables and smart monitoring devices enables new service models focused on proactive and preventative care based on continuous health tracking.
- Niche Practice Specialization:Building dedicated software modules for high-value, specialized fields like equine medicine, oncology, or ophthalmology allows vendors to capture market share within specific segments of the veterinary profession.
Industry Challenges
- User Training and Adoption Gaps:A persistent challenge is ensuring that veterinary staff are adequately trained to leverage the full capabilities of sophisticated software, which often leads to underutilization of advanced features and diminished return on investment.
- Third-Party System Integration:The technical complexity and cost of building and maintaining reliable integrations with a fragmented landscape of external laboratories, payment processors, and client communication tools remains a significant operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Practice Management Software Market |
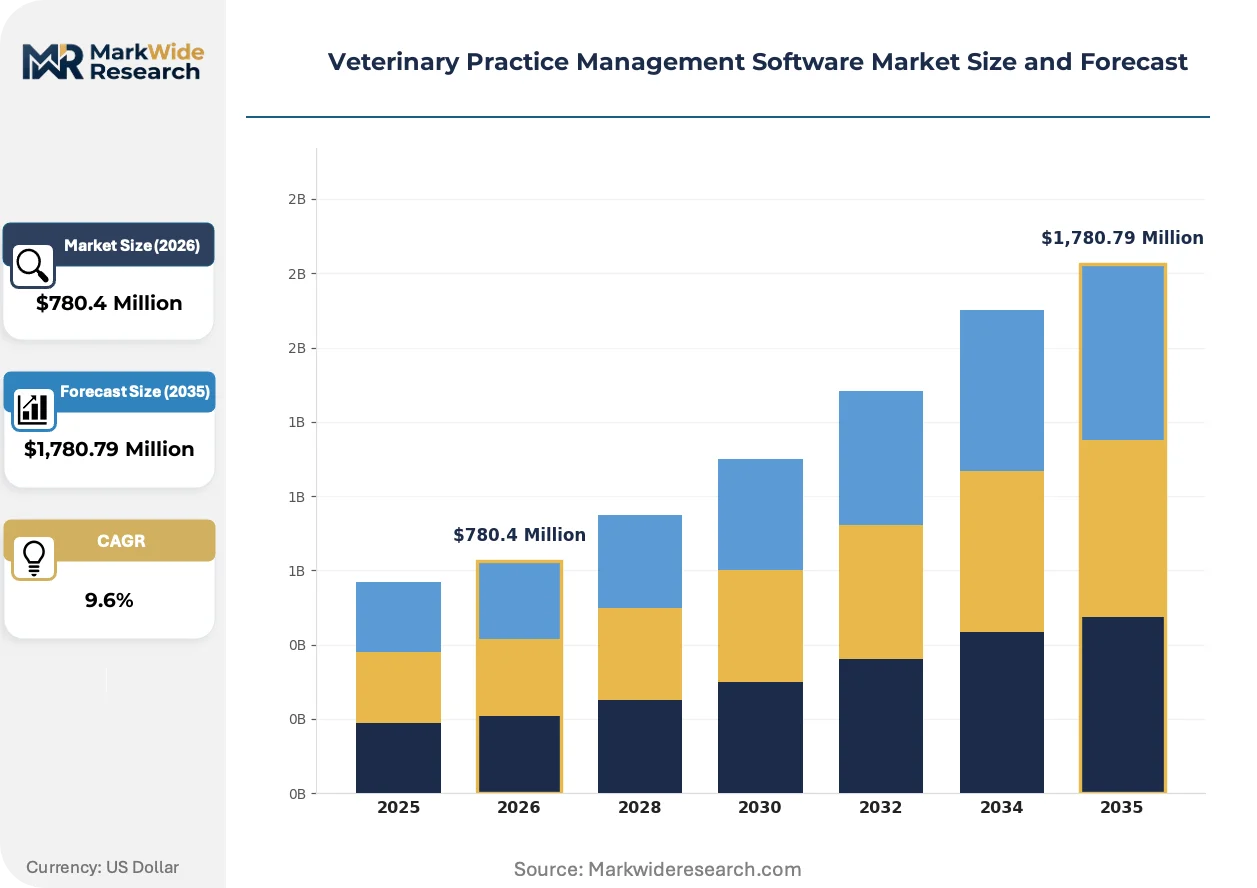
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,780.79 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Licensed Solution Type: Appointment Scheduling, Billing Management, Inventory Control, Patient Records, Telemedicine, Reporting Tools End User: Veterinary Clinics, Referral Centers, Animal Hospitals, Mobile Clinics, Research Facilities Integration Level: Standalone, Integrated Practice Suites, Third-Party API, Laboratory Management Systems, Financial Software |
| Companies Covered | Vetspire, Provet Cloud, ezyVet, AVImark, DaySmart Vet, Covetrus Pulse, Digitail, Cornerstone, Shepherd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Practice Management Software Market Strategic Shifts & Innovations
The market's evolution is defined by a move from simple administrative record-keeping to intelligent clinical workflow automation. This transition prioritizes platforms that can actively enhance diagnostic accuracy, streamline operations in multi-site clinics, and improve client engagement through digital channels.
Artificial intelligence serves as a clinical decision support tool within modern software. Large animal hospitals and specialty referral centers are the primary adopters of AI for analyzing diagnostic images and unstructured clinical notes. This advanced analytical capability is expanding into routine wellness examinations and preventative care planning, augmenting the veterinarian's diagnostic process.
Europe's General Data Protection Regulation (GDPR) imposes strict rules on processing client data. This regulation forces software developers to embed functionalities for data access requests, consent management, and data portability directly into their platforms. Client communication and marketing modules are the most affected, requiring complete workflow redesigns to ensure auditable compliance for clinics operating within the EU.
Veterinary practices are demonstrating a clear preference for API-first platforms over traditionally closed, monolithic systems. This behavioral shift disrupts the vendor lock-in model by allowing clinics to assemble a custom technology stack using specialized third-party applications. The trend is most prominent in developed markets like the United States and Germany, which feature a mature ecosystem of compatible veterinary technology applications.
Veterinary Practice Management Software Market Segmentation
Market segmentation provides a critical lens for understanding the diverse needs and technological preferences within the veterinary practice management software industry. This analysis highlights how different deployment models, solution types, end-user profiles, and integration levels shape vendor strategies and product development roadmaps.
Deployment:
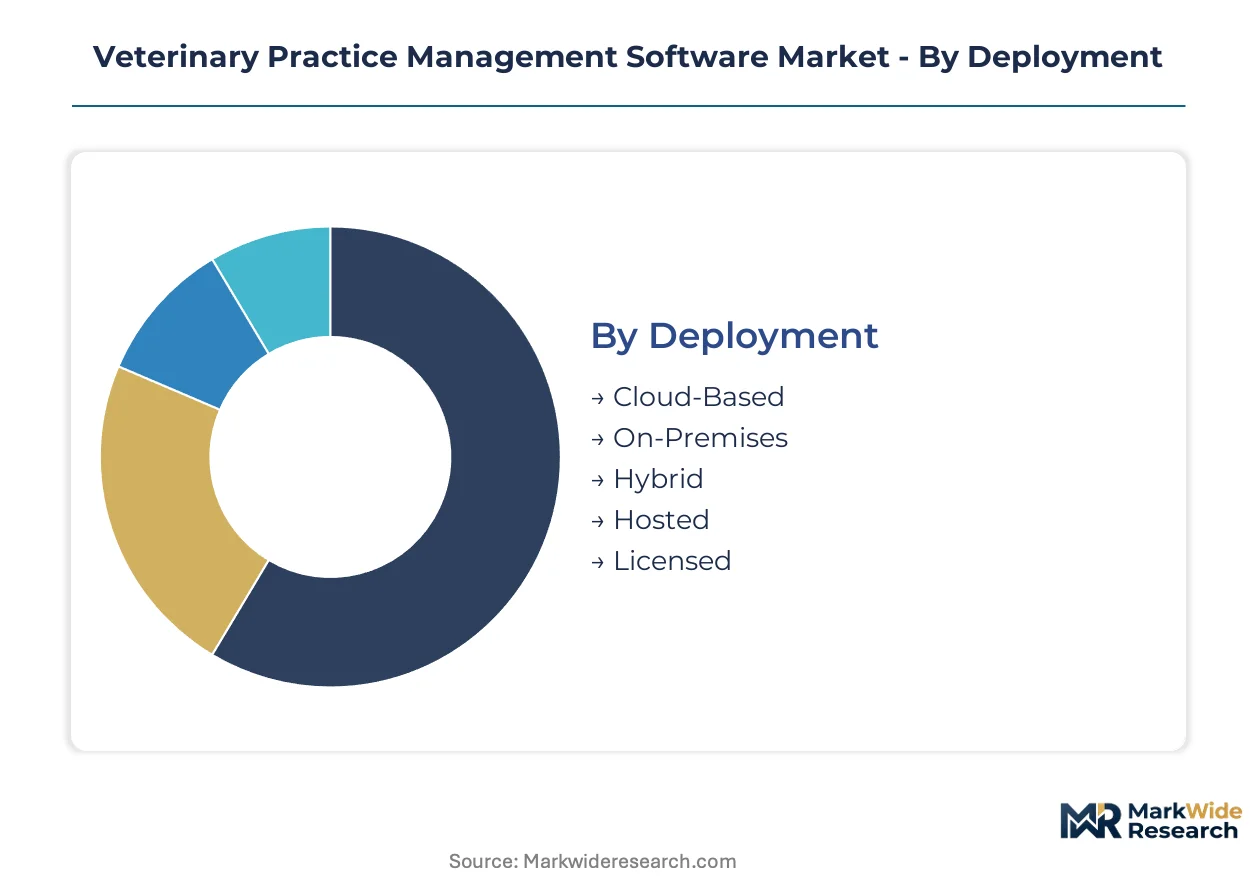
The market for veterinary practice management software exhibits a clear volume versus premium split in deployment models, with cloud-based solutions capturing the premium segment due to their advanced capabilities and accessibility.
- Cloud-Based:These platforms host software and data on remote servers, delivering services over the internet. Developed markets like the United States and Germany show strong demand for these scalable solutions, driven by benefits such as remote access and reduced IT infrastructure costs.
- On-Premises:Software installed and run locally on a clinic's own servers and computers, requiring in-house IT management. Many established, independent veterinary practices continue to utilize these systems, often due to significant prior investment and a reluctance to migrate historical data.
- Hybrid:This model combines elements of both on-premises and cloud-based deployments, allowing clinics to store sensitive data locally while leveraging cloud services for other functions. This offers a transitional pathway for practices modernizing their IT infrastructure.
- Hosted:Third-party providers manage the software and infrastructure, offering a dedicated environment that is not fully cloud-native. This option appeals to clinics seeking managed services without the full multi-tenancy of public cloud.
- Licensed:Traditional software purchase model where a clinic buys a perpetual license to use the software, typically installed on-premises. This model is seeing declining adoption for new installations.
Mature deployment sits with On-Premises solutions. Newer deployment is concentrated in Cloud-Based platforms.
Solution Type:
Solution types categorize the core functionalities offered by practice management software, with clinical workflow automation and client engagement tools driving significant innovation.
- Patient Records:Digital systems for managing comprehensive pet health histories, including diagnoses, treatments, medications, and vaccination schedules. This functionality is critical for large animal hospitals and specialty referral centers, ensuring accurate data for complex cases and regulatory compliance.
- Telemedicine:Software modules facilitating remote veterinary consultations, diagnostics, and monitoring through video calls, chat, and digital image sharing. The integration of these tools into comprehensive platforms is a key technological factor for multi-location veterinary clinics seeking to expand service reach.
- Appointment Scheduling:Tools for managing and optimizing clinic calendars, client bookings, and staff availability. This feature streamlines front-office operations for busy veterinary clinics.
- Billing Management:Systems handling invoicing, payment processing, insurance claims, and financial reporting for veterinary services. Efficient billing is essential for the financial health of all practice types.
- Inventory Control:Modules for tracking pharmaceuticals, supplies, and equipment within a veterinary practice. Accurate inventory management reduces waste and optimizes purchasing for animal hospitals.
- Reporting Tools:Features that generate customized reports on clinic performance, patient trends, and financial metrics. These tools provide valuable insights for practice managers and corporate veterinary groups.
The fastest-growing segment is Telemedicine, driven by the expansion of remote care options and client convenience.
End User:
The end-user segmentation reflects the diverse operational scales and specialized requirements across the veterinary care ecosystem.
- Animal Hospitals:Large facilities offering a wide range of services, including emergency care, surgery, and specialized treatments, often requiring sophisticated integrated software. These institutions drive demand for advanced features like integrated laboratory management systems and detailed reporting tools.
- Veterinary Clinics:General practice facilities providing routine health check-ups, vaccinations, and basic medical care for pets. Multi-location veterinary groups are consolidating these practices, creating a need for scalable, cloud-based software that standardizes operations.
- Referral Centers:Specialized veterinary facilities that receive patients referred from general practices for advanced diagnostics and treatments. These centers prioritize software with robust integration capabilities for diagnostic imaging and specialized medical records.
- Mobile Clinics:Veterinary practices operating from mobile units, offering on-site services to clients. These clinics benefit from cloud-based solutions providing remote access and streamlined patient record management.
- Research Facilities:Institutions involved in veterinary research, requiring software capable of managing animal populations, experimental data, and regulatory compliance. These facilities often need highly customizable data management solutions.
Demand concentration is highest in Animal Hospitals, while Mobile Clinics represents a significant growth area.
Integration Level:
Integration level defines how practice management software interacts with other systems, ranging from isolated applications to comprehensive, interconnected ecosystems.
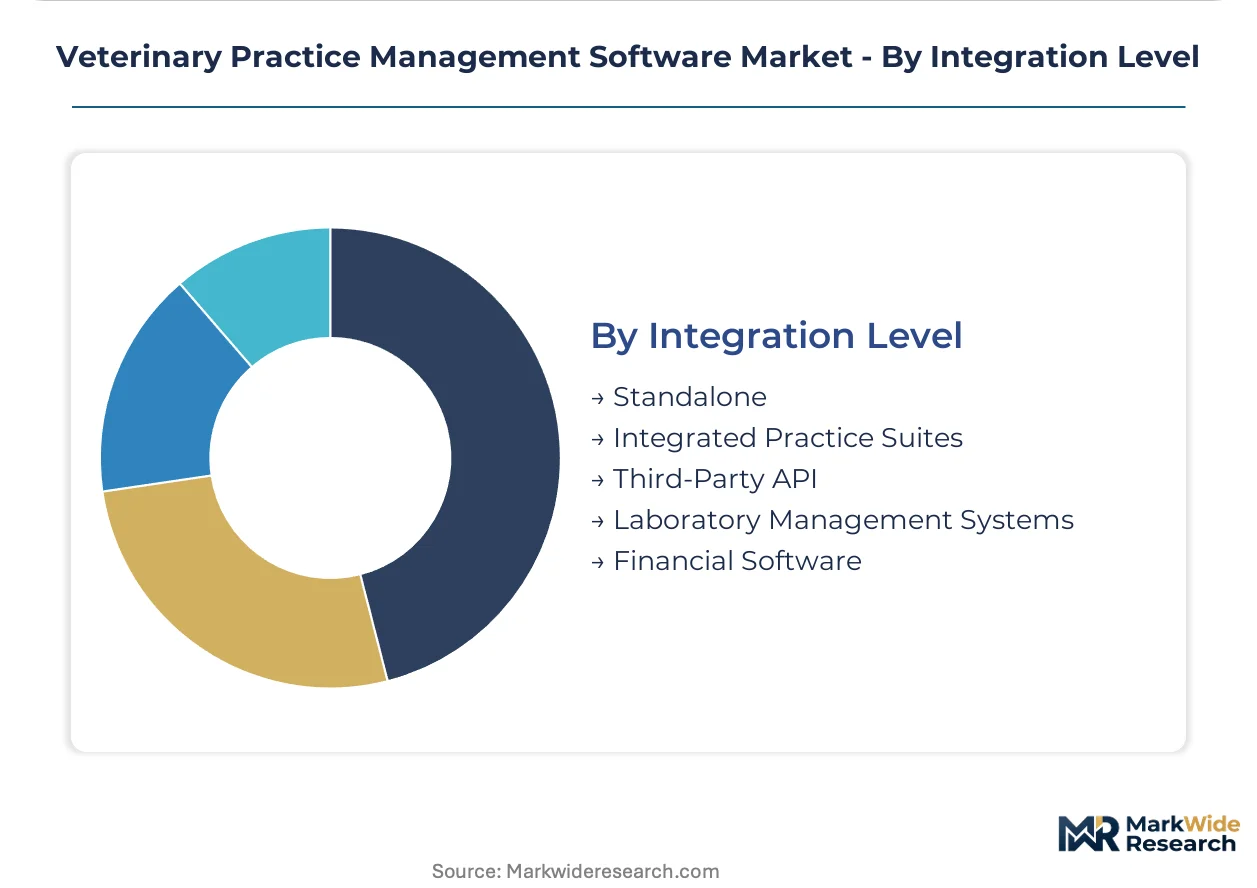
- Integrated Practice Suites:All-in-one software solutions combining multiple functionalities like patient records, billing, and scheduling into a single platform. These suites appeal to clinics seeking a unified system from one vendor.
- Third-Party API:Platforms designed with open Application Programming Interfaces, allowing seamless connection and data exchange with specialized external applications. This approach is preferred in developed markets like the United States and Germany, enabling clinics to assemble custom technology stacks.
- Standalone:Single-function software tools that operate independently without integration into a broader practice management system. These tools often serve niche needs for small practices.
- Laboratory Management Systems:Software specifically designed to manage laboratory requests, results, and equipment integration. This integration level is crucial for animal hospitals with in-house diagnostic capabilities.
- Financial Software:Integration with external accounting and financial management platforms for comprehensive business oversight. This connection streamlines financial reporting and compliance for veterinary groups.
The market is evolving towards Third-Party API integration, with Integrated Practice Suites still holding considerable installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area, a hub for technology innovation, anchors significant development in veterinary practice management software. This region drives demand for advanced cloud-native solutions and AI-driven diagnostic tools. Developed markets prioritize comprehensive, integrated platforms.
United States
United States veterinary clinics demand scalable cloud-based software for multi-site operations and advanced telemedicine capabilities. HIPAA principles guide best practices for securing sensitive pet health data, influencing software design. The Boston-Cambridge biotech cluster sees significant investment in veterinary health tech startups, developing AI-powered diagnostic tools.
Germany
Germany's veterinary market prioritizes comprehensive cloud-based platforms and API-first solutions, reflecting a mature technology ecosystem. Europe's GDPR imposes strict rules on client data processing, necessitating robust consent management features. Munich's technology sector fosters innovation in veterinary software, supporting advanced practice management solutions.
Brazil
Brazil presents strategic opportunities for localized, cost-effective software versions, serving its growing pet population. ANVISA regulations influence the development and deployment of veterinary health technology solutions. São Paulo's urban centers drive demand for mobile clinics and accessible veterinary services, creating new software deployment opportunities.
United Kingdom
United Kingdom practices seek software supporting practice consolidation and improved client engagement through digital channels. GDPR regulations profoundly shape client communication and data storage modules within veterinary software. London's vibrant tech scene supports developers creating advanced practice management tools for operational efficiency.
Japan
Japan's market shows demand for specialized software modules, particularly for high-value fields like oncology or ophthalmology. PMDA guidelines influence the development of veterinary medical device software components. Tokyo's metropolitan area leads in adopting sophisticated imaging and laboratory management systems, supporting advanced veterinary care.
Veterinary Practice Management Software Market Key Industry Players
Premium-margin players sit above commodity-margin players across the solution complexity dimension, creating a tiered market structure. This market shows a clear bifurcation between closed, all-in-one software suites and open, API-centric platforms. Two main archetypes emerge: comprehensive suite providers targeting large animal hospitals and flexible platform providers catering to multi-site clinics. Strategic partnerships, portfolio diversification, and targeted acquisitions are dominant competitive moves.
Within the integrated suite segment, Provet Cloud leverages its modern architecture to effectively serve multi-site clinic groups, representing a scalable cloud-native approach for consolidating practices. Covetrus Pulse differentiates by deeply connecting its software to a wider supply chain and integrated pharmacy services network, emphasizing comprehensive ecosystem integration. Cornerstone further exemplifies established providers, offering robust, comprehensive solutions that appeal to a broad base of veterinary practices seeking a unified system. These companies anchor market evolution through distinct strategic focuses, shaping competitive positioning.
| Leading Market Players |
|---|
| Vetspire |
| Provet Cloud |
| ezyVet |
| AVImark |
| DaySmart Vet |
| Covetrus Pulse |
| Digitail |
| Cornerstone |
| Shepherd |
| Others |
Cost & Logistics Intelligence
Multi-location veterinary groups' demand for standardized platforms shapes subscription-based pricing. This concentration of purchasing power influences vendor strategies for feature bundling and service level agreements.
Pricing Analysis
Value derived from enhanced clinic throughput anchors pricing for advanced veterinary practice management software. The dominant pricing model is SaaS-tiered subscription, offering scalability for diverse practice sizes. Price differentiation stems from customization levels for specialized fields like equine medicine and the extent of after-sales service and support. Pricing pressure stems from the high total cost of ownership for smaller, independent practices. Solo practitioners represent the most price-sensitive segment, while large animal hospitals prioritize comprehensive feature sets.
Supply Chain Analysis
Dual-sourcing requirements for critical software components are not prevalent in this market, as proprietary platforms dominate. The primary "supply" of software development talent concentrates in developed markets like the United States and Germany. Key dependencies include cloud infrastructure providers and specialized AI/telemedicine API vendors. A structural risk is vendor lock-in, hindering data interoperability. Distribution runs through direct sales teams and channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary practice management software market is becoming a vertical-integration race, with vendors pursuing deeper control over integrated pharmacy services. This strategic move aims to capture more value across the entire veterinary supply chain.
For Market Incumbents:
Cement market leadership by expanding API ecosystems to fend off niche solution providers. Incumbents should invest in AI-driven diagnostic tool integration to counter emerging tech-focused entrants. Strengthening data privacy compliance for GDPR and HIPAA principles across all modules reinforces platform stickiness. Prioritize capacity additions in cloud infrastructure to support multi-site clinic groups.
For New Entrants and Emerging Players:
Veterinary distributors and equipment manufacturers offer strategic entry points for new software solutions. Target underpenetrated mobile clinics and specialized practices like equine medicine with cost-effective, cloud-based modules. A go-to-market angle involves offering flexible, API-first solutions that integrate seamlessly with existing legacy systems. This allows for incremental adoption without full data migration risks.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor cloud-native platform providers in developed markets like the United States. Long-term viability hinges on platforms capable of handling diverse species data and regulatory compliance over a 5-10 year window. Acquisition targets include specialized AI diagnostic tool developers and telemedicine solution providers. The signal to watch is accelerating consolidation among multi-site veterinary groups, indicating a demand for scalable, integrated platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-powered diagnostic module | Enhances clinical decision support and diagnostic accuracy for large animal hospitals. |
| Platform Integration: Deep integration with pet insurance providers | Streamlines billing and claims processing, improving client financial experience. |
| Strategic Partnership: Collaboration with veterinary pharmaceutical suppliers | Extends supply chain connectivity and optimizes inventory management for clinics. |
| Acquisition of Specialist Firm: Acquiring a niche equine medicine software company | Captures market share in high-value, specialized veterinary segments. |
| Geographic Expansion: Localized software versions for Brazil | Penetrates emerging markets with growing pet populations and unique regulatory needs. |
Research Approach
Trade association data, regulatory filings, and academic research anchored secondary inputs, complemented by primary interviews with veterinary practice managers, software engineers, and IT procurement officers. This approach combined top-down market sizing with bottom-up validation of segment-specific dynamics. Secondary data sources included SEC filings of public companies and veterinary industry reports.
Data-stream reconciliation across multiple sources informed the quantitative model, projecting market evolution over the projection horizon. Segmentation dimensions modeled included deployment model, solution type, end-user profile, and integration level, alongside regional adoption patterns. Compound annual growth rates were derived by analyzing historical trends and future demand drivers. Key forecast inputs included pet population growth rates and veterinary technology investment trends.
Caveats apply where rapid technological advancements in AI or unforeseen regulatory changes could materially shift the outlook. Forecasts reflect assumptions documented regarding market dynamics and competitive landscape. Deviation in pet insurance penetration rates or global economic stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Global Dental Software Market