
 Integrated Operating Room Management Systems Market | 2026-2036
Integrated Operating Room Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Operating Room Management Systems Market Foresight
Modular platform bundling is hardening as the dominant procurement configuration for integrated operating room management systems, with hospitals favoring expandable core systems over point solutions. Stryker Corporation leverages its surgical hardware footprint to anchor comprehensive ecosystem plays. Epic Systems Corporation sustains dominance in electronic health record interoperability, a critical gateway for OR data flows. Getinge AB competes through specialized infection control and surgical workflow integration.
Integrated operating room management systems coordinate surgical instrumentation, imaging, software, and human workflow through centralized command interfaces, typically operating on sub-100-millisecond latency requirements for real-time device synchronization. Their primary commercial purpose is eliminating procedural delays, reducing turnover times, and capturing complete perioperative data for quality and billing accuracy. Software solutions command the deepest margin pools as recurring-license architectures displace perpetual deployments. Cloud-based delivery is expanding fastest among surgical centers lacking capital for on-premises infrastructure. Workflow management applications attract concentrated R&D investment as predictive scheduling algorithms demonstrate measurable block-time recovery.
FDA software-as-medical-device guidance and HIPAA security rule enforcement jointly elevate compliance costs for vendors seeking US hospital access. The EU Medical Device Regulation imposes additional clinical validation burdens on OR software modules marketed in Europe. Stakeholders must monitor whether emerging AI-driven surgical decision support triggers reclassification under stricter premarket approval pathways.
Market Dynamics
Health system consolidation is compressing vendor procurement cycles, forcing integrated operating room management system suppliers to restructure pricing architectures around enterprise-wide licensing rather than individual facility deployments.
Growth Catalysts
- HIPAA Security Rule enforcement:US hospitals face escalating penalties for perioperative data breaches, accelerating replacement of legacy OR documentation systems with encrypted, audit-ready platforms.
- Academic medical center expansion:Teaching hospitals in the United States are consolidating surgical service lines across multiple campuses, creating demand for unified command interfaces that synchronize instrumentation, imaging, and staffing across distributed OR networks.
- Predictive scheduling algorithms:Machine learning models trained on historical block utilization patterns are recovering 12-18 minutes of lost OR time per day, delivering measurable ROI that justifies capital outlays for integrated platforms.
Market Restraints
- FDA software-as-medical-device premarket notification:Vendors face 90-180 day review cycles and substantial documentation burdens for AI-driven surgical decision support modules, delaying revenue recognition and elevating compliance costs.
- EU Medical Device Regulation clinical validation:OR software modules marketed in Europe require prospective clinical studies under MDR Annex XIV, imposing cost structures that disadvantage smaller vendors without existing trial infrastructure.
- Cloud infrastructure concentration:Surgical centers lacking capital for on-premises deployments depend on third-party cloud providers, creating vendor lock-in risks and data sovereignty complications for cross-border health systems.
Strategic Opportunities
- Ambulatory surgical center penetration:Freestanding ASCs in the United States represent an underpenetrated channel where subscription-based SaaS delivery models bypass capital constraints that block traditional hospital sales cycles.
- ISO 13485 quality management convergence:Vendors achieving unified certification across hardware and software quality systems can accelerate regulatory submissions in multiple jurisdictions, compressing time-to-market for integrated platform bundles.
- Interoperability incentive programs:US federal reimbursement adjustments for hospitals demonstrating seamless EHR-OR data exchange create procurement tailwinds for vendors with certified Epic Systems Corporation integration pathways.
Industry Challenges
- Perioperative informatics specialist scarcity:Health systems struggle to recruit clinical engineers capable of configuring sub-100-millisecond latency device synchronization, forcing vendors to absorb implementation costs or risk deployment failures.
- Legacy anesthesia information system integration:Proprietary data formats from entrenched vendors create middleware development burdens that erode margin on initial platform sales and complicate ongoing support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Operating Room Management Systems Market |
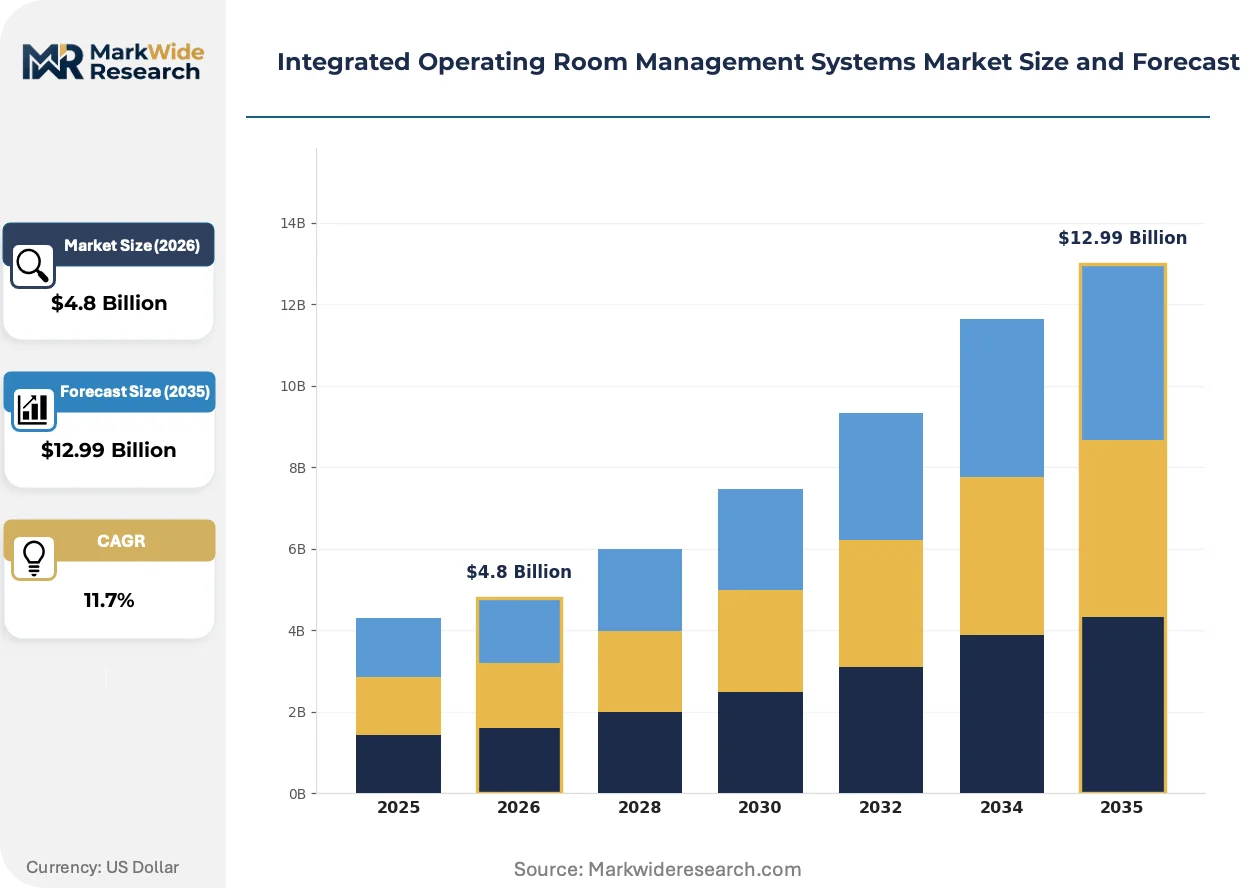
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instrumentation, Imaging Systems, Software Solutions, Workflow Management End User: Hospitals, Surgical Centers, Ambulatory Care Facilities, Clinics Technology: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Applications Application: Integration, Scheduling, Inventory Management, Patient Tracking |
| Companies Covered | Oracle (Cerner Corporation), Epic Systems Corporation, Surgical Information Systems, Stryker Corporation, STERIS Corporation, Getinge AB, Olympus Corporation, GE Healthcare, Brainlab AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Operating Room Management Systems Market Shifts & Advancements
Real-time device synchronization protocols are reshaping competitive differentiation, with latency performance replacing feature breadth as the primary procurement evaluation criterion for integrated OR platforms.
Edge computing architectures for surgical device control is expanding into mid-tier community hospitals previously priced out of integrated OR deployments. These facilities adopt modular core systems with expandable device connectivity rather than comprehensive turnkey installations. The technology is compressing implementation timelines from 18 months to 6-8 weeks, enabling vendors to penetrate satellite campuses of consolidating health systems.
EU Medical Device Regulation software classification guidance is redefining regulatory pathways for AI-enabled surgical modules. The policy elevates clinical validation requirements for predictive algorithms influencing operative decisions. European vendors are responding by establishing prospective trial programs in Germany and France, while US-based suppliers delay EU market entry pending clarity on predicate device strategies.
Subscription pricing for OR workflow management applications is displacing perpetual license structures among capital-constrained surgical centers. The shift transfers implementation risk to vendors and aligns payment with measurable utilization outcomes. This pattern concentrates in United States ASCs, where monthly SaaS fees preserve liquidity for equipment procurement while delivering equivalent functional capability.
Integrated Operating Room Management Systems Market Segmentation
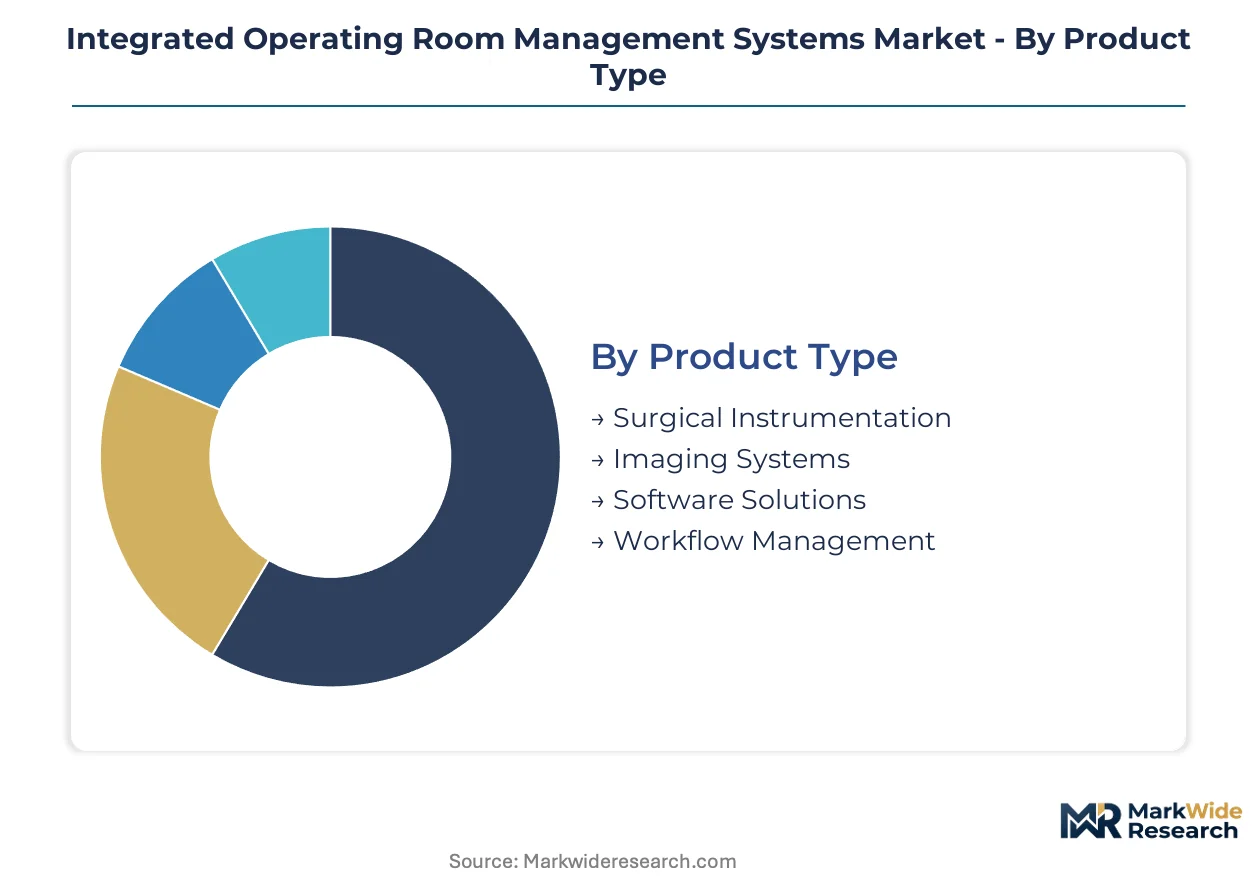
Integrated operating room management systems fragment across four critical dimensions that determine deployment architecture, procurement pathway, and vendor selection criteria. Each segmentation axis carries distinct margin profiles, regulatory burdens, and implementation timelines that shape competitive positioning.
Product Type:
Customization intensity varies sharply across this category, with hardware bundles demanding site-specific engineering while software modules scale through configuration templates.
- Software Solutions:Recurring-license architectures dominate revenue pools, with predictive analytics modules commanding premium positioning. Academic medical centers in the United States concentrate demand here, drawn by HIPAA-compliant audit trails and Epic Systems interoperability pathways.
- Workflow Management:Machine learning algorithms trained on historical block utilization patterns deliver 12-18 minutes of recovered OR time daily. Subscription pricing is displacing perpetual licenses fastest in this segment, particularly among capital-constrained surgical centers.
- Surgical Instrumentation:Device synchronization protocols operating under sub-100-millisecond latency requirements anchor physical integration layers.
- Imaging Systems:PACS connectivity and real-time visualization feeds complete the centralized command interface architecture.
Most installed capacity flows through Software Solutions. Expansion is steepest in Workflow Management.
End User:
Procurement sophistication tiers separate enterprise health systems from independent facilities, with consolidation dynamics compressing vendor pricing architectures differentially.
- Hospitals:Enterprise-wide licensing negotiations dominate, with consolidated health systems demanding unified command interfaces across distributed OR networks. FDA software-as-medical-device premarket notification requirements shape vendor development priorities for AI-driven modules deployed at this tier.
- Ambulatory Care Facilities:Freestanding ASCs represent an underpenetrated channel where SaaS delivery models bypass capital constraints blocking traditional hospital sales cycles. Monthly subscription fees preserve liquidity for equipment procurement.
- Surgical Centers:Mid-tier facilities adopt modular core systems with expandable connectivity rather than comprehensive turnkey installations.
- Clinics:Limited procedural volume constrains platform investment to basic scheduling and inventory modules.
Revenue concentration sits with Hospitals. Penetration gains are sharpest among Ambulatory Care Facilities.
Technology:
Infrastructure ownership models determine capital deployment patterns, with cloud migration accelerating among facilities lacking on-premises engineering capacity.
- Cloud-Based:Third-party hosting eliminates server infrastructure capital outlays, though data sovereignty complications emerge for cross-border health systems. Surgical centers lacking capital for on-premises deployments depend on this architecture, creating vendor lock-in risks.
- Hybrid Solutions:Edge computing for surgical device control combines local latency performance with centralized data aggregation. Implementation timelines compress from 18 months to 6-8 weeks, enabling satellite campus penetration.
- On-Premises:Full infrastructure control satisfies stringent institutional security policies at academic medical centers.
- Mobile Applications:Perioperative staff coordination tools extend platform reach beyond fixed workstation locations.
Deployment volume favors Cloud-Based infrastructure. Adoption velocity is highest for Hybrid Solutions.
Application:
Functional modules map directly to measurable ROI categories, with scheduling optimization delivering the most quantifiable returns for capital justification.
- Scheduling:Predictive algorithms recover lost block time through machine learning analysis of historical utilization patterns. Academic medical centers consolidating surgical service lines across multiple campuses create concentrated demand for synchronization capabilities.
- Integration:Real-time device synchronization protocols coordinate instrumentation, imaging, and human workflow through centralized command interfaces. Latency performance has replaced feature breadth as the primary procurement evaluation criterion.
- Inventory Management:Automated supply tracking reduces procedural delays from missing instrumentation.
- Patient Tracking:Perioperative data capture ensures billing accuracy and quality documentation completeness.
Functional deployment centers on Integration modules. Measurable ROI is strongest in Scheduling optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The integrated operating room management systems industry traces its commercial origins to the United States, where academic medical centers first deployed centralized surgical command interfaces during the 1990s. Early adoption concentrated in teaching hospitals seeking to coordinate complex multi-specialty procedures. European and Asia-Pacific markets subsequently developed distinct procurement patterns shaped by regional regulatory frameworks.
United States
Health system consolidation drives enterprise-wide OR integration investments across the United States, with consolidated networks demanding unified command interfaces across distributed surgical campuses. FDA software-as-medical-device premarket notification requirements shape vendor development priorities for AI-driven modules. The Boston-Cambridge corridor anchors concentrated vendor R&D activity, while Nashville and Dallas-Fort Worth host major health system headquarters negotiating enterprise licensing agreements.
Germany
University hospitals in Germany accelerate adoption of unified surgical platforms as regional health networks consolidate surgical service lines. EU Medical Device Regulation imposes additional clinical validation burdens on OR software modules marketed in Europe, elevating compliance costs for market entry. The Rhine-Ruhr metropolitan region and Bavaria's Munich-Stuttgart axis concentrate medical technology manufacturing clusters, with Heidelberg and Berlin hosting prominent university hospital networks piloting predictive scheduling algorithms.
Japan
Metropolitan Tokyo and Osaka health systems prioritize perioperative data capture systems ensuring billing accuracy under national health insurance frameworks. PMDA regulatory pathways for software-as-medical-device create structured premarket review timelines distinct from US FDA processes. The Kanto region surrounding Tokyo and the Kansai region centered on Osaka concentrate surgical volume, with Nagoya's Chubu region emerging as a secondary hub for mid-tier hospital system procurement.
United Kingdom
NHS England procurement frameworks favor modular platform bundling over point solutions, compressing vendor pricing architectures around standardized interoperability requirements. GDPR compliance obligations intersect with HIPAA-equivalent data protection standards for perioperative information systems. London's academic medical center cluster and Manchester's northern hub drive concentrated demand, with Cambridge and Oxford university hospitals piloting edge computing architectures for surgical device control.
India
Corporate hospital chains in India deploy cloud-based OR management systems bypassing capital constraints that block on-premises infrastructure investment. CDSCO medical device regulations for software modules remain under development, creating regulatory uncertainty for international vendors. Mumbai's private hospital corridor and Bangalore's health technology startup ecosystem concentrate adoption activity, with Delhi-NCR's Apollo-Artemis-Fortis network representing the largest consolidated procurement opportunity.
Integrated Operating Room Management Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the software-hardware integration spectrum, with recurring-license architectures commanding superior economics to perpetual deployments or hardware-centric bundles. The vendor base organizes into three recognizable tiers: diversified medical technology conglomerates with surgical hardware footprints, specialized OR software developers with EHR interoperability pathways, and emerging cloud-native workflow specialists targeting ambulatory surgical centers. Consolidation pressures intensify as health system procurement cycles compress, forcing M&A activity and strategic partnership formations to maintain enterprise account access.
Within the diversified medical technology tier, Stryker Corporation and Getinge AB occupy positions anchored by surgical hardware ecosystems that bundle integrated OR management capabilities. Epic Systems Corporation exemplifies the specialized software archetype, sustaining dominance in electronic health record interoperability that functions as a critical gateway for OR data flows. Oracle, through its Cerner Corporation acquisition, represents the scale-driven consolidation play seeking to bridge enterprise health system IT infrastructure with perioperative workflow management.
| Leading Market Players |
|---|
| Oracle (Cerner Corporation) |
| Epic Systems Corporation |
| Surgical Information Systems |
| Stryker Corporation |
| STERIS Corporation |
| Getinge AB |
| Olympus Corporation |
| GE Healthcare |
| Brainlab AG |
| Others |
Supply & Pricing Matrix
Perioperative informatics specialists concentrated in the Boston-Cambridge corridor command compensation premiums that compress margins at the premium tier while enabling aggressive SaaS pricing for mid-market ambulatory surgical centers. Labor-cost differentials between academic medical center deployments and freestanding ASCs drive pricing-tier spreads exceeding threefold across equivalent functional modules.
Pricing Analysis
Subscription-based SaaS delivery dominates commercial configurations, with monthly recurring fees displacing perpetual licenses fastest among capital-constrained surgical centers. Price differentiation rests on HIPAA compliance certification tier and Epic Systems interoperability pathway depth. Pricing pressure stems from health system consolidation compressing enterprise licensing negotiations. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize latency performance over cost.
Supply Chain Analysis
Freight costs for surgical hardware components from Germany, Sweden, and Japan elevate landed costs for integrated instrumentation bundles. Raw material dependencies center on medical-grade stainless steel, specialized optical sensors, and edge-computing processors. Single-source vulnerability concentrates in cloud infrastructure providers serving cross-border health systems. Distribution runs through regional medical device distributors with GPO contract access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The integrated operating room management systems market functions as a regulatory compounder, with FDA software-as-medical-device premarket notification requirements continuously elevating compliance barriers that favor established vendors with dedicated regulatory affairs infrastructure.
For Market Incumbents: Deepen vertical integration into edge-computing hardware to secure sub-100-millisecond latency performance guarantees against cloud-native entrants. Prioritize ISO 13485 unified certification across software and hardware quality systems to accelerate multi-jurisdictional regulatory submissions. Defensive consolidation of perioperative informatics specialist talent pools in the Boston-Cambridge corridor limits implementation cost absorption. For New Entrants and Emerging Players: Cloud-native SaaS delivery routes bypass capital constraints blocking traditional hospital sales cycles and penetrate freestanding ASCs with minimal field engineering footprint. Target ambulatory surgical centers in the United States Sun Belt corridor where health system consolidation has not yet captured independent facilities. Lead with predictive scheduling algorithms demonstrating measurable block-time recovery to justify subscription fees. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with surgical hardware footprints are the most active acquirers in this space, seeking software capabilities to anchor ecosystem plays. Long-term viability favors vendors with demonstrated Epic Systems interoperability pathways and recurring-license architectures exceeding sixty percent of revenue mix. Watch FDA guidance on AI-driven surgical decision support reclassification as the critical inflection signal for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market access for AI-driven surgical decision support modules under premarket notification. |
| Epic Systems Interoperability Certification | Unlocks enterprise health system procurement governed by federal reimbursement incentive programs. |
| ISO 13485 Unified Certification | Compresses time-to-market for integrated platform bundles across US and EU regulatory jurisdictions. |
| Hospital System Partnership | Secures reference sites for predictive scheduling algorithms demonstrating measurable OR time recovery. |
| Ambulatory Surgical Center SaaS Launch | Captures underpenetrated channel where monthly subscription fees preserve liquidity for equipment procurement. |
Research Methodology
Direct dialogue with OR directors, biomedical engineers, GPO contracts managers, and perioperative informatics specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and GPO contract archives. Bottom-up and top-down triangulation reconciled vendor shipment data with health system capital expenditure disclosures across the analysis window.
Bottom-up modeling segmented deployment volume by product type, end user tier, technology infrastructure, and application module across the projection horizon. Top-down approaches validated aggregate market scale against health system IT spending benchmarks and surgical procedure volume growth. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory milestone impacts. Forecast inputs incorporated health system consolidation timelines and FDA software-as-medical-device review cycle durations.
The model assumes a particular technology adoption path; alternative pathways for edge-computing architectures displacing cloud-hosted deployments would alter the outlook. Forecasts reflect assumptions regarding HIPAA enforcement intensity and EU MDR clinical validation burden stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Secure Messaging in Healthcare Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Global Personal Health Records Software Market