
 Docking System Market | 2026-2036
Docking System Market Size, Share, and Industry Trends Forecast 2026-2036
Docking System Market Analytics
Multi-source procurement for steel fabrication and hydraulic actuators is hardening as port operators seek supply chain resilience against raw material volatility. Kawasaki Heavy Industries leverages its shipbuilding heritage to dominate heavy-duty fixed installations for cargo terminals. Semmco anchors its position through specialized access platforms for vessel maintenance applications. Zarges competes with lightweight aluminum modular systems that reduce crane dependency during assembly.
A docking system is a mechanical or electromechanical platform that secures vessels to shore infrastructure, typically incorporating fendering, mooring winches, and gangway assemblies rated for specific load classes and tidal ranges. Its primary commercial purpose is to enable safe, efficient transfer of passengers, cargo, and maintenance personnel between watercraft and land-based facilities. Fixed docking systems occupy the mature revenue base at major container ports where capital-intensive permanent infrastructure dominates. Automated docking technology is capturing the fastest expansion as ports integrate sensor-guided mooring and autonomous line handling to reduce turnaround times. Hydraulic docking systems concentrate margin pools where custom engineering for heavy-lift cargo vessels commands premium pricing.
ISO standards for maritime fendering and mooring equipment shape baseline safety requirements, while the EU Green Deal's port emissions directives are accelerating demand for electrified and automated berthing solutions in European harbors. The US Coast Guard and OSHA maritime safety regulations enforce structural load certifications and worker protection protocols that influence system design and installation protocols. Stakeholders must monitor how evolving cybersecurity frameworks for port automation will reshape procurement criteria for remote control and integrated docking architectures.
Market Dynamics
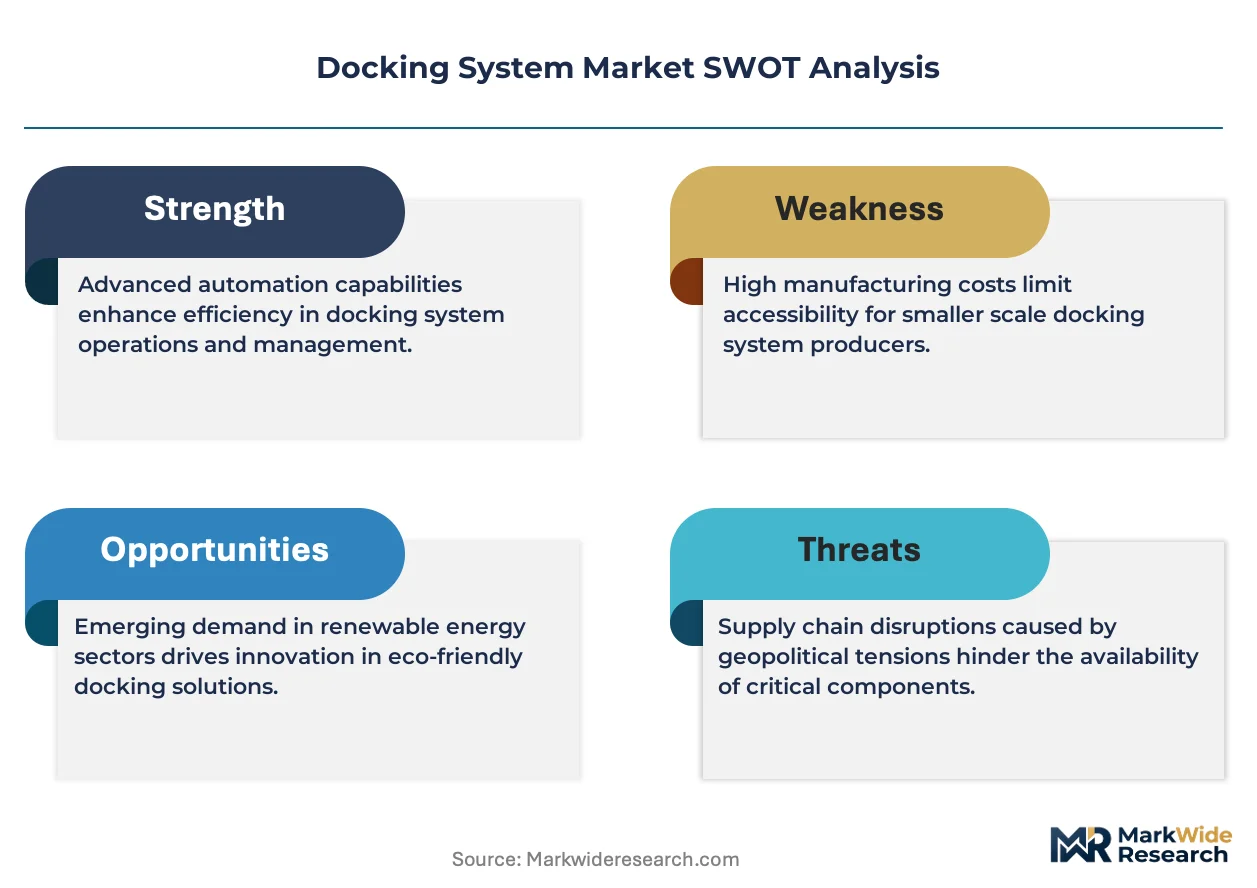
EU Green Deal emissions mandates are forcing port authorities to accelerate electrification of berthing infrastructure and automated mooring systems, reshaping capital allocation across maritime logistics networks.
Growth Catalysts
- EU Green Deal port emissions directives:Tighter berthing emission standards in Hamburg and Bremen are compelling terminal operators to install shore power connections and automated docking to cut vessel idling.
- Container throughput concentration:Mega-ports handling transshipment volumes exceeding 15 million TEU annually require synchronized mooring systems to compress turnaround windows and maximize quay utilization.
- Sensor-guided mooring technology:Laser positioning and tension-monitoring arrays enable single-operator line handling, reducing labor headcount per berthing operation by half.
Market Restraints
- Steel and hydraulic actuator cost volatility:Port operators face margin compression when commodity price swings disrupt fixed-price installation contracts.
- Specialized fabrication capacity concentration:Heavy-duty fendering and winch assembly relies on a narrow base of certified maritime steelworkers clustered in Northern European shipbuilding regions.
- Legacy quay structural load limits:Older container terminals built for 1960s vessel dimensions cannot support automated mooring tension loads without costly foundation reinforcement.
Strategic Opportunities
- Offshore wind service vessel integration:Crew transfer vessels and jack-up barges for turbine maintenance require dedicated docking systems at marshalling ports in Germany and the Netherlands.
- Shore power infrastructure mandates:EU Alternative Fuels Infrastructure Regulation is creating bundled procurement opportunities combining electrified berthing with automated mooring.
- Convergence of IoT sensors and predictive maintenance:Mooring load monitoring data streams enable condition-based service contracts, shifting vendor revenue from hardware to recurring software subscriptions.
Industry Challenges
- Maritime automation technician scarcity:Port authorities struggle to recruit control systems engineers capable of integrating sensor arrays with legacy terminal operating systems.
- ISO 17357 fendering certification timelines:New materials testing protocols extend product approval cycles, delaying revenue recognition for innovative composite fender designs.
- Interoperability with proprietary terminal software:Automated docking systems must interface with vendor-specific quay crane management platforms, complicating system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Docking System Market |
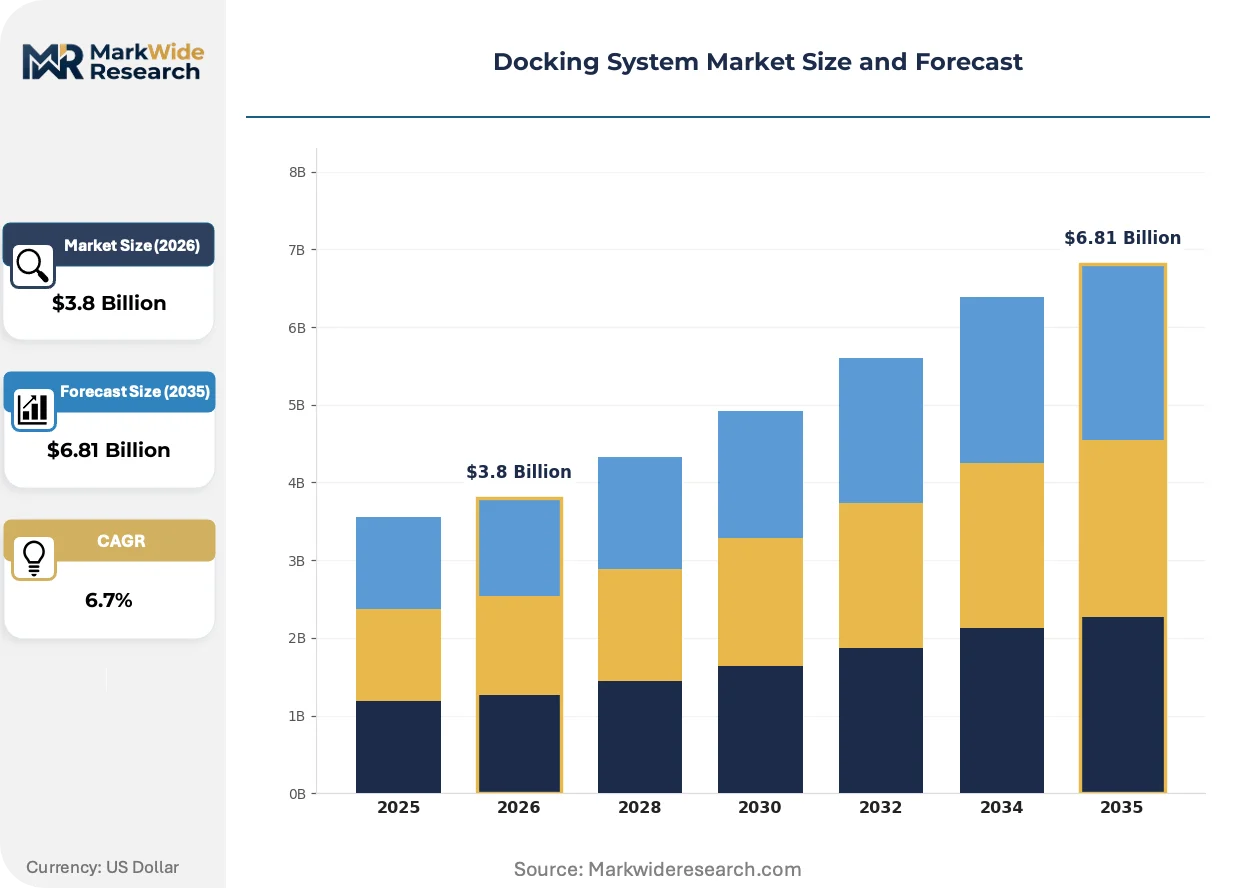
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Docking Systems, Floating Docking Systems, Mobile Docking Systems, Hydraulic Docking Systems End User: Shipping Companies, Fishing Industry, Recreational Boats, Maritime Services Technology: Manual Docking, Automated Docking, Remote Control Systems, Integrated Docking Solutions Application: Cargo Transport, Vessel Maintenance, Passenger Transfers, Emergency Services |
| Companies Covered | Kawasaki Heavy Industries, NIJL Aircraft Docking, Semmco, Fortal, Shanghai Ifly GSE, DAE Industries, CTI Systems, Instant Upright, Zarges, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Docking System Market Evolving Landscape
Electrification of berthing infrastructure and autonomous line handling are compressing vessel turnaround times while regulatory pressure on port emissions accelerates technology refresh cycles.
Electro-hydraulic mooring winches with regenerative braking are electrifying heavy-load vessel securing at container terminals. Hamburg port operators are retrofitting existing quays with these systems to meet EU Green Deal shore power mandates. The technology is compressing maintenance intervals from mechanical wear while enabling remote diagnostics that reduce on-site technician visits.
EU Green Deal port emissions directives are mandating cold-ironing infrastructure and zero-emission berthing zones at major harbors. Terminal operators in Bremen must install automated mooring to qualify for green port certification and public funding. Container handling facilities are responding by bundling electrified docking with shore power in single procurement packages.
Long-term service agreements with guaranteed uptime commitments are displacing traditional equipment purchase and break-fix maintenance models. Port authorities in Rotterdam and Antwerp now favor 10-year performance contracts where vendors retain ownership of mooring hardware. This shift concentrates vendor risk on reliability engineering while transferring capex burdens from public balance sheets to private infrastructure funds.
Docking System Market Segmentation
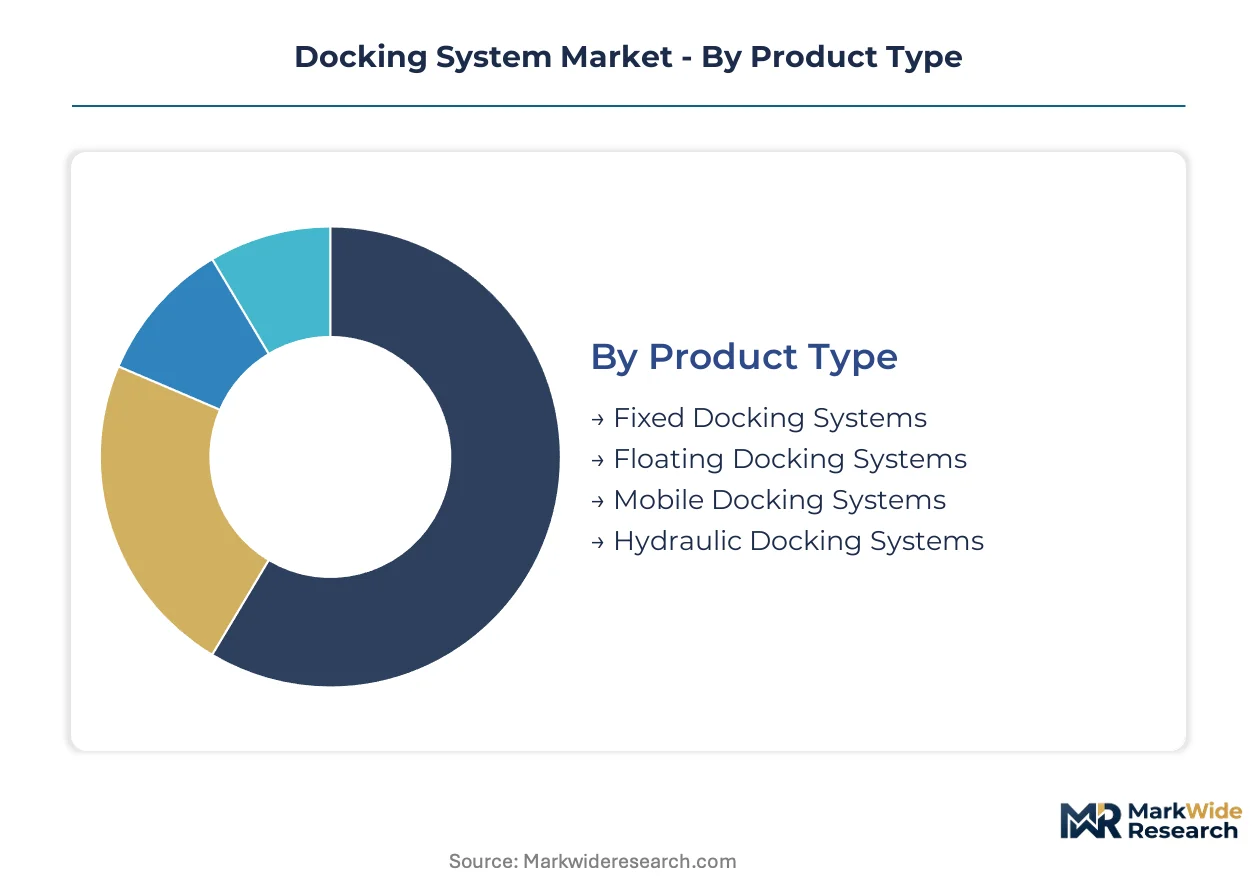
Docking system procurement varies sharply by operational intensity and integration depth. Ports handling transshipment volumes above 10 million TEU annually favor permanently installed infrastructure, while seasonal harbors and offshore wind service bases prioritize reconfigurable platforms that adapt to vessel class mix.
Product Type:
Fixed installations dominate permanent quay infrastructure where tidal range and load class are predictable, while floating and mobile variants serve temporary or variable-waterline applications.
- Fixed Docking Systems:Steel-reinforced concrete quay walls with integrated fendering and bollard arrays rated for Panamax and Neo-Panamax vessel dimensions. Hamburg and Bremen port authorities specify these for container terminals where 50-year asset life justifies capital-intensive foundation work and EU Green Deal shore power retrofit compatibility.
- Floating Docking Systems:Pneumatic or foam-filled pontoon assemblies that adjust to tidal variation without fixed pilings. Marinas in the Netherlands deploy these for recreational craft and crew transfer vessels where water level fluctuation exceeds 3 meters and permanent structures face environmental permitting barriers.
- Mobile Docking Systems:Modular ramp and gangway units repositionable by terminal tractors. Offshore wind service ports in Germany use these to switch between jack-up barge and crew transfer vessel configurations during turbine maintenance campaigns.
- Hydraulic Docking Systems:Electro-hydraulic winch and tension-monitoring arrays for heavy-lift cargo securing. Custom engineering for bulk carriers and Ro-Ro vessels commands premium pricing where automated line handling reduces berthing crews from six operators to one.
Fixed systems lead volumes today; hydraulic variants are gaining share fastest as labor costs and EU emissions mandates accelerate automation adoption.
End User:
Customer procurement patterns split between asset-heavy fleet operators seeking long-term infrastructure partnerships and seasonal users favoring operational leasing.
- Shipping Companies:Container lines and bulk operators with dedicated terminal concessions drive demand for synchronized mooring systems that compress turnaround windows. Maersk and MSC specify automated docking compatibility in their terminal operating agreements to maximize vessel utilization rates.
- Fishing Industry:Processing trawlers and factory ships require washdown-resistant aluminum gangways and ice-rated fendering. Fleet operators in Bremerhaven prioritize quick-release mooring for tidal fishing schedules where departure windows narrow to 20-minute intervals.
- Recreational Boats:Marina developers specify low-maintenance composite materials and integrated shore power pedestals. Yacht harbors along the German Baltic coast bundle electrified berthing with automated payment systems to attract high-value slip rentals.
- Maritime Services:Pilot boat operators, tug fleets, and offshore support vessel contractors need rapid embarkation platforms. Service bases in Cuxhaven configure floating docks for 24-hour crew rotation on North Sea wind farm contracts.
Shipping companies dominate capital expenditure; maritime services are expanding most quickly as offshore wind maintenance scales.
Technology:
Control architecture sophistication determines labor substitution potential and cybersecurity exposure for port authorities.
- Manual Docking:Conventional line handling with deck-mounted capstans and bollards requiring full mooring crews. Legacy container terminals in older port districts maintain these where quay structural limits prevent automated tension loads and foundation reinforcement costs prove prohibitive.
- Automated Docking:Sensor-guided winch arrays with laser positioning and load-monitoring feedback loops. Rotterdam and Antwerp terminal operators specify these to qualify for EU Green Deal green port certification and public infrastructure funding tied to emissions reductions.
- Remote Control Systems:Radio or fiber-linked operator stations positioned away from vessel contact zones. Port authorities favor these for hazardous cargo berths where OSHA maritime safety regulations mandate minimum separation from potential release events.
- Integrated Docking Solutions:Mooring automation fused with terminal operating systems and quay crane management platforms. Full integration remains rare due to vendor-specific software protocols that complicate interoperability across equipment suppliers.
Manual systems retain installed base dominance; automated docking shows the steepest expansion trajectory as EU mandates tighten.
Application:
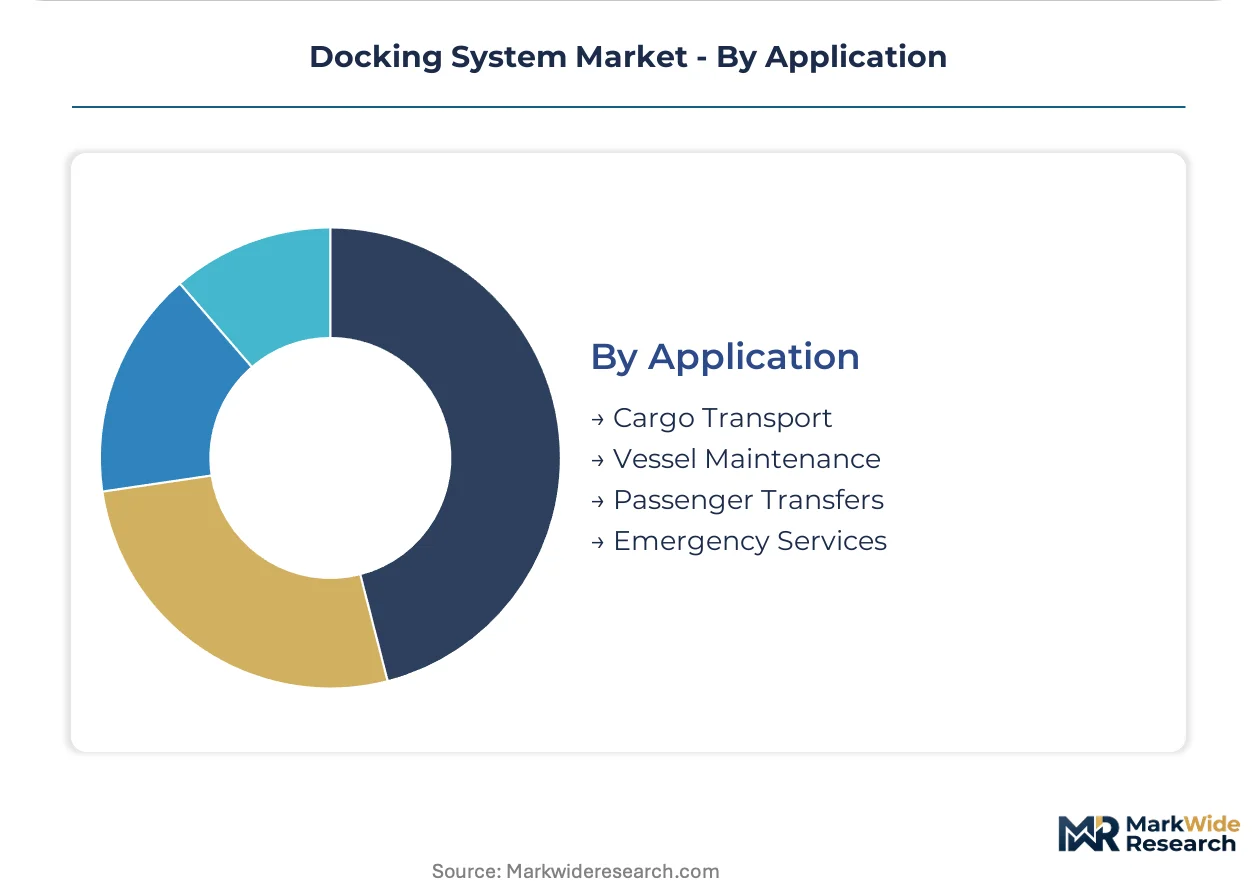
Load profile and passenger safety requirements dictate fendering energy absorption ratings and gangway motion compensation specifications.
- Cargo Transport:Heavy-duty fendering rated for 50-tonne bollard loads and continuous Ro-Ro ramp traffic. Container terminals specify these for 15 million TEU-plus annual throughput where quay utilization rates determine terminal profitability.
- Vessel Maintenance:Elevated access platforms and enclosed gangways for shipyard dry-docking preparation. Semmco specializes in these applications where worker protection protocols under OSHA and ISO standards govern platform design certification.
- Passenger Transfers:Motion-compensated gangways with tidal range adjustment for cruise and ferry operations. Port authorities in Kiel and Rostock install these to meet passenger safety regulations while minimizing embarkation delays that trigger contractual penalties.
- Emergency Services:Rapid-deployment floating docks for search-and-rescue and firefighting vessels. Coastal authorities specify military-grade aluminum construction with helicopter-lift compatibility for disaster response staging.
Cargo transport anchors revenue volumes; vessel maintenance climbs fastest as fleet renewal extends dry-docking demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port operators in lower-compliance jurisdictions attract fabrication contracts as EU Green Deal mandates elevate European production costs, while advanced economies absorb premium automation to offset labor scarcity.
Germany
Container throughput expansion at Hamburg and Bremen drives automated mooring procurement, with EU Green Deal shore power mandates compelling terminal electrification. Port authorities bundle cold-ironing infrastructure with sensor-guided berthing systems to qualify for federal infrastructure funding tied to emissions reduction targets.
Netherlands
Rotterdam's transshipment dominance requires synchronized mooring arrays to compress 15 million TEU-plus annual throughput windows. The EU Alternative Fuels Infrastructure Regulation mandates shore power at priority berths, pushing terminal operators toward integrated electrified docking procurement packages.
China
Dual carbon goals under MEE oversight accelerate port electrification at Shanghai and Ningbo-Zhoushan, the world's largest container hub. State-owned terminal operators deploy automated mooring to reduce vessel turnaround times while meeting national emissions intensity targets for maritime logistics.
United States
OSHA maritime safety regulations and US Coast Guard load certification requirements shape procurement for heavy-duty fendering at Los Angeles and Long Beach. Labor union contracts at West Coast ports create cost pressure favoring automated line handling to reduce mooring crew headcount per vessel.
South Korea
Busan port authority modernization aligns with METI-influenced automation standards for Northeast Asian transshipment competition. Government-backed infrastructure funds support sensor-guided mooring installation to maintain hub status against Chinese mega-port expansion.
Docking System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and predictive maintenance software. The vendor base stratifies across heavy industrial conglomerates with shipbuilding heritage, specialized access platform fabricators, and lightweight materials specialists. Three archetypes dominate: integrated maritime engineering groups, niche maintenance equipment specialists, and modular aluminum system providers. Competitive moves concentrate on bundling hardware with long-term service contracts and backward integration into steel fabrication to hedge commodity volatility.
Within the industrial conglomerate tier, Kawasaki Heavy Industries anchors heavy-duty fixed installation supply through its shipbuilding lineage. Semmco occupies a specialist position in vessel maintenance access platforms where worker protection certification requirements create barriers. Zarges exemplifies the lightweight materials archetype with aluminum modular systems that reduce crane dependency during port assembly operations. These three represent distinct competitive vectors: capital-intensive permanent infrastructure, regulated safety equipment, and deployable reconfigurable platforms.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries |
| NIJL Aircraft Docking |
| Semmco |
| Fortal |
| Shanghai Ifly GSE |
| DAE Industries |
| CTI Systems |
| Instant Upright |
| Zarges |
| Others |
Value Network & Pricing Analysis
Steel price indices and hydraulic actuator commodity benchmarks cascade through maritime fabrication tiers, compressing margins for standardized fendering while amplifying premiums for custom-engineered automated mooring arrays. Port operators absorb volatility through multi-year procurement contracts, yet spot-market exposure persists for maintenance spares and emergency retrofits.
Pricing Analysis
Input-cost pass-through from steel and high-grade hydraulics stratifies pricing across three performance tiers. Project-based contracting dominates heavy-duty fixed installations where Hamburg and Bremen port authorities negotiate bundled electrification packages. Price differentiation hinges on ISO 17357 certification grade and after-sales service bundling, with premium automation systems commanding substantial uplifts over mechanical alternatives. Pricing pressure stems from EU Green Deal compliance deadlines as terminal operators accelerate procurement timelines. Shipping companies exhibit lowest price sensitivity where vessel utilization rates justify automation premiums; seasonal recreational harbors resist cost escalation most acutely.
Supply Chain Analysis
Direct-to-port-authority channels handle hyperscale buyer demand for integrated quay systems, while specialized distributors serve maintenance and retrofit segments. Manufacturing concentrates in Germany, the Netherlands, and South Korea where maritime steelworker certification clusters support heavy-fendering fabrication. Supply chains draw from specialized alloy steel, electro-hydraulic actuators, and marine-grade composite fendering. Single-source vulnerability concentrates in certified hydraulic component suppliers serving automated mooring arrays. Distribution runs through terminal engineering contractors for greenfield projects and aftermarket service networks for legacy quay upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum as EU Green Deal port emissions directives harden into procurement mandates across European harbor authorities.
For Market Incumbents: Anchor market position through backward integration into steel fabrication capacity and captive hydraulic actuator supply. Kawasaki Heavy Industries exemplifies this path through shipbuilding heritage leverage. Defend against lightweight aluminum modular competitors by embedding predictive maintenance software into hardware contracts. Certification investment in EU Green Deal compliance tooling creates switching costs for port authority customers. For New Entrants and Emerging Players: Launch via offshore wind service vessel integration where marshalling port demand outpaces established vendor coverage. Target mobile docking configurations for jack-up barge and crew transfer vessel applications in Germany and the Netherlands. Crew transfer vessel rapid-configuration systems represent the most penetrable white space. Go-to-market should emphasize deployable assembly reducing crane dependency during port installation. For Investors and Strategic Acquirers: Asymmetric upside sits with predictive maintenance software platforms layered onto mooring hardware. Long-term viability favors vendors capturing recurring revenue streams from condition-based service contracts over pure equipment manufacturers. Acquisition target archetype: IoT sensor integration specialists with port automation cybersecurity credentials. Signal to watch: federal infrastructure funding disbursement velocity for EU Green Deal shore power retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captive supply of marine-grade alloys hedges commodity volatility for Hamburg terminal operators. |
| Predictive Maintenance Platform Development | Condition-based subscriptions shift vendor economics from hardware sales to recurring software revenue. |
| EU Green Deal Certification Investment | Green port compliance tooling qualifies terminal operators for federal infrastructure funding pools. |
| Offshore Wind Service Vessel Specialization | Jack-up barge configurations address turbine maintenance scaling in German North Sea clusters. |
| Long-Term Performance Contracting | 10-year uptime guarantees transfer capex burdens from Rotterdam port authorities to private infrastructure funds. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research encompassed port authority engineering directors, terminal operating system vendors, maritime steel fabrication procurement leads, and offshore wind service vessel operators. Secondary validation drew from EU Green Deal regulatory filings, Hamburg and Bremen port authority capital expenditure disclosures, ISO 17357 certification databases, and customs trade records for hydraulic actuator imports. Bottom-up installation forecasts triangulated against top-down port infrastructure spending projections.
Segment-weighting approaches distributed value across fixed, floating, mobile, and hydraulic product architectures. Technology segmentation captured manual, automated, remote control, and integrated solution penetration curves. End-user weighting reflected shipping company, fishing industry, recreational boat, and maritime service procurement patterns. Application segmentation balanced cargo transport, vessel maintenance, passenger transfer, and emergency services demand. CAGRs derived from regression analysis against container throughput expansion and regulatory compliance deadline clustering. Forecast inputs incorporated EU Alternative Fuels Infrastructure Regulation implementation pacing and offshore wind capacity installation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price spike scenarios and maritime automation technician scarcity conditions. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and port authority funding continuity. Steel price volatility, hydraulic component lead time extension, and cybersecurity framework evolution for port automation represent primary revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airship Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Fighter Aircraft Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
North America Aviation Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Military Aircraft Market
Aircraft
Aerospace Winglet System Market
Aircraft
Aircraft Cables Market
Aircraft
India Aviation Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Aircraft Radome Market