
 Middle-East and Africa Helicopters Market | 2026-2036
Middle-East and Africa Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Helicopters Market Foresight
Buyer concentration across Middle-East and Africa helicopter fleets is shifting as national oil companies consolidate vendor panels while private medical operators fragment procurement. Airbus SE leverages its H145 and H175 platforms to sustain dominance in offshore energy missions across the Gulf of Guinea. Leonardo S.p.A anchors its regional position through specialized naval and search-and-rescue configurations tailored to Mediterranean and Red Sea operators. Gulf Helicopters Co competes aggressively on maintenance, repair and overhaul contracts tied to QatarEnergy and ADNOC fleets.
Helicopters are rotary-wing aircraft generating lift through powered rotors, typically operating at cruise speeds of 120-150 knots with payload capacities spanning 500 kg to over 20 tonnes depending on class, designed for vertical takeoff and landing in confined or unprepared sites. The product type spectrum shows light helicopters occupying the volume base for training and private aviation, while heavy and super heavy categories capture premium margin pools in offshore heavy-lift and military transport. Twin turbine technology leads commercial and military procurement due to reliability requirements over water and desert terrain, though hybrid propulsion is gaining traction in sustainability-focused fleet renewal programs across European-influenced North African operators.
Saudi Arabia's General Authority of Civil Aviation and South Africa's Civil Aviation Authority enforce divergent certification standards that fragment type acceptance across the region, while EASA-aligned regulations in Morocco and Tunisia accelerate fleet modernization. The UAE's GCAA mandates enhanced flight data monitoring for commercial operators, tightening market access for non-compliant legacy equipment. Stakeholders must monitor certification reciprocity negotiations between Gulf and sub-Saharan regulators to anticipate fleet migration patterns and maintenance network investments.
Market Dynamics
Offshore energy operators across the Gulf of Guinea and Arabian Gulf are consolidating rotary-wing procurement under long-term fleet management contracts, compressing vendor margins while locking in maintenance revenue pools for incumbent lessors.
Growth Catalysts
- Offshore platform logistics:Oil majors in Nigeria and Angola are expanding crew-change helicopter capacity to deepwater fields beyond 150 nautical miles from shore.
- Enhanced flight data monitoring:The UAE's GCAA mandates are accelerating replacement of legacy analog avionics with digital health monitoring systems across commercial fleets.
- EASA-aligned regulatory convergence:Morocco and Tunisia have adopted European airworthiness standards, enabling faster type certification for modern twin-turbine platforms.
Market Restraints
- Jet fuel price volatility:Kerosene cost swings in the 30-40% range over 18-month cycles erode operating lease economics for independent operators without fuel pass-through clauses.
- Airframe supply concentration:Final assembly for heavy-lift categories concentrates in three European and US facilities, creating 24-36 month delivery backlogs for African utility operators.
- Pilot certification bottlenecks:South Africa's Civil Aviation Authority maintains divergent instrument rating standards that block license reciprocity with Gulf regulators.
Strategic Opportunities
- East African medical evacuation:Kenya and Ethiopia present underdeveloped air-ambulance infrastructure where dedicated HEMS networks could anchor regional coverage hubs.
- Hybrid-electric propulsion trials:European-influenced North African operators are piloting battery-assisted turbine configurations for 30-minute urban shuttle missions.
- Performance-based logistics contracts:QatarEnergy and ADNOC are shifting from hourly charter to availability-based pricing, rewarding uptime guarantees over asset ownership.
Industry Challenges
- Airworthiness directive compliance:Saudi Arabia's General Authority of Civil Aviation has imposed accelerated inspection intervals on aging single-turbine fleets, forcing premature retirement decisions.
- Maintenance technician scarcity:Composite rotor blade repair certification programs are unavailable in sub-Saharan Africa, requiring costly airfreight to European facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Helicopters Market |
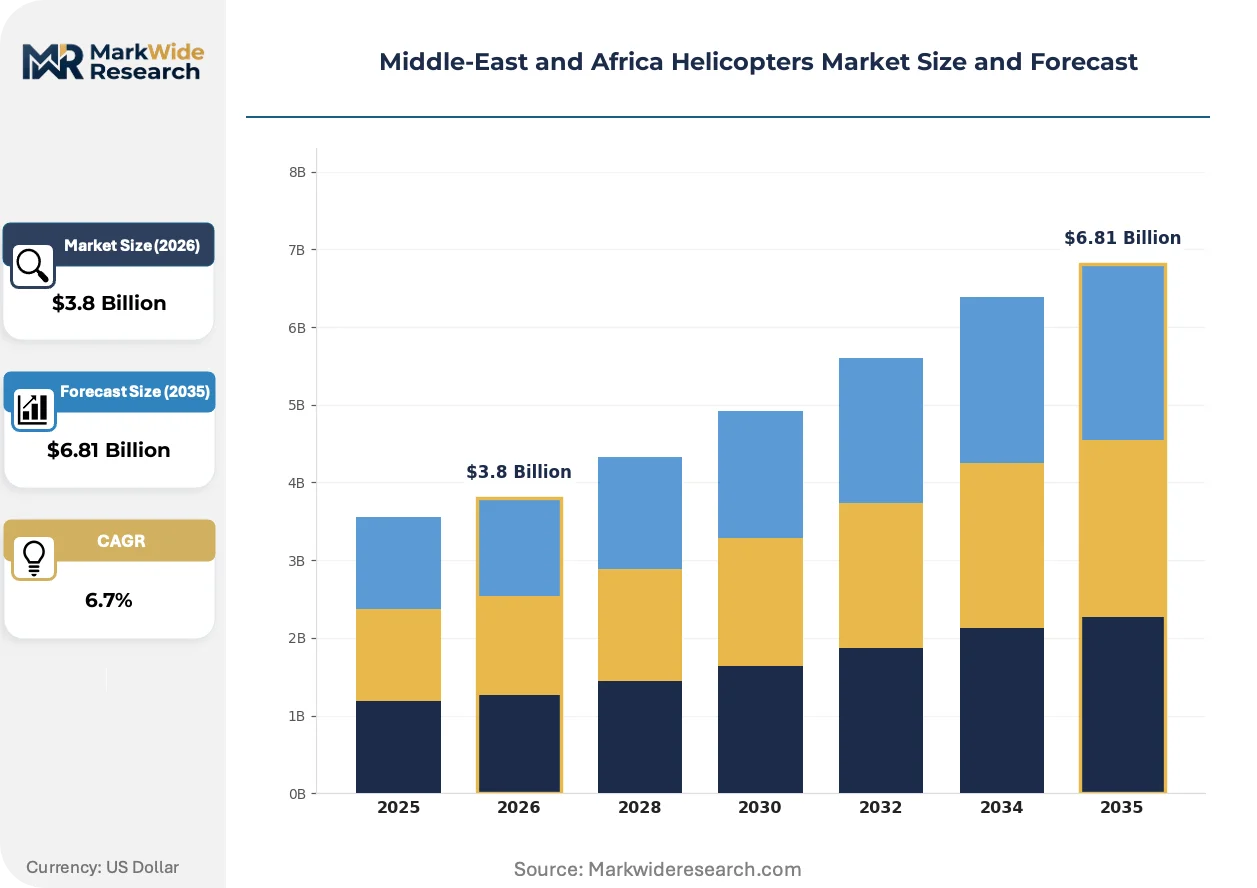
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Super Heavy Helicopters Application: Commercial Aviation, Military Operations, Medical Evacuation, Search and Rescue End User: Government Agencies, Private Sector, Oil & Gas Industry, Tourism Operators Technology: Single Turbine, Twin Turbine, Electric, Hybrid |
| Companies Covered | Airbus SE, Leonardo S.p.A, Textron Inc., The Boeing Company, Rostec State Corporation, Lockheed Martin Corporation, Abu Dhabi Aviation Co., Gulf Helicopters Co, The Helicopter Company (THC), Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Helicopters Market Shifts & Advancements
Digital avionics and predictive maintenance systems are displacing reactive overhaul cycles across Middle-East and Africa helicopter operations, while regulatory divergence between Gulf and sub-Saharan authorities fragments fleet standardization strategies.
Health and usage monitoring systems (HUMS) embedded in main rotor gearboxes and turbine modules are rewriting fleet economics for offshore energy operators. Nigerian and Angolan oil majors now mandate HUMS-equipped platforms for all crew-transport contracts above 50 nautical miles. The technology is compressing unscheduled downtime by enabling component replacement before failure, shifting maintenance from calendar-based to condition-based intervals.
EASA-aligned type certification pathways in Morocco and Tunisia are accelerating fleet modernization timelines versus legacy national procedures. Operators in these jurisdictions can now achieve commercial operating certificates for new helicopter variants within 8-12 months versus 24-36 months previously. Light and medium twin-turbine categories are capturing disproportionate share of new registrations as a result.
Buyer concentration among national oil companies is fragmenting vendor relationships that historically ran through single-source lessors. QatarEnergy, ADNOC, and Sonangol now maintain approved supplier lists with 4-6 competing operators per basin, forcing incumbents to unbundle maintenance contracts from flight-hour agreements. This pattern is most visible in the Arabian Gulf, where availability-based pricing now dominates deepwater logistics procurement.
Middle-East and Africa Helicopters Market Segmentation
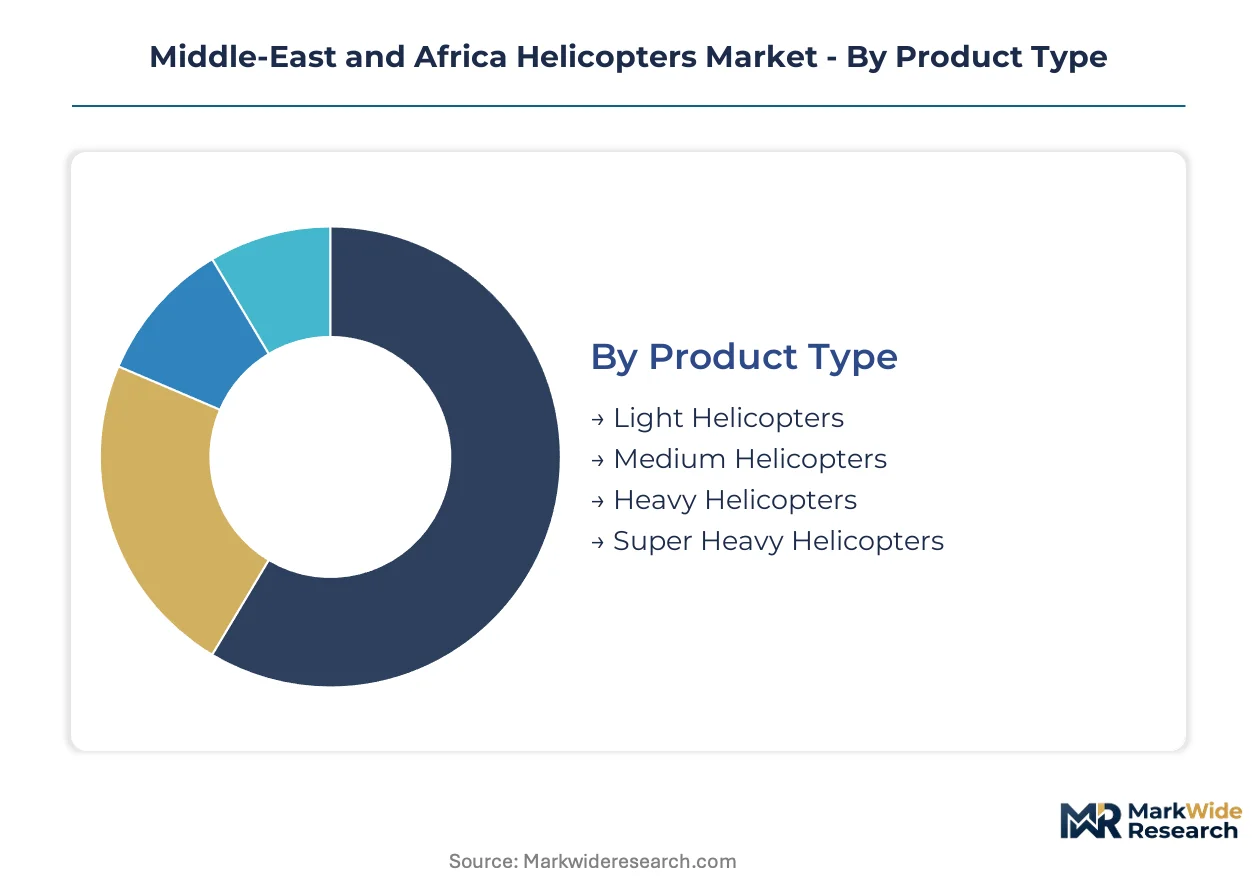
Helicopter fleet composition across the Middle-East and Africa reflects divergent mission profiles ranging from offshore energy logistics to desert border patrol. Understanding segment boundaries clarifies where procurement budgets concentrate and which airframe categories face regulatory pressure.
Product Type:
Supply concentration in heavy-lift final assembly limits fleet expansion timelines for resource-rich operators.
- Light Helicopters:Single-turbine airframes below 3,000 kg MTOW dominate training academies and private aviation in South Africa and Kenya. Dubai-based flight schools are modernizing fleets with glass cockpit variants to meet GCAA instrument rating mandates.
- Medium Helicopters:Twin-turbine platforms in the 4-8 tonne class anchor offshore crew-change contracts across the Gulf of Guinea. Nigerian oil majors specify HUMS-equipped variants for missions beyond 50 nautical miles from shore.
- Heavy Helicopters:10-20 tonne capacity units serve ADNOC and QatarEnergy deepwater platform logistics with external load certification.
- Super Heavy Helicopters:Above-20 tonne categories remain confined to military transport and specialized heavy-lift contracts with limited civil registrations.
Medium helicopters absorb the bulk of installed capacity; heavy helicopters are expanding most quickly among national oil company fleets.
Application:
End-use fragmentation across civilian and state missions creates divergent certification pathways.
- Commercial Aviation:VIP transport and corporate shuttle services concentrate in UAE hubs with Dubai serving as the regional charter coordination center.
- Military Operations:Border surveillance and naval rotary-wing requirements drive procurement in Saudi Arabia and Algeria with emphasis on night vision compatibility.
- Medical Evacuation:Dedicated HEMS networks remain underdeveloped in East Africa where Kenya and Ethiopia present coverage gaps for trauma response within the golden hour.
- Search and Rescue:Mediterranean and Red Sea operators specify Leonardo naval configurations with winch-equipped cabins for maritime recovery missions.
Commercial aviation holds the largest active fleet share; medical evacuation is climbing the fastest as infrastructure investment accelerates.
End User:
Customer type determines contract structure with availability-based pricing gaining traction among consolidated buyers.
- Government Agencies:Interior and defense ministries in Saudi Arabia and Algeria procure through sovereign fleet management with multi-year maintenance bundling.
- Private Sector:Independent charter operators in South Africa face margin pressure from fuel volatility without pass-through clauses.
- Oil & Gas Industry:QatarEnergy and ADNOC have shifted from hourly charter to performance-based logistics with uptime guarantees replacing asset ownership.
- Tourism Operators:Scenic flight providers in Morocco and Tunisia benefit from EASA-aligned certification accelerating new type approvals.
Oil and gas industry accounts for the dominant procurement volume; tourism operators are gaining share fastest on regulatory convergence.
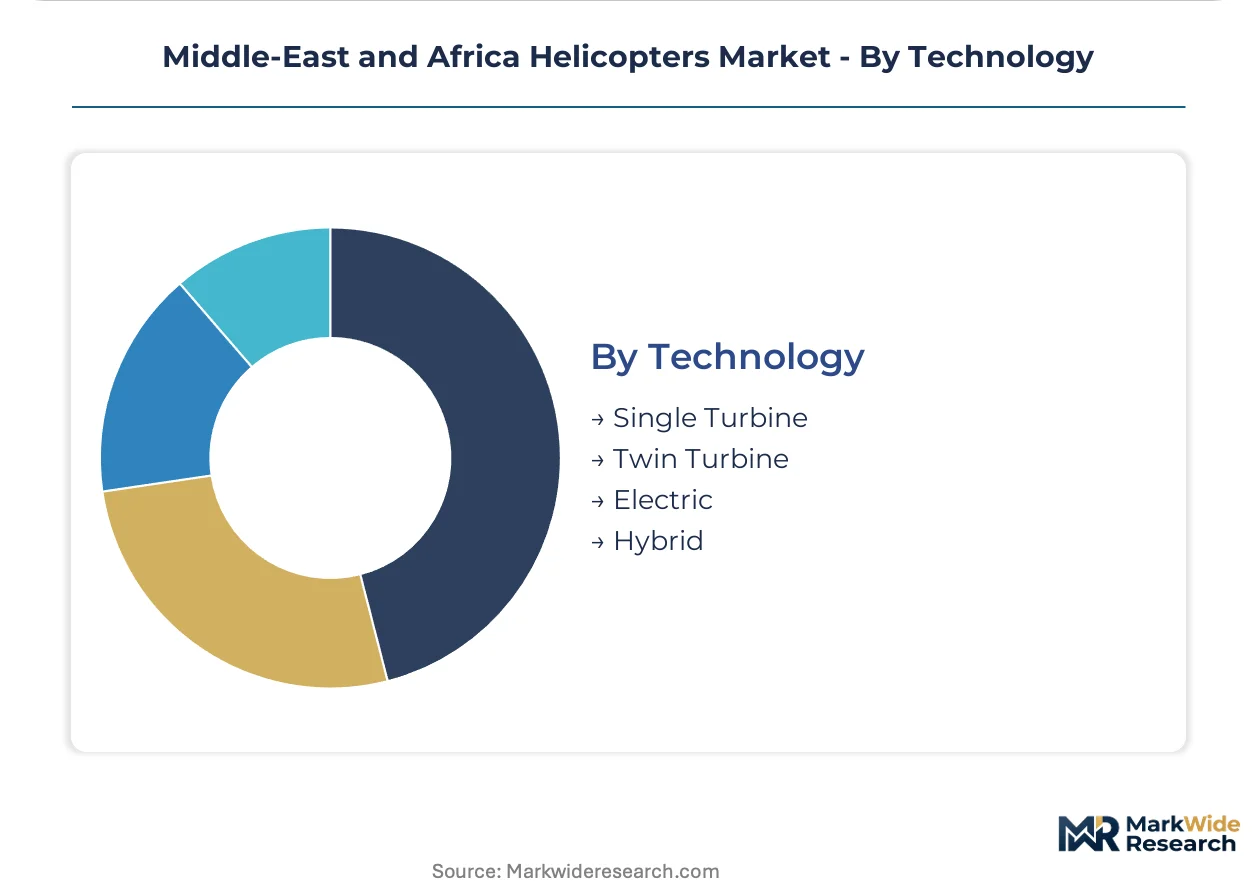
Technology:
Propulsion architecture directly determines operating economics over water and desert terrain.
- Single Turbine:Legacy piston and turbine configurations face accelerated retirement under Saudi GACA inspection interval tightening for aging fleets.
- Twin Turbine:Redundant powerplants dominate offshore energy procurement with reliability requirements over water and unimproved landing zones.
- Electric:Battery-only platforms remain experimental with limited payload-range profiles unsuited to regional mission distances.
- Hybrid:Battery-assisted turbine configurations are piloting in North African urban shuttle missions with 30-minute sector capability.
Twin turbine technology commands the installed base; hybrid systems are expanding most quickly among European-influenced North African operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude reserves along the Arabian Gulf and the Gulf of Guinea anchor helicopter demand for offshore logistics, while regulatory divergence between Gulf Cooperation Council states and sub-Saharan jurisdictions fragments fleet standardization strategies.
United Arab Emirates
Dubai and Abu Dhabi concentrate VIP transport and emergency medical services demand through hub-and-spoke charter networks. The General Civil Aviation Authority mandates enhanced flight data monitoring for commercial operators, accelerating digital avionics replacement cycles. Jebel Ali and Al Maktoum International Airport clusters host maintenance, repair and overhaul facilities serving regional offshore energy fleets.
Saudi Arabia
The General Authority of Civil Aviation has tightened airworthiness certification requirements for commercial helicopter operators, forcing accelerated retirement of aging single-turbine fleets. Aramco's offshore platform logistics in the Persian Gulf drive heavy-lift procurement under performance-based contracts. Eastern Province cities including Dammam and Dhahran anchor crew-change operations to deepwater oilfields.
Nigeria
Oil majors operating in the Gulf of Guinea are expanding crew-change helicopter capacity to deepwater fields beyond 150 nautical miles from shore. The Nigerian Civil Aviation Authority maintains divergent type certification timelines that delay modern twin-turbine platform approvals. Lagos and Port Harcourt serve as coordination hubs for offshore logistics procurement across the Niger Delta basin.
South Africa
Training academies and private aviation operators dominate light helicopter demand in Johannesburg and Cape Town metropolitan corridors. The Civil Aviation Authority maintains divergent instrument rating standards that block license reciprocity with Gulf regulators, fragmenting pilot mobility. Kruger National Park and surrounding reserves sustain tourism operator procurement for scenic flight services.
Morocco
EASA-aligned airworthiness standards enable faster type certification for modern twin-turbine platforms, accelerating fleet modernization timelines. Tourism operators in Marrakech and Agadir benefit from streamlined new variant approvals versus legacy national procedures. Royal Air Maroc's helicopter division and independent charter providers compete for coastal resort transport contracts.
Middle-East and Africa Helicopters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized mission configurations and maintenance service bundling. The vendor base concentrates around European and American airframe manufacturers with Gulf-based operators capturing downstream service revenue. Three archetypes dominate: full-spectrum manufacturers with naval and civilian portfolios, regional lessors with integrated maintenance capabilities, and state-affiliated fleet managers serving national oil companies. Competitive moves center on long-term availability-based contract structures and predictive maintenance technology licensing.
Among European-based manufacturers, Airbus SE and Leonardo S.p.A anchor the full-spectrum tier with platforms spanning light training to heavy-lift offshore categories. Gulf Helicopters Co represents the integrated regional lessor archetype, competing on maintenance, repair and overhaul contracts tied to QatarEnergy and ADNOC fleets. Abu Dhabi Aviation Co occupies a position within the state-affiliated fleet management segment, reflecting the broader pattern of national oil companies consolidating vendor relationships under performance-based logistics arrangements.
| Leading Market Players |
|---|
| Airbus SE |
| Leonardo S.p.A |
| Textron Inc. |
| The Boeing Company |
| Rostec State Corporation |
| Lockheed Martin Corporation |
| Abu Dhabi Aviation Co. |
| Gulf Helicopters Co |
| The Helicopter Company (THC) |
| Others |
Supply & Pricing Matrix
Digital avionics retrofit mandates across Gulf regulators are simultaneously compressing operating margins for legacy fleet operators and concentrating procurement leverage among airframe OEMs with integrated health monitoring platforms. This technology transition reshapes cost economics by unbundling traditional flight-hour contracts from predictive maintenance subscriptions while tightening supply access for analog-equipped operators.
Pricing Analysis
Warranty and maintenance bundling now separates incumbent lessors from independent charter operators across Middle-East and Africa helicopter markets. Three-tier pricing structure across premium, standard, and economy levels reflects airframe age, HUMS equipment status, and GCAA compliance certification. Price differentiation hinges on flight data monitoring integration and composite rotor blade repair capability. Cost compression in light single-turbine categories is intensifying because Saudi GACA inspection interval tightening accelerates fleet retirement timelines. Private training academies in South Africa exhibit highest price sensitivity due to fuel volatility exposure without pass-through clauses, while QatarEnergy and ADNOC long-term availability contracts show lowest sensitivity.
Supply Chain Analysis
Turbine engine supply rests on concentrated final assembly capacity across France, the United States, and Germany for heavy-lift categories serving deepwater oilfield logistics. Critical inputs span nickel-based superalloys for hot-section components, composite prepregs for rotor blade fabrication, and specialized avionics chipsets. Single-source vulnerability concentrates in main rotor gearbox manufacturing where European facilities serve global demand. Distribution runs through Jebel Ali and Al Maktoum International Airport clusters anchoring regional maintenance, repair and overhaul networks for Gulf of Guinea and Arabian Gulf offshore operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
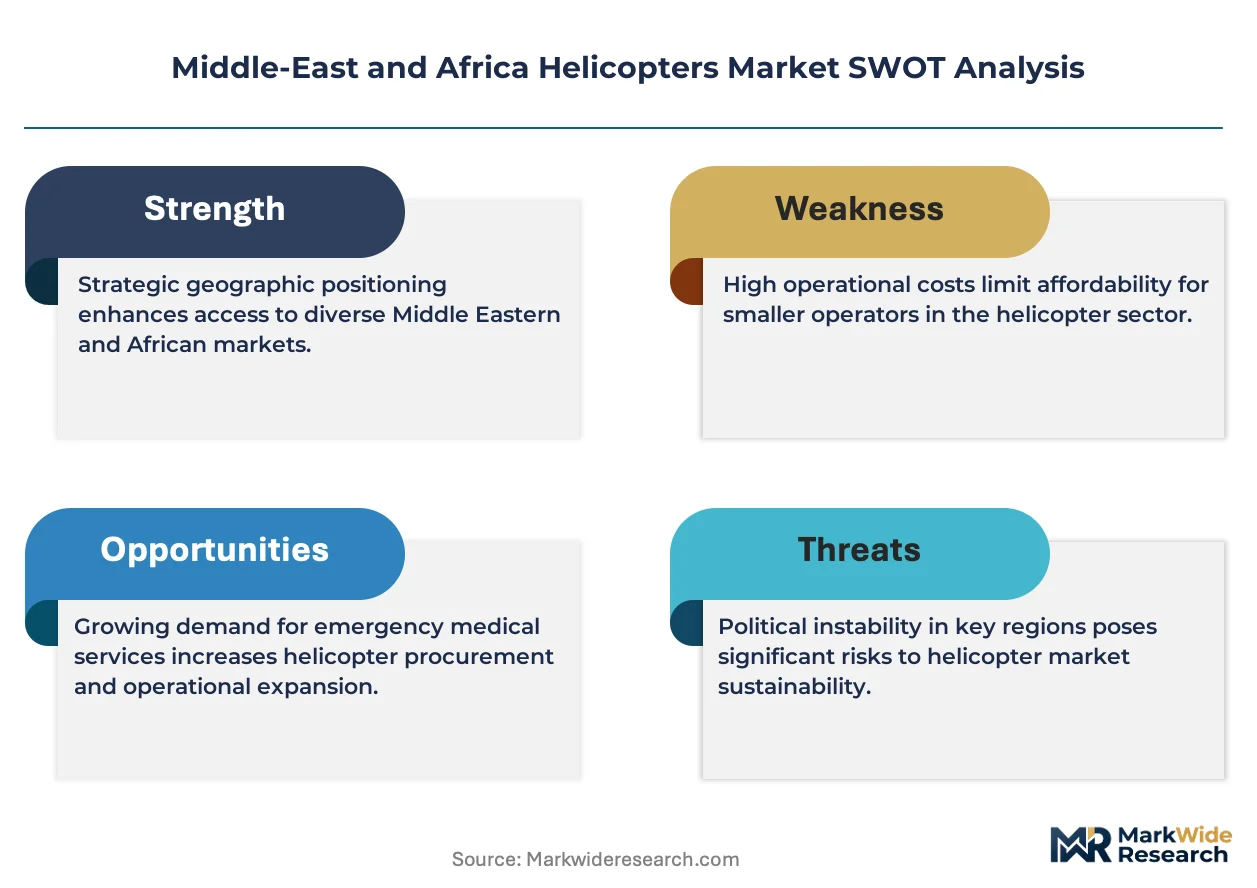
Saudi GACA airworthiness directive tightening constructs a cost-of-compliance moat that rewards operators with early digital avionics investment and penalizes legacy fleet holders.
For Market Incumbents: Hedge exposure to accelerated single-turbine retirement by securing long-term composite rotor blade repair certification programs in European facilities before regional capacity constraints materialize. Anchor position through performance-based logistics contracts with QatarEnergy and ADNOC that substitute uptime guarantees for asset ownership, countering margin pressure from fuel pass-through elimination. For New Entrants and Emerging Players: Underserved East African medical evacuation operators present white-space entry points where Kenya and Ethiopia trauma response networks remain underdeveloped beyond golden-hour coverage radii. Target HEMS infrastructure gaps through availability-based contracting models rather than capital-intensive fleet ownership, leveraging EASA-aligned certification pathways in Morocco and Tunisia for faster type approval timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated regional lessors with captive maintenance capabilities serving national oil company panels. Long-term viability favors operators with hybrid-electric pilot programs and digital health monitoring licensing agreements. Monitor GCAA-EASA certification reciprocity negotiations as inflection signal for fleet migration patterns and maintenance network investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| HUMS Platform Integration | Nigerian oil majors now mandate health monitoring for crew-transport contracts beyond 50 nautical miles. |
| Performance-Based Logistics Contracting | QatarEnergy and ADNOC availability-based pricing rewards uptime guarantees over traditional asset ownership. |
| EASA Certification Alignment | Morocco and Tunisia operators achieve commercial certificates within 8-12 months versus legacy 24-36 month timelines. |
| Hybrid-Electric Propulsion Trials | North African urban shuttle missions pilot battery-assisted turbine configurations for 30-minute sector capability. |
| Composite Repair Capability Investment | Sub-Saharan Africa lacks rotor blade certification programs, requiring costly European airfreight for maintenance. |
Research Methodology
Independent corroboration across fleet operators, maintenance facility directors, and civil aviation authority officials underwrites the qualitative findings in this analysis. Primary interviews with offshore logistics procurement leads, HEMS network planners, and flight training academy operators combined with secondary validation from GCAA regulatory filings, EASA type certificate databases, and national oil company tender disclosures. Bottom-up triangulation across airframe registration data and top-down reconciliation against energy sector capex announcements anchor volume estimates.
Rate-of-change decomposition separates fleet replacement cycles from net capacity expansion across the analysis window. Segmentation dimensions span product type, application mission profile, end-user contract structure, and propulsion technology tier. CAGRs derive from logistic diffusion curves fitted to regulatory mandate implementation timelines and oilfield development project pipelines. Forecast inputs incorporate jet fuel price scenario bands and pilot certification reciprocity negotiation status between Gulf and sub-Saharan regulators.
Revisions become necessary when EASA-GCAA certification reciprocity agreements materialize or when hybrid-electric propulsion trials demonstrate commercial scalability beyond 30-minute urban missions. Forecasts reflect documented assumptions regarding airframe delivery backlog durations and composite technician training pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Afterburner Market
Aircraft
Aircraft Cables Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Airplane Ailerons Market
Aircraft
Docking System Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Firefighting Aircraft Market
Aircraft
Electric Aircraft Market
Aircraft
Wind Tunnel Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Global Business Aircraft Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Asia-Pacific Attack Helicopter Market