
 Global Primary Battery Recycling Market | 2026-2036
Global Primary Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Primary Battery Recycling Market Outlook
EU Battery Regulation is pivoting compliance costs upward for new entrants across the European recycling value chain. ECOBAT Technologies sustains integrated collection networks spanning multiple countries. Umicore SA specializes in hydrometallurgical recovery of critical metals at scale. Redwood Materials Inc. dominates North American processing capacity through backward integration into cathode precursor production.
Primary battery recycling encompasses the recovery of metallic content from spent single-use and rechargeable cells through thermal, chemical, or mechanical means, typically yielding lithium carbonate, cobalt sulfate, or nickel intermediates with purity grades exceeding 99.5% for battery-grade reuse. The process serves to close material loops for portable electronics, electric mobility, and grid storage supply chains. Alkaline and lithium-ion streams command divergent margin profiles, with the latter attracting capital due to cobalt and lithium value concentration. Hydrometallurgical routes are gaining preference over pyrometallurgical alternatives as energy costs and air-permitting constraints reshape operating economics. Collection through retail take-back programs is expanding fastest in jurisdictions with extended producer responsibility mandates.
FDA guidelines on medical device battery disposal, EPA hazardous waste rules under RCRA, and REACH compliance requirements for recovered substances collectively shape collection obligations and material certification standards across the United States and European Union. The EU Green Deal's critical raw materials targets are tightening recycled-content quotas, while China's MEE enforces discharge permits for recycling facilities. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded collection infrastructure and misaligned processing investments.
Market Dynamics
EU Battery Regulation's recycled-content mandates are compressing timelines for cathode precursor qualification across the European value chain. Hydrometallurgical processing capacity is concentrating around cobalt and lithium supply nodes as pyrometallurgical routes face energy-cost displacement.
Growth Catalysts
- Critical Raw Materials Act:The EU's binding recycled-content thresholds for lithium, cobalt, and nickel are forcing OEMs to secure offtake agreements with qualified recyclers.
- Electric vehicle battery retirement waves:Early-generation EV packs are reaching end-of-life in volume, creating feedstock concentration in Germany, China, and South Korea.
- Direct recycling advances:Cathode regeneration without full elemental decomposition is reducing reagent costs and energy intensity for lithium-iron-phosphate streams.
Market Restraints
- Black mass supply concentration:Collection infrastructure remains concentrated among incumbent smelters, limiting independent processor feedstock access in North America and Europe.
- Lithium price volatility:Spodumene and brine cost swings compress hydrometallurgical margins when primary material prices undershoot recovery economics.
- Permitting timelines:EPA hazardous waste licensing under RCRA and MEE discharge permits in China extend facility commissioning by 18-36 months.
Strategic Opportunities
- India's emerging EV ecosystem:The country's PLI scheme for advanced chemistry cell manufacturing is creating parallel demand for domestic recycling capacity.
- Grid storage second-life diversion:Stationary energy applications are absorbing retired EV modules, delaying recycling feedstock but creating battery-as-a-service revenue pools.
- REACH compliance arbitrage:Recovered-material certification under EU chemical registration rules is enabling premium pricing for battery-grade nickel sulfate versus primary-sourced alternatives.
Industry Challenges
- Pyrometallurgical talent scarcity:High-temperature process engineering expertise is retiring faster than training programs in Europe and Japan can replace.
- Collection-to-processing traceability:Chain-of-custody documentation for conflict-mineral compliance and carbon-accounting claims requires IT infrastructure investment that mid-scale operators struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Primary Battery Recycling Market |
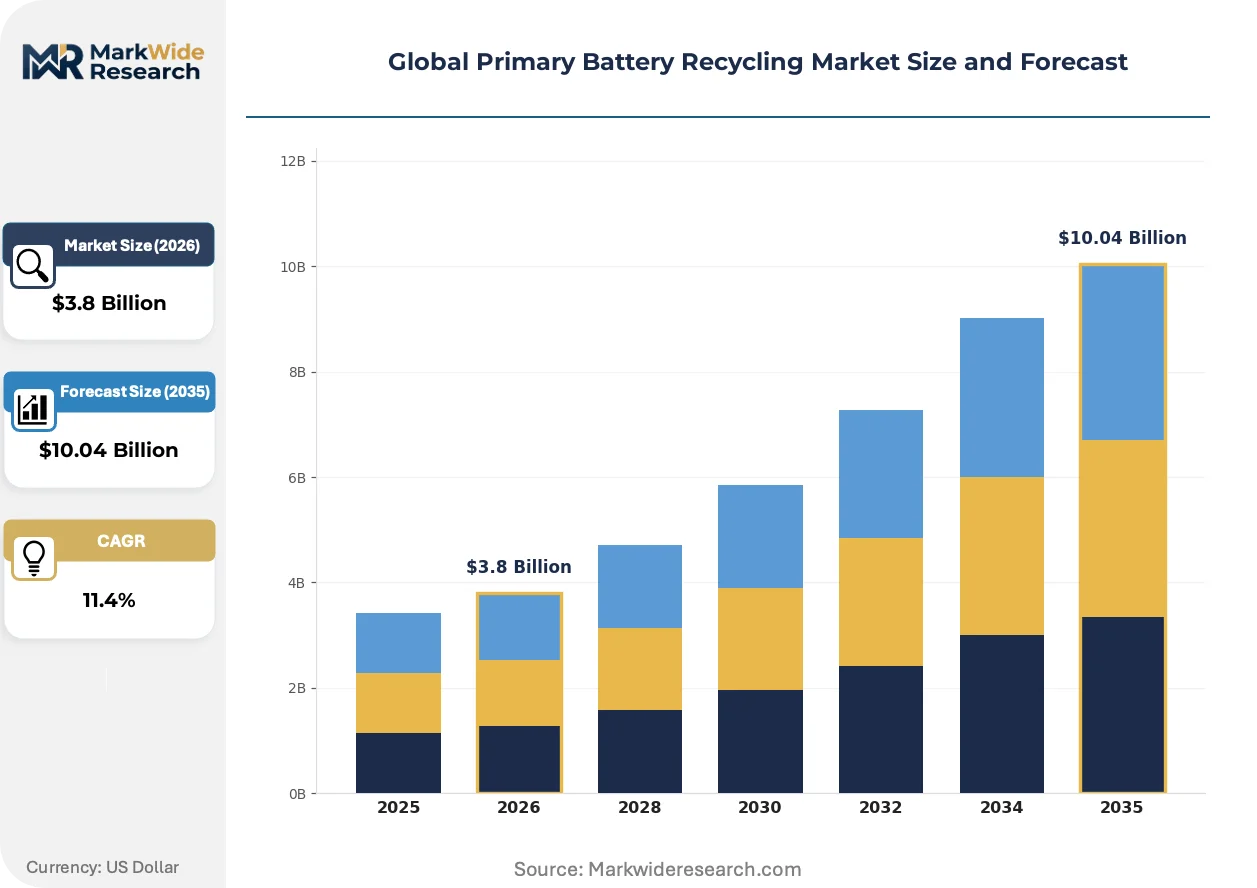
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Cadmium, Alkaline, Lead-acid Collection Method: Drop-off Centers, Curbside Collection, Retail Take-back, Mail-in Recycling End User: Manufacturers, Retailers, Consumers, Industrial Users Technology: Hydrometallurgical, Pyrometallurgical, Biotechnological, Mechanical |
| Companies Covered | Call2Recycle Inc., ECOBAT Technologies, Exide Technologies, Umicore SA, Li-Cycle Holdings Corp., GEM Co. Ltd., Glencore plc, Gravita India Limited, Redwood Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Primary Battery Recycling Market Strategic Shifts
Hydrometallurgical process flowsheets are fragmenting into modular unit operations that reduce capital risk and enable feedstock-flexible configurations. Regulatory timing differences between jurisdictions are creating arbitrage windows for technology licensing and equipment supply.
Direct cathode regeneration technology is modularizing around solid-state electrolyte recovery and single-crystal reconstruction methods. Solid-state battery developers in Japan and South Korea are piloting closed-loop partnerships with specialized recyclers. The approach is compressing reagent consumption and enabling lithium retention above 95% without sulfuric acid leaching.
REACH substance registration requirements for recovered cobalt and nickel compounds are tightening purity certification protocols across the European Union. Battery manufacturers are demanding batch-level analytical data that exceeds historical scrap-metal trading standards. The automotive OEM segment is responding by integrating recycler qualification into supplier scorecards alongside primary material vendors.
Long-term offtake contracting is displacing spot-market black mass trading as the dominant procurement mechanism for qualified recyclers. Tier-one cathode producers in China and South Korea are locking in decade-long supply agreements that embed collection responsibility clauses. The shift is most visible in Germany, where automakers are acquiring minority stakes in recycling ventures to secure volume guarantees.
Global Primary Battery Recycling Market Segmentation
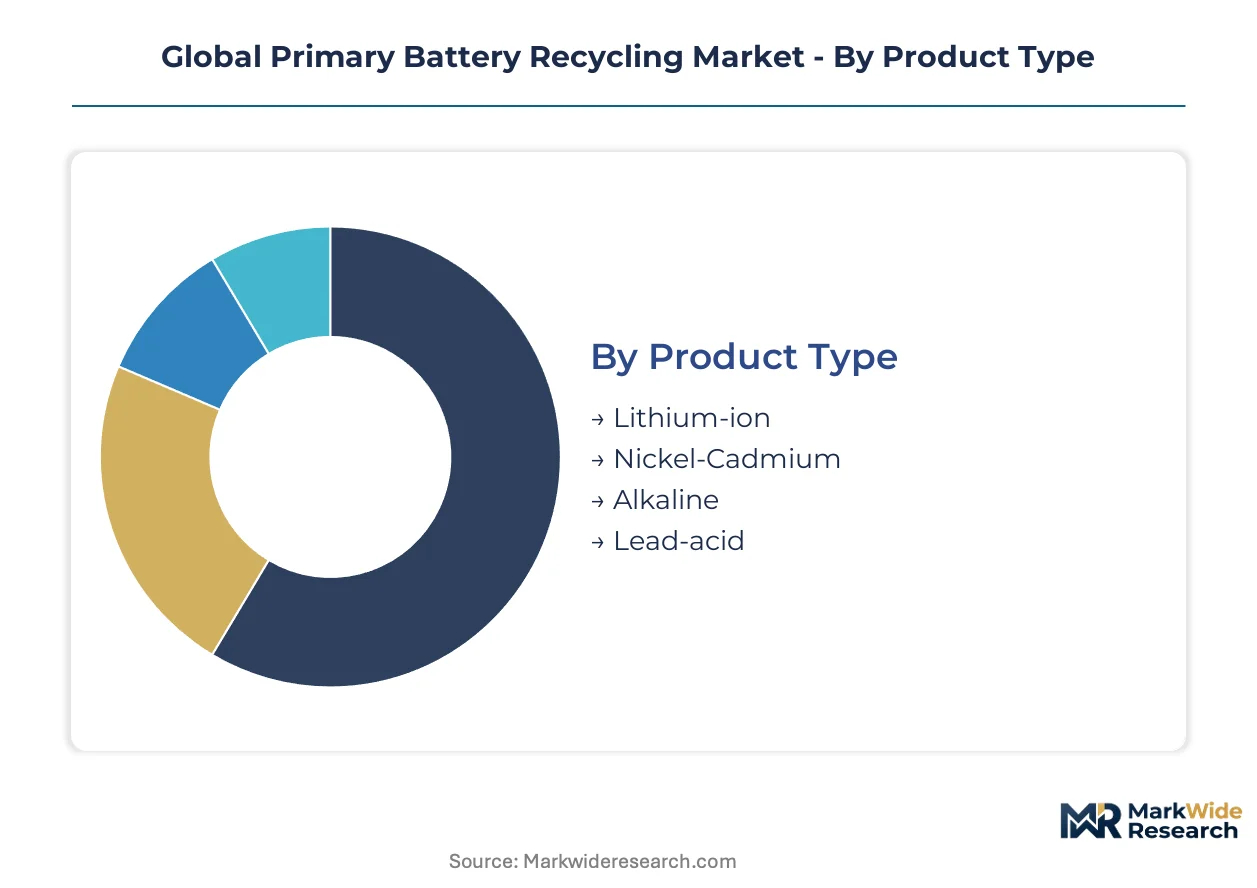
Segmentation in primary battery recycling reveals divergent margin profiles and capital requirements across chemistry types and processing routes. Technology choices and collection infrastructure investments shape competitive positioning more than scale alone in this feedstock-constrained industry.
Product Type:
Lithium-ion streams command processing priority due to metal value concentration, while legacy chemistries sustain volume through established collection networks.
- Lithium-ion:Cathode materials containing cobalt, nickel, and lithium drive hydrometallurgical investment. Demand concentrates in Germany and South Korea where EV manufacturers enforce closed-loop supply agreements. Permitting complexity under EPA RCRA and EU REACH extends facility timelines.
- Alkaline:Zinc-manganese dioxide cells dominate residential waste streams with lower recovery economics. Collection runs through municipal curbside programs in the United States and Japan. Metal price volatility compresses processor margins when zinc futures undershoot recovery costs.
- Lead-acid:Mature recycling infrastructure achieves recovery rates exceeding 95% through pyrometallurgical smelting. Automotive battery retailers in China and Mexico anchor collection networks.
- Nickel-Cadmium:Cadmium toxicity triggers strict EPA hazardous waste handling requirements. Industrial power tool manufacturers in Japan maintain dedicated take-back programs.
Mature deployment sits with Lead-acid. Newer deployment is concentrated in Lithium-ion.
Collection Method:
Regulatory mandates and producer responsibility schemes are redistributing collection cost burdens across the value chain.
- Retail Take-back:Extended producer responsibility laws in France and California obligate electronics retailers to accept spent batteries. Compliance infrastructure requires barcode tracking systems for chain-of-custody documentation. Best Buy and MediaMarkt operations illustrate scaling challenges.
- Drop-off Centers:Municipal hazardous waste facilities aggregate diverse battery chemistries for pre-sorting. Germany's dual collection system achieves highest per-capita recovery rates through dense network coverage. Operating subsidies from state environmental agencies sustain viability.
- Curbside Collection:Co-mingled residential waste streams in the United Kingdom and Netherlands require post-collection separation. Contamination rates from damaged lithium-ion cells elevate fire risk at material recovery facilities.
- Mail-in Recycling:Prepaid shipping programs serve rural and commercial generators with lower volume density. Call2Recycle partnerships with logistics providers in Canada demonstrate unit economics constraints.
Volume leadership belongs to Retail Take-back. Steepest expansion trajectory is visible in Drop-off Centers.
End User:
Customer type determines pricing power, contract duration, and technical specification requirements for recovered materials.
- Manufacturers:OEMs in the battery and automotive sectors drive demand for battery-grade nickel sulfate and cobalt hydroxide. Long-term offtake agreements with qualified recyclers embed recycled-content quotas under EU Battery Regulation. Qualification timelines exceed 18 months for cathode precursor supply.
- Industrial Users:Grid-scale energy storage developers and data center operators generate concentrated feedstock from backup power systems. Secondary smelters in China purchase black mass for metal recovery without full hydrometallurgical refining.
- Retailers:Consumer electronics chains face compliance-driven collection obligations with limited revenue recovery. Operational focus centers on liability reduction and brand reputation management.
- Consumers:Residential generators contribute fragmented volumes through intermittent disposal behavior. Education gaps persist regarding proper handling of damaged lithium-ion cells.
Contract value concentrates with Manufacturers. Emerging volume pools are forming around Industrial Users.
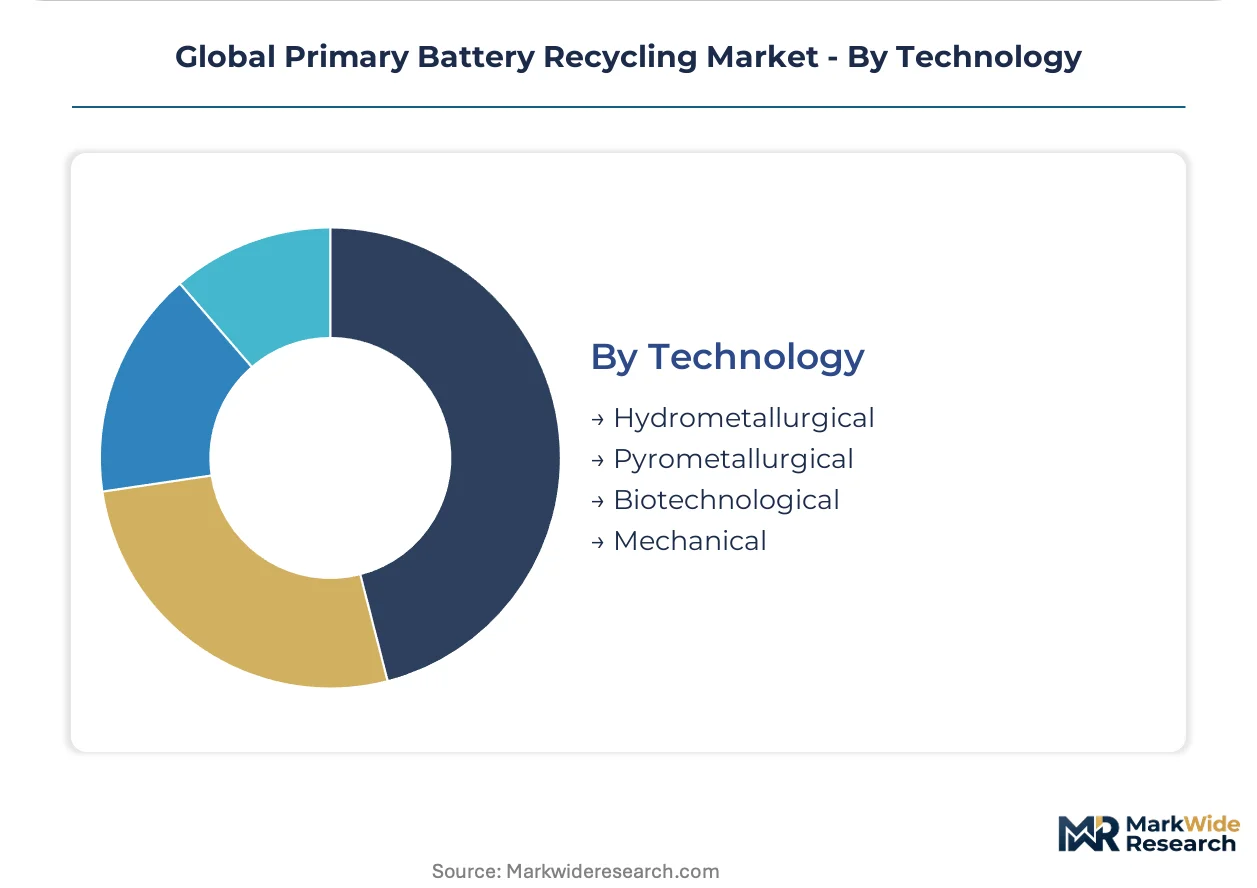
Technology:
Process selection balances energy costs, metal recovery rates, and air-permitting constraints across regulatory jurisdictions.
- Hydrometallurgical:Acid leaching and solvent extraction achieve selective metal recovery with lower carbon intensity. Umicore and Redwood Materials operations demonstrate scalability for lithium-ion black mass. Water discharge permits under China's MEE and EPA NPDES constrain site selection.
- Pyrometallurgical:High-temperature smelting handles mixed chemistries and plastic contamination without pre-sorting. Glencore's integrated operations in Canada and Belgium leverage existing non-ferrous metals infrastructure. Natural gas price exposure shapes operating economics.
- Mechanical:Crushing, sorting, and physical separation prepare feedstock for downstream refining. Lower capital requirements enable distributed pre-processing near collection points.
- Biotechnological:Bioleaching using acidophilic bacteria reduces reagent consumption for low-grade ores and residues. Pilot deployments in Finland and Australia remain sub-commercial scale.
Installed capacity concentrates in Pyrometallurgical. Capital deployment is accelerating fastest toward Hydrometallurgical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Germany, and the United States concentrate the bulk of processing capacity and feedstock generation for battery recycling. Collection infrastructure and regulatory mandates vary sharply across these demand centers.
China
State-backed recycling infrastructure investments are consolidating processing capacity around GEM Co. Ltd. and regional operators. The Ministry of Ecology and Environment enforces discharge permits that filter sub-scale facilities from the market. Jiangsu and Guangdong provinces host the densest concentration of hydrometallurgical refineries serving cathode precursor manufacturers.
Germany
Automotive OEMs are acquiring minority stakes in recycling ventures to secure volume guarantees under EU Battery Regulation recycled-content mandates. The dual collection system achieves highest per-capita recovery rates through dense municipal network coverage. The Rhine-Ruhr industrial corridor anchors pyrometallurgical smelting capacity integrated with non-ferrous metals infrastructure.
United States
Early-generation EV battery retirement waves are concentrating feedstock in California, Texas, and Michigan. EPA hazardous waste licensing under RCRA extends facility commissioning timelines by 18-36 months. Nevada and Tennessee are emerging as processing hubs where cathode precursor producers seek backward integration into black mass refining.
South Korea
Battery manufacturers are locking in decade-long offtake agreements that embed collection responsibility clauses. The national regulator encloses recycling investments within the broader advanced chemistry cell manufacturing strategy. The Seoul Capital Area and Busan-Ulsan corridor concentrate both cell production and dedicated recycling joint ventures.
India
The PLI scheme for advanced chemistry cell manufacturing is creating parallel demand for domestic recycling capacity. Central Electricity Authority guidelines are tightening disposal protocols for grid-scale battery installations. Maharashtra and Gujarat are attracting preliminary investments in collection infrastructure ahead of projected EV fleet expansion.
Global Primary Battery Recycling Market Competitive Environment
European producers anchor one tier; North American specialists hold emerging positions through backward integration into cathode materials. The vendor base splits between integrated metals conglomerates with existing smelting infrastructure and pure-play recyclers building dedicated hydrometallurgical capacity. Three archetypes dominate: collection-integrated operators, technology-focused refiners, and automotive-captive processors. Competitive moves concentrate on long-term offtake contracting and geographic licensing of modular process technology.
Among Belgium-based operators, Umicore SA exemplifies the large-scale hydrometallurgical refiner archetype. Glencore plc represents the integrated metals conglomerate model leveraging existing non-ferrous infrastructure. Redwood Materials Inc. anchors the North American pure-play category with backward integration into precursor production. These three occupy distinct competitive positions without direct overlap in customer segmentation or geographic focus.
| Leading Market Players |
|---|
| Call2Recycle Inc. |
| ECOBAT Technologies |
| Exide Technologies |
| Umicore SA |
| Li-Cycle Holdings Corp. |
| GEM Co. Ltd. |
| Glencore plc |
| Gravita India Limited |
| Redwood Materials Inc. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into cathode precursor production anchors both supply security and pricing power for North American processors competing against Asian integrated conglomerates. This structural choice determines margin capture across the black mass-to-battery-grade material value chain under divergent regulatory cost burdens.
Pricing Analysis
Volume leadership sits with contract-based long-term offtake agreements, while spot-market black mass trading retains margin volatility for unqualified processors. Price differentiation hinges on battery-grade purity certification exceeding 99.5% and embedded carbon-accounting documentation under EU Battery Regulation. Cost compression in hydrometallurgical processing is intensifying because lithium price volatility from spodumene and brine markets periodically undershoots recovery economics. Industrial users demonstrate highest price sensitivity due to alternative feedstock access through secondary smelters, whereas automotive OEMs accept premium pricing to secure recycled-content quotas.
Supply Chain Analysis
REACH substance registration and EU Battery Regulation qualification gating filter sub-scale operators from qualified supplier lists across the European value chain. Feedstock concentration centers on China, Germany, and South Korea where state-backed infrastructure and automotive OEM collection programs dominate. The supply chain rests on black mass, spent lithium-ion cells, and reagent chemicals as critical inputs. Single-source vulnerability emerges from collection infrastructure concentration among incumbent smelters in North America. Distribution runs through qualified recycler-to-cathode-producer direct contracts, displacing historical scrap-metal trading channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Primary battery recycling sits in a technology-transition phase as hydrometallurgical routes displace pyrometallurgical alternatives for lithium-ion streams. Direct cathode regeneration without full elemental decomposition is replacing legacy acid-leaching flowsheets for lithium-iron-phosphate chemistries.
For Market Incumbents: Extend hydrometallurgical capacity additions into Nevada and Tennessee where cathode precursor producers seek backward integration, defending against pure-play recyclers capturing automotive OEM offtake. Lock in decade-long supply agreements with embedded collection responsibility clauses before EU Battery Regulation recycled-content mandates fully compress qualification timelines. Certify batch-level analytical data exceeding historical scrap-metal standards to maintain premium positioning under REACH tightening.
For New Entrants and Emerging Players: Modular hydrometallurgical unit operations offer a technology-first wedge into India's emerging EV ecosystem where PLI scheme incentives for advanced chemistry cell manufacturing create parallel recycling demand ahead of domestic capacity buildout. Target grid storage second-life diversion services for battery-as-a-service revenue pools before retired EV modules saturate recycling feedstock. Pursue equipment licensing and technology export models to capture regulatory timing arbitrage between jurisdictions.
For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-captive processor acquisitions as OEMs acquire minority stakes to secure volume guarantees under binding recycled-content thresholds. Long-term viability favors qualified recyclers with demonstrated cathode precursor supply relationships and water discharge permits under China's MEE or EPA NPDES compliance. Watch for lithium price inflections that compress hydrometallurgical margins below pyrometallurgical breakeven as the signal to reassess processing technology bets.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks volume guarantees with EU Battery Regulation recycled-content clauses for cathode precursor supply. |
| Backward Integration | Captures margin from black mass refining through in-house battery-grade nickel sulfate production. |
| Technology Licensing | Monetizes modular hydrometallurgical process flowsheets across regulatory timing arbitrage windows. |
| Joint Venture | Combines OEM collection networks with processor refining capacity under shared qualification investment. |
| Green Certification Program | Enables premium pricing through carbon-accounting documentation under EU Green Deal targets. |
Study Parameters
Trade databases, SEC filings from listed battery material companies, and EU regulatory submissions formed the secondary backbone, cross-referenced against primary interviews with hydrometallurgical plant managers, cathode precursor procurement leads, automotive sustainability officers, and EPA hazardous waste compliance specialists. Bottom-up feedstock volume estimates from collection infrastructure databases combined with top-down cathode material demand projections to triangulate market sizing across the analysis window.
Historical trendline analysis of lithium carbonate and cobalt sulfate pricing informed recovery economics modeling, with segmentation across chemistry type, processing technology, and end-user qualification tier. CAGRs derived from installed capacity buildout timelines, permitting velocity under EPA RCRA and MEE discharge frameworks, and EV battery retirement wave projections. Forecast inputs incorporated direct recycling technology maturation curves and second-life diversion rates for grid storage applications.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on critical mineral flows, breakthrough solid-state battery commercialization timelines, and pyrometallurgical talent scarcity acceleration in Europe and Japan. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and feedstock collection infrastructure buildout. A model refresh is warranted upon material change in EU Battery Regulation recycled-content threshold implementation schedules or lithium spot price sustained movements beyond recovery breakeven bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Prepaid Battery Recycling Market