
 Lithium-Ion Battery Recycling Service Market | 2026-2036
Lithium-Ion Battery Recycling Service Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Recycling Service Market Insights
Spent battery collection revenue is reshaping competitive economics across the recycling value chain, pulling margin pools away from pure processing toward integrated logistics and reverse supply chain control. Umicore leverages its European smelting footprint to anchor cathode precursor production. Redwood Materials specializes in closed-loop hydrometallurgical recovery for North American automakers. GEM Co., Ltd. dominates black mass processing scale across China's industrial belt.
Lithium-ion battery recycling service encompasses the systematic recovery of cobalt, lithium, nickel, and manganese from end-of-life cells through thermal, chemical, or mechanical separation, typically achieving recovery rates above 95% for target metals under controlled conditions. The primary purpose is to reintroduce battery-grade materials into cathode manufacturing, reducing virgin mining dependence. Hydrometallurgical routes command premium margins due to lower energy intensity and higher selectivity for lithium recovery compared with pyrometallurgical alternatives. Direct recycling preserves cathode crystal structures and represents the fastest-growing technology category, though it remains limited to homogeneous feedstock streams. Collection and transportation services absorb disproportionate capital as OEMs build captive reverse logistics networks.
The EU Battery Regulation and EPA hazardous waste rules under RCRA shape feedstock access and facility permitting timelines across core operating jurisdictions. China's MEE solid waste standards and the EU's REACH chemical registration requirements impose divergent compliance burdens on cross-border material flows. Stakeholders must monitor regulatory fragmentation between jurisdictions as it determines where refining capacity achieves viable economics.
Market Dynamics
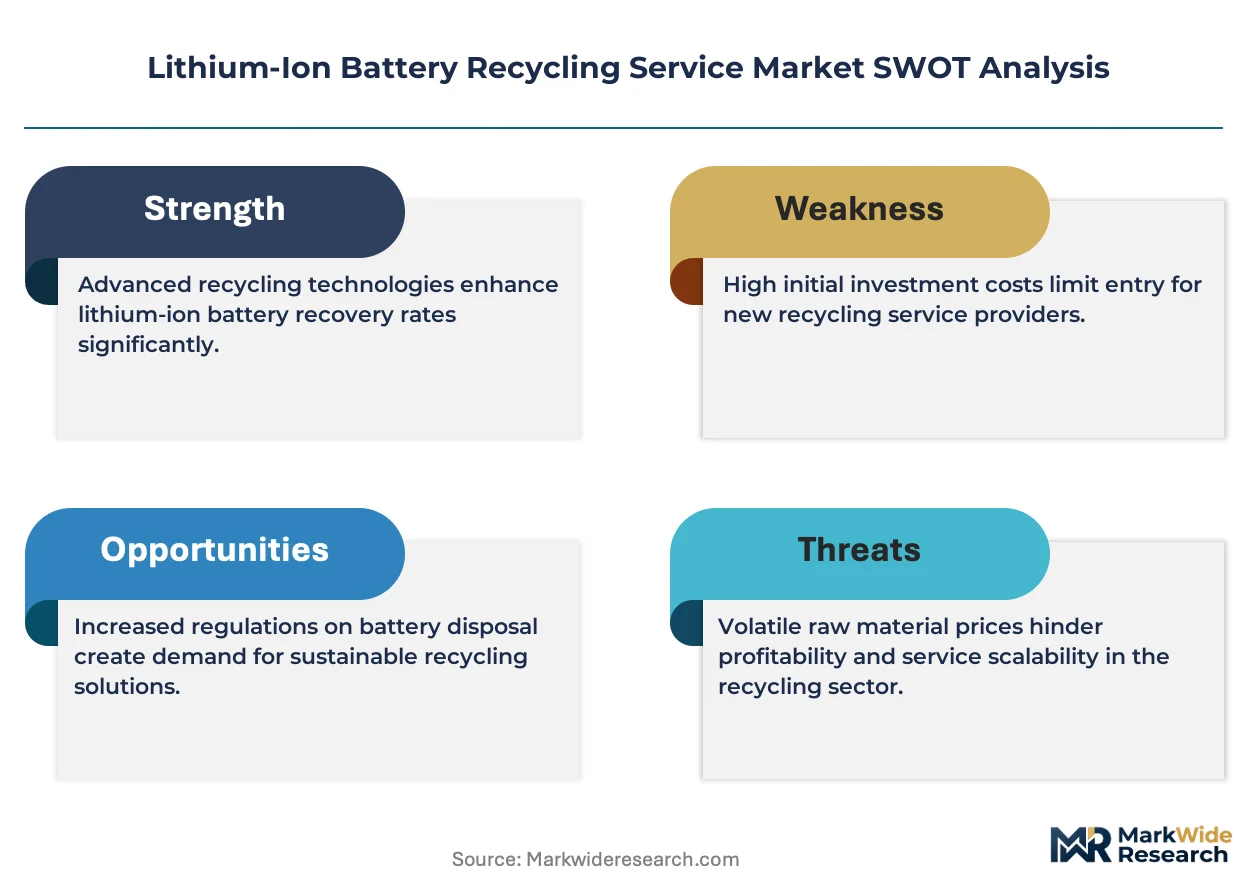
EU Battery Regulation mandates are forcing recyclers to build captive refining capacity inside European borders rather than exporting black mass to Asia, compressing legacy merchant processing models and accelerating integrated smelter-precursor investments across Germany, Poland, and Finland.
Growth Catalysts
- EU recycled content quotas:The Battery Regulation mandates minimum recycled lithium, cobalt, and nickel thresholds in new cells, compelling automakers to secure offtake from European refiners.
- EV end-of-life wave:Early-generation electric vehicle batteries are reaching retirement age, creating predictable feedstock volumes that justify large-scale hydrometallurgical facility investments.
- Lithium recovery economics:Advanced solvent extraction methods now capture battery-grade lithium at commercial scale, closing the loop on the most volatile raw material in cathode production.
Market Restraints
- Feedstock supply fragmentation:Spent batteries arrive from thousands of dispersed collection points across multiple jurisdictions, inflating logistics costs and complicating hazardous waste transport permits under EPA RCRA and EU ADR rules.
- Cobalt price volatility:London Metal Exchange cobalt futures swing unpredictably, undermining long-term offtake contract viability and deterring project finance for new refineries.
- Pyrometallurgical lock-in:Existing smelters in Belgium and Canada rely on high-temperature routes that lose lithium to slag, creating stranded asset risk as battery chemistry shifts toward lithium-rich chemistries.
Strategic Opportunities
- North American closed-loop networks:The US Inflation Reduction Act domestic content credits incentivize automakers to establish circular supply chains that bypass Asian intermediate processing entirely.
- Direct recycling scale-up:Startups are commercializing cathode regeneration that preserves crystal structure, slashing re-manufacturing energy intensity for homogeneous electric bus and stationary storage retirements.
- Second-life stationary storage:Retired electric vehicle packs with 70-80% remaining capacity are finding second applications in grid buffering, delaying recycling and creating new revenue streams for collection networks.
Industry Challenges
- Qualified technical workforce scarcity:Hydrometallurgical plants require chemists and process engineers with rare earth and battery metals expertise, a skill set concentrated in mining regions rather than industrial recycling hubs.
- Permitting timeline compression:EPA hazardous waste facility approvals and state-level environmental impact reviews routinely extend 18-36 months, misaligning with automaker supply chain deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Recycling Service Market |
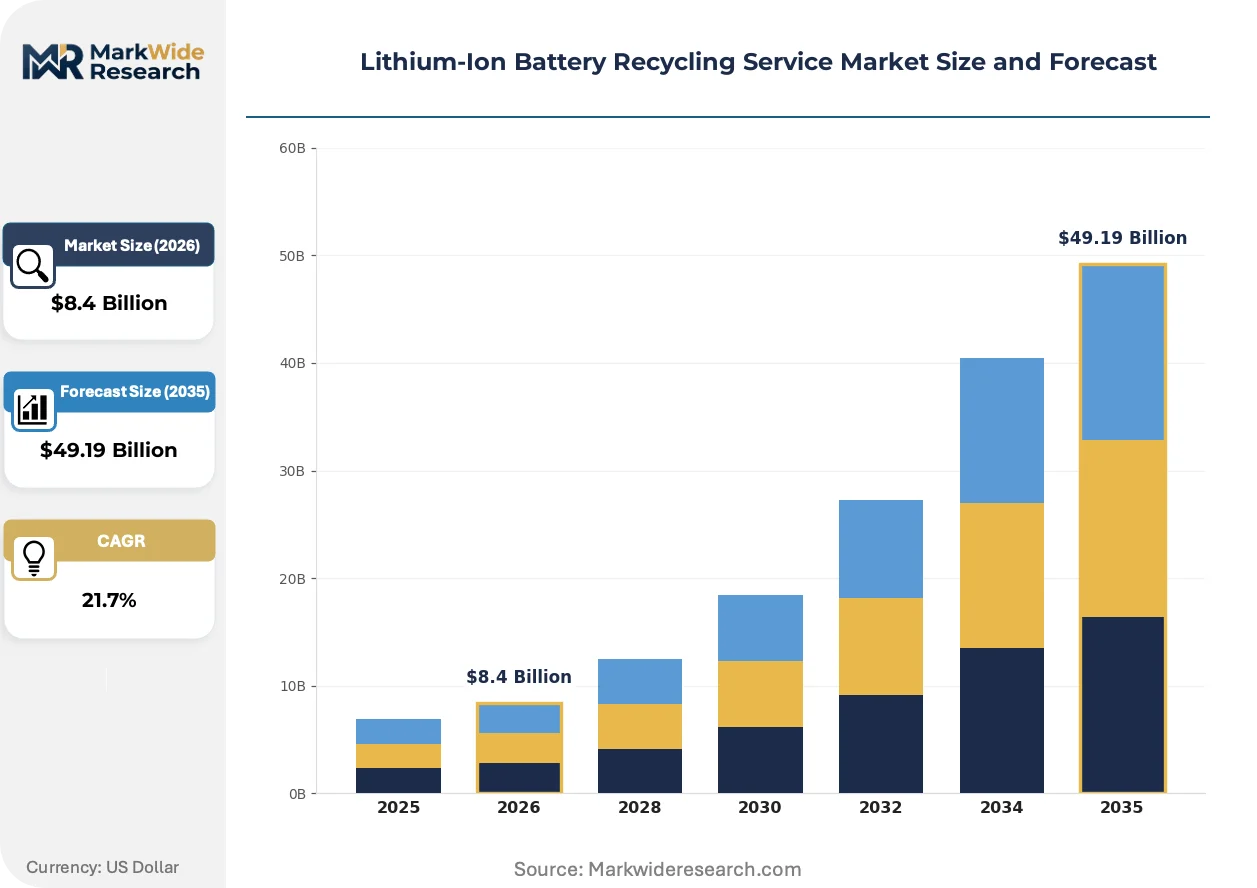
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $49.19 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Transportation, Processing, Refining Technology: Hydrometallurgical, Pyrometallurgical, Direct Recycling, Chemical End User: Automakers, Electronics Manufacturers, Battery Manufacturers, Waste Management Companies Regulatory Compliance: Waste Management Standards, Environmental Regulations, Health Safety Guidelines, Recycling Certifications |
| Companies Covered | Umicore, Glencore, Cirba Solutions, Li-Cycle Holdings Corp., GEM Co., Ltd., Redwood Materials, Contemporary Amperex Technology Co., Ltd., Fortum, Ecobat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Recycling Service Market Trends and Innovations
Recycling technology trajectories are diverging sharply between pyrometallurgical consolidation and hydrometallurgical specialization, with regulatory pressure and feedstock chemistry determining which route achieves viable unit economics in each geography.
Direct cathode regeneration is hybridizing mechanical separation with selective relithiation to restore spent NMC and LFP materials without full elemental dissolution. North American automakers are piloting this approach for their first-generation electric vehicle retirements. The technology is compressing the traditional smelter-refiner-precursor supply chain into single-facility operations.
REACH chemical registration requirements under ECHA are tightening traceability mandates for recovered materials entering European cathode manufacturing. Battery passports must document recycling origin and carbon intensity. Premium electric vehicle producers in Germany and Sweden are responding by qualifying only refiners with certified mass-balance accounting.
Automaker procurement departments are consolidating supplier lists around recyclers offering guaranteed battery-grade output specifications rather than commodity metal offtake. Tier-one cathode producers in South Korea and Japan are replacing spot-market black mass purchases with decade-long tolling agreements. This preference shift is most visible in contracts signed for European electric vehicle platform launches scheduled across 2027-2029.
Lithium-Ion Battery Recycling Service Market Segmentation
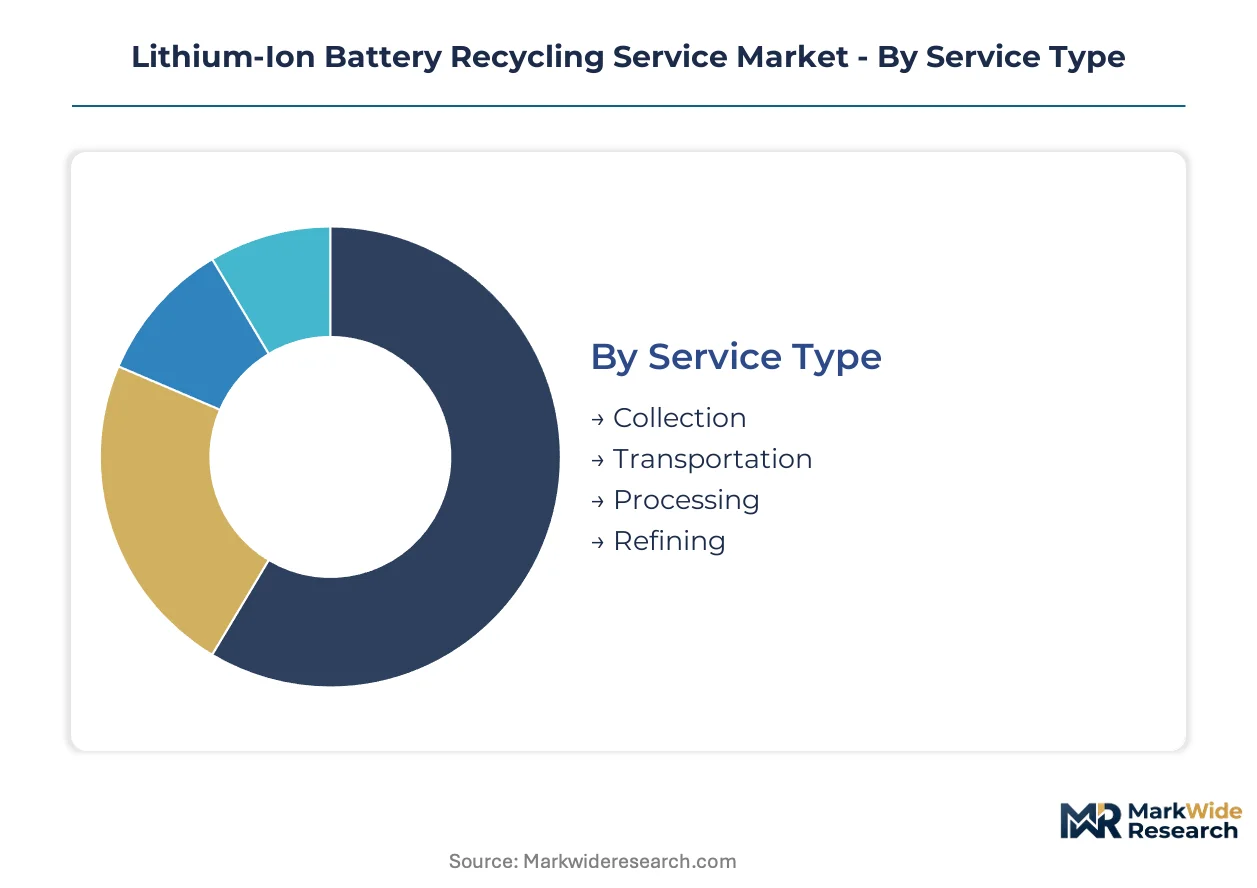
Recycling service segmentation reveals where margin pools concentrate across the value chain. Technology choices determine lithium recovery rates. Service type selection shapes capital intensity and regulatory exposure for operators.
Service Type:
Cost tier determines which service layers capture disproportionate investment as OEMs build captive networks.
- Collection:Reverse logistics networks aggregate spent cells from dispersed automotive dealerships and electronics retailers. Germany's dense charging infrastructure creates favorable collection economics for early EV retirements. EPA RCRA hazardous waste manifests complicate cross-state transport in the United States.
- Transportation:Specialized UN-certified containers and temperature-controlled trucking fleets move Class 9 dangerous goods under ADR and DOT regulations. Battery fires during transit have triggered insurer exclusions that inflate premiums for uncertified carriers.
- Processing:Mechanical shredding and black mass production concentrate feedstock for downstream refining. Chinese operators achieve scale advantages through integrated industrial park locations.
- Refining:Hydrometallurgical circuits extract battery-grade lithium, cobalt, and nickel salts for cathode precursor manufacturing. EU Battery Regulation recycled content mandates are pulling refining capacity into Poland and Finland.
Processing holds installed capacity. Refining is rotating up the share rankings.
Technology:
Application suitability varies sharply by feedstock chemistry homogeneity and target metal recovery specifications.
- Hydrometallurgical:Acid leaching and solvent extraction circuits operate below 100°C, preserving lithium in solution rather than slag. Umicore's Belgian facility and Redwood Materials' Nevada plant exemplify this route for automaker offtake contracts. The method commands premium margins where electricity costs are contained.
- Pyrometallurgical:High-temperature smelting at 1500°C recovers cobalt and nickel efficiently but volatilizes lithium into dust fractions requiring secondary capture. Legacy investments in Canada and Belgium face stranded asset risk as battery chemistries shift toward lithium-rich formulations.
- Direct Recycling:Cathode regeneration preserves crystal structure through selective relithiation, slashing re-manufacturing energy intensity. The approach demands homogeneous feedstock from single electric bus or stationary storage fleets.
- Chemical:Emerging precipitation and electrochemical methods target specific metal separations without full dissolution. Laboratory-stage variants show promise for LFP chemistry processing.
Hydrometallurgical routes dominate new investment. Direct recycling is expanding most quickly in pilot deployments.
End User:
Customer type determines contract structure, with automakers driving long-term tolling agreements versus spot-market waste handlers.
- Automakers:Volkswagen, BMW, and Tesla are signing decade-long offtake contracts to secure recycled content for EU Battery Regulation compliance. Their procurement teams specify battery-grade output rather than commodity metal pricing.
- Electronics Manufacturers:Consumer device OEMs generate smaller, more dispersed feedstock streams with lower cobalt concentrations than automotive packs. Collection economics favor urban consolidation hubs.
- Battery Manufacturers:CATL and LG Energy Solution are backward-integrating into recycling to control cathode precursor supply. Their specifications drive refining technology selection.
- Waste Management Companies:Traditional hazardous waste handlers lack battery-specific expertise, creating acquisition targets for specialized recyclers seeking collection network scale.
Automakers concentrate contract value. Battery manufacturers are climbing the fastest as vertical integrators.
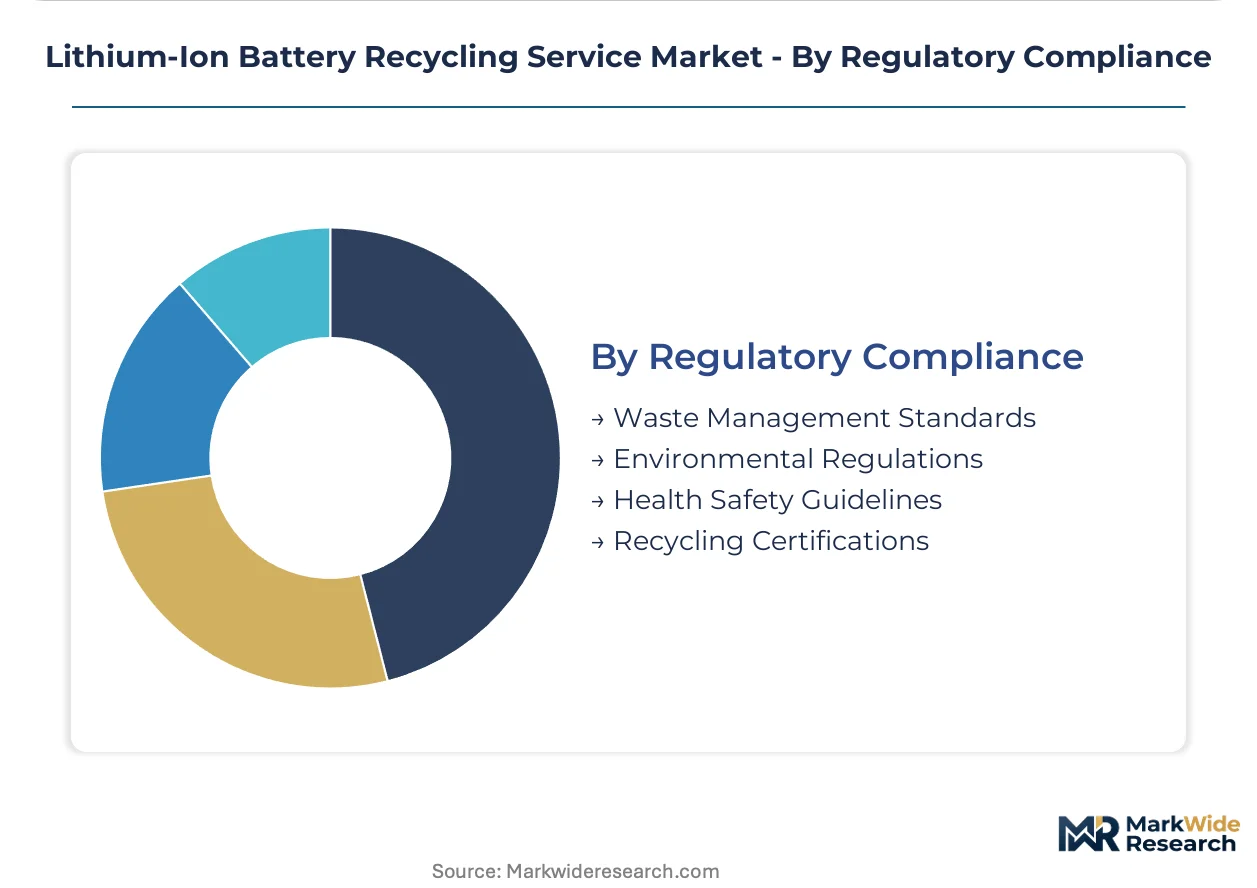
Regulatory Compliance:
Geography determines which compliance frameworks govern facility permitting and material traceability.
- Waste Management Standards:China's MEE solid waste classification rules and EPA RCRA subtitle C requirements create divergent feedstock access conditions. Cross-border black mass shipments face tightening scrutiny.
- Environmental Regulations:EU REACH chemical registration and ECHA battery passport mandates impose traceability burdens that favor integrated European refiners over Asian intermediate processors.
- Health Safety Guidelines:OSHA process safety management and EU SEVESO III rules govern thermal runaway prevention in storage and processing facilities. Compliance costs favor large-scale centralized operations.
- Recycling Certifications:ISO 14001 and R2/e-Stewards electronics recycling standards qualify suppliers for premium electric vehicle producer procurement lists in Germany and Sweden.
Environmental regulations hold enforcement gravity. Recycling certifications are gaining share fastest as procurement gatekeepers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refining capacity is clustering in jurisdictions with strict domestic content mandates and established automotive supply chains. Germany, China, the United States, Finland, and South Korea each host distinct competitive dynamics shaped by regulatory pressure and feedstock availability.
Germany
Volkswagen and BMW procurement teams are executing decade-long offtake contracts to secure recycled cobalt and nickel for EU Battery Regulation compliance. ECHA battery passport mandates under REACH require mass-balance traceability that favors integrated domestic refiners over Asian intermediate processors. The industrial belt around Dresden and Chemnitz is attracting hydrometallurgical investments from cathode precursor specialists.
China
CATL and BYD's vertical integration strategies are pulling black mass processing into captive industrial parks. MEE solid waste classification rules are tightening cross-border shipment scrutiny and accelerating domestic refining capacity buildout. The Yangtze River Delta around Ningbo and Suzhou concentrates mechanical shredding and hydrometallurgical operations at unmatched scale.
United States
Tesla and Ford are negotiating closed-loop supply chains to capture IRA domestic content credits for battery manufacturing. EPA RCRA hazardous waste facility approvals are extending permitting timelines to 24-36 months, compressing project delivery schedules. Nevada's Tahoe-Reno Industrial Center is emerging as a hub for automaker-aligned hydrometallurgical operations.
Finland
Nordic Energy's refining investments are targeting European automaker demand for low-carbon recycled nickel. The country's SEVESO III implementation creates favorable regulatory clarity for large-scale hazardous waste processing. The Kokkola industrial zone is expanding hydrometallurgical capacity to serve German cathode producer offtake agreements.
South Korea
LG Energy Solution and Samsung SDI are backward-integrating into recycling to secure precursor supply for NCM cathode production. The country's national waste management framework is evolving to classify spent EV batteries as strategic resources rather than disposable waste. The Ochang industrial complex is hosting pilot direct recycling facilities for homogeneous electric bus retirements.
Lithium-Ion Battery Recycling Service Market Competitive Landscape
Integrated smelter-precursor operators and specialized hydrometallurgical recyclers split the market along technology and geography lines. The structure is consolidating around three archetypes: European legacy smelters with cathode chemical expertise, North American closed-loop specialists serving automaker offtake contracts, and Chinese scale processors dominating black mass throughput. Competitive moves center on captive collection network buildout and regulatory-driven capacity localization.
Among European integrated operators, Umicore anchors the smelter-precursor archetype through its Belgian refining footprint and cathode material expertise. Redwood Materials exemplifies the North American closed-loop model with Nevada-based operations targeting automaker direct recycling partnerships. GEM Co., Ltd. occupies the scale-processing position within China's industrial belt, concentrating black mass throughput advantages. These three represent distinct strategic responses to diverging regulatory mandates across the EU Battery Regulation, IRA domestic content rules, and China's MEE solid waste standards.
| Leading Market Players |
|---|
| Umicore |
| Glencore |
| Cirba Solutions |
| Li-Cycle Holdings Corp. |
| GEM Co., Ltd. |
| Redwood Materials |
| Contemporary Amperex Technology Co., Ltd. |
| Fortum |
| Ecobat |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese black mass processing is compressing spot pricing and forcing European refiners toward captive offtake structures. Utilization rates below 60% in Yangtze River Delta shredding facilities are triggering margin defense through long-term tolling agreements with automakers.
Pricing Analysis
After-sales collection revenue now drives lifetime value more than commodity metal recovery, with reverse logistics commanding 35-45% of total service margins. Contract-based long-term offtake agreements dominate, with price differentiation resting on battery-grade output certification and mass-balance traceability under EU Battery Regulation mandates. Cost compression in spot-market black mass trading is intensifying because of feedstock oversupply from premature EV retirements. Waste management companies show highest price sensitivity; automakers accept premium pricing for guaranteed regulatory compliance.
Supply Chain Analysis
Tariff exposure between the United States and China is dominating strategic planning as the IRA domestic content rules reshape sourcing decisions. Geographic supply concentrates in China, Germany, and the United States for refining capacity, while raw material dependencies center on DRC cobalt, Chilean lithium, and Indonesian nickel. Single-source vulnerability in hydrometallurgical reagent supply creates chokepoint risk for European operators. Distribution runs through automaker-captive reverse logistics networks rather than merchant waste channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against direct recycling technologies that bypass traditional smelting entirely. Cathode regeneration startups threaten to displace elemental dissolution for homogeneous feedstock streams.
For Market Incumbents: Harden regulatory compliance moats by securing EU Battery Regulation certification ahead of 2027 enforcement deadlines. Expand hydrometallurgical capacity in Poland and Finland to capture German automaker offtake. Lock in exclusive collection agreements with Volkswagen and BMW procurement teams before direct recycling scales.
For New Entrants and Emerging Players: Southeast Asian underpenetration in integrated refining presents white-space opportunity as battery manufacturing shifts to Thailand and Vietnam. Target collection network gaps in secondary cities across Indonesia and Malaysia. Lead with second-life stationary storage partnerships to delay recycling costs and build feedstock relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrometallurgical refining as solvent extraction circuit complexity increases. Five-to-ten year viability favors operators with automaker-captive offtake rather than merchant spot exposure. Acquire mid-scale European refiners with pending EU Battery Regulation qualification. Watch for lithium price floor stabilization as the signal for refining margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Secures feedstock access under EPA RCRA and EU ADR hazardous waste rules. |
| Hydrometallurgical Capacity Expansion | Captures lithium recovery premiums as battery chemistries shift toward LFP and high-nickel NCM. |
| Direct Recycling Technology Licensing | Preserves cathode crystal structure for homogeneous electric bus and stationary storage retirements. |
| Long-term Automaker Offtake Agreements | Guarantees volume under EU Battery Regulation recycled content mandates. |
| Second-life Stationary Storage Partnerships | Delays recycling costs while extracting residual value from 70-80% capacity EV packs. |
Research Methodology
Operator-level perspectives from hydrometallurgical plant managers, automaker procurement directors, hazardous waste logistics coordinators, and cathode precursor R&D leads anchored the qualitative base. Primary interviews combined with secondary validation from EPA RCRA facility filings, EU ECHA battery passport registries, and Chinese MEE solid waste classification records. Bottom-up capacity buildout tracking and top-down metal flow analysis provided triangulation across the analysis window.
Scenario-bracketing framed the analytical approach, with segmentation modeled across service type, technology route, end-user category, and regulatory compliance tier. CAGRs derived from installed capacity expansion schedules and feedstock availability curves throughout the forecast period. Key inputs included EV retirement velocity projections and lithium spot price volatility bands.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and cobalt futures volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market