
 India Lithium-Ion Battery Market | 2026-2036
India Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
India Lithium-Ion Battery Market Outlook
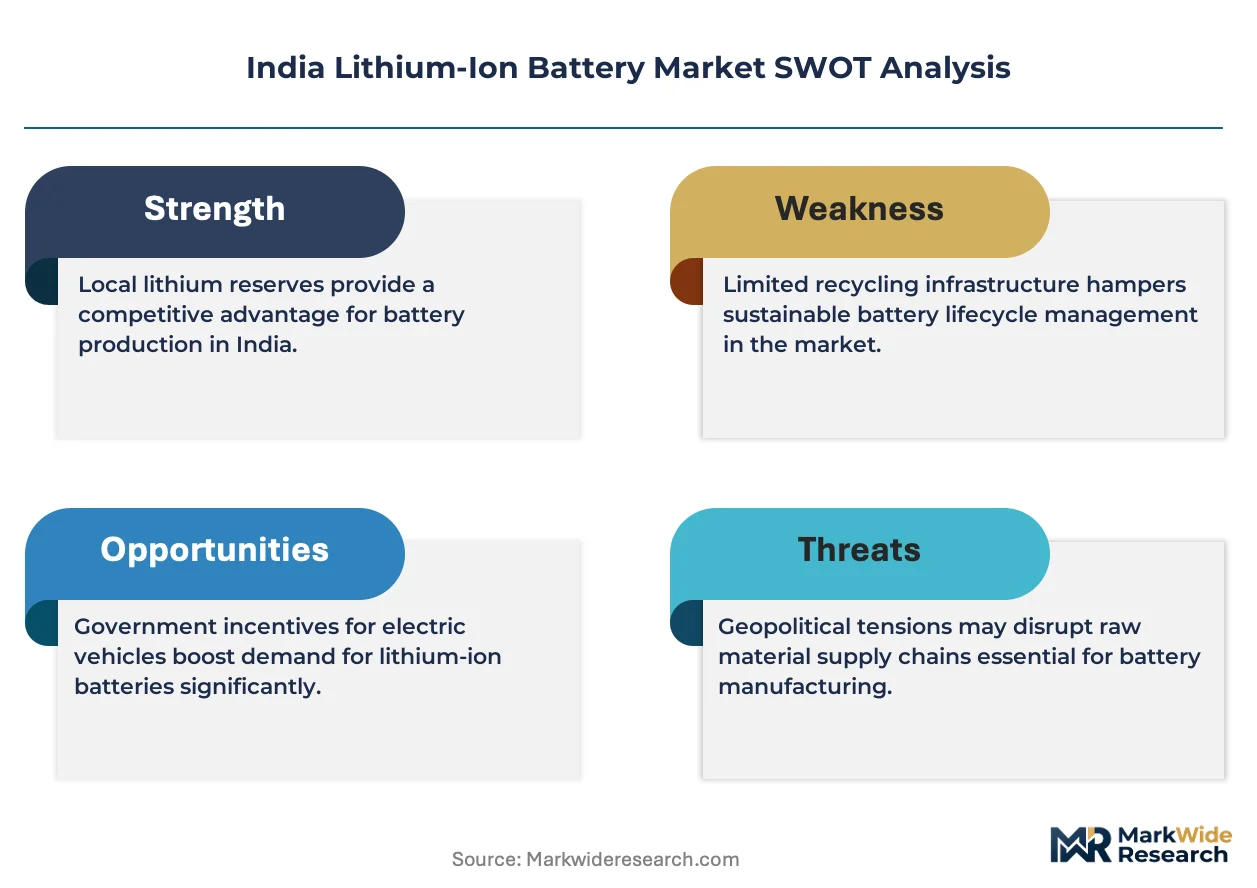
Two-wheeler fleet operators are redrawing procurement patterns across the India lithium-ion battery landscape as passenger EV uptake accelerates in parallel. Exide Industries leverages its established lead-acid distribution network to push into lithium-ion assembly. Ola Electric anchors its position through captive cell sourcing ambitions for its scooter platform. Reliance New Energy competes via aggressive backward integration into electrode materials and electrolyte production.
A lithium-ion battery stores electrochemical energy through reversible intercalation of lithium ions between a graphite anode and a metal-oxide cathode, delivering nominal cell voltages of 3.2–3.7 V depending on cathode chemistry; its primary purpose is to power mobile equipment and grid-connected storage with high energy density and cycle stability. LFP chemistry dominates commercial vehicle and stationary storage tenders where thermal safety and cycle life outweigh energy density requirements. NMC formulations occupy premium passenger EV segments where volumetric energy density drives pack-level range performance. NCA technology leads in imported high-performance applications where cobalt content enables maximum cathode specific capacity.
BIS certification mandates and the PLI scheme administered by the Ministry of Heavy Industries shape product standards and market access for domestic manufacturers. CEA grid interconnection regulations and state-level EV policies in Maharashtra, Delhi, and Telangana direct procurement specifications for energy storage deployments. Stakeholders must monitor cell-to-pack localization thresholds and cathode precursor supply security as policy compliance tightens.
Market Dynamics
India's lithium-ion battery sector faces acute cathode precursor import dependence as domestic cell assembly scales faster than upstream chemical refining capacity. The PLI scheme's localization thresholds are compressing supply chain timelines for electrode active material sourcing.
Growth Catalysts
- PLI Scheme Incentives:The Ministry of Heavy Industries administers production-linked incentives that offset capital costs for advanced chemistry cell manufacturing, drawing investment toward Tamil Nadu and Gujarat gigafactory clusters.
- Electric Two-Wheeler Fleet Deployment:Commercial operators in Bengaluru and Delhi are consolidating procurement through long-term offtake agreements with pack assemblers, creating predictable demand baselines for cell suppliers.
- LFP Chemistry Maturation:Iron phosphate cathode formulations are capturing stationary storage and commercial vehicle tenders where cycle stability and thermal runaway resistance outweigh energy density requirements.
Market Restraints
- Lithium Carbonate Import Concentration:Over 95% of battery-grade lithium compounds arrive from Chinese refiners, exposing assemblers to price volatility and supply disruption during trade friction episodes.
- Cobalt Supply Chain Ethics:NMC and NCA cathode chemistries depend on cobalt originating from Central African mining jurisdictions with documented labor practice concerns, triggering due diligence cost inflation.
- BIS Certification Timelines:Bureau of Indian Standards cell testing protocols extend product qualification cycles by 8-14 months, delaying commercialization for new domestic entrants.
Strategic Opportunities
- Recycling Infrastructure Buildout:Spent battery collection networks in Maharashtra and Telangana are creating feedstock streams for hydrometallurgical lithium recovery, reducing virgin material dependence.
- Solid-State Electrolyte Development:Research partnerships between IIT institutions and industrial labs are advancing sulfide and oxide ceramic separators that could leapfrog liquid electrolyte limitations in high-temperature applications.
- State EV Policies:Delhi's electric vehicle policy mandates 50% fleet electrification for commercial operators by 2027, creating guaranteed demand pools for swappable battery business models.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell design and manufacturing process engineering expertise concentrates in South Korean and Japanese expatriate pools, constraining domestic knowledge transfer.
- Dry Electrode Coating Scale-Up:Solvent-free electrode manufacturing reduces energy intensity but requires precision calendaring equipment that lacks local service infrastructure.
- Pack Thermal Management Integration:Liquid cooling system design for Indian ambient temperature profiles demands computational fluid dynamics capabilities that most domestic integrators are assembling from scratch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lithium-Ion Battery Market |
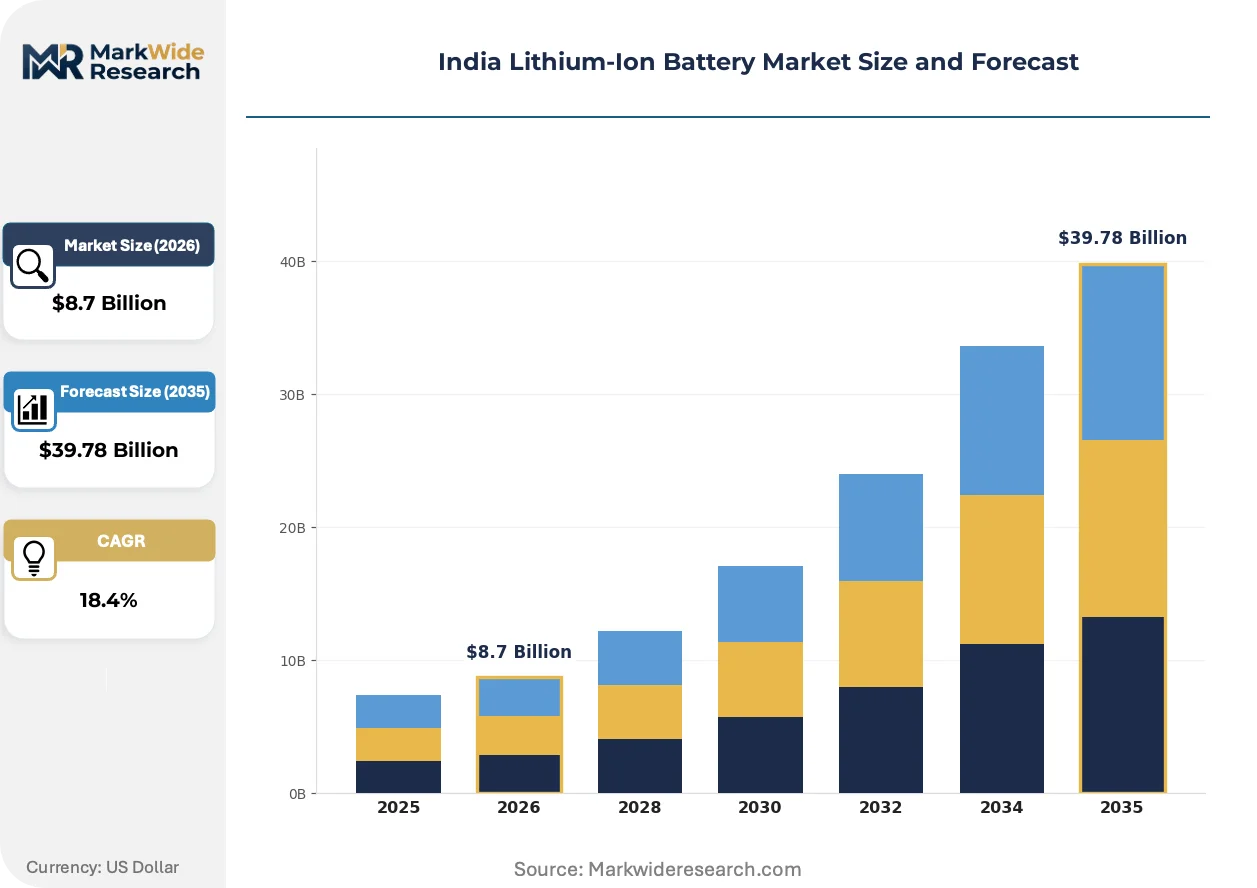
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Applications End User: Automotive Manufacturers, Electronics Companies, Energy Suppliers, Telecommunications Providers Technology: LFP, NMC, NCA, LCO Application: Power Tools, UPS Systems, Renewable Energy Grids, Medical Devices |
| Companies Covered | Exide Industries, Amara Raja, Ola Electric, LG Energy Solution, Reliance New Energy, Okaya Power, Waaree Energies, Servotech Renewable Power System, LOHUM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lithium-Ion Battery Market Strategic Shifts
Cell-to-pack architectures are eliminating module housings and busbar complexity, while solid-state research programs accelerate. Regulatory pressure on supply chain traceability is forcing disclosure system investments.
Prismatic cell formats with cell-to-pack integration are miniaturizing auxiliary structural components in passenger EV applications. Maruti Suzuki and Tata Motors procurement teams are specifying these designs for 2026 platform launches. The technology is compressing pack-level cost structures by 12-18% while improving volumetric energy density.
BIS certification mandates for lithium-ion cells and battery management systems are tightening product liability frameworks for domestic manufacturers. The regulations are forcing pack assemblers to invest in in-house testing laboratories rather than relying on third-party certification bodies. Two-wheeler OEMs in Gujarat are responding by consolidating supplier bases to reduce qualification overhead.
Fleet operators are unbundling battery ownership from vehicle acquisition through leasing structures that transfer residual value risk to financial intermediaries. Commercial two-wheeler and three-wheeler segments in Delhi and Bengaluru are adopting this model fastest. The shift is compressing payback period calculations for electrification decisions and accelerating replacement cycle velocity in high-utilization applications.
India Lithium-Ion Battery Market Segmentation
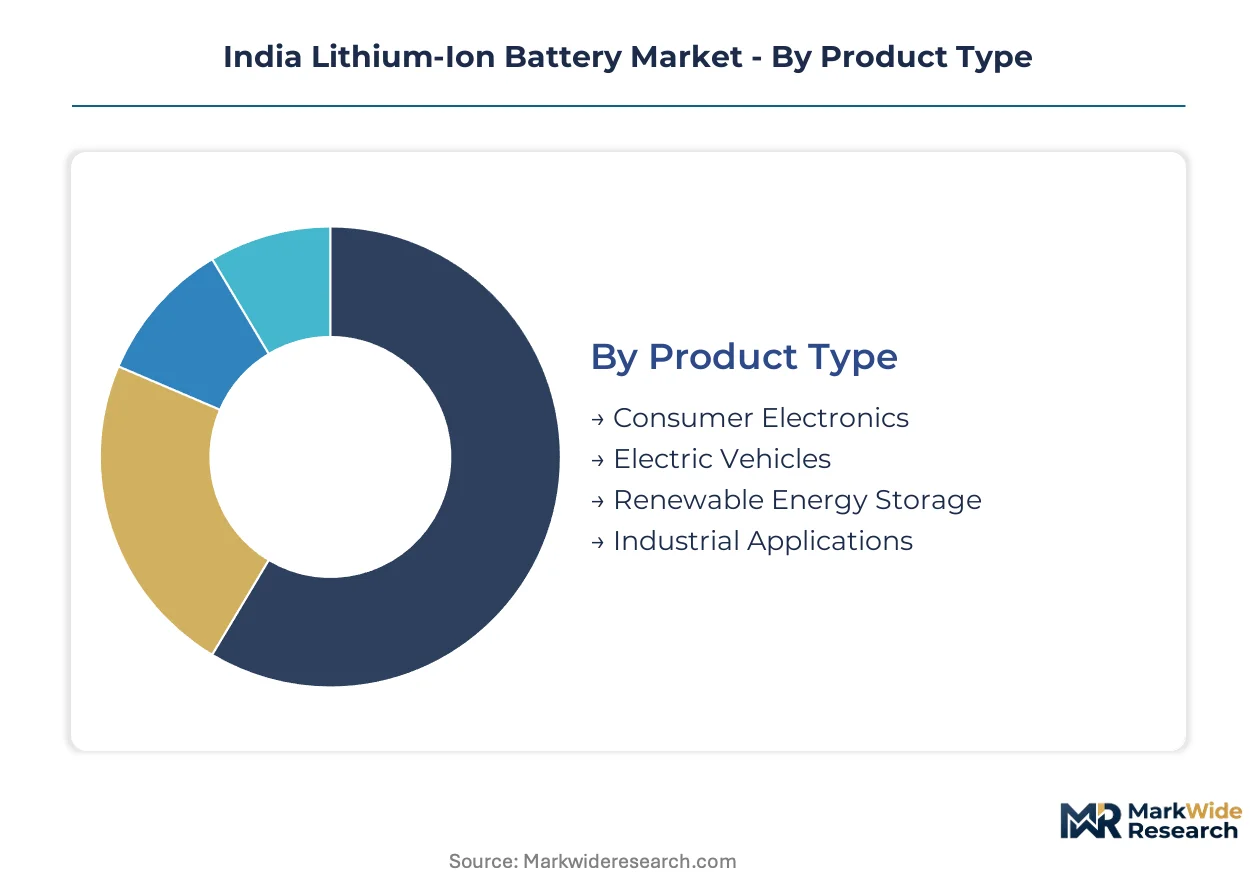
Segmentation in India's lithium-ion battery market reveals how cathode chemistry selection and end-use thermal requirements dictate procurement specifications. Manufacturers must align product portfolios with BIS certification pathways and PLI localization thresholds that vary sharply across application categories.
Product Type:
Substitution pressure from lead-acid alternatives and supercapacitor hybrids is most acute in segments where cycle life requirements remain modest.
- Electric Vehicles:LFP and NMC chemistries dominate pack designs for two-wheelers, three-wheelers, and passenger cars, with Gujarat and Tamil Nadu assembly plants driving procurement concentration. The PLI scheme's advanced chemistry cell incentives are accelerating local gigafactory investment for this segment.
- Renewable Energy Storage:Grid-scale lithium-ion systems face competition from sodium-ion and flow battery technologies in long-duration applications, though four-hour discharge configurations retain cost advantages for solar-wind hybrid projects in Rajasthan and Karnataka.
- Consumer Electronics:Cylindrical 18650 and 21700 formats serve smartphone and laptop OEMs.
- Industrial Applications:Forklift and material handling equipment conversions favor LFP for safety compliance.
Electric Vehicles retains volume leadership; Renewable Energy Storage holds the steepest expansion curve.
End User:
Cost tier differentiation separates integrators with captive cell ambitions from those dependent on merchant supply.
- Automotive Manufacturers:Tata Motors, Mahindra, and Ola Electric are consolidating supplier bases around cell-to-pack architectures, with in-house BMS development becoming a competitive necessity for platform differentiation.
- Energy Suppliers:NTPC, Tata Power, and state discoms in Maharashtra and Gujarat are tendering for grid-connected storage with stringent localization requirements.
- Electronics Companies:Smartphone and laptop OEMs specify UN38.3-certified cells for export compliance.
- Telecommunications Providers:Tower operators in Delhi and Bengaluru are deploying swappable battery systems for diesel displacement.
Automotive Manufacturers command the premium tier; Energy Suppliers are expanding most quickly.
Technology:
Volume concentration in LFP is reshaping cathode precursor import requirements and thermal management specifications.
- LFP:Iron phosphate cathodes deliver 3.2V nominal voltage with superior thermal stability, capturing commercial vehicle and stationary storage tenders where cycle life exceeds 4,000 cycles and safety certification is paramount.
- NMC:Nickel-manganese-cobalt layered oxides achieve higher volumetric energy density for premium passenger EVs, though cobalt sourcing ethics and BIS testing timelines constrain new entrants.
- NCA:Nickel-cobalt-aluminum chemistry leads in imported high-performance applications.
- LCO:Lithium cobalt oxide remains confined to consumer electronics with limited domestic assembly.
LFP retains volume leadership; NMC holds the steepest expansion curve.
Application:
Geographic clustering in western and southern states is driving specification divergence between grid-scale and portable power applications.
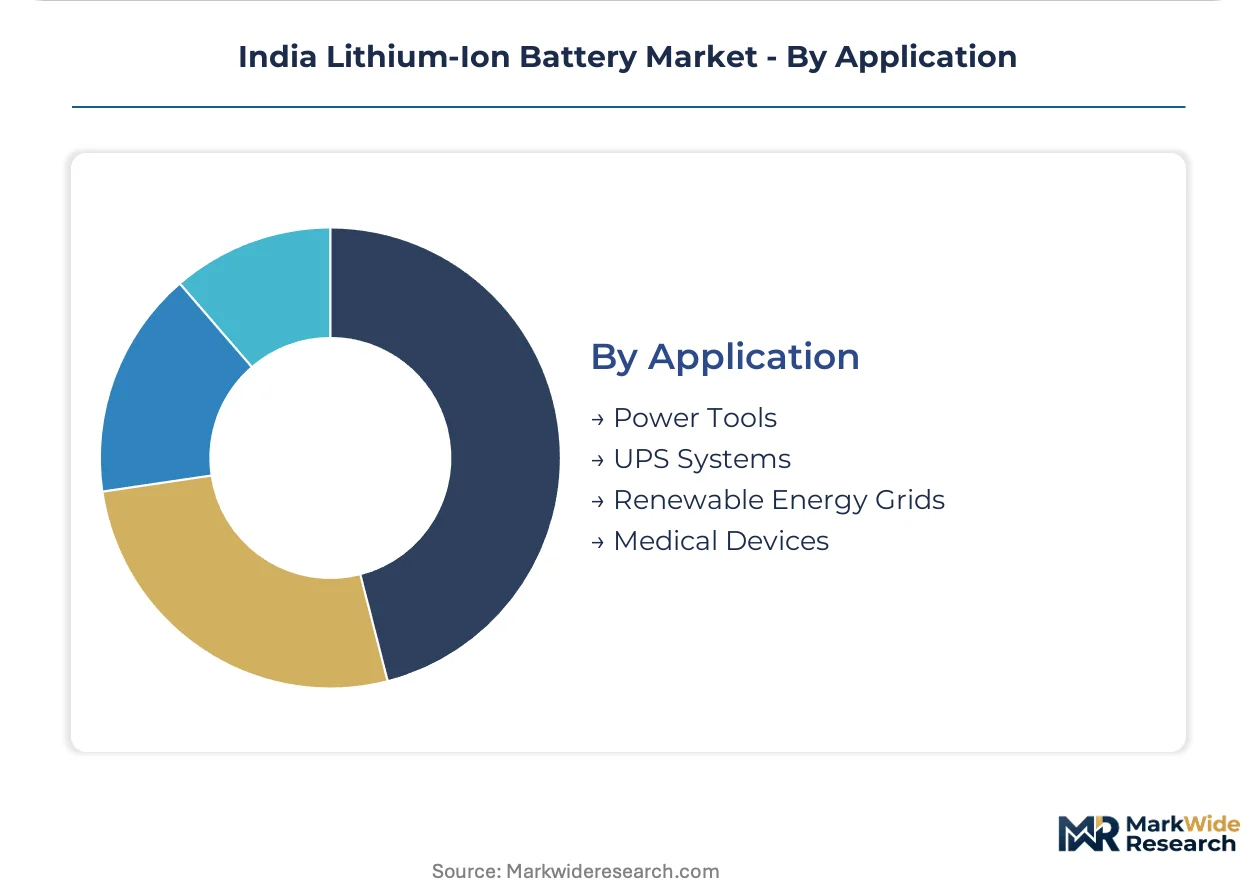
- Renewable Energy Grids:Solar-wind hybrid projects in Rajasthan, Gujarat, and Karnataka are specifying containerized battery energy storage systems with CEA grid interconnection compliance, creating demand for 1C continuous discharge capability.
- UPS Systems:Data center operators in Mumbai, Chennai, and Hyderabad are transitioning from lead-acid to lithium-ion for footprint reduction, with 15-minute backup configurations dominating.
- Power Tools:Cordless equipment OEMs source cylindrical cells for torque density.
- Medical Devices:Portable diagnostic equipment requires IEC 62133 certification.
Renewable Energy Grids retains volume leadership; UPS Systems holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mundra Port deepwater facility anchors Gujarat's battery export capacity, handling cathode precursor imports and finished pack shipments for OEM supply chains across western India.
Gujarat
Two-wheeler OEMs and commercial vehicle assemblers drive procurement concentration around the Sanand-Vithalapur industrial corridor. The state's EV policy administered by the Gujarat Industrial Development Corporation offers capital subsidies for gigafactory establishment. Reliance New Energy's Jamnagar complex is scaling electrode active material production to feed regional cell assembly lines.
Tamil Nadu
Passenger EV manufacturers and energy storage integrators cluster around the Sriperumbudur-Oragadam belt. The Tamil Nadu EV policy administered by the state's Industries Department mandates 100% renewable power for battery manufacturing facilities. Hyundai Motor India's Chennai operations are localizing cell-to-pack assembly for platform launches targeting 2026.
Karnataka
Electric two-wheeler fleet operators and data center UPS deployers concentrate demand in Bengaluru's urban perimeter. The Karnataka Electric Vehicle and Energy Storage Policy administered by the state's Department of Industries and Commerce incentivizes swappable battery infrastructure. Ola Electric's Krishnagiri facility is expanding cylindrical cell assembly capacity for captive scooter platform consumption.
Maharashtra
Grid-scale storage tenders and telecom tower backup systems shape procurement specifications across Mumbai-Pune-Nashik triangle. The Maharashtra EV policy administered by the state's Transport Department mandates 25% fleet electrification for commercial operators by 2025. Tata Power's Pune operations are tendering for containerized battery energy storage systems with CEA grid interconnection compliance.
Delhi-NCR
Commercial two-wheeler fleet electrification and public transport battery leasing drive demand concentration. The Delhi EV policy administered by the state's Transport Department mandates 50% commercial fleet electrification by 2027. Okaya Power's Faridabad operations are deploying swappable battery stations for last-mile delivery operators.
India Lithium-Ion Battery Market Competitive Environment
Listed leaders compete with private specialists across capital access and speed-to-market dimensions. The vendor base stratifies into three tiers: diversified conglomerates with captive demand, pure-play battery specialists with assembly expertise, and Korean-Japanese cell suppliers with technology licensing arrangements. Consolidation pressure intensifies as PLI localization thresholds favor scale. Dominant competitive moves include backward integration into electrode materials and strategic partnerships for BMS software development.
Within the diversified conglomerate tier, Reliance New Energy and Exide Industries occupy positions that exemplify contrasting strategic postures. Reliance anchors upstream chemical refining ambitions through its Jamnagar complex. Exide leverages established lead-acid distribution infrastructure to push into lithium-ion pack assembly. Among pure-play specialists, Ola Electric represents the captive-demand archetype through its scooter platform integration.
| Leading Market Players |
|---|
| Exide Industries |
| Amara Raja |
| Ola Electric |
| LG Energy Solution |
| Reliance New Energy |
| Okaya Power |
| Waaree Energies |
| Servotech Renewable Power System |
| LOHUM |
| Others |
Value Chain & Pricing Dynamics
Inventory carrying costs spanning 90-120 days for cathode precursor stockpiles concentrate pricing power with Chinese refiners who dictate contract terms to Indian pack assemblers. The PLI scheme's localization mandates compress these timelines while BIS certification delays extend capital lockup periods, squeezing margins across the value chain.
Pricing Analysis
Volume-discount tiering separates gigafactory-scale offtake agreements from spot procurement for sub-gigawatt-hour assemblers. Pricing stratifies across premium NMC cells for passenger EVs, standard LFP formats for commercial vehicles, and economy-grade refurbished packs for telecom backup. Cost compression in the economy tier intensifies as recycling infrastructure matures and secondary material flows expand. Fleet operators with consolidated procurement volumes exhibit lowest price sensitivity; small pack assemblers dependent on merchant cell supply face highest margin pressure.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and cobalt sulfate dominates procurement strategy given maritime transit unreliability through the Strait of Malacca. Raw material sourcing draws from Chinese refiners for battery-grade lithium compounds, South Korean cathode manufacturers for precursor materials, and Australian spodumene concentrate for upstream feedstock. Single-source vulnerability concentrates in Chinese-controlled lithium hydroxide refining capacity. Distribution runs through Mundra and Chennai port facilities to Gujarat and Tamil Nadu assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cathode chemistry specializations creates niche opportunities as fleet operators, grid developers, and consumer OEMs diverge on thermal management and cycle life priorities.
For Market Incumbents: Shield market position through backward integration into electrode active material production and captive BMS software development. Sodium-ion substitution technology threatens LFP dominance in stationary storage tenders. Capacity addition in Tamil Nadu and Gujarat gigafactory corridors secures PLI incentive access while supplier base consolidation reduces BIS qualification overhead. For New Entrants and Emerging Players: Differentiate on solid-state electrolyte development partnerships with IIT research networks and hydrometallurgical recycling capabilities in Maharashtra. Swappable battery infrastructure for commercial two-wheeler fleets in Delhi-NCR represents the most penetrable white space. Go-to-market execution should anchor on long-term leasing structures that transfer residual value risk to financial intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cell-to-pack architecture manufacturing as precision calendaring equipment requirements escalate. Acquisition targets with electrode coating expertise and established BIS certification pathways offer strongest five-to-ten-year viability. Monitor PLI localization threshold tightening as the signal indicating margin compression for import-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Reliance New Energy's Jamnagar complex reduces import dependence for Indian cell manufacturers. |
| Cell-to-Pack Architecture Adoption | Tata Motors and Maruti Suzuki procurement specifications eliminate module housing costs for 2026 platforms. |
| Swappable Battery Infrastructure Deployment | Okaya Power's Faridabad stations enable Delhi's 50% commercial fleet electrification mandate. |
| Hydrometallurgical Recycling Scale-Up | LOHUM's Maharashtra operations recover lithium from spent batteries to reduce virgin material sourcing. |
| Solid-State Electrolyte R&D Partnerships | IIT collaborations advance sulfide ceramic separators for high-temperature Indian ambient conditions. |
Study Parameters
Operator-level perspectives from cell manufacturing engineers, pack assembly plant managers, OEM procurement leads, and CEA grid interconnection officers anchored the qualitative base. Primary interview findings triangulated against secondary sources including BIS certification databases, Ministry of Heavy Industries PLI scheme disclosures, CEA grid regulations, and state EV policy documents. Bottom-up capacity buildout estimates from Tamil Nadu and Gujarat gigafactory clusters converged with top-down demand projections from automotive and energy storage segments.
Sensitivity analysis tested forecast robustness across lithium carbonate price volatility bands and PLI localization threshold scenarios. Segmentation modeling incorporated cathode chemistry type, end-use application, and regional manufacturing cluster dimensions. CAGRs derived from installed capacity ramp schedules and offtake agreement timelines. Key inputs included electric two-wheeler fleet deployment trajectories in Bengaluru and Delhi, plus solar-wind hybrid storage tender specifications in Rajasthan and Karnataka.
Material uncertainties — raw material supply disruption, BIS certification timeline extensions, and state EV policy revisions — sit outside the modeled envelope. Forecasts reflect assumptions on cathode precursor import dependence and cell-to-pack localization progress. Revision becomes warranted when Chinese lithium refining capacity utilization crosses thresholds that trigger export restriction protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market