
 Lithium Ion Battery Recovery Market | 2026-2036
Lithium Ion Battery Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Battery Recovery Market Insights
The price gap between high-purity cathode-grade lithium carbonate and mixed black mass is hardening as feedstock quality diverges. Umicore leverages integrated hydrometallurgical refining to sustain premium product positioning across European cathode supply chains. Redwood Materials anchors North American operations through closed-loop partnerships with domestic automakers, while Brunp Recycling dominates Chinese capacity expansion via direct ties to CATL's manufacturing ecosystem.
Lithium ion battery recovery encompasses the collection, dismantling, and chemical processing of spent cells to reclaim cobalt, lithium, nickel, and manganese at purities exceeding 99.5% for re-entry into cathode manufacturing. The process employs hydrometallurgical leaching, pyrometallurgical smelting, or mechanical shredding followed by solvent extraction to isolate individual metals from complex cell chemistries including NMC, LFP, and NCA formulations. Hydrometallurgical routes command widening margin pools as cathode makers demand battery-grade salts rather than intermediate alloys. Pyrometallurgical recovery retains scale advantages for mixed feedstocks but faces energy cost pressures that biotechnological alternatives have yet to resolve at commercial throughput.
The EU Battery Regulation and REACH compliance frameworks mandate minimum recycled content thresholds and full material traceability, forcing non-compliant material out of European supply chains. EPA hazardous waste rules under RCRA govern US interstate transport and permitting for spent battery processing facilities, while China's MIIT issues capacity licenses that constrain unqualified entrants. Stakeholders must track how regulatory divergence between these jurisdictions reshapes arbitrage opportunities for black mass trade and determines where downstream refining investments concentrate.
Market Dynamics
The EU Battery Regulation's recycled content mandates are compressing compliance timelines and forcing cathode manufacturers to secure qualified feedstock years ahead of statutory deadlines. This regulatory pressure is reshaping investment flows toward integrated refining capacity.
Growth Catalysts
- EU Battery Regulation:Mandated minimum recycled content thresholds for lithium, cobalt, and nickel in new batteries create guaranteed offtake for qualified refiners.
- Electric vehicle manufacturers:Closed-loop collection programs with direct recycling partnerships secure proprietary feedstock streams independent from spot black mass markets.
- Hydrometallurgical leaching:Direct recovery of battery-grade salts bypasses intermediate alloy stages, capturing margin pools previously lost to smelters.
Market Restraints
- Feedstock quality volatility:Mixed black mass from consumer electronics lacks the metal concentrations of automotive packs, depressing unit economics for non-integrated processors.
- Chinese capacity concentration:MIIT licensing constraints limit qualified entrants while CATL-affiliated recyclers dominate domestic feedstock allocation.
- Pyrometallurgical energy intensity:Natural gas and electricity cost spikes in European smelting operations erode margins against hydrometallurgical alternatives.
Strategic Opportunities
- India's nascent EV fleet:Battery waste volumes remain below commercial threshold, creating first-mover advantage for pre-positioned collection infrastructure.
- Direct recycling technologies:Cathode regeneration without full elemental separation preserves crystal structure and reduces reprocessing energy by half.
- US Inflation Reduction Act:Domestic content credits for North American recycled materials accelerate refinery construction timelines.
Industry Challenges
- Qualified chemical engineer scarcity:Hydrometallurgical process design and solvent extraction optimization require specialized talent pools concentrated in mining and specialty chemicals.
- EPA RCRA permitting timelines:Hazardous waste facility approvals for spent battery processing stretch 18-36 months, delaying revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Battery Recovery Market |
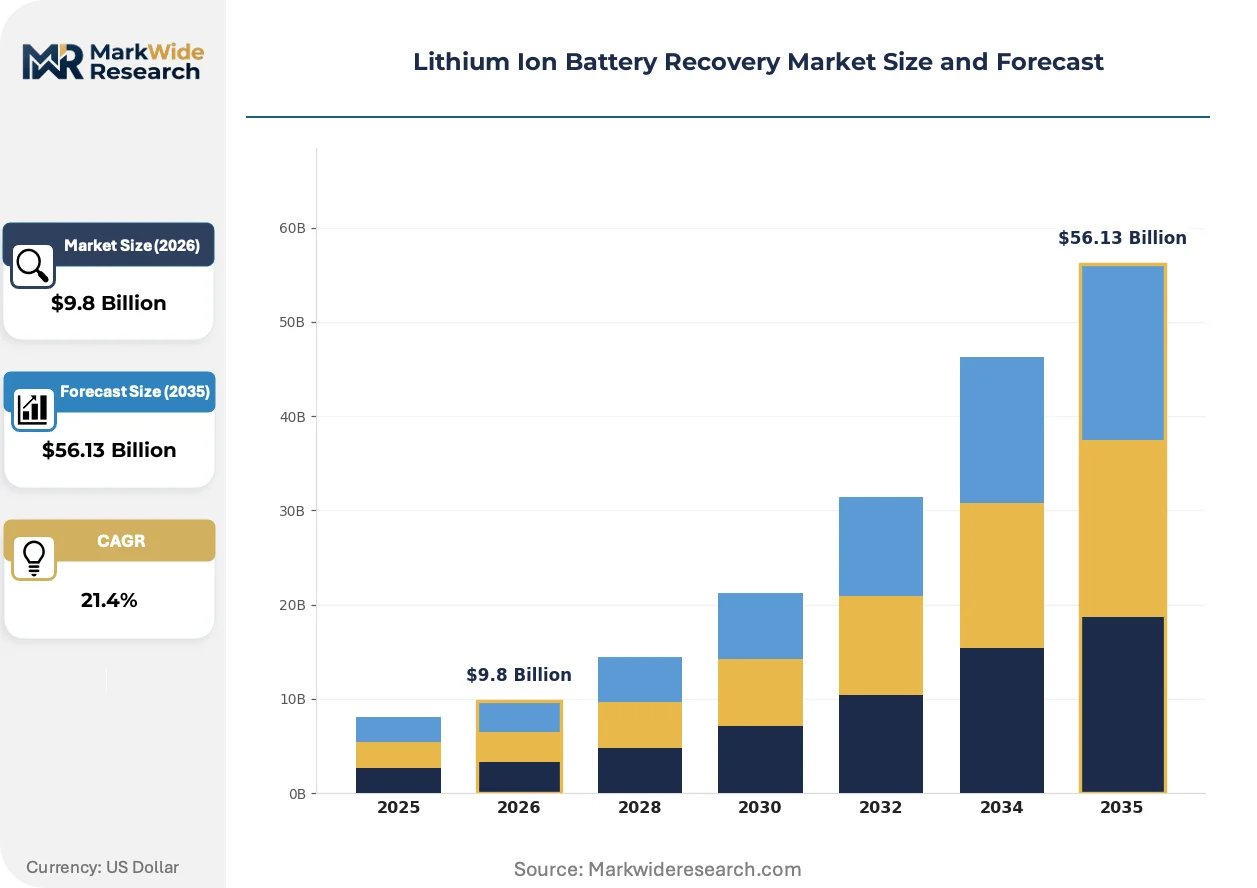
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $56.13 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycling, Reuse, Refurbishing, Disposal Technology: Hydrometallurgical, Pyrometallurgical, Biotechnological, Mechanical End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Application: Energy Storage Systems, Electric Vehicles, Portable Devices, Backup Power |
| Companies Covered | Umicore, Glencore, Cirba Solutions, Li-Cycle Holdings Corp, Redwood Materials, GEM Co., Ltd., Brunp Recycling, Accurec Recycling GmbH, American Battery Technology Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Battery Recovery Market Trends and Innovations
Recovery technology is pivoting from metal extraction toward cathode reconstruction, while regulatory traceability requirements and automaker vertical integration are rewriting procurement hierarchies.
Direct cathode regeneration is absorbing engineering investment previously directed toward elemental separation. BMW and Ford have pilot programs with American Manganese and Li-Cycle testing regeneration of NMC 622 structures without full dissolution. The process preserves crystalline morphology and cuts reprocessing energy by forty percent, compressing payback periods for integrated facilities.
REACH Article 33 disclosure obligations and the EU Battery Regulation's digital passport requirements are forcing full material provenance tracking from collection through refining. Umicore and Glencore have deployed blockchain-based chain-of-custody systems to satisfy downstream cathode maker audits. European OEMs now reject black mass without certified origin documentation, segmenting the feedstock market into compliant and non-compliant tiers.
Automakers are internalizing collection networks and pre-negotiating tolling arrangements rather than purchasing recycled materials on spot markets. Volkswagen's partnership with Redwood Materials and Mercedes-Benz's equity stake in Primobius lock in decade-long offtake at fixed conversion fees. This channel compression is most advanced in Germany and California, where producer responsibility laws assign legal liability for end-of-life batteries to vehicle manufacturers.
Lithium Ion Battery Recovery Market Segmentation
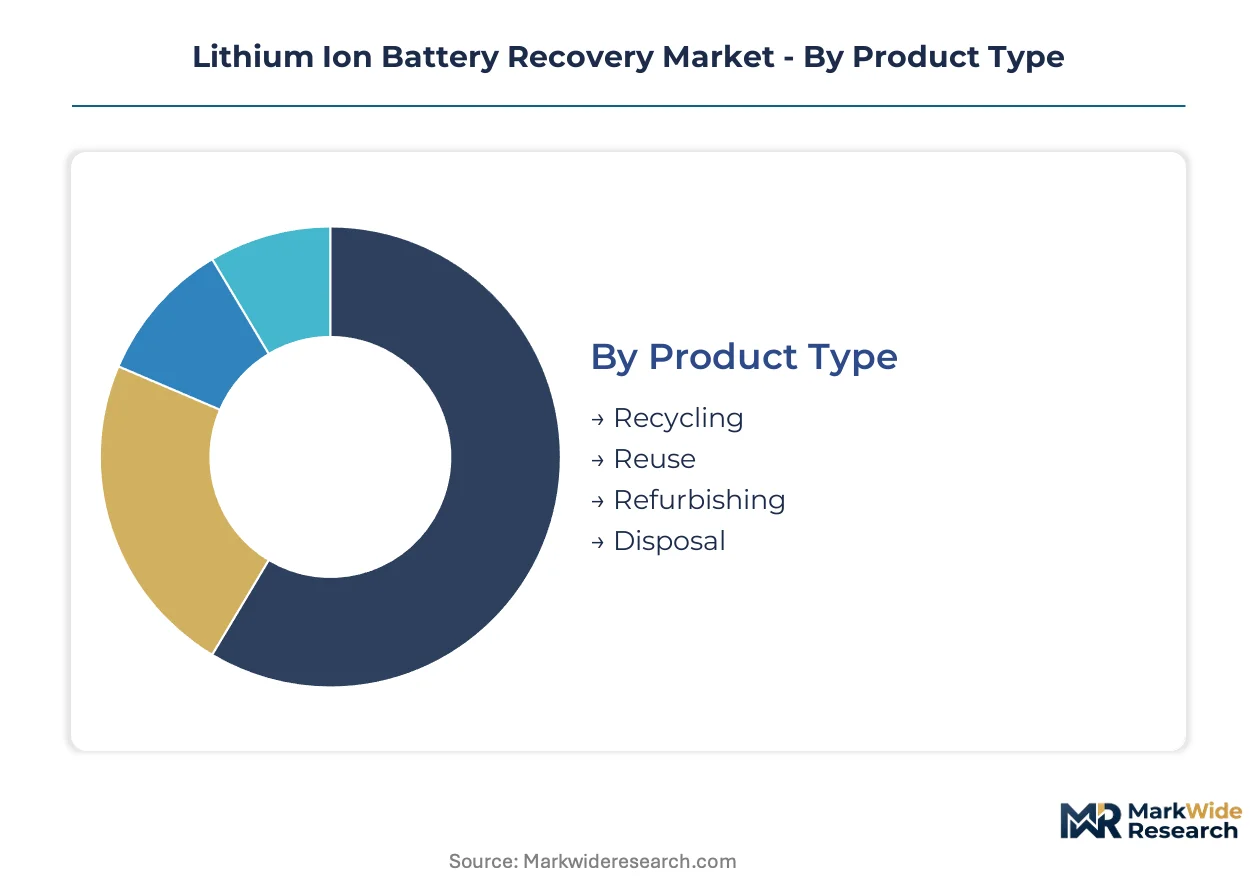
Recovery economics diverge sharply across process technologies and battery chemistries. Procurement teams now segment suppliers by metal purity thresholds and regulatory compliance tiers rather than tonnage throughput alone.
Product Type:
End-of-life value capture hinges on remaining state-of-health diagnostics and residual capacity testing.
- Recycling:Full elemental recovery through hydrometallurgical or pyrometallurgical routes yields battery-grade lithium carbonate, cobalt sulfate, and nickel sulfate. European cathode manufacturers under EU Battery Regulation mandates now require certified recycled content quotas, locking in premium offtake for qualified refiners.
- Reuse:Second-life applications repurpose automotive packs with 70-80% remaining capacity into stationary energy storage. California's SGIP incentive program and Germany's KfW funding schemes concentrate demand for grid-scale battery installations.
- Refurbishing:Cell replacement and module rebalancing extend service life for industrial forklift fleets and telecom backup systems. Toyota Material Handling and Linde operate captive refurbishing centers for their installed base.
- Disposal:Landfill diversion for damaged or uneconomical cells requires hazardous waste permitting under EPA RCRA rules in the United States and equivalent national frameworks elsewhere.
Recycling leads on scale; reuse leads on momentum.
Technology:
Process selection determines both capital intensity and product slate chemistry.
- Hydrometallurgical:Acid leaching and solvent extraction recover individual metals at 99.5%+ purity for direct cathode re-entry. Energy costs run 40% below pyrometallurgical alternatives, widening margin capture as European natural gas prices spike.
- Pyrometallurgical:High-temperature smelting produces mixed metal alloys requiring secondary refining. The route retains throughput advantages for contaminated feedstocks but faces carbon border adjustment exposure under EU CBAM implementation.
- Biotechnological:Bioleaching with acidophilic bacteria operates at ambient temperatures and pressures. Glencore's pilot with Mint Innovation targets copper and cobalt recovery from low-grade black mass.
- Mechanical:Shredding, sorting, and density separation prepare feedstock for downstream chemical processing. The step is universally required but adds limited value without integrated refining.
Hydrometallurgical routes dominate new capacity announcements; biotechnological approaches are climbing the fastest.
End User:
Volume concentration and collection logistics vary dramatically by sector maturity.
- Automotive:OEM-led collection networks under extended producer responsibility laws generate homogeneous, high-metal-content feedstock. Volkswagen's closed-loop partnership with Redwood Materials and Mercedes-Benz's equity in Primobius exemplify captive sourcing strategies.
- Consumer Electronics:Fragmented discard channels and mixed chemistries depress unit economics. Apple's independent recycler program and Best Buy's retail collection points represent partial consolidation efforts.
- Renewable Energy:Utility-scale solar-plus-storage installations are approaching first replacement cycles. Tesla's Megapack and Fluence deployments in California and Australia will generate predictable volume streams.
- Industrial:Forklift, mining equipment, and telecom backup batteries operate on predictable replacement schedules. Crown Equipment and Hyster-Yale maintain direct service relationships enabling planned collection.
Automotive leads on scale; renewable energy leads on momentum.
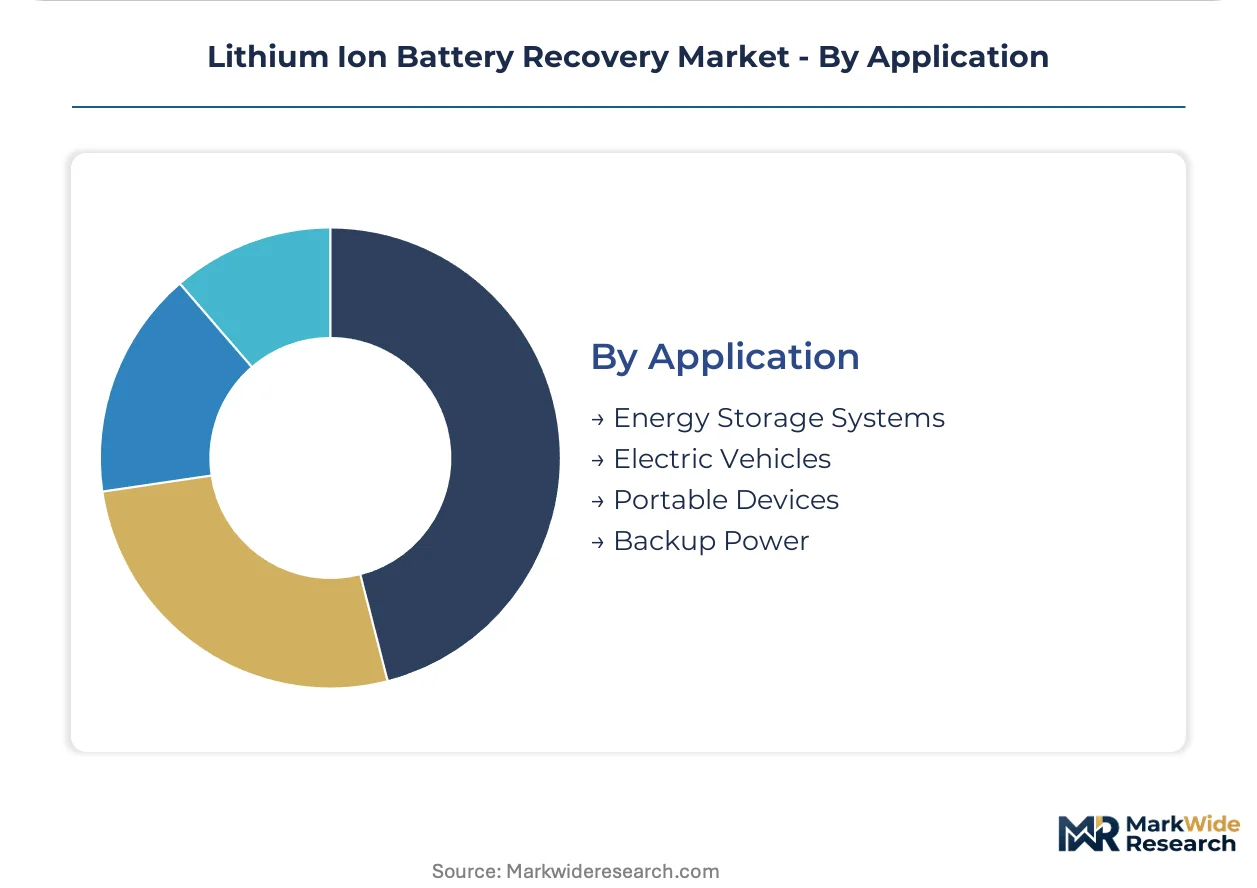
Application:
Battery architecture and cell format dictate dismantling complexity and metal recovery yields.
- Electric Vehicles:Large-format pouch and prismatic cells with aluminum housings enable efficient disassembly. NMC and LFP chemistries dominate, with diverging cobalt and lithium concentrations affecting refinery process design.
- Energy Storage Systems:Stationary installations prioritize LFP chemistry for cycle life, reducing cobalt recovery value but simplifying lithium extraction. Containerized designs from CATL and BYD standardize module formats.
- Portable Devices:Cylindrical 18650 and 21700 cells in laptops and power tools require specialized shredding to manage electrolyte venting risks. Collection density challenges persist outside urban cores.
- Backup Power:Lead-acid replacement cycles in data centers and telecom are accelerating lithium adoption. Vertiv and Eaton specify recycling clauses in procurement contracts.
Electric vehicles leads on scale; energy storage systems leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrometallurgical engineers cluster around established mining and chemical processing corridors in Germany, China, and the United States, anchoring regional capacity buildouts.
United States
Domestic automakers under IRA domestic content credits are pre-negotiating decade-long offtake agreements with integrated refiners. EPA RCRA hazardous waste permitting timelines stretch 18-36 months, constraining facility ramp speed. Nevada and South Carolina host emerging recycling parks tied to battery gigafactory clusters.
Germany
Volkswagen and Mercedes-Benz equity stakes in Primobius lock in captive feedstock streams under extended producer responsibility laws. The EU Battery Regulation's recycled content mandates compress compliance timelines for cathode manufacturers. North Rhine-Westphalia and Saxony-Anhalt concentrate hydrometallurgical refining investments near chemical industry infrastructure.
China
CATL-affiliated recyclers dominate domestic feedstock allocation through direct manufacturing ecosystem ties. MIIT capacity licenses constrain unqualified entrants and consolidate qualified processing permits. Guangdong and Fujian provinces anchor the black mass-to-cathode supply chain with integrated refining parks.
Japan
Automotive OEMs coordinate collection networks through METI-guided industry consortia for homogeneous high-metal-content feedstock. JIS standards govern recycled material quality thresholds for domestic cathode re-entry. Kansai region chemical processors leverage existing specialty metals refining expertise for battery-grade salt production.
Canada
Pilot direct recycling programs with American Manganese test cathode regeneration without full elemental dissolution. Provincial extended producer responsibility frameworks assign end-of-life liability to vehicle importers. Ontario's mining corridor attracts hydrometallurgical talent from adjacent nickel and cobalt extraction operations.
Lithium Ion Battery Recovery Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light black mass traders for margin capture across the value chain. The vendor base splits between cathode-maker-affiliated processors securing captive feedstock and independent tolling operators serving spot markets. Three archetypes dominate: automaker-integrated recyclers with closed-loop collection networks, mining-house-backed refiners leveraging existing metal trading desks, and pure-play hydrometallurgical specialists scaling modular capacity. Competitive positioning hardens through M&A consolidation of regional collection networks and strategic partnerships locking in decade-long offtake at fixed conversion fees.
Within the automaker-integrated tier, Redwood Materials and Li-Cycle Holdings Corp exemplify the closed-loop partnership model with domestic OEMs. Among mining-house-backed operators, Glencore occupies a position leveraging existing metal trading infrastructure for black mass procurement. Umicore anchors the European specialist tier through integrated hydrometallurgical refining serving cathode supply chains under EU Battery Regulation compliance mandates.
| Leading Market Players |
|---|
| Umicore |
| Glencore |
| Cirba Solutions |
| Li-Cycle Holdings Corp |
| Redwood Materials |
| GEM Co., Ltd. |
| Brunp Recycling |
| Accurec Recycling GmbH |
| American Battery Technology Company |
| Others |
Pricing and Supply Chain Analysis
Natural gas and electricity costs cascade through pyrometallurgical smelting operations into premium spreads for hydrometallurgical battery-grade salts, compressing margins for energy-intensive European refiners while rewarding German and Chinese operators with integrated chemical processing parks.
Pricing Analysis
Black mass tolling splits between bundled collection-to-refining contracts and unbundled spot material sales. Contract-based long-term offtake dominates automotive partnerships, with Volkswagen and Mercedes-Benz locking in decade-fixed conversion fees. Price differentiation hinges on EU Battery Regulation compliance certification and cathode-grade purity thresholds above 99.5%. Cost compression in pyrometallurgical tiers is intensifying because European energy price spikes. Consumer electronics recyclers show highest price sensitivity; integrated OEM partnerships show lowest.
Supply Chain Analysis
Feedstock supply rests on German extended producer responsibility networks, Chinese MIIT-licensed capacity zones, and California SGIP-tied collection infrastructure. Critical inputs include spent NMC automotive packs, LFP stationary storage systems, and mixed consumer electronics cells. Single-source vulnerability concentrates in CATL-affiliated recycler feedstock allocation. Distribution runs through OEM-captive closed-loop channels rather than spot black mass markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lithium Ion Battery Recovery Market functions as a geographic-arbitrage play where EU Battery Regulation compliance timelines compress faster than EPA RCRA permitting cycles, rewarding early European capacity positioning over North American facility development.
For Market Incumbents: Acquire regional collection network assets to defend feedstock access against emerging hydrometallurgical specialists. Lock in backward integration into cathode precursor manufacturing before EU recycled content mandates tighten. Priority lever: secure qualified chemical engineering talent pools concentrated in German and Chinese mining corridors. For New Entrants and Emerging Players: Begin with India's nascent EV fleet waste streams, where battery volumes sit below commercial threshold but first-mover collection infrastructure yields captive positioning. Target renewable energy sector LFP replacement cycles as most penetrable segment. Go-to-market angle: direct cathode regeneration partnerships with American and Canadian pilot programs. For Investors and Strategic Acquirers: Consolidation pressure builds where EPA RCRA permitting timelines stretch 18-36 months and qualified hydrometallurgical engineers cluster in established chemical processing regions. Long-term viability favors integrated refiners with OEM offtake lock-in over black mass traders. Acquisition target archetype: modular hydrometallurgical specialists with solvent extraction optimization capabilities. Signal to watch: EU Battery Regulation digital passport implementation accelerating compliant-non-compliant feedstock tier segmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Redwood Materials scales Nevada refining parks adjacent to Tesla and Panasonic gigafactories. |
| Backward Integration | Umicore anchors European cathode supply chains through integrated hydrometallurgical refining under REACH compliance. |
| Long-term Supply Agreement | Mercedes-Benz equity stake in Primobius locks in decade-captive feedstock streams under German producer responsibility laws. |
| Joint Venture | |
| Technology Licensing | Brunp Recycling leverages CATL manufacturing ecosystem ties to dominate Chinese MIIT-licensed capacity allocation. |
Research Methodology
Coverage spans Germany, China, the United States, and Japan, with primary inputs from each market cluster combining interviews with hydrometallurgical process engineers, OEM sustainability procurement leads, EPA hazardous waste permitting officers, and cathode manufacturer quality directors. Secondary validation draws from MIIT capacity license disclosures, EU Battery Regulation implementation texts, EPA RCRA facility permit databases, and SEC 10-K filings from listed recyclers. Bottom-up feedstock volume estimates triangulate against top-down cathode demand projections.
Granularity-level modeling disaggregates recovery economics by process technology, battery chemistry, and regulatory compliance tier across the analysis window. Segmentation dimensions include hydrometallurgical versus pyrometallurgical routes, NMC versus LFP versus NCA formulations, and automotive versus stationary storage versus consumer electronics end-use. CAGRs derive from installed base retirement curves and replacement cycle assumptions. Industry-specific inputs incorporate EU recycled content mandate phase-in schedules and IRA domestic content credit qualification thresholds.
Several conditions sit outside the modeled scope, including breakthrough biotechnological leaching scale-up, pyrometallurgical energy cost normalization, and direct recycling technology commercialization timelines. Forecasts reflect assumptions about regulatory enforcement consistency and cathode chemistry mix stability. Material deviation in EU Battery Regulation implementation pace or EPA permitting acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market