
 Indoor Air Purification Market | 2026-2036
Indoor Air Purification Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Air Purification Market Analysis
Activated carbon composite media is realigning cost structures across mid-tier product lines as manufacturers reduce reliance on virgin coconut shell supplies. Daikin Industries leverages captive refrigerant-to-filtration R&D pipelines to sustain technology leadership in Asia-Pacific commercial installations. Honeywell International Inc. anchors North American distribution through building-automation channel integration. Dyson competes on design-intensive residential positioning with proprietary air-multiplier architectures.
Indoor air purification encompasses mechanical, electrostatic, and photocatalytic systems engineered to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed environments, with HEPA filtration rated at 99.97% efficiency at 0.3 microns serving as the clinical benchmark. These platforms serve critical functions in healthcare infection control, commercial building wellness certification, and residential allergen management. HEPA filters occupy the dominant revenue position due to regulatory mandates in healthcare and aviation applications, while UV-C purifiers represent the fastest-expanding technology segment as germicidal wavelength integration becomes standard in premium residential and commercial units. The residential end-user category commands the largest volume base, though the healthcare segment captures disproportionate margin pools through validated cleanroom-grade specifications.
The U.S. EPA sets baseline efficiency reporting requirements under Energy Star verification protocols, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-linked ventilation system configurations. China's GB standards and SAMR certification requirements create distinct product qualification pathways for imported equipment. Stakeholders must monitor evolving alignment between ASHRAE ventilation guidelines and national building codes to anticipate specification shifts in commercial procurement cycles.
Market Dynamics
The Indoor Air Purification Market is undergoing a fundamental recalibration as multi-stage filtration architectures displace single-technology units. Healthcare procurement mandates and residential wellness certification programs are compressing replacement cycles and elevating performance thresholds beyond legacy HEPA-only specifications.
Growth Catalysts
- Healthcare Infection Control Mandates:Medical-grade HEPA specifications are becoming mandatory in hospital HVAC retrofits across Germany, Japan, and the United States. Procurement volumes in tertiary care facilities are accelerating specification upgrades.
- EPA Indoor airPLUS Integration:The U.S. EPA program is embedding air quality verification into residential construction standards. Builders are pre-installing whole-home purification systems to secure certification premiums.
- Photocatalytic Oxidation Maturation:Titanium dioxide-based UV-C systems are achieving commercial viability for VOC degradation. Premium residential buyers in urban China are adopting these platforms for formaldehyde remediation.
Market Restraints
- Virgin Coconut Shell Supply Concentration:Activated carbon feedstock depends on Southeast Asian agricultural output. Weather volatility and export restrictions in Indonesia are creating input cost instability for composite media manufacturers.
- EU F-Gas Regulation Constraints:Refrigerant-linked ventilation configurations face phase-down schedules. System designers must decouple filtration performance from cooling circuits, adding engineering complexity.
- Filter Replacement Friction:Consumer adherence to maintenance schedules remains below 40% in residential segments. Sustained performance claims degrade when users defer cartridge exchanges.
Strategic Opportunities
- Indian Urban Household Penetration:Current adoption rates in Delhi, Mumbai, and Bangalore remain under 15% for premium systems. Rising AQI awareness and NCMRWF health advisories are creating first-time buyer expansion.
- Building Automation Integration:BACnet and Modbus protocol compatibility is enabling centralized air quality management. Commercial property managers in Singapore and Dubai are specifying networked purification as standard.
- ASHRAE 241 Compliance Services:The guideline for reducing airborne infectious aerosol exposure is creating consultative revenue streams. Engineering firms are bundling purification specification with ventilation audits.
Industry Challenges
- Cleanroom-Grade Certification Timelines:ISO 14644 validation for healthcare specifications requires 12-18 month testing protocols. Product launch cycles compress competitive windows before standards evolve.
- Electrostatic Precipitator Ozone Emission Control:Balancing ionization intensity with OSHA indoor ozone limits demands precision calibration. Field performance drift creates liability exposure in commercial deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Air Purification Market |
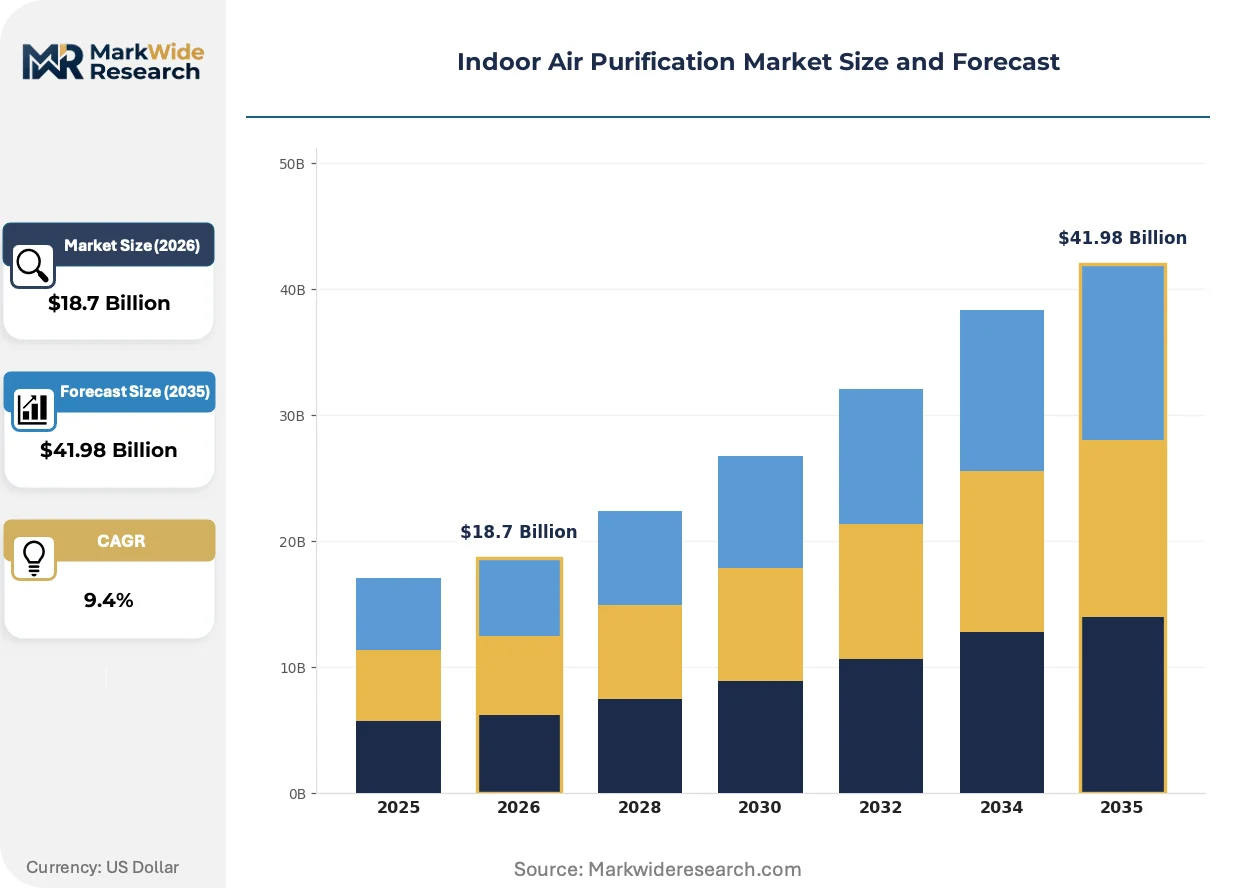
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, UV-C Purifiers, Ionizers End User: Residential, Commercial, Industrial, Healthcare Technology: Electrostatic, Photocatalytic, Ultrasonic, Negative Ion Application: Dust Removal, Allergens Control, Odor Elimination, Smoke Removal |
| Companies Covered | Honeywell International Inc., LG Electronics, Dyson, Daikin Industries, Ltd., Sharp Corporation, Philips, Panasonic Corporation, Blueair, IQAir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Air Purification Market Emerging Trajectories
Active filtration technologies are merging with environmental sensing and predictive maintenance platforms. This convergence is redrawing competitive boundaries between HVAC incumbents, consumer appliance specialists, and building automation providers.
Photocatalytic oxidation is converging with machine learning-driven air quality monitoring. Hospital facilities in South Korea and the Netherlands are deploying these integrated platforms to automate ventilation responses to real-time contaminant detection. The technology is compressing the gap between residential and medical-grade performance claims.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane filter manufacturers to reformulate hydrophobic coatings. European suppliers are accelerating fluorine-free alternatives to maintain CE marking eligibility. Nonwoven media producers in Germany and Switzerland are absorbing R&D costs to preserve market access.
Facility managers are unbundling purification performance from equipment ownership through managed air quality contracts. Commercial real estate operators in London and New York are adopting subscription models where vendors guarantee particulate and VOC thresholds. The shift transfers capital burden to suppliers while locking in recurring revenue streams.
Indoor Air Purification Market Segmentation
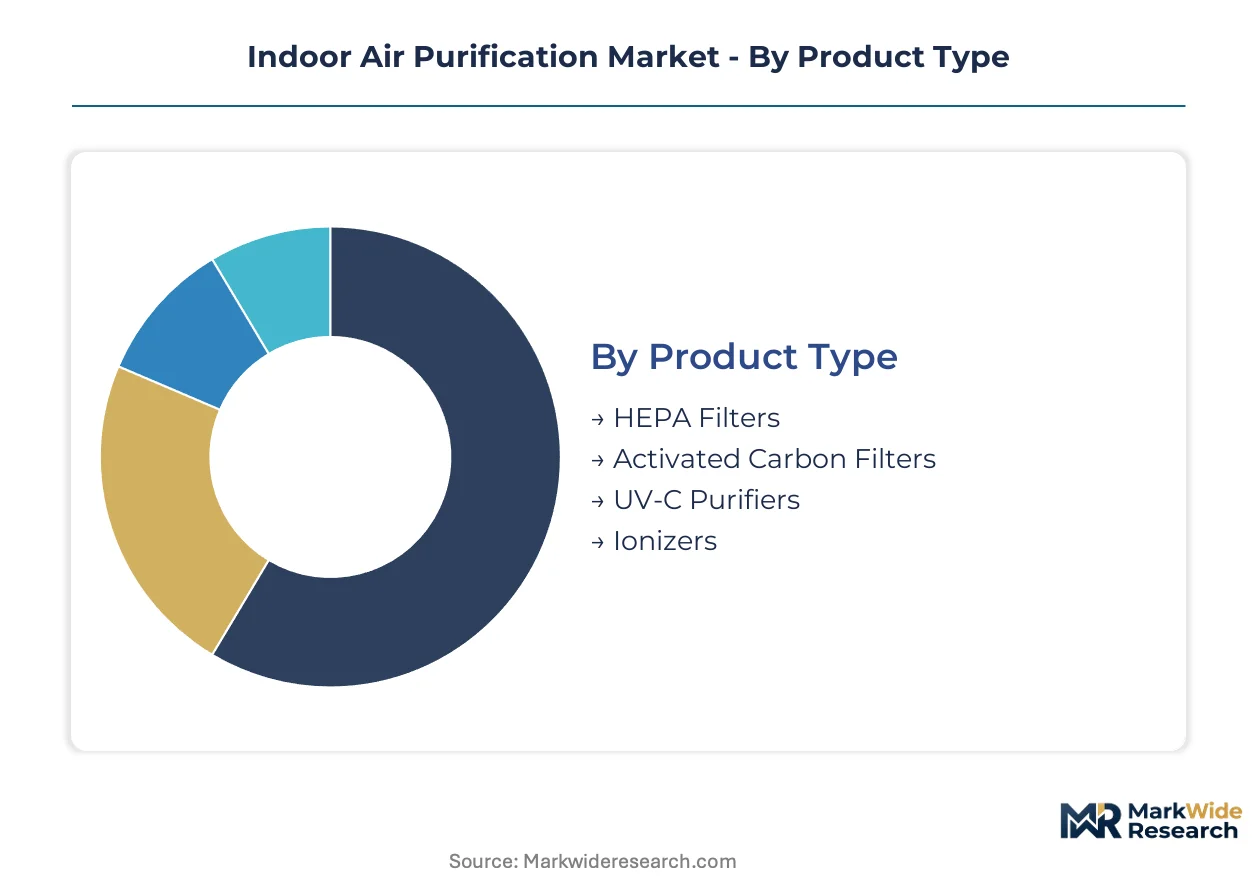
Segmentation in the Indoor Air Purification Market reveals how supply concentration and technology maturity create divergent margin pools across product architectures. Understanding these divisions exposes where procurement budgets are consolidating and where specification thresholds are tightening fastest.
Product Type:
Supply concentration in filter media manufacturing has concentrated competitive advantage around captive raw material access and certified production infrastructure.
- HEPA Filters:Fiberglass or polypropylene microfiber matrices rated at 99.97% efficiency at 0.3 microns constitute the clinical benchmark. Procurement in Germany, Japan, and the United States now mandates medical-grade specifications for hospital HVAC retrofits, compressing replacement cycles.
- Activated Carbon Filters:Coconut shell, coal, or wood-based porous structures adsorb VOCs and gaseous contaminants. Virgin coconut shell supply dependence on Indonesian agricultural output creates input cost instability for composite media manufacturers facing weather volatility and export restrictions.
- UV-C Purifiers:Mercury-vapor or LED-based 253.7nm germicidal irradiation systems are gaining share fastest in premium residential and commercial units.
- Ionizers:Corona discharge electrodes generating charged particles for particulate precipitation face OSHA ozone emission compliance scrutiny in commercial deployments.
Today's leader: HEPA Filters. Tomorrow's challenger: UV-C Purifiers.
End User:
Customer type determines whether procurement prioritizes validated cleanroom specifications or cost-optimized residential convenience.
- Healthcare:ISO 14644-validated cleanroom-grade systems serve infection control mandates in tertiary care facilities. The 12-18 month certification timelines compress competitive windows before standards evolve, locking in premium margin pools through validated specifications.
- Residential:Portable and whole-home units dominate volume, though consumer adherence to maintenance schedules remains below 40% and degrades sustained performance claims.
- Commercial:BACnet and Modbus protocol compatibility enables centralized air quality management in Singapore and Dubai property portfolios.
- Industrial:Heavy-duty electrostatic precipitators and multi-stage systems address process emissions and occupational exposure limits in manufacturing environments.
Volume concentrates in Residential. Margin concentrates in Healthcare.
Technology:
Technology maturity curves separate proven mechanical filtration from emerging photocatalytic platforms still navigating commercialization thresholds.
- Photocatalytic:Titanium dioxide-coated substrates activated by UV-A irradiation achieve VOC degradation through oxidation reactions. Urban households in China are adopting these platforms for formaldehyde remediation, compressing the gap between residential and medical-grade performance claims.
- Electrostatic:Charged collection plates or ionization zones remove sub-micron particles without pressure drop penalties. Balancing ionization intensity with OSHA indoor ozone limits demands precision calibration.
- Ultrasonic:High-frequency mechanical vibration generates water droplets for humidification-integrated purification in dry climate residential applications.
- Negative Ion:Electron emission devices cluster airborne particles for gravitational settling, competing on silent operation in bedroom installations.
Proven incumbent: Electrostatic. Steepest expansion trajectory: Photocatalytic.
Application:
Application focus determines whether product positioning emphasizes allergen mitigation for wellness consumers or contaminant removal for regulatory compliance.
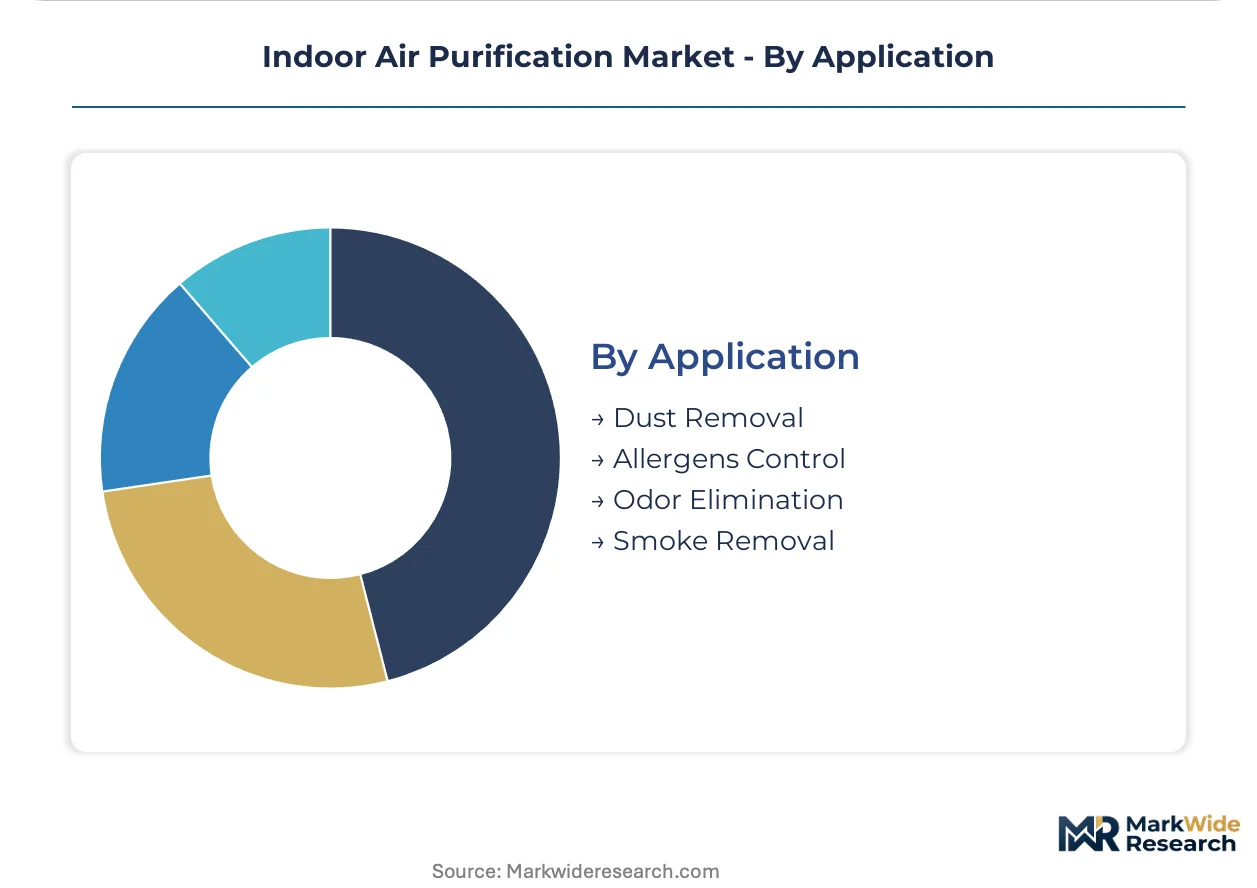
- Allergens Control:Pollen, pet dander, and dust mite antigen reduction targets respiratory-sensitive residential demographics. The U.S. EPA Indoor airPLUS program embeds verification into construction standards, with builders pre-installing whole-home systems to secure certification premiums.
- Dust Removal:Particulate matter filtration addresses PM2.5 and PM10 exposure in urban environments with elevated ambient air quality index readings.
- Odor Elimination:Activated carbon and photocatalytic systems target volatile organic compound sources including cooking, tobacco, and pet emissions.
- Smoke Removal:High-CADR (Clean Air Delivery Rate) configurations address wildfire season demand spikes and commercial kitchen exhaust requirements.
Wellness positioning anchors on Allergens Control. Regulatory pressure elevates Dust Removal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors global purification equipment manufacturing, with Shenzhen and Dongguan housing the densest concentration of HEPA filter fabrication and UV-C module assembly operations. National GB standards and SAMR certification requirements create distinct qualification pathways for imported equipment entering this market.
United States
Hospital HVAC retrofit mandates in Texas, Florida, and California are accelerating medical-grade HEPA procurement cycles. The EPA Indoor airPLUS program embeds air quality verification into residential construction standards, with builders in Phoenix and Austin pre-installing whole-home systems to secure certification premiums. Commercial property managers in Manhattan and Chicago specify BACnet-compatible networked purification.
Germany
Tertiary care facilities in Bavaria and North Rhine-Westphalia now mandate ISO 14644-validated cleanroom-grade specifications. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-linked ventilation configurations, forcing system designers in Stuttgart and Munich to decouple filtration performance from cooling circuits. Engineering firms in Frankfurt bundle ASHRAE 241 compliance services with ventilation audits.
Japan
Tokyo and Osaka healthcare clusters are deploying titanium dioxide-based UV-C systems for VOC degradation in premium residential and commercial units. METI efficiency guidelines and JIS standards govern product qualification. Daikin Industries leverages captive R&D pipelines from refrigerant technology to sustain leadership in commercial installations across Kanto and Kansai regions.
India
Adoption rates in Delhi, Mumbai, and Bangalore remain under 15% for premium systems, creating first-time buyer expansion as NCMRWF health advisories elevate AQI awareness. BIS certification requirements and DGFT import regulations shape equipment qualification. Residential demand concentrates in Gurugram and Hyderabad as urban households upgrade from basic filtration to multi-stage platforms.
Indoor Air Purification Market Vendor Landscape
Strategic partnerships dominate the current landscape as HVAC incumbents, consumer appliance specialists, and building automation providers redraw competitive boundaries. The vendor base fragments across three tiers: diversified conglomerates with captive distribution networks, mid-scale specialists with certified production infrastructure, and design-intensive challengers competing on residential aesthetics. Two moves define current positioning: backward integration into filter media manufacturing to reduce feedstock volatility exposure, and building-automation channel integration to capture commercial specification lock-in.
Within the diversified conglomerate tier, Honeywell International Inc. and Daikin Industries, Ltd. anchor North American and Asia-Pacific commercial installations respectively. Dyson occupies a position on the design-intensive residential vector, exemplifying proprietary architecture competition. LG Electronics and Panasonic Corporation represent the consumer electronics crossover archetype, leveraging scale manufacturing and retail channel density.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| LG Electronics |
| Dyson |
| Daikin Industries, Ltd. |
| Sharp Corporation |
| Philips |
| Panasonic Corporation |
| Blueair |
| IQAir |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in filter media manufacturing have consolidated Indonesian coconut shell processing assets, tightening feedstock control and compressing margin pools for downstream OEMs competing on activated carbon composite formulations. This ownership concentration transmits directly into pricing discipline across mid-tier product lines where virgin shell supply volatility now determines contract renegotiation frequency.
Pricing Analysis
Input-cost pass-through from Southeast Asian agricultural feedstock runs through three distinct pricing tiers separating medical-grade HEPA specifications from residential convenience models. Price differentiation hinges on ISO 14644 certification level and after-sales service bundling, with healthcare procurement showing lowest sensitivity due to mandated replacement cycles. Cost compression in standard residential units is intensifying because Indonesian export restrictions on coconut shell charcoal have elevated activated carbon input expenses by double-digit increments over recent contract periods.
Supply Chain Analysis
Certification gating through China's SAMR and India's BIS authorities concentrates finished goods assembly in Shenzhen, Dongguan, and Yangtze River Delta manufacturing clusters. Raw material supply draws from Indonesian coconut plantations, German nonwoven membrane producers, and Japanese UV-C LED fabricators. Single-source vulnerability in virgin coconut shell charcoal creates exposure to monsoon-driven harvest shortfalls. Distribution runs through building-automation channel partners in North American commercial markets and appliance retail networks in Asian residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Indoor Air Purification Market functions as a stable compounder anchored by regulatory mandates for healthcare infection control that institutionalize replacement demand regardless of economic cyclicality.
For Market Incumbents: Deepen backward integration into HEPA microfiber manufacturing to offset polypropylene feedstock volatility from petrochemical suppliers. Lock in multi-year activated carbon offtake agreements with Indonesian processors before monsoon season disrupts harvest yields. Channel control through BACnet-certified building automation partnerships represents the critical defensive lever against HVAC conglomerates expanding filtration portfolios. For New Entrants and Emerging Players: First-time buyers in Indian urban households present the most penetrable white-space opportunity given sub-15% premium system adoption in Delhi, Mumbai, and Bangalore. NCMRWF health advisory integration offers a direct go-to-market angle through air quality app partnerships that trigger purification recommendations at specific AQI thresholds. Photocatalytic oxidation platforms for formaldehyde remediation in Chinese residential markets provide secondary entry velocity. For Investors and Strategic Acquirers: HVAC conglomerates seeking building-automation integration are the most active acquirer in this space, prioritizing targets with certified cleanroom-grade production infrastructure. The long-term viability window favors specialists with captive filter media manufacturing and validated ISO 14644 testing protocols. Watch ASHRAE guideline alignment with national building codes as the signal indicating accelerated commercial procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media Manufacturing | Captive HEPA microfiber production insulates margins from petrochemical feedstock volatility. |
| Building Automation Protocol Certification | BACnet compatibility secures specification lock-in with Manhattan and Chicago property managers. |
| ISO 14644 Cleanroom Validation Investment | 12-18 month certification timelines create defensive moats around healthcare procurement mandates. |
| Photocatalytic Oxidation Platform Launch | Titanium dioxide UV-C systems capture formaldehyde remediation demand in urban Chinese households. |
| Managed Air Quality Service Model | Subscription contracts transfer capital burden to vendors while locking London and New York real estate operators into recurring revenue. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HVAC procurement directors, hospital biomedical engineers, residential appliance retail buyers, and building automation integration specialists against secondary validation from EPA Indoor airPLUS documentation, EU Ecodesign Directive filings, SAMR certification registries, and ASHRAE guideline publications. Bottom-up unit economics and top-down sectoral demand curves were cross-referenced to anchor volume estimates.
Comparable historical periods across the projection horizon established baseline replacement cycle frequencies and technology transition velocities. The analytical framework segmented demand by product architecture, end-user compliance tier, and regional regulatory cluster, modeling CAGRs through technology adoption S-curves and healthcare capital expenditure patterns. Photocatalytic oxidation commercialization timelines and coconut shell feedstock availability curves served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; medical-grade HEPA specifications carry tighter precision than emerging residential wellness categories due to validated procurement data availability. Forecasts reflect documented assumptions regarding ASHRAE guideline adoption velocity and Indonesian agricultural export policy stability. Deviation in EU F-Gas Regulation enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Quality Control Systems Market