
 Emission Management Software Market | 2026-2036
Emission Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Management Software Market Analysis
The gap between energy producers and transportation companies as dominant buyers is collapsing as manufacturers now drive the fastest procurement cycles for emission management platforms. IBM Corporation leverages its Watson analytics backbone to anchor enterprise-grade carbon accounting suites across heavy industrial accounts. SAP SE sustains deep ERP integration that locks manufacturing clients into compliance-automated workflows. Schneider Electric SE differentiates through native IoT sensor connectivity that feeds real-time emissions data directly into regulatory dashboards.
Emission management software denotes digital platforms that aggregate, calculate, and report greenhouse gas and pollutant outputs across stationary and mobile sources, typically ingesting sensor streams, utility bills, and supply chain records to output audit-ready disclosures aligned with GHG Protocol or ISO 14064 methodologies. Cloud-based deployment now leads functionality adoption because energy producers demand elastic compute for seasonal emission spikes and distributed asset monitoring. Regulatory compliance applications command the deepest margin pools as penalties for inaccurate filings harden under EPA and EU enforcement, while carbon footprint tracking grows fastest among manufacturers scrambling to scope three supplier data.
EPA enforcement under the Clean Air Act and the EU Green Deal's carbon border adjustment mechanism are forcing importers and domestic emitters alike to install auditable software trails or face market exclusion. ISO 14064 and the GHG Protocol shape product standards by mandating granular activity-data hierarchies that vendors must embed as native calculation engines. Stakeholders must decide whether to build in-house compliance modules or absorb third-party platforms before supplier audit requirements cascade through tier-two manufacturing networks.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing importers and domestic emitters to install auditable software trails before supplier audit requirements cascade through tier-two manufacturing networks, compressing procurement cycles and elevating compliance automation to a competitive necessity.
Growth Catalysts
- EU Green Deal enforcement:The carbon border adjustment mechanism mandates granular emissions documentation for imports into the European Union, compelling manufacturers across steel, cement, and chemicals to deploy tracking platforms or face market exclusion.
- Scope three data mandates:Large industrial buyers now require suppliers to submit verified emissions data, creating procurement-driven demand that ripples through tier-two and tier-three manufacturing networks in Germany, China, and the United States.
- IoT sensor proliferation:Real-time emissions monitoring hardware costs have dropped substantially, enabling continuous data streams that feed directly into cloud-based calculation engines and eliminate manual meter-reading bottlenecks.
Market Restraints
- Data integration complexity:Legacy ERP systems in heavy manufacturing lack standardized APIs, forcing expensive middleware development to connect 1990s-era production databases with modern emissions platforms.
- Supplier concentration in sensor hardware:Industrial-grade gas and particulate sensors rely heavily on specialized German and Japanese component manufacturers, creating vulnerability to regional supply disruptions or export licensing delays.
- Validation protocol fragmentation:Divergent national requirements for third-party emissions verification—particularly between EPA methodologies and EU-accredited bodies—force vendors to maintain parallel certification tracks, inflating compliance costs.
Strategic Opportunities
- India's industrial digitization:The country's PLI scheme for manufacturing is accelerating factory automation investments, creating first-mover advantage for emissions platforms that integrate with BIS-mandated quality and environmental reporting systems.
- Blockchain-anchored verification:Immutable ledger technology is converging with emissions data streams to create tamper-proof audit trails that satisfy both EPA enforcement actions and EU Green Deal documentation requirements.
- Aviation and maritime fuel tracking:Emerging IMO and ICAO carbon accounting rules for international transport are opening specialized application modules that calculate bunker fuel and jet kerosene emissions across complex multi-leg routes.
Industry Challenges
- Carbon accounting talent scarcity:Proficiency in GHG Protocol methodologies and ISO 14064-1 calculation hierarchies remains concentrated among a small pool of consultants, constraining vendor implementation capacity and extending deployment timelines.
- Multi-site data harmonization:Manufacturers operating dozens of facilities across divergent regulatory jurisdictions struggle to consolidate emissions factors, grid emission coefficients, and activity data into unified corporate disclosures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Management Software Market |
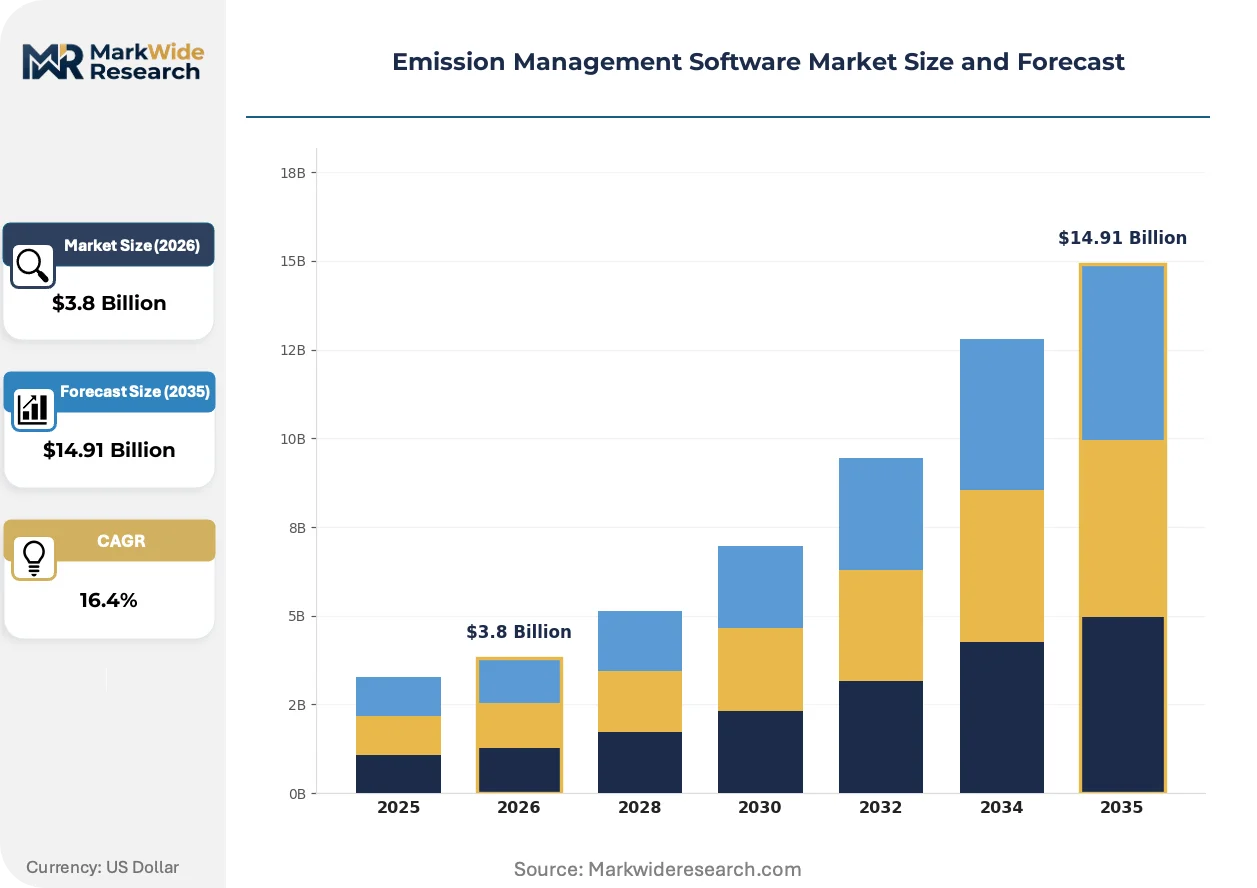
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Carbon Footprint Tracking, Regulatory Compliance, Emission Reporting, Risk Assessment End User: Manufacturers, Energy Producers, Transportation Companies, Construction Firms Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Functionality: Data Analytics, Real-Time Monitoring, Reporting Tools, Integration Capabilities |
| Companies Covered | IBM Corporation, SAP SE, Schneider Electric SE, Siemens AG, Accenture, Carbonetworks, Greenstone Carbon Management, Enviance, Sphera Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Management Software Market Emerging Trajectories
Artificial intelligence is actively reshaping how emissions data transforms into actionable intelligence, compressing the gap between raw sensor output and regulatory-grade disclosure while enabling predictive optimization of carbon-intensive processes.
Digital twin technology is decomposing traditional static emissions inventories into dynamic, physics-based simulations that model facility-level greenhouse gas outputs in real time. Energy producers and integrated steel manufacturers are deploying these systems fastest, drawn by the ability to test operational changes virtually before committing capital. The technology is decomposing the market for retrospective carbon accounting into forward-looking emissions optimization services.
The EU's Corporate Sustainability Reporting Directive now mandates audited sustainability disclosures for approximately 50,000 companies, extending liability to scope three supply chain data. Industrial software vendors are embedding CSRD-aligned calculation engines as native modules. Manufacturing clients in Germany and France face the steepest compliance ramps and are driving premium pricing for integrated reporting suites.
Buyer expectations are hardening around continuous monitoring rather than annual calculations, with procurement teams in automotive and electronics demanding quarterly or monthly emissions updates from critical suppliers. Subscription-based platform pricing is displacing perpetual license models as vendors align revenue with ongoing data validation services. This shift is most visible in the United States, where EPA enforcement under the Clean Air Act has intensified penalties for inaccurate filings.
Emission Management Software Market Segmentation
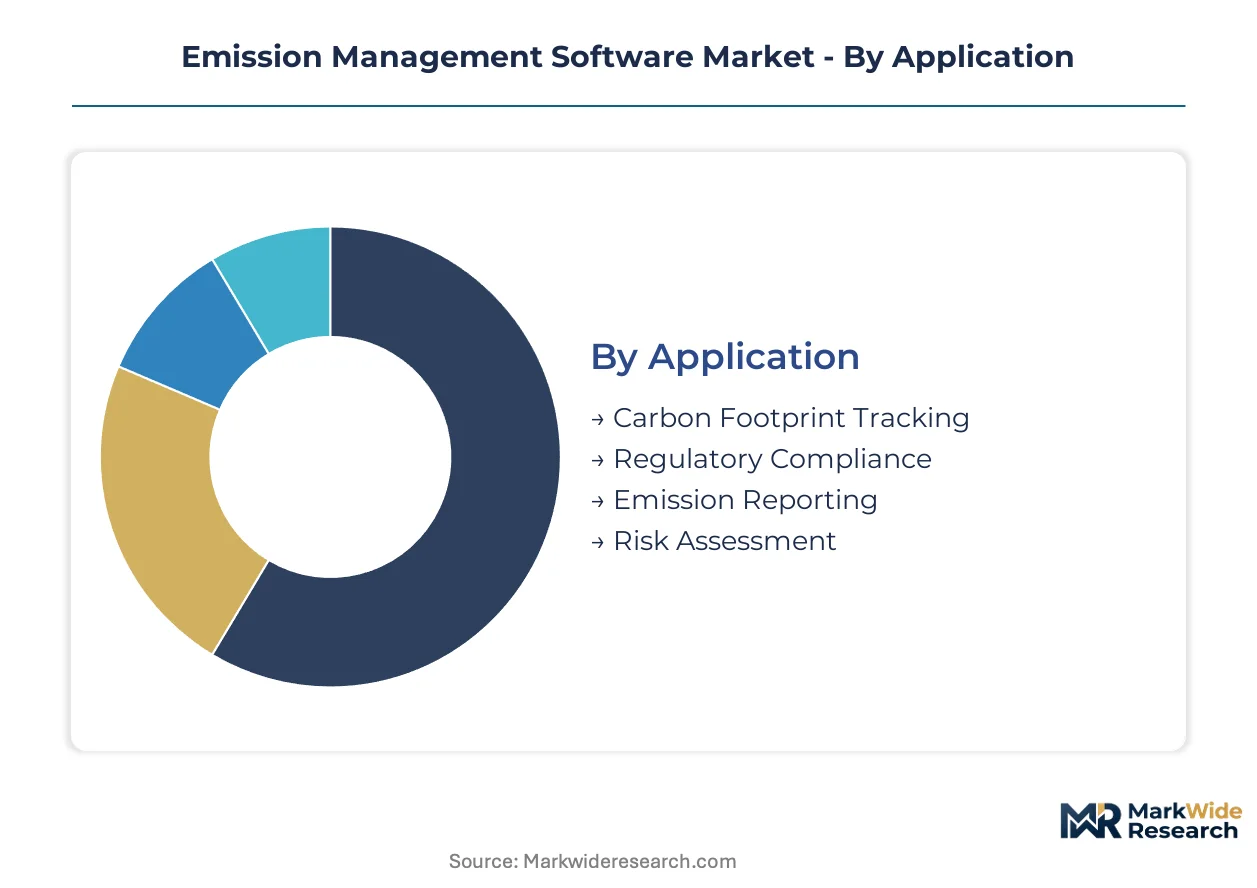
Segmentation in emission management software reveals how compliance automation, deployment economics, and user sophistication create divergent margin structures. Vendors must align product architecture with the specific data intensity and regulatory exposure of each buyer cohort.
Application:
Margin pools concentrate in regulatory compliance modules where penalty exposure justifies premium pricing, while carbon footprint tracking commands volume through manufacturer procurement mandates.
- Regulatory Compliance:Platforms embed EPA and EU Green Deal calculation engines that automate threshold monitoring and filing preparation. Energy producers in Germany and the United States absorb the steepest licensing costs as enforcement actions intensify.
- Carbon Footprint Tracking:Scope three data aggregation tools ingest supplier records and utility streams to output GHG Protocol-aligned inventories. Manufacturers across steel, cement, and chemicals drive procurement as customer audit requirements cascade through tier-two networks.
- Emission Reporting:Audit-ready disclosure generators consolidate facility-level outputs into stakeholder-facing documents.
- Risk Assessment:Scenario-modeling modules quantify carbon price exposure and physical climate risk to asset valuations.
The dominant share belongs to regulatory compliance, while carbon footprint tracking is closing the gap fastest.
End User:
Deployment complexity scales with operational footprint dispersion, creating tiered pricing power across buyer categories with divergent data harmonization challenges.
- Manufacturers:Multi-site industrial operators require scope three supplier integration and CSRD-aligned reporting engines. German and French automotive and electronics producers are compressing procurement cycles to quarterly data updates.
- Energy Producers:Utilities and oil and gas operators demand elastic compute for seasonal emission spikes and distributed asset monitoring across generation portfolios. Cloud-based deployment dominates this cohort.
- Transportation Companies:Fleet operators and logistics providers calculate mobile source emissions across complex route networks.
- Construction Firms:Project-based contractors track embodied carbon in materials and equipment fuel consumption.
Manufacturers command the deepest contract values, though energy producers are expanding their platform footprints most aggressively.
Deployment:
Cost structures diverge sharply between capital-intensive on-premise installations and recurring-revenue cloud subscriptions, with hybrid architectures capturing buyers in regulated industries with data sovereignty requirements.
- Cloud-Based:Elastic infrastructure enables seasonal compute scaling and distributed sensor ingestion without hardware procurement. Energy producers and mid-market manufacturers favor this model for rapid deployment and automatic regulatory engine updates.
- On-Premise:Localized data storage satisfies national security restrictions and legacy system integration requirements in defense and critical infrastructure sectors. Upfront license and server costs create lumpy revenue recognition.
- Hybrid:Sensitive emissions data remains on-site while analytics and reporting layers operate in cloud environments.
- Mobile:Field technician applications enable real-time emission source identification and corrective action logging.
Cloud-based deployment holds the largest installed base, yet hybrid configurations are gaining share fastest among regulated heavy industry.
Functionality:
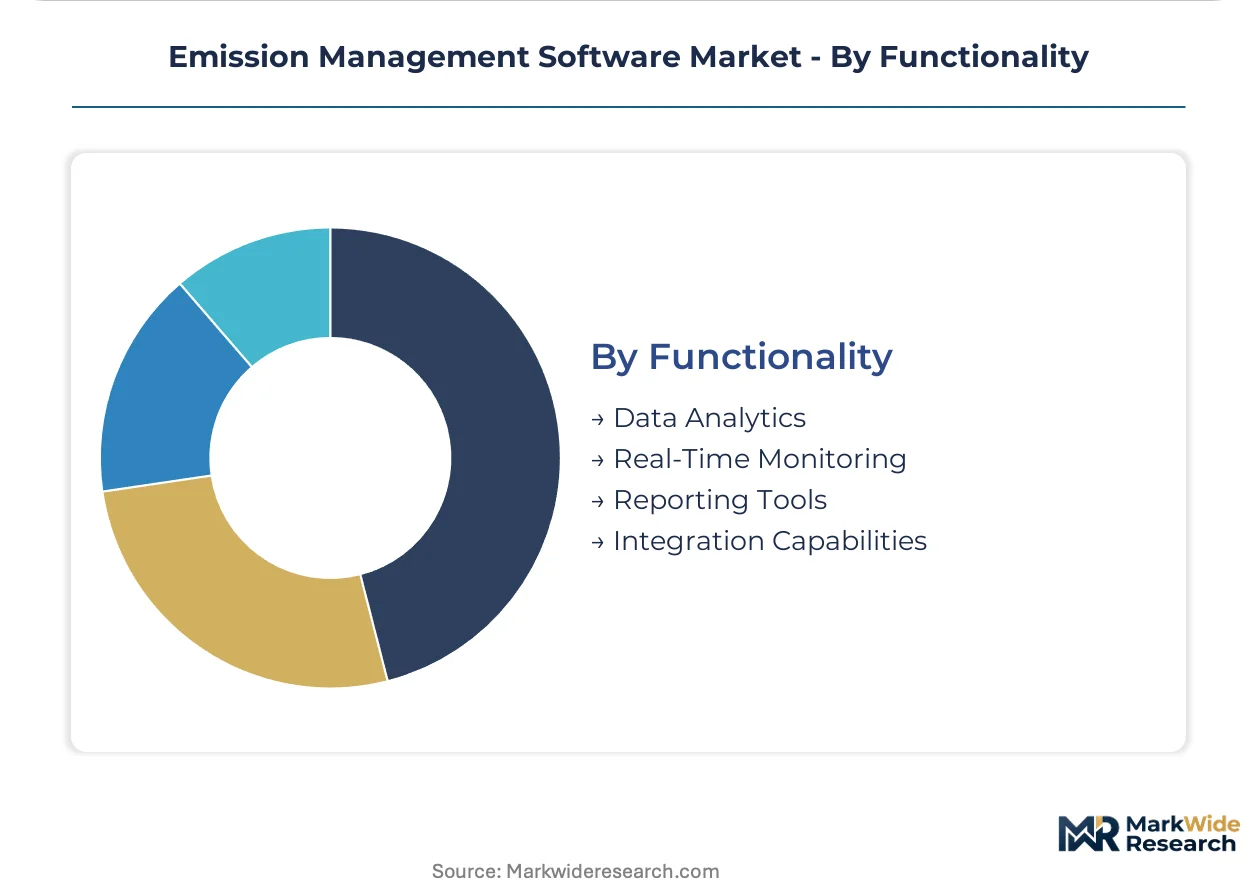
Core platform value migrates from retrospective reporting toward predictive optimization as artificial intelligence capabilities reshape buyer expectations and vendor pricing models.
- Real-Time Monitoring:Continuous sensor data ingestion and threshold alerting replace manual meter reading and quarterly calculations. IoT hardware cost declines are accelerating adoption across steel and cement facilities.
- Data Analytics:Machine learning models identify emission intensity patterns and recommend operational adjustments. Predictive capabilities command subscription premiums as buyers shift from compliance to optimization.
- Reporting Tools:Template-driven disclosure generators align outputs with GHG Protocol, ISO 14064, and CSRD requirements.
- Integration Capabilities:API and middleware layers connect emissions platforms to ERP, SCADA, and supplier data systems.
Real-time monitoring anchors the largest revenue pool, while data analytics is climbing the fastest as vendors layer optimization services atop compliance foundations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for emission management clusters in Germany, the United States, China, India, and Japan, where industrial digitization and regulatory enforcement create concentrated demand for compliance platforms.
United States
Energy producers and heavy manufacturers drive procurement of cloud-based emission tracking systems. EPA enforcement under the Clean Air Act intensifies penalty exposure for inaccurate filings, compressing deployment timelines. Industrial corridors in Texas and the Gulf Coast anchor adoption as refineries digitize compliance workflows.
Germany
Automotive and chemicals manufacturers demand scope three supplier integration and CSRD-aligned reporting engines. The EU Green Deal's carbon border adjustment mechanism forces exporters to install auditable software trails. The Rhine-Ruhr industrial belt leads implementation as steel and cement producers face tightening disclosure mandates.
China
State-owned energy conglomerates and steel manufacturers accelerate platform adoption under dual carbon goals and MEE enforcement protocols. Provincial governments in Jiangsu and Shandong mandate real-time emissions monitoring for heavy industry. The Yangtze River Delta concentrates software procurement as manufacturing clusters digitize environmental controls.
India
The PLI scheme for manufacturing accelerates factory automation investments, creating demand for emissions platforms integrated with BIS-mandated reporting systems. Cement and metals producers in Gujarat and Maharashtra deploy cloud solutions to satisfy customer audit requirements. Supplier compliance cascades through tier-two automotive networks in Tamil Nadu.
Japan
Integrated steel and chemicals manufacturers invest in predictive emissions optimization under METI decarbonization guidelines. Tokyo-based trading houses require verified scope three data from Southeast Asian suppliers. The Keihin industrial corridor leads adoption as facilities replace manual calculations with continuous monitoring systems.
Emission Management Software Market Vendor Landscape
Concentration sits with diversified industrial software conglomerates that leverage existing ERP relationships and IoT infrastructure to lock manufacturing clients into compliance-automated workflows. The vendor base stratifies across three tiers: enterprise technology platforms with analytics backbones, specialized environmental software houses with native regulatory engines, and emerging cloud-native challengers with API-first architectures. Dominant competitive moves include strategic partnerships with sensor hardware manufacturers and geographic expansion through localized regulatory certification.
Within the enterprise technology tier, IBM Corporation and SAP SE exemplify archetypes that anchor carbon accounting suites through deep system integration. Schneider Electric SE occupies a position bridging operational technology and software layers. Specialized environmental platforms like Sphera Solutions and Enviance represent the regulatory-native segment with purpose-built calculation engines. Cloud-native entrants including Carbonetworks and Greenstone Carbon Management sit within the agile-deployment tier targeting mid-market manufacturers with accelerated implementation timelines.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Schneider Electric SE |
| Siemens AG |
| Accenture |
| Carbonetworks |
| Greenstone Carbon Management |
| Enviance |
| Sphera Solutions |
| Others |
Supply Flow & Price Mechanics
Long-term SaaS subscription contracts with tiered capacity commitments lock in both cloud infrastructure access and predictable unit economics for emission management platforms, insulating vendors from spot-price volatility in compute resources while anchoring buyer switching costs.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across the emission management software landscape, with CSRD-aligned compliance modules commanding premium positioning against basic carbon footprint tracking. Pricing stratifies across enterprise-grade regulatory automation, mid-market cloud subscriptions, and entry-level supplier data portals. Cost compression in the mid-tier is intensifying because cloud-native entrants are undercutting legacy ERP-integrated suites. Energy producers exhibit the least price sensitivity due to penalty exposure under EPA enforcement, while tier-three manufacturers in automotive supply chains demonstrate acute budget constraints.
Supply Chain Analysis
Germany and Japan anchor industrial-grade gas sensor fabrication, with Taiwan and South Korea supplying specialized semiconductor components for IoT monitoring hardware. Emission management software draws from German precision engineering for particulate measurement devices, Japanese optical sensing technology, and Chinese cloud infrastructure provisioning. Single-source vulnerability concentrates in specialized electrochemical sensor membranes subject to export licensing delays. Distribution runs through direct enterprise sales teams for large energy producers and channel partners for mid-market manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
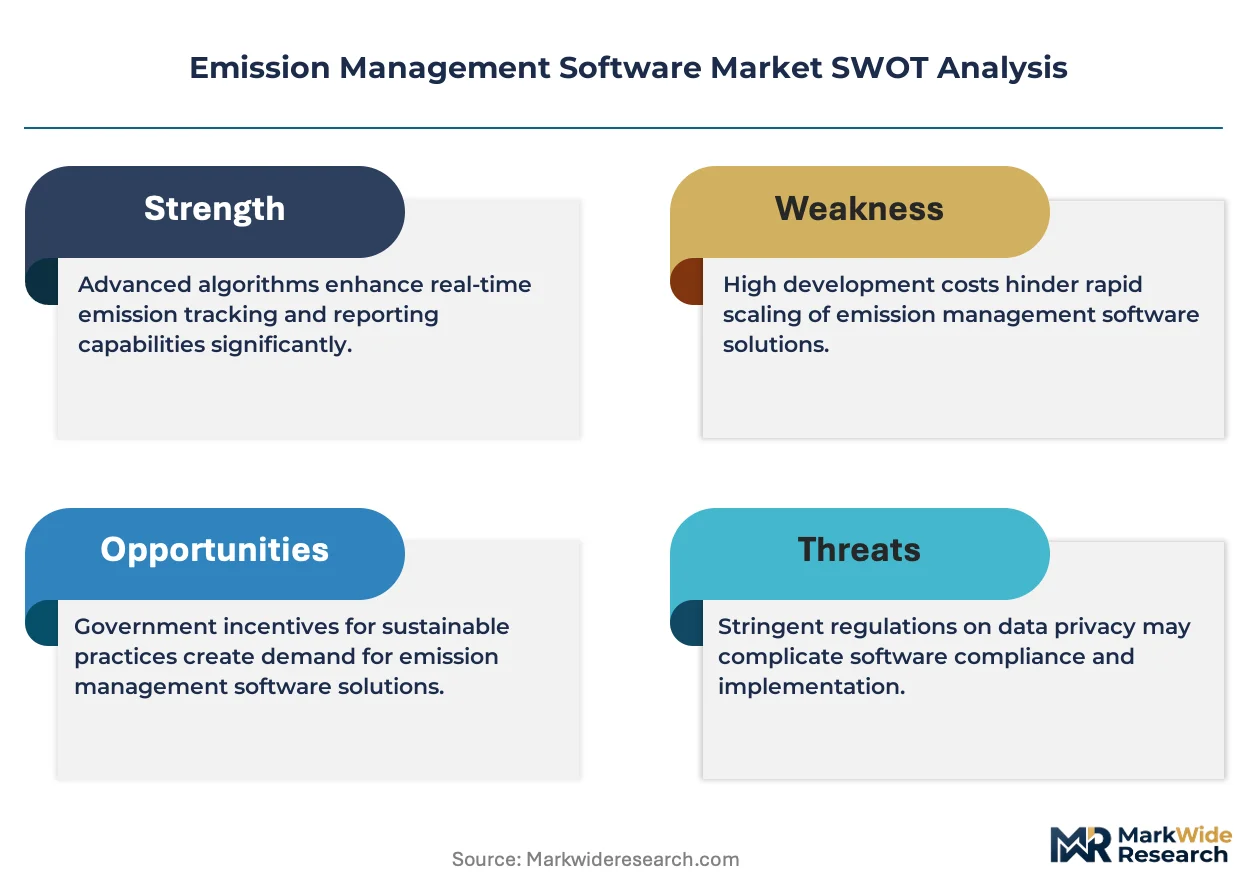
The emission management software market functions as a defensive-moat arena where regulatory entrenchment creates formidable switching costs—once buyers embed EPA and EU calculation engines into audit workflows, displacement becomes prohibitively expensive.
For Market Incumbents: Fortify platform stickiness by deepening native IoT sensor integration and embedding CSRD-aligned reporting as default modules rather than add-ons. Cloud-native challengers with API-first architectures threaten mid-market share through accelerated deployment timelines. Incumbents should prioritize backward integration into sensor hardware partnerships to control data pipeline quality and accelerate real-time monitoring adoption.
For New Entrants and Emerging Players: Lead with blockchain-anchored verification modules targeting tier-two automotive suppliers in India and Southeast Asia, where customer audit requirements are cascading fastest but incumbent penetration remains shallow. India's PLI-accelerated manufacturing digitization presents the most penetrable geography. A channel partnership strategy with industrial automation distributors outperforms direct sales for reaching fragmented metal and cement producers.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized environmental software houses with native regulatory engines and established EU accreditation pathways, as these assets command scarcity premiums in a consolidating vendor landscape. Long-term viability hinges on the ability to serve both compliance automation and predictive optimization use cases. The signal to watch as inflection indicator is acceleration in scope three data mandates from large industrial buyers cascading to tier-three networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectivity locks manufacturing clients into SAP or Oracle workflows, elevating switching costs. |
| Strategic Partnership | Sensor hardware alliances with German and Japanese component manufacturers secure data pipeline quality. |
| Acquisition of Specialist Firm | Regulatory-native calculation engines from environmental software houses fill CSRD compliance gaps. |
| Geographic Expansion | Localized certification for India's BIS-mandated reporting systems captures PLI-driven factory automation. |
| Product Launch | Aviation and maritime fuel tracking modules address emerging IMO and ICAO carbon accounting rules. |
Methodological Framework
Initial hypotheses were tested against primary input from sustainability officers, environmental compliance managers, IT procurement leads, and industrial automation engineers, and refined through secondary validation against EPA enforcement records, EU ETS transaction databases, SEC climate disclosure filings, and GHG Protocol implementation guidelines. Bottom-up estimates of platform deployments across energy, manufacturing, and transportation verticals were triangulated with top-down assessments of regulatory compliance spending.
Variance in projected adoption curves was decomposed across deployment model, organization size, vertical industry, integration complexity, and regional regulatory enforcement intensity. CAGRs were derived from segment-level growth rate distributions weighted by addressable buyer counts and average contract values. Forecast inputs incorporated sensor hardware cost decline trajectories and the cascade velocity of scope three supplier mandates through tiered manufacturing networks.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity, EU carbon border adjustment implementation, or continued IoT hardware cost declines would require recalibration. Forecasts reflect documented assumptions about regulatory timeline adherence and buyer procurement cycle compression. Recalibration cycles align with material shifts in enforcement actions, accreditation protocol changes, or breakthroughs in automated emissions verification technology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Ozone Generation Market