
 Air Quality Control Systems Market | 2026-2036
Air Quality Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Quality Control Systems Market Intelligence
The declining share of coal-fired power generation in many developed economies is repositioning the market's end-use focus toward industrial processing and advanced manufacturing. Legacy providers like Babcock & Wilcox adapt their large-scale utility solutions for new industrial applications. Siemens Energy leverages its broad energy infrastructure portfolio to serve both conventional and emerging sectors. Meanwhile, Donaldson Company specializes in filtration media for diverse industrial applications, from chemical processing to food manufacturing.
Air quality control systems are engineered solutions designed to capture and neutralize airborne pollutants from industrial exhaust streams. These systems remove particulate matter, sulfur oxides (SOx), and nitrogen oxides (NOx) before they are released into the atmosphere. While electrostatic precipitators and scrubbers remain dominant in heavy industries like power generation, fabric filters are gaining share. The chemical processing application demands highly customized systems for specific volatile organic compound abatement, driving innovation in gas absorption technologies.
Regulations from the US Environmental Protection Agency (EPA) set stringent limits on criteria pollutants for industrial facilities. Similarly, the EU's Industrial Emissions Directive and standards from China's Ministry of Ecology and Environment (MEE) mandate the use of best available control technologies. System selection increasingly hinges on balancing upfront capital costs with long-term operational efficiency and future regulatory compliance risk.
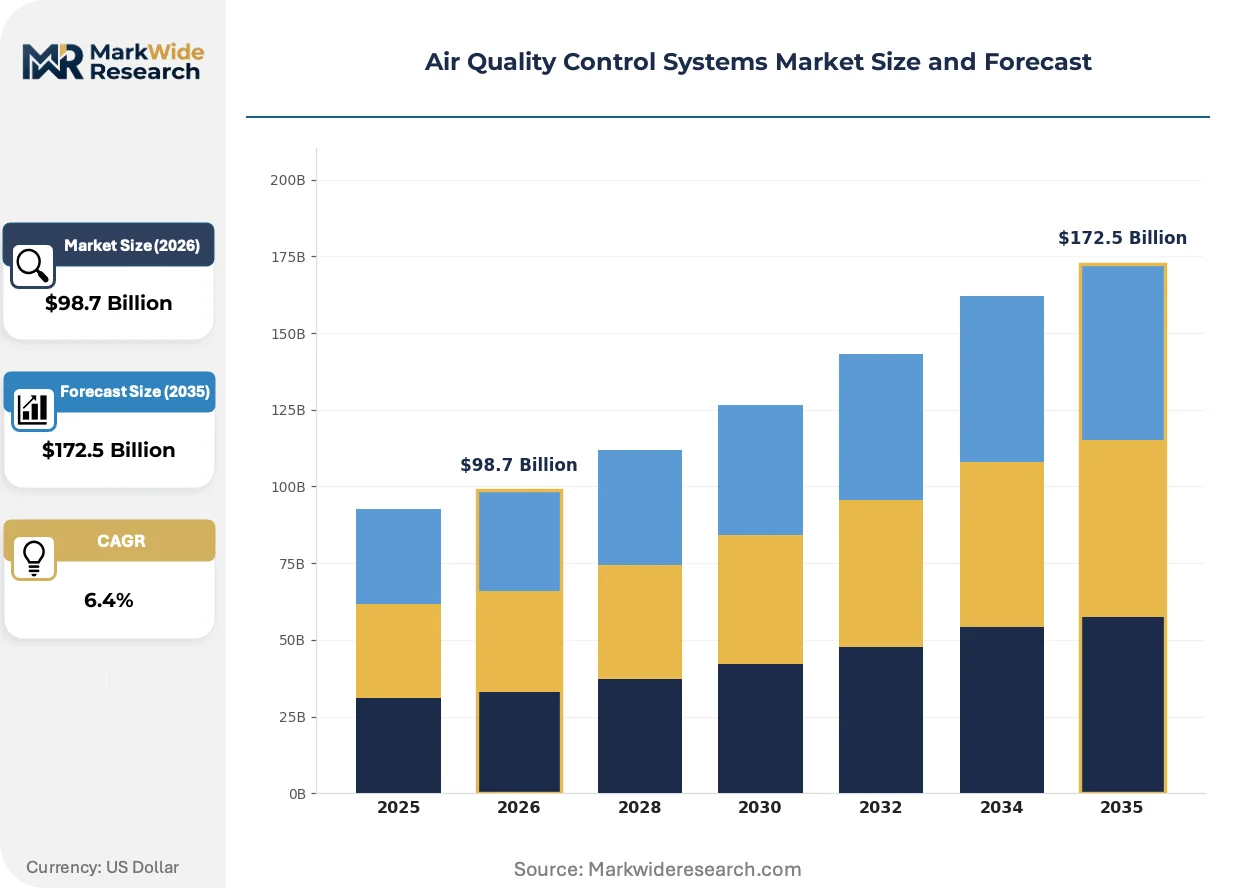
Market Dynamics
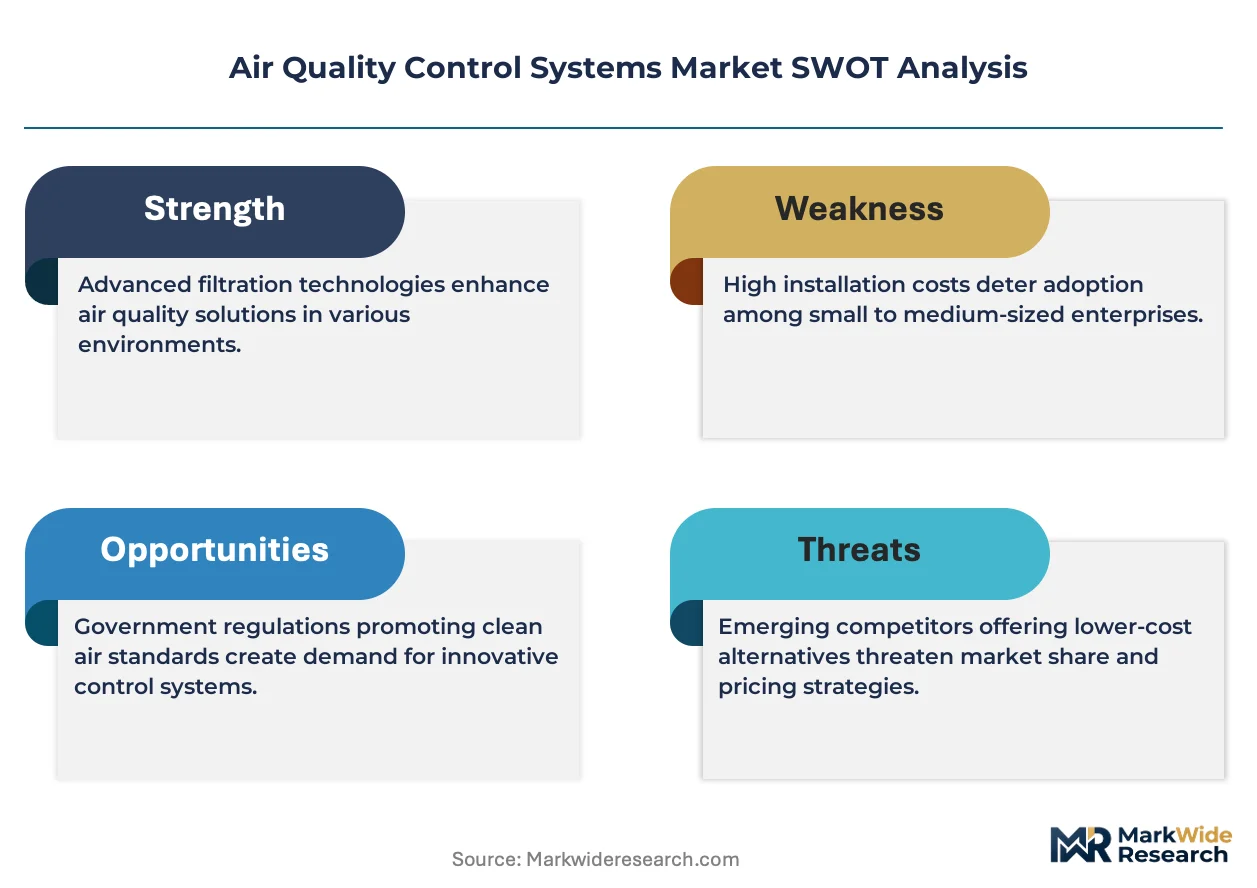
The market's central dynamic is a structural demand shift from the declining coal-fired power generation sector toward advanced manufacturing and industrial processing. This pivot is driven by stringent air quality mandates, compelling investment in more specialized and efficient systems.
Growth Catalysts
- Industrial Policy Mandates:China's dual carbon goals and India's production-linked incentive schemes for manufacturing are forcing industrial operators to integrate best-available control technologies, directly stimulating system demand in those regions.
- Advanced Manufacturing Expansion:The rapid build-out of semiconductor fabrication plants, which require ultra-clean environments and abatement of specific process gases, provides a high-value catalyst for customized filtration and scrubber systems.
- Technology Adoption in New Sectors:Fabric filters and specialized gas absorption technologies are gaining adoption beyond their traditional heavy industry base, finding new applications in food processing and chemical manufacturing for particulate and VOC control.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for large-scale systems like electrostatic precipitators or regenerative thermal oxidizers represents a major barrier for small and medium-sized industrial enterprises.
- Technical Customization Complexity:Developing effective abatement solutions for unique volatile organic compound (VOC) streams in the chemical and pharmaceutical industries requires extensive engineering, increasing project costs and lead times.
- Operational Cost Sensitivity:The long-term costs associated with energy consumption, consumable filter media, and sorbent materials for scrubbers can deter adoption, particularly in industries with thin profit margins.
Strategic Opportunities
- Emerging Industrial Applications:Developing tailored air quality control solutions for new industries such as battery gigafactories and green hydrogen production facilities presents a significant white-space opportunity for system providers.
- Integrated Monitoring Systems:There is a clear opportunity to bundle air quality control hardware with IoT-enabled sensors and predictive analytics software, offering clients a service model based on guaranteed compliance and operational efficiency.
- Geographic Expansion:Industrializing economies in Southeast Asia and Latin America, which are beginning to implement stricter environmental regulations, represent underpenetrated markets for both new equipment and retrofitting services.
Industry Challenges
- Legacy System Integration:Retrofitting modern, efficient air quality control systems into older industrial plants with space constraints and outdated infrastructure poses significant engineering and logistical challenges.
- Specialized Talent Scarcity:A shortage of process engineers and technicians with expertise in both industrial chemistry and advanced automation systems constrains the ability of vendors to design, install, and service complex solutions.
- Regulatory Patchwork Navigation:Manufacturers must navigate a complex and often inconsistent web of emissions standards that vary by country, state, and even municipality, complicating system design and increasing compliance risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Quality Control Systems Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $172.5 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Precipitators, Fabric Filters, Scrubbers, Gas Absorption Systems Technology: Particulate Removal, Gas Separation, Odor Control, Filtration Media Application: Power Generation, Chemical Processing, Food Processing, Semiconductor Fabrication End User: Utilities, Petrochemical Plants, Food Manufacturers, Electronics Producers |
| Companies Covered | Mitsubishi Heavy Industries, GE Vernova, Babcock & Wilcox, Siemens Energy, GEA Group Aktiengesellschaft, Daikin Industries, Donaldson Company, Thermax Limited, Fujian Longking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Quality Control Systems Market Strategic Shifts & Innovations
The evolution of air quality control technology is defined by a push for greater precision, efficiency, and adaptability. System design is moving away from one-size-fits-all utility-scale solutions toward configurable systems tailored for diverse industrial exhaust streams and stricter pollutant-specific regulations.
Compact, multi-pollutant control units are a key product evolution. Advanced manufacturing sectors, particularly semiconductor and pharmaceutical facilities, are rapidly adopting these integrated systems. This development is modularizing system architecture, enabling operators to deploy scalable pollution control targeted at specific production lines or processes, offering greater flexibility than facility-wide installations.
Europe's Industrial Emissions Directive (IED) is a significant regulatory driver. It compels facilities across numerous sectors to adopt Best Available Techniques (BAT) to meet stringent emission limit values for pollutants like NOx, SOx, and particulate matter. The chemical, cement, and non-ferrous metals industries are most affected, accelerating investment in technologies like selective catalytic reduction (SCR) and advanced fabric filters.
A notable behavioral shift involves industrial customers moving from one-time equipment purchases toward performance-based service contracts. This model disrupts traditional capital sales by bundling equipment with long-term operational support, consumable management, and guaranteed emissions compliance. This trend is most visible in the waste-to-energy and chemical processing sectors, where regulatory certainty and operational uptime are critical priorities.
Air Quality Control Systems Market Segmentation
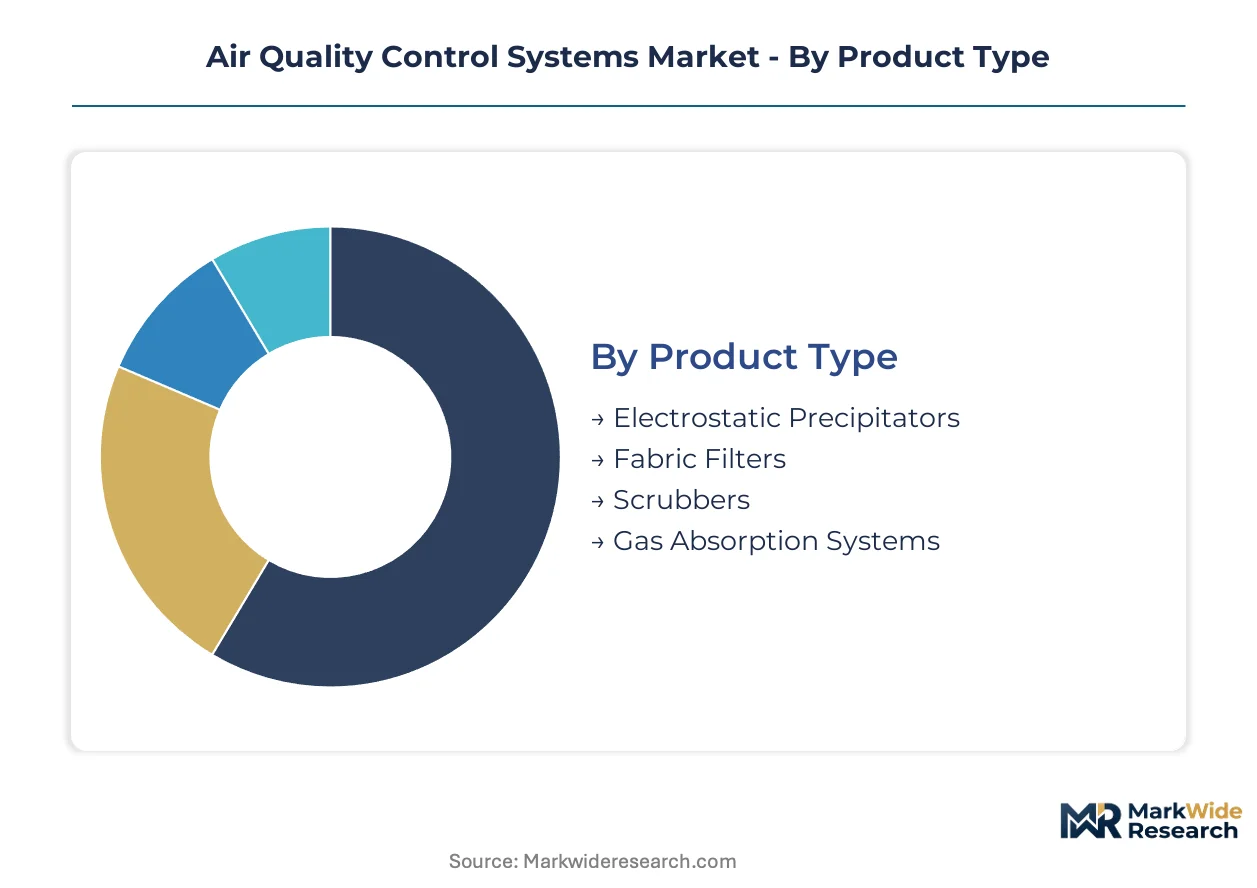
The Air Quality Control Systems Market exhibits diverse segmentation, reflecting the varied technological approaches and industrial demands for pollution abatement. Understanding these distinctions is crucial for providers to align their product development and service offerings with specific end-user requirements and regulatory pressures across different sectors.
Product Type:
The market for air quality control systems is differentiated by the core technologies employed for pollutant capture and neutralization.
- Electrostatic Precipitators:These systems utilize electrical charges to collect particulate matter from industrial gas streams, offering high efficiency for fine particle removal. Demand for these robust systems is concentrating in heavy industries like cement manufacturing and metals processing, driven by mandates for significant particulate reduction.
- Fabric Filters:Fabric filters, also known as baghouses, physically capture particulate matter on porous filter media, providing high collection efficiency for a wide range of particle sizes. Adoption is expanding significantly within the chemical processing and food manufacturing sectors, where stringent control of fine dust and airborne contaminants is essential.
- Scrubbers:Scrubbers remove gaseous and particulate pollutants from exhaust streams by bringing them into contact with a liquid, typically water, containing reagents. These systems are critical for sulfur oxides (SOx) and nitrogen oxides (NOx) abatement in industrial facilities.
- Gas Absorption Systems:These systems employ solvents to selectively absorb specific gaseous pollutants, such as volatile organic compounds (VOCs), from industrial emissions. Chemical and pharmaceutical industries rely on these for complex gas stream purification.
Mature deployment sits with Electrostatic Precipitators. Newer deployment is concentrated in Fabric Filters.
Technology:
The technological sophistication of air quality control systems directly impacts their effectiveness in mitigating specific industrial emissions.
- Particulate Removal:Technologies focused on particulate removal physically or electrostatically separate solid particles from gas streams, preventing their release into the atmosphere. Industrial facilities in China and India are heavily investing in these solutions due to strict national air quality standards.
- Gas Separation:Gas separation technologies isolate and remove specific gaseous pollutants, such as SOx, NOx, and VOCs, from industrial exhaust streams using chemical or physical processes. Chemical processing plants and petrochemical facilities require these advanced systems for compliance with stringent emission limits.
- Odor Control:Odor control systems neutralize or remove malodorous compounds from industrial emissions, often employing activated carbon adsorption or biofiltration techniques. Wastewater treatment plants and food processing facilities use these to address community impact concerns.
- Filtration Media:This segment encompasses the consumable materials used in fabric filters and other systems to capture pollutants, ranging from woven fabrics to specialized membranes. Donaldson Company specializes in these components for diverse industrial applications.
The market exhibits a pronounced shift towards advanced gas separation technologies. Legacy particulate removal technologies continue to see consistent investment for baseline compliance.
Application:
The diverse applications of air quality control systems reflect the varied pollution challenges across different industrial sectors.
- Semiconductor Fabrication:This application demands ultra-clean environments and precise abatement of specific process gases, requiring highly customized filtration and scrubber systems. The rapid build-out of semiconductor fabrication plants globally provides a high-value catalyst for system providers.
- Chemical Processing:Chemical processing applications require highly customized systems for specific volatile organic compound abatement, driving innovation in gas absorption technologies. Strict environmental regulations from the US EPA and the EU's Industrial Emissions Directive compel continuous investment in this sector.
- Power Generation:Historically a dominant application, power generation facilities, particularly coal-fired plants, utilize large-scale scrubbers and electrostatic precipitators for SOx, NOx, and particulate control. The declining share of coal-fired generation in developed economies is repositioning this segment.
- Food Processing:Food processing applications increasingly adopt fabric filters and specialized gas absorption technologies for particulate and VOC control, ensuring product purity and environmental compliance. These systems prevent cross-contamination and address specific airborne contaminants.
Demand for air quality control systems in semiconductor fabrication is expanding most quickly. Power generation applications represent a mature segment undergoing significant transformation.
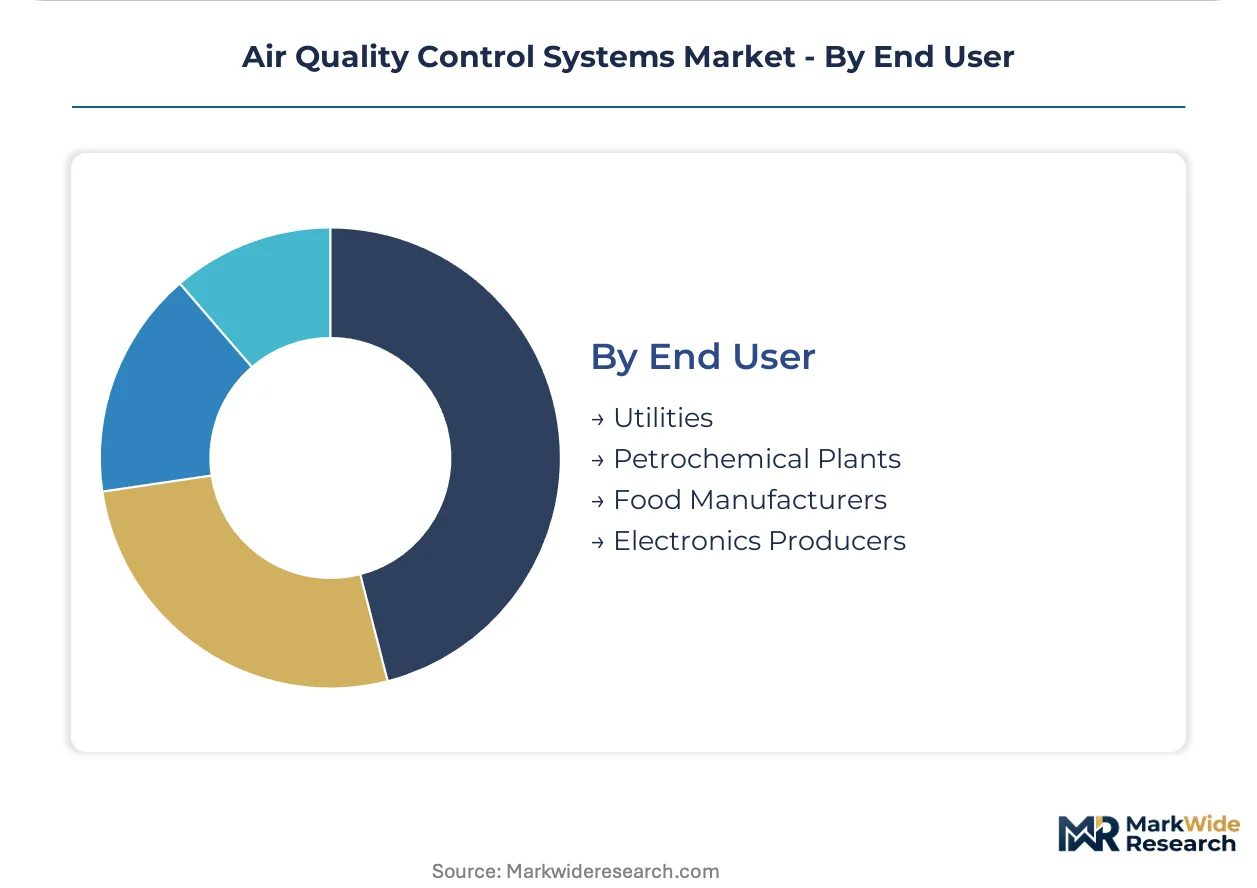
End User:
The end-user segment distinguishes between the primary industrial operators deploying air quality control solutions.
- Electronics Producers:These users, including semiconductor manufacturers, require advanced and precise air quality control systems to maintain ultra-clean production environments and manage process gas emissions. Stricter mandates and the expansion of fabrication plants globally underpin investment from this sector.
- Petrochemical Plants:Petrochemical facilities generate complex volatile organic compound streams and other gaseous pollutants, necessitating specialized gas absorption and scrubbing technologies for compliance. Regulatory pressure from organizations like the US EPA drives continuous upgrades in these operations.
- Utilities:Utility companies, primarily power generators, are major purchasers of large-scale air quality control systems for SOx, NOx, and particulate matter reduction. Siemens Energy serves this sector with broad energy infrastructure solutions.
- Food Manufacturers:Food manufacturers deploy air quality control systems to ensure product safety, prevent contamination, and manage process emissions such as odors and fine particulates. These systems contribute to both operational hygiene and environmental responsibility.
Investment from Electronics Producers is heavily influencing new system design and deployment. Utilities face structural shifts impacting their traditional procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and India's production-linked incentive schemes compel industrial operators to integrate best-available control technologies. These policy mandates are concentrating demand for air quality control systems in manufacturing-intensive zones across Asia, driving significant investment in pollution abatement solutions.
China
China's dual carbon goals directly stimulate system demand by requiring industrial operators to integrate best-available control technologies. The Ministry of Ecology and Environment (MEE) enforces stringent emission limits for particulate matter and SOx. Manufacturing hubs in the Yangtze River Delta are heavily investing in fabric filters and scrubbers.
India
Production-linked incentive schemes in India accelerate industrial expansion, necessitating concurrent investments in air pollution control. The Central Pollution Control Board (CPCB) mandates specific emission standards for new and existing facilities. Industrial clusters in Gujarat and Maharashtra are seeing increased adoption of particulate removal systems and gas separation technologies.
United States
The rapid build-out of semiconductor fabrication plants in the United States provides a high-value catalyst for customized filtration and scrubber systems. Regulations from the US Environmental Protection Agency (EPA) set stringent limits on criteria pollutants for industrial facilities. Technology hubs in Arizona and New York are investing in advanced gas absorption systems for process gas abatement.
Germany
Compliance with the EU's Industrial Emissions Directive compels facilities in Germany to adopt Best Available Techniques. This accelerates investment in technologies like selective catalytic reduction (SCR) and advanced fabric filters. Industrial regions like North Rhine-Westphalia are upgrading legacy systems to meet stricter emission limit values for NOx and SOx.
South Korea
Advanced manufacturing expansion, particularly in electronics production, drives demand for ultra-clean environments and precise abatement in South Korea. The Ministry of Environment sets strict air quality standards for industrial emissions, impacting chemical and semiconductor operations. Semiconductor fabrication facilities in Gyeonggi Province are adopting compact, multi-pollutant control units.
Air Quality Control Systems Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied technological sophistication and project scale requirements. The market exhibits a tiered structure, with large diversified industrial conglomerates competing with specialized technology providers. Strategic archetypes include full-service engineering firms, filtration media experts, and niche gas abatement solution providers. Geographic expansion into industrializing economies and technology licensing for advanced solutions are dominant competitive moves among these players.
Within the full-service engineering archetype, Babcock & Wilcox exemplifies legacy providers adapting large-scale utility solutions for new industrial applications. Siemens Energy, a German-based AG, leverages its broad energy infrastructure portfolio to serve both conventional and emerging sectors globally. Donaldson Company, an Inc., occupies a position as a specialized filtration media expert, providing components for diverse industrial applications from chemical processing to food manufacturing. These firms represent different strategic approaches to capturing value, highlighting the market's differentiation between comprehensive system integration and specialized component supply.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| GE Vernova |
| Babcock & Wilcox |
| Siemens Energy |
| GEA Group Aktiengesellschaft |
| Daikin Industries |
| Donaldson Company |
| Thermax Limited |
| Fujian Longking |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed specialists are shaping supply behavior and pricing discipline in the air quality control systems market. Their investment strategies directly influence component availability and system costs for industrial end-users.
Pricing Analysis
Premium pricing for short lead times characterizes the air quality control systems market, while standard inventory often sees competitive discounting. Project-based pricing dominates, reflecting the customized nature of abatement solutions for industrial exhaust streams. Price differentiation stems from the level of customization required for volatile organic compound abatement and the after-sales service packages offered. Pricing pressure stems from the high capital expenditure required for large-scale systems, particularly impacting small and medium-sized industrial enterprises. Electronics producers are generally less price-sensitive due to compliance urgency and cleanroom requirements, while food manufacturers exhibit higher price sensitivity.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke logistics patterns characterize the supply chain for air quality control systems, facilitating equipment delivery and spare parts. Geographic supply concentration for core components draws from China, Germany, and the United States, especially for advanced filtration media and specialized sensors. Raw material dependencies include rare earth elements for catalytic converters and specialized polymers for fabric filters. Single-source vulnerability for highly specialized components represents a key structural supply chain risk. The dominant downstream distribution model involves direct sales and engineering-procurement-construction (EPC) contractors managing large-scale industrial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play, driven by the increasing complexity of regulatory compliance which forces weaker players out. Only firms with deep engineering expertise and robust financial backing can meet evolving demands.
For Market Incumbents:
Hedge against the declining coal-fired power generation market by aggressively expanding into advanced manufacturing and green hydrogen applications. Secure long-term contracts with semiconductor fabrication plants, leveraging existing engineering capabilities for customized scrubber and filtration systems. Invest in advanced material science R&D for next-generation filtration media to counter the threat from more efficient, specialized solutions. Control key intellectual property for gas absorption technologies to maintain a competitive edge.
For New Entrants and Emerging Players:
Specialized engineering consultancies represent a viable entry point, offering niche expertise for complex volatile organic compound abatement. Target the chemical processing and pharmaceutical industries, which demand highly customized systems for specific pollutant streams. Focus on modular, compact multi-pollutant control units for easier integration into existing facilities. A go-to-market strategy emphasizing performance-based service contracts, bundling equipment with guaranteed compliance, offers a strong differentiation angle.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor private equity firms in industrializing economies like India, targeting regional players with strong local customer bases. Long-term viability over a five-to-ten-year window favors companies specializing in advanced gas separation technologies and integrated monitoring solutions. Acquire firms with proven expertise in battery gigafactories or green hydrogen production facilities, securing early positions in these emerging industrial applications. The signal to watch is the increasing stringency of national and regional emissions standards, driving forced adoption across new industrial sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialized Filtration Media Provider | Secures proprietary technology and critical components for next-generation air quality control systems, enhancing product performance. |
| Investment in IoT-Enabled Monitoring Platforms | Offers clients real-time compliance data and predictive maintenance, shifting towards a service-oriented business model for Siemens Energy. |
| Joint Venture for Green Hydrogen Abatement Systems | Positions the company in a high-growth emerging industrial application, leveraging expertise in gas separation for Mitsubishi Heavy Industries. |
| Expansion of Engineering Services in Southeast Asia | Captures demand in industrializing economies implementing stricter environmental regulations, extending market reach for Babcock & Wilcox. |
| Development of Compact Multi-Pollutant Control Units | Addresses the space constraints and specific needs of advanced manufacturing facilities, particularly for Donaldson Company. |
Research Approach
Multi-period observation of industrial emission trends and regulatory compliance rates anchored the trend analysis, supplemented by interviews with plant managers, environmental compliance officers, and procurement leads. Secondary validation drew from US EPA reports, EU Industrial Emissions Directive documents, and China's Ministry of Ecology and Environment publications, alongside corporate sustainability reports. This approach combined bottom-up data from facility-level deployments with top-down market sizing, ensuring comprehensive data triangulation.
Input-output matrices informed the forecast framework, modeling market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived through a regression analysis of historical market data and projected industrial output. Key industry-specific forecast inputs included planned semiconductor fabrication plant expansions and projected growth in chemical processing capacity.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions or rapid, disruptive technological breakthroughs not currently in pilot stages. Forecasts reflect assumptions documented through stakeholder consultations and secondary research. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Air Scrubber Market