
 Global Caspofungin Market | 2026-2036
Global Caspofungin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Caspofungin Market Foresight
The EU Green Deal is consolidating pharmaceutical manufacturing standards across European supply chains, pushing injectable antifungal producers toward greener synthesis pathways. Merck & Co., Inc. anchors originator-grade caspofungin production through its established fermentation infrastructure. Fresenius SE & Co. KGaA (Fresenius Kabi) leverages hospital-centric distribution networks across European acute care settings. Sun Pharmaceutical Industries Ltd. competes on cost-optimized lyophilized powder output from Indian manufacturing hubs.
Caspofungin is a semisynthetic lipopeptide antifungal agent derived from fermentation of Glarea lozoyensis, formulated as acetate salt for intravenous administration, and functions by noncompetitive inhibition of beta-1,3-D-glucan synthase to disrupt fungal cell wall integrity in Candida and Aspergillus species. The injection segment dominates hospital procurement due to immediate bioavailability requirements in septic patients, while lyophilized powder formats sustain margin pools through extended shelf stability and cold-chain flexibility. Therapy area demand tilts toward invasive candidiasis as ICU stays lengthen and immunocompromised patient populations expand across tertiary care centers.
FDA post-market surveillance, EMA pharmacovigilance frameworks, and WHO prequalification standards collectively elevate barrier-to-entry for generic caspofungin manufacturers seeking institutional tenders. India's CDSCO aligns with ICH stability guidelines for export-oriented injectable facilities supplying regulated markets. Stakeholders must monitor evolving FDA guidance on endotoxin thresholds for lipopeptide injectables and anticipate how EU MDR traceability mandates will reshape batch-release documentation requirements for hospital pharmacy buyers.
Market Dynamics
Hospital procurement consolidation under antimicrobial stewardship programs is compressing supplier margins while elevating compliance thresholds for generic injectable manufacturers across regulated markets.
Growth Catalysts
- Antimicrobial Stewardship Mandates:US hospital systems now embed echinocandins into invasive fungal infection protocols, institutionalizing caspofungin within ICU formularies.
- CDSCO-ICH Alignment:Indian export-oriented injectable facilities leverage harmonized stability guidelines to supply regulated markets with cost-optimized lyophilized powder formats.
- Immunocompromised Patient Expansion:Extended ICU stays and oncology patient volume growth in tertiary care centers drive sustained demand for beta-1,3-D-glucan synthase inhibition therapy.
Market Restraints
- Fermentation Input Volatility:Glarea lozoyensis culture media costs fluctuate with agricultural commodity prices, squeezing originator-grade production economics.
- EMA Pharmacovigilance Burden:Post-market surveillance frameworks for lipopeptide injectables extend batch-release timelines and elevate documentation overhead for European market entry.
- Azole Substitution Pressure:Triazole antifungals retain formulary preference in prophylactic settings, limiting caspofungin penetration to confirmed invasive candidiasis cases.
Strategic Opportunities
- EU Green Deal Synthesis Pathways:Greener fermentation and purification processes unlock preferential tender scoring in European hospital procurement.
- Lyophilized Powder Cold-Chain Flexibility:Extended shelf stability formats enable distribution into secondary hospital networks with limited ultra-low temperature infrastructure.
- WHO Prequalification:Institutional tender access in low- and middle-income health systems expands addressable demand beyond regulated markets.
Industry Challenges
- Endotoxin Threshold Compliance:FDA guidance evolution for lipopeptide injectables demands enhanced in-process testing capabilities and quality control workforce expansion.
- EU MDR Traceability Documentation:Batch-release record systems require reconfiguration to meet unique device identifier mandates for hospital pharmacy buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Caspofungin Market |
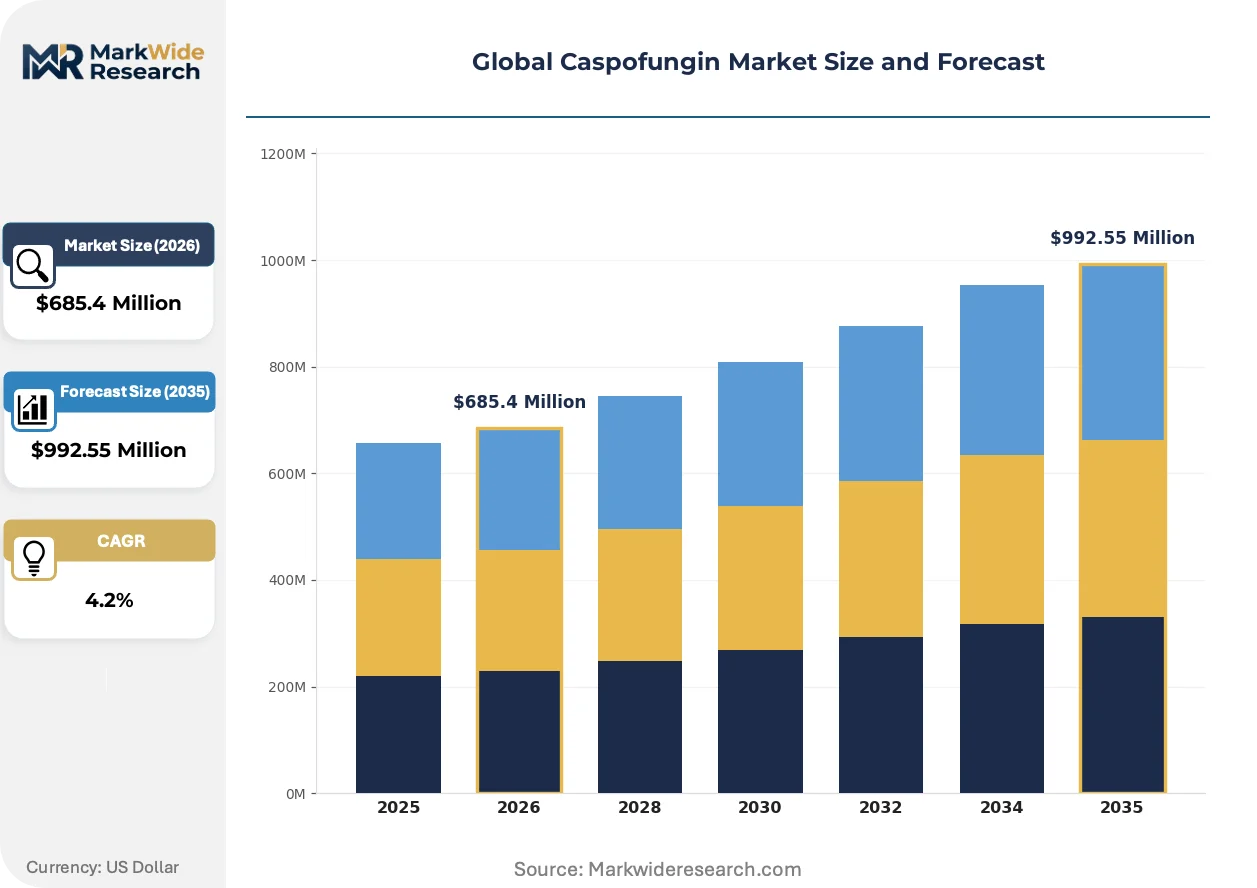
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Lyophilized Powder, Pre-filled Syringe, Vial Therapy Area: Invasive Candidiasis, Aspergillosis, Esophageal Candidiasis, Other Fungal Infections End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Outpatient Care Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Sun Pharmaceutical Industries Ltd., Alvogen Inc., Merck & Co., Inc., Athenex, Inc., Juno Pharmaceuticals, Fresenius SE & Co. KGaA (Fresenius Kabi), Gland Pharma Limited, Sandoz International GmbH, Cipla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Caspofungin Market Shifts & Advancements
Continuous manufacturing modalities and real-time release testing are compressing production cycles for parenteral antifungals while regulatory data harmonization accelerates multi-market filing strategies.
Single-use bioreactor systems is rewriting fermentation economics for Glarea lozoyensis-derived lipopeptides. Contract manufacturing organizations in India and Germany are adopting disposable vessel technologies at scale. This shift is rewriting capital deployment patterns, enabling mid-tier producers to enter originator-grade supply chains without fixed stainless-steel infrastructure commitments.
EU MDR traceability mandates now require serialized batch records linking active pharmaceutical ingredient fermentation to finished lyophilized vial distribution. European hospital pharmacy buyers demand machine-readable documentation for every unit administered. Injectable antifungal producers serving Germany, France, and Italy are reconfiguring enterprise resource planning systems to capture device identifier data across contract manufacturing networks.
Formulary preference is tilting toward immediate bioavailability in septic patients, compressing switching cycles between antifungal classes. Hospital antimicrobial stewardship committees in the United States and Germany now mandate echinocandin first-line therapy for documented invasive candidiasis, displacing empiric azole protocols. This behavioral shift is most visible in academic medical centers with dedicated fungal disease services.
Global Caspofungin Market Segmentation
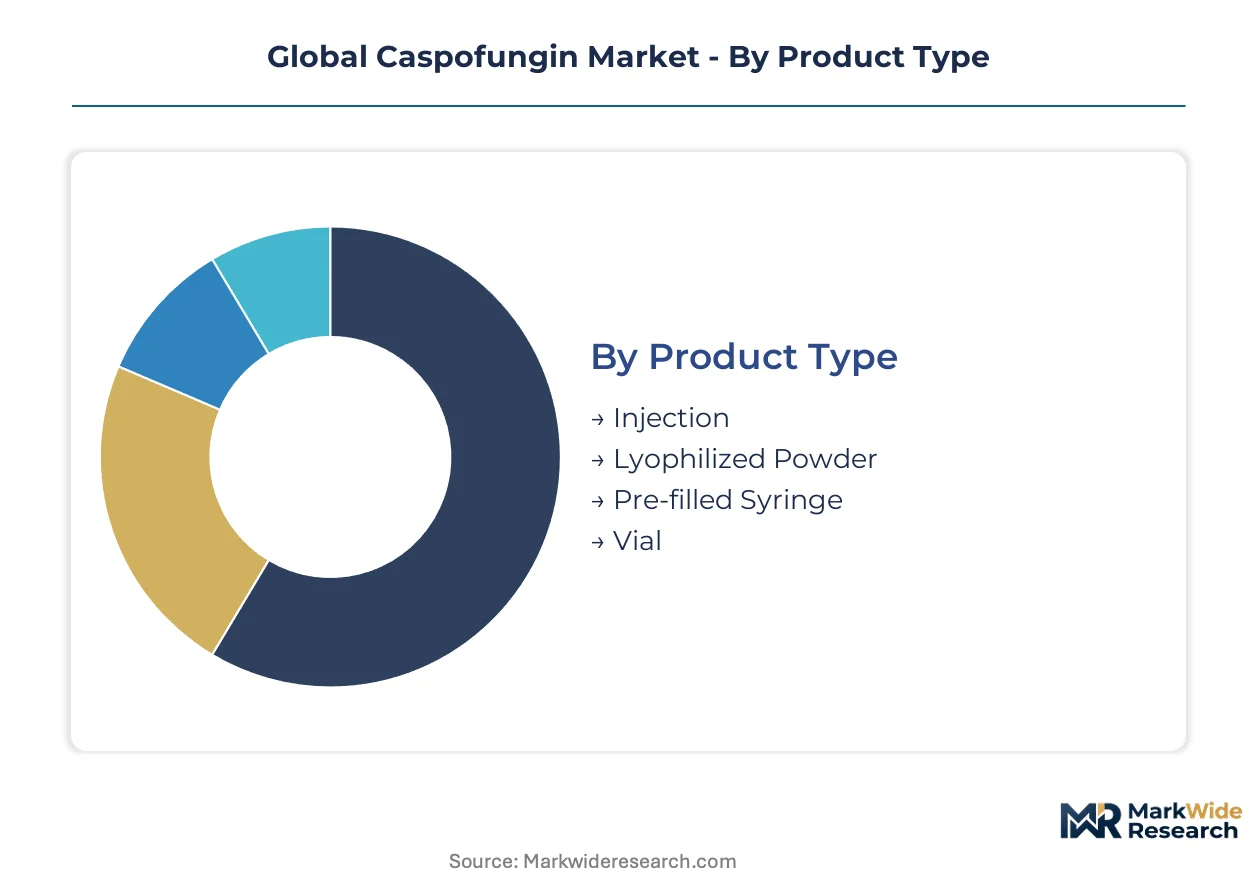
Caspofungin market segmentation reflects the tension between acute care immediacy and supply chain logistics. Hospital procurement teams balance bioavailability requirements against cold-chain infrastructure constraints when selecting product formats. Therapy protocols and distribution economics together determine which segments capture institutional formulary placement.
Product Type:
Standalone injection formats dominate immediate-use scenarios, while lyophilized and pre-configured systems embed into broader antimicrobial stewardship workflows.
- Injection:Ready-to-administer liquid formulation delivers immediate bioavailability for septic patients in ICU settings. Demand concentrates in United States academic medical centers where antimicrobial stewardship committees mandate echinocandin first-line therapy for documented invasive candidiasis.
- Lyophilized Powder:Freeze-dried acetate salt format extends shelf stability and enables distribution into secondary hospital networks with limited ultra-low temperature infrastructure. German and Indian hospital systems favor this format for formulary flexibility across tertiary and district care tiers.
- Pre-filled Syringe:Unit-dose presentation reduces compounding error risk and accelerates nursing workflow in emergency departments.
- Vial:Multi-dose glass containers support centralized pharmacy compounding operations with batch preparation economies.
Injection leads volumes today; lyophilized powder is gaining share fastest.
Therapy Area:
Cost tier stratification separates curative inpatient protocols from prophylactic outpatient management, with reimbursement intensity varying by diagnosis severity.
- Invasive Candidiasis:Bloodstream and deep-seated Candida infections requiring intravenous echinocandin therapy in immunocompromised and ICU populations. United States hospital systems embed this indication into core formulary tiers with dedicated antifungal stewardship oversight.
- Aspergillosis:Invasive mold infections in hematologic malignancy and transplant patients where caspofungin serves as salvage or combination therapy. German and French tertiary centers drive demand through specialized fungal disease services.
- Esophageal Candidiasis:Mucosal infection in HIV and oncology patients, typically stepping down from systemic therapy.
- Other Fungal Infections:Refractory or rare mycoses including endemic dimorphic pathogens and breakthrough infections.
Invasive candidiasis leads volumes today; aspergillosis is expanding most quickly.
End User:
Customer type segmentation tracks institutional purchasing power and formulary control, with acute care sites commanding procurement consolidation.
- Hospitals:Tertiary and secondary acute care facilities with centralized pharmacy and antimicrobial stewardship infrastructure. United States, Germany, and India anchor procurement volume through expanding ICU formulary coverage for invasive fungal infection protocols.
- Specialty Clinics:Oncology and transplant outpatient centers managing prolonged neutropenia and prophylactic antifungal regimens.
- Diagnostic Laboratories:Reference labs providing fungal identification and susceptibility testing to guide targeted therapy selection.
- Outpatient Care Centers:Ambulatory infusion sites administering step-down therapy for stable patients transitioning from inpatient care.
Hospitals lead volumes today; specialty clinics are climbing the fastest.
Distribution Channel:
Supply concentration favors direct and institutional channels over fragmented retail, reflecting parenteral administration requirements and cold-chain sensitivity.
- Hospital Pharmacies:Internal procurement arms managing formulary placement, inventory, and bedside delivery for inpatient units. United States health systems and German hospital networks consolidate purchasing through centralized pharmacy committees.
- Retail Pharmacies:Community dispensaries handling limited outpatient prescriptions and discharge medication fulfillment.
- Online Pharmacies:Digital procurement platforms serving outpatient and specialty clinic segments with direct-to-site delivery.
- Direct Sales:Manufacturer-to-institution contracts for large health systems and group purchasing organizations.
Hospital pharmacies lead volumes today; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Originating from Merck & Co.'s fermentation-based development in New Jersey during the early 2000s, caspofungin production has diffused across three continents as hospital formulary adoption expanded. Manufacturing gravity now concentrates in jurisdictions with established sterile injectable infrastructure and aligned regulatory frameworks.
United States
Academic medical centers in Boston and New York anchor demand through dedicated fungal disease services and antimicrobial stewardship mandates. FDA post-approval safety monitoring elevates compliance costs for generic injectable manufacturers seeking institutional tenders. The Research Triangle Park corridor in North Carolina hosts contract manufacturing organizations specializing in lipopeptide fermentation and lyophilized powder finishing.
Germany
Tertiary care networks in Munich and Hamburg drive echinocandin formulary placement through specialized ICU protocols for invasive candidiasis. EU MDR traceability mandates reshape batch-release documentation requirements for hospital pharmacy buyers across Bavaria and North Rhine-Westphalia. The Frankfurt-Rhine-Main pharmaceutical cluster concentrates sterile injectable finishing capacity for European distribution.
India
Export-oriented injectable facilities in Hyderabad and Ahmedabad leverage CDSCO-ICH alignment to supply regulated markets with cost-optimized lyophilized powder formats. Oncology patient volume growth in Mumbai and Delhi tertiary centers expands domestic consumption alongside manufacturing for external markets. The country's national pharmaceutical regulator maintains stability guideline harmonization to sustain prequalification pathways.
Switzerland
Specialized fungal disease services in Basel and Zurich academic hospitals sustain demand for originator-grade caspofungin in hematologic malignancy protocols. Swissmedic pharmacovigilance frameworks extend batch-release timelines for lipopeptide injectables entering the market. The Basel biopharmaceutical corridor anchors fermentation infrastructure for semisynthetic lipopeptide production.
Japan
Hematopoietic stem cell transplant centers in Tokyo and Osaka drive aspergillosis segment demand through salvage therapy protocols. PMDA stability requirements for parenteral antifungals align with ICH guidelines to facilitate multi-market filing strategies. The Kanto pharmaceutical manufacturing belt concentrates lyophilized powder finishing for domestic hospital procurement.
Global Caspofungin Market Competitive Landscape
Capital-heavy fermentation producers compete with asset-light formulation specialists across the caspofungin supply chain. Market structure tilts toward consolidated originator-grade supply anchored by established biopharmaceutical infrastructure, with fragmented generic competition compressing margins in lyophilized powder segments. Three archetypes dominate: integrated fermentation-originators, hospital-centric distributors, and cost-optimized Indian manufacturers. Capacity expansion in single-use bioreactor systems and strategic partnerships for European distribution represent the dominant competitive vectors.
Among originator-grade producers, Merck & Co., Inc. anchors fermentation-based supply through its New Jersey infrastructure. Sun Pharmaceutical Industries Ltd. and Gland Pharma Limited exemplify the Indian cost-optimization archetype, occupying positions within export-oriented lyophilized powder manufacturing. Fresenius SE & Co. KGaA represents the hospital-centric distribution model, leveraging acute care networks across European settings.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd. |
| Alvogen Inc. |
| Merck & Co., Inc. |
| Athenex, Inc. |
| Juno Pharmaceuticals |
| Fresenius SE & Co. KGaA (Fresenius Kabi) |
| Gland Pharma Limited |
| Sandoz International GmbH |
| Cipla Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up contract manufacturing organizations now control substantial sterile injectable capacity across India and Germany, concentrating pricing discipline through portfolio-wide procurement leverage while simultaneously reshaping supply chain sourcing patterns toward single-use bioreactor systems.
Pricing Analysis
Three-tier pricing structure across originator-grade, certified-generic, and unbranded-generic levels dominates hospital procurement contracts, with FDA and EMA certification tiers commanding substantial premiums over CDSCO-only registered alternatives. Price differentiation separates fermentation-originator supply from lyophilized powder generics, with German and United States buyers absorbing higher costs for EU MDR-compliant batch documentation. Cost compression in the unbranded-generic tier is intensifying because Indian manufacturers compete aggressively for WHO prequalification status. Specialty clinics in oncology and transplant settings exhibit the highest price sensitivity due to prolonged prophylactic regimens, while academic medical centers with dedicated fungal disease services prioritize immediate bioavailability over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical sector are reshaping sourcing patterns for fermentation media and active pharmaceutical ingredient precursors, pushing export-oriented facilities toward captive cultivation of Glarea lozoyensis strains. Supply concentrates in India, Germany, and the United States for finished lyophilized powder formats, with Switzerland anchoring originator-grade fermentation infrastructure. Raw material dependencies center on agricultural commodity-priced culture media, specialized filtration membranes, and borosilicate glass vial supply. Single-source vulnerability in Glarea lozoyensis strain banks represents a structural risk, as proprietary cell lines remain concentrated with originator heritage. Distribution runs through hospital pharmacy committees and group purchasing organizations in the United States, direct manufacturer contracts in Germany, and institutional tender platforms in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA post-approval safety monitoring and EMA pharmacovigilance frameworks continuously elevating compliance thresholds that institutionalize demand for certified manufacturers.
For Market Incumbents: Acquire single-use bioreactor capacity and disposable vessel technology platforms to compress capital deployment cycles for mid-tier production expansion. Defend against azole substitution pressure by embedding caspofungin into antimicrobial stewardship protocols through clinical data partnerships with academic medical centers. Backward integration into Glarea lozoyensis strain banking secures supply continuity against fermentation input volatility. For New Entrants and Emerging Players: Continuous manufacturing modalities with real-time release testing capabilities offer entry pathways into European hospital procurement networks constrained by EU MDR traceability mandates. Target secondary hospital networks in India and district care tiers in Germany with lyophilized powder formats optimized for limited cold-chain infrastructure. WHO prequalification status unlocks institutional tender access in low- and middle-income health systems with compressed competitive intensity. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian cost-optimized lyophilized powder manufacturers with CDSCO-ICH alignment and established export capacity to regulated markets. Long-term viability over the forecast horizon hinges on regulatory data harmonization sustaining multi-market filing efficiencies. Monitor FDA guidance evolution on endotoxin thresholds for lipopeptide injectables as the inflection indicator for quality control workforce expansion requirements and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Bioreactor Adoption | Disposable vessel technologies enable mid-tier producers to enter originator-grade supply chains without fixed stainless-steel infrastructure. |
| WHO Prequalification Pathway | Institutional tender access in low- and middle-income health systems expands addressable demand beyond regulated markets. |
| EU MDR Traceability Compliance | Serialized batch records linking API fermentation to finished vial distribution satisfy German and French hospital pharmacy requirements. |
| Antimicrobial Stewardship Integration | Embedding echinocandins into ICU protocols institutionalizes formulary placement against empiric azole competition. |
| CDSCO-ICH Stability Alignment | Harmonized guidelines enable Indian export facilities to supply regulated markets with cost-optimized formats. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up volume modeling from individual country demand trajectories and top-down cross-checks against antimicrobial stewardship program adoption rates ensured analytical consistency.
Historical reference periods anchored the projection horizon to observed formulary placement cycles and regulatory approval timelines across major markets. The analytical framework segmented by product type, therapy area, end user, and distribution channel, with regional regulatory clusters treated as distinct demand determinants. CAGRs were derived from fitted growth curves calibrated to ICU expansion rates and immunocompromised patient population trends, incorporating fermentation capacity utilization and lyophilized powder format adoption as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance evolution on endotoxin thresholds, EU MDR implementation pace, and Glarea lozoyensis culture media cost volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market