
 Global Rabies Vaccine Market | 2026-2036
Global Rabies Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rabies Vaccine Market Foresight
Multi-source procurement for active pharmaceutical ingredients is consolidating as manufacturers seek supply security amid geopolitical friction. Serum Institute of India leverages its vertically integrated fermentation infrastructure to dominate bulk antigen production. Sanofi sustains competitive positioning through differentiated purification platforms for human diploid cell vaccines. GlaxoSmithKline anchors European distribution through established cold-chain partnerships with public health agencies.
Rabies vaccines are sterile biological preparations derived from inactivated or attenuated rabies virus strains, formulated for intramuscular or intradermal administration to induce neutralizing antibody titers exceeding 0.5 IU/mL. Cell culture platforms, particularly Vero cell substrates, command the largest production volumes due to scalability and WHO prequalification acceptance. Post-exposure prophylaxis generates the dominant revenue pool given mandatory administration following category II and III exposures under WHO guidelines. Recombinant DNA vaccines represent the fastest-expanding technology segment as developers pursue reduced dose regimens and thermostable formulations for last-mile delivery.
FDA, EMA, and WHO prequalification programs collectively shape product standards, batch release protocols, and market access timelines across manufacturing jurisdictions. National immunization programs in endemic countries increasingly mandate domestic regulatory alignment with WHO norms, compressing approval pathways for imported products. Stakeholders must monitor evolving intradermal fractionation protocols and thermostable formulation breakthroughs that could reshape dosing economics and cold-chain requirements.
Market Dynamics
Post-exposure prophylaxis volume concentration in India, China, and Brazil is forcing manufacturers to reconfigure batch sizing and cold-chain logistics around tropical distribution corridors rather than temperate-zone hospital networks.
Growth Catalysts
- WHO prequalification pathways:Accelerated batch release protocols for Vero cell vaccines enable faster market entry in endemic regions.
- Intradermal fractionation protocols:Reduced antigen dosing per patient expands effective supply coverage without manufacturing expansion.
- Brazil:Mandatory notification systems for category III exposures drive consistent demand for complete PEP regimens through public health channels.
Market Restraints
- Fermentation capacity concentration:Bulk antigen supply clusters in Indian subcontinent facilities, creating single-source vulnerability for global fill-finish operations.
- EMA batch release timelines:Extended testing protocols for human diploid cell vaccines delay European market replenishment cycles.
- Lyophilization equipment scarcity:Limited global installed base for thermostable formulation drying constrains conversion from liquid to dry-powder presentations.
Strategic Opportunities
- Sub-Saharan Africa:National immunization program expansion creates first-mover advantage for WHO-prequalified intradermal regimen suppliers.
- Recombinant DNA platforms:Convergence with nanoparticle delivery systems enables single-dose post-exposure protection, collapsing conventional multi-visit compliance requirements.
- Direct government procurement:Bypassing multilateral procurement pools captures margin in Indonesia and Philippines national stockpile tenders.
Industry Challenges
- Biofermentation technician scarcity:Specialized cell culture expertise shortages in emerging manufacturing hubs delay facility commissioning.
- Legacy cold-chain infrastructure:Last-mile temperature excursions in tropical distribution networks compromise potency verification and wastage accounting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rabies Vaccine Market |
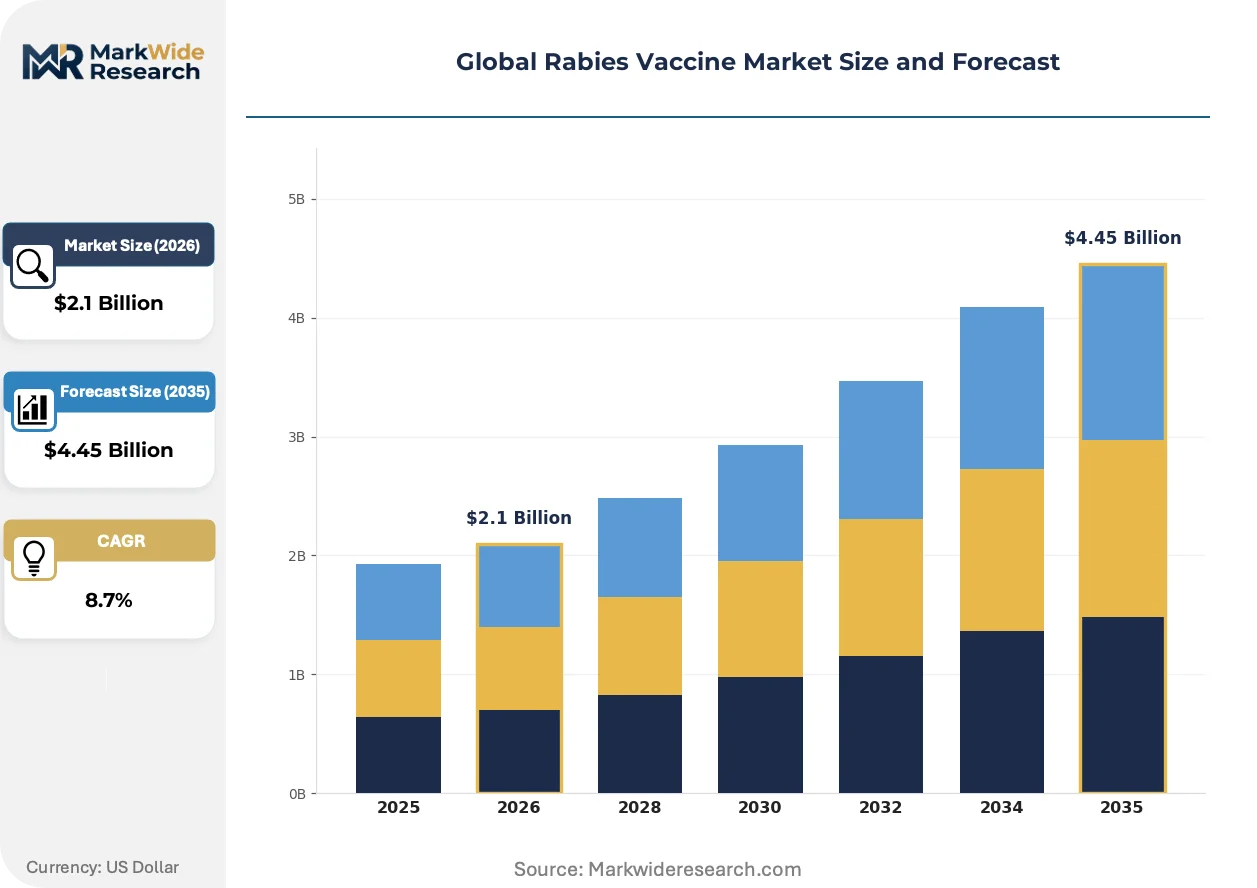
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Cell Culture, Embryonated Egg, Purified Duck Embryo, Recombinant DNA, Vero Cell Application: Post-Exposure Prophylaxis, Pre-Exposure Prophylaxis, Veterinary Immunization, Wildlife Control, Laboratory Research End User: Hospitals, Clinics, Veterinary Centers, Diagnostic Laboratories, Public Health Agencies Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Government Clinics, Veterinary Supply Stores |
| Companies Covered | Serum Institute of India, Sanofi, GlaxoSmithKline, Novartis AG, Merck & Co., Inc., Bharat Biotech International Limited, Cadila Pharmaceuticals, Zoetis, Berna Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rabies Vaccine Market Shifts & Advancements
Technology convergence between recombinant platforms and delivery system engineering is compressing dosing schedules while regulatory harmonization accelerates cross-border supply mobility.
Thermostable lyophilized formulations are unifying previously separate cold-chain and ambient distribution networks. Public health agencies in tropical endemic zones are adopting these presentations for rural outreach programs. This unification eliminates dry ice dependency and enables motorcycle-based last-mile delivery to village health posts previously unreachable within potency windows.
EMA's updated guidance on continuous manufacturing for biologicals is pressuring legacy batch-based production systems. European fill-finish operators must revalidate line configurations for real-time release testing. Human diploid cell vaccine specialists face the steepest compliance curves due to complex viral clearance demonstration requirements.
Consolidated national tendering by ministry of health procurement offices is displacing fragmented hospital-level purchasing across Southeast Asia. UNICEF and PAHO pooled mechanisms now dominate volume allocation decisions in Indonesia, Vietnam, and Philippines. This concentration rewards suppliers with WHO prequalification breadth and penalizes single-market registrants.
Global Rabies Vaccine Market Segmentation
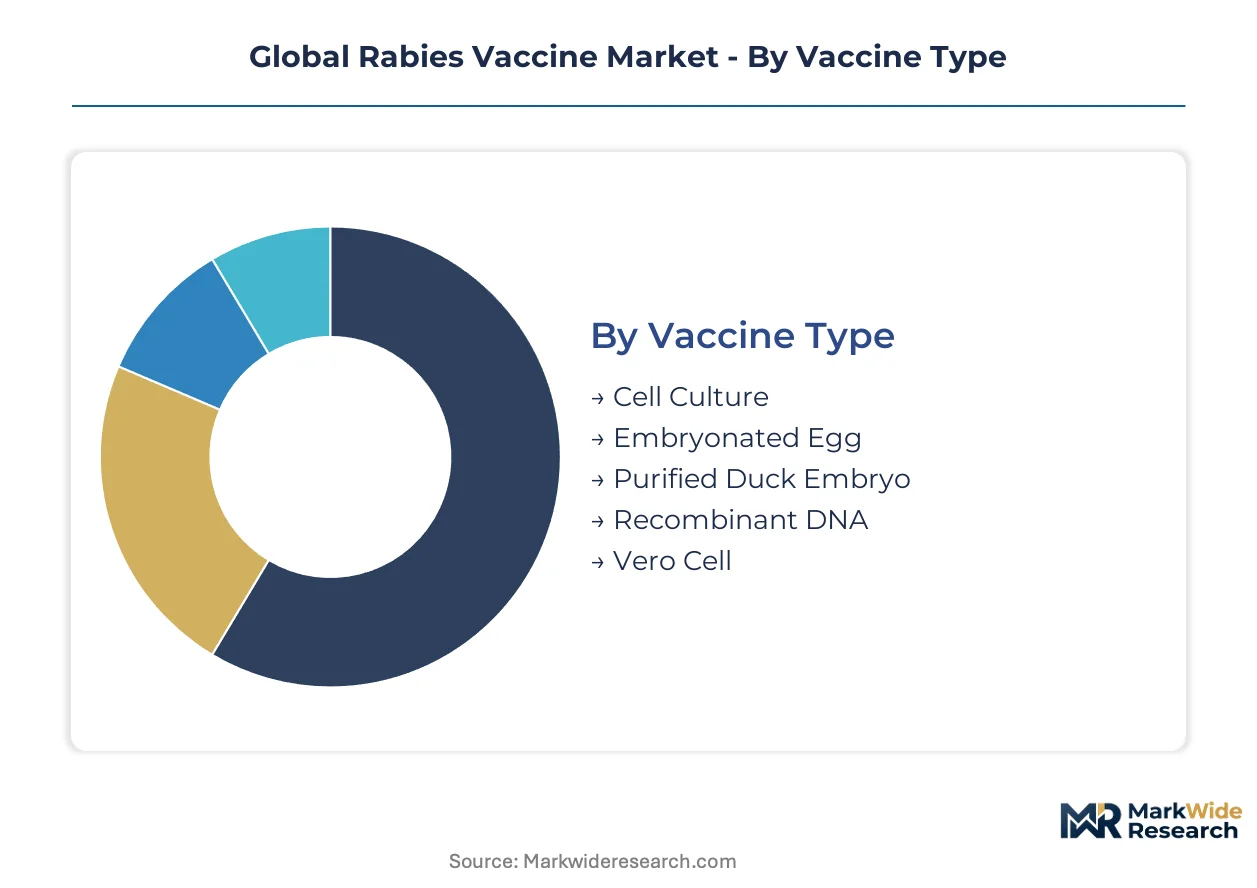
Rabies vaccine segmentation reflects divergent manufacturing economics across platform technologies and sharply contrasting cold-chain requirements between human and veterinary applications. Understanding these divides enables procurement offices to align supplier selection with specific delivery contexts.
Vaccine Type:
Platform concentration shapes antigen supply security, with fermentation capacity clustering around specific cell substrates and creating divergent vulnerability profiles for fill-finish networks.
- Vero Cell:Derived from African green monkey kidney epithelial cells, these vaccines achieve WHO prequalification acceptance through demonstrated scalability and consistent viral yield. Demand concentrates across Indian, Chinese, and Brazilian public health procurement channels where intradermal fractionation protocols maximize dose efficiency.
- Cell Culture:Human diploid cell substrates deliver superior purity profiles through extended purification cycles. European hospital networks and premium private clinics absorb volumes despite higher per-dose economics, constrained by EMA batch release timelines that extend replenishment cycles.
- Recombinant DNA:Engineered antigen expression systems enable thermostable formulation potential and reduced dosing schedules.
- Embryonated Egg:Legacy production infrastructure persists in select manufacturing jurisdictions with established avian supply chains.
- Purified Duck Embryo:Niche positioning for patients with documented cell culture hypersensitivity reactions.
Vero cell platforms absorb the bulk of installed fermentation capacity; recombinant DNA approaches are expanding most quickly as developers pursue single-dose regimens.
Application:
Prophylaxis timing relative to exposure event creates fundamentally different compliance architectures and margin structures across the demand spectrum.
- Post-Exposure Prophylaxis:Mandatory multi-dose administration following category II and III exposures under WHO guidelines generates consistent volume through public health channels. Brazil's compulsory notification systems and India's national immunization program expansion anchor demand concentration.
- Pre-Exposure Prophylaxis:Occupational risk categories including veterinary workers, laboratory personnel, and cave expedition guides drive scheduled administration. Western European occupational health mandates and North American adventure tourism medical standards sustain premium pricing tiers.
- Veterinary Immunization:Mass canine vaccination campaigns in endemic zones target reservoir population control.
- Wildlife Control:Oral bait distribution programs for raccoon, fox, and bat populations.
- Laboratory Research:Standardized challenge virus stocks and reference sera for assay validation.
Post-exposure prophylaxis commands dominant volume allocation; pre-exposure protocols are climbing the fastest as occupational safety regulations tighten across Southeast Asian manufacturing hubs.
End User:
Institutional purchasing power and cold-chain infrastructure maturity create tiered access patterns that segment pricing realization.
- Public Health Agencies:National immunization programs and ministry of health procurement offices leverage consolidated tendering volumes. UNICEF and PAHO pooled mechanisms in Indonesia, Vietnam, and Philippines reward WHO prequalification breadth with preferential allocation.
- Hospitals:Tertiary care centers manage severe category III exposures with complete immunoglobulin co-administration protocols. Urban hospital networks in São Paulo, Mumbai, and Shanghai concentrate advanced case management capacity.
- Clinics:Primary care points handle category II exposures and initial wound cleansing.
- Veterinary Centers:Companion animal practitioners and agricultural extension services administer pre-exposure schedules.
- Diagnostic Laboratories:Reference facilities confirm exposure status through fluorescent antibody testing prior to vaccine initiation.
Public health agencies absorb the bulk of procurement volume; clinics are expanding most quickly as intradermal protocols enable decentralized administration.
Distribution Channel:
Channel selection determines temperature monitoring accountability and wastage liability allocation across the delivery chain.
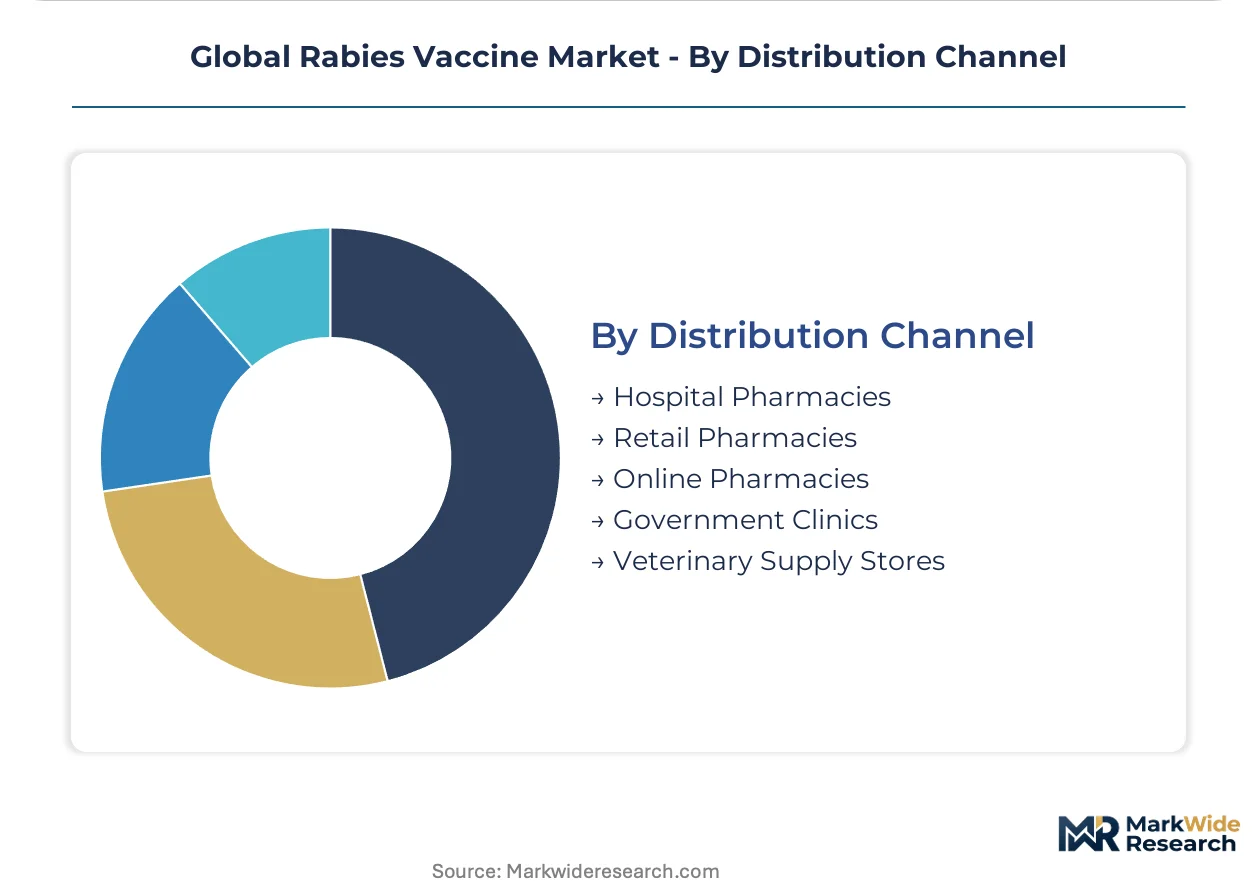
- Government Clinics:Direct ministry distribution bypasses commercial markups and enables centralized cold-chain oversight. Last-mile motorcycle delivery networks in Indonesian archipelago provinces and Philippine island chains demonstrate thermostable formulation advantages.
- Hospital Pharmacies:Captive procurement within integrated health systems ensures immediate availability for emergency exposures. Academic medical centers in Boston, London, and Singapore maintain stockpiles for research protocol requirements.
- Retail Pharmacies:Community access points support pre-exposure travelers and booster schedules.
- Online Pharmacies:Direct-to-consumer channels emerging for veterinary and travel medicine segments.
- Veterinary Supply Stores:Specialized distributors serving agricultural and companion animal practices.
Government clinics absorb the bulk of volume throughput; hospital pharmacies are expanding most quickly as urban emergency departments consolidate exposure management protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian fermentation infrastructure anchors bulk antigen supply for Vero cell platforms, while Brazilian notification systems and Chinese cold-chain networks shape demand distribution across tropical corridors.
India
Serum Institute of India and Bharat Biotech concentrate domestic fill-finish capacity around Pune and Hyderabad clusters. CDSCO alignment with WHO prequalification standards accelerates batch release for export markets. The Pune-Ahmedabad corridor houses vertically integrated fermentation facilities supplying global intradermal fractionation programs.
Brazil
Mandatory SINAN notification systems for category III exposures sustain consistent PEP regimen demand through public health channels. ANVISA harmonization with WHO norms compresses approval timelines for imported Vero cell products. São Paulo's tertiary hospital networks concentrate severe case management capacity with immunoglobulin co-administration protocols.
China
NMPA oversight of cell culture vaccine production scales domestic supply for national immunization program expansion. Provincial CDC cold-chain networks in Guangdong and Sichuan provinces enable rural outreach through motorcycle-based last-mile delivery. Chengdu and Shenzhen manufacturing hubs serve Southeast Asian export markets.
United States
FDA Emergency Use Authorization pathways accelerate thermostable formulation review for travel medicine segments. Occupational safety mandates from OSHA sustain pre-exposure prophylaxis demand among veterinary and laboratory workers. Boston and Atlanta academic medical centers maintain research stockpiles for challenge virus standardization.
Germany
EMA batch release timelines for human diploid cell vaccines extend replenishment cycles across European hospital networks. Bavaria and North Rhine-Westphalia host fill-finish operators serving premium private clinic channels. German distributors anchor continental cold-chain partnerships with public health agencies.
Global Rabies Vaccine Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reconfigure fermentation batch sizing around tropical distribution corridors. The vendor base concentrates around three strategic tiers: vertically integrated bulk antigen producers, differentiated purification specialists, and regional fill-finish operators. Consolidated national tendering rewards WHO prequalification breadth while penalizing single-market registrants. Technology licensing and geographic expansion constitute the dominant competitive moves as developers pursue thermostable formulation breakthroughs.
Within the vertically integrated tier, Serum Institute of India exemplifies fermentation infrastructure scale, while Sanofi occupies a position among differentiated purification specialists. GlaxoSmithKline anchors European distribution archetypes through established cold-chain partnerships. Bharat Biotech represents emerging market fill-finish capacity expansion, and Zoetis sits within veterinary immunization specialization. These five entities collectively illustrate competitive positioning across platform technologies and geographic coverage vectors.
| Leading Market Players |
|---|
| Serum Institute of India |
| Sanofi |
| GlaxoSmithKline |
| Novartis AG |
| Merck & Co., Inc. |
| Bharat Biotech International Limited |
| Cadila Pharmaceuticals |
| Zoetis |
| Berna Biotech |
| Others |
Supply & Pricing Matrix
Captive fermentation infrastructure in the Indian subcontinent anchors both bulk antigen availability and the pricing power of vertically integrated manufacturers serving WHO-prequalified procurement channels. Serum Institute of India's Pune-Ahmedabad corridor demonstrates how backward integration into Vero cell substrates insulates pricing from fermentation capacity bottlenecks while compressing margins for fill-finish-only competitors dependent on spot antigen purchases.
Pricing Analysis
Warranty and potency-guarantee bundling separate government tender winners from hospital channel suppliers, with cold-chain liability transfer marking the critical unbundling point. Three-tier pricing structure across premium, standard, and economy levels reflects WHO prequalification status, intradermal regimen approval breadth, and thermostable formulation certification. Price differentiation hinges on batch release speed and immunoglobulin co-administration bundling. Margins are tightening in European hospital networks due to EMA extended testing timelines, while public health agencies in India and Brazil demonstrate lowest price sensitivity through consolidated volume commitments.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and Brazil's ANVISA localization requirements are reshaping sourcing patterns toward regional fermentation clusters. Bulk antigen supply concentrates in India, China, and select Southeast Asian facilities, with Vero cell substrates and specialized culture media feeding from Indian and Chinese chemical suppliers. Single-source vulnerability persists for lyophilization equipment and cold-chain monitoring systems. Distribution runs through government clinic networks in endemic zones, hospital pharmacy captive procurement in urban centers, and UNICEF/PAHO pooled mechanisms across Southeast Asian archipelago provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global rabies vaccine market functions as a vertical-integration race where captive fermentation capacity and WHO prequalification breadth determine competitive survival. Players are pursuing upstream control over Vero cell substrates and downstream capture of national tender channels as the decisive levers.
For Market Incumbents: Deepen backward integration into thermostable formulation lyophilization to escape cold-chain dependency penalties. Expand intradermal regimen validation across Sub-Saharan African national immunization programs before recombinant DNA platforms achieve single-dose breakthroughs. Serum Institute of India's fermentation scale and Sanofi's purification differentiation must consolidate against emerging fill-finish operators in Southeast Asia. For New Entrants and Emerging Players: Recombinant DNA platform specialization offers the most penetrable wedge against established cell culture incumbents. Target Sub-Saharan African ministry of health procurement offices seeking alternatives to Vero cell supply concentration. Pursue direct government procurement bypass of UNICEF pooled mechanisms in Indonesia and Philippines through accelerated WHO prequalification investment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated mid-cap specialists seeking geographic expansion. Long-term viability favors manufacturers with demonstrated thermostable formulation conversion and intradermal regimen regulatory breadth. Watch for recombinant DNA platform readouts collapsing multi-visit compliance requirements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Acceleration | CDSCO and ANVISA alignment compresses batch release timelines for Indian and Brazilian market entry. |
| Thermostable Formulation Conversion | Lyophilization capacity expansion eliminates dry ice dependency for last-mile motorcycle delivery networks. |
| Intradermal Regimen Validation | Reduced antigen dosing per patient expands effective supply coverage without fermentation expansion. |
| Backward Integration into Fermentation | Captive Vero cell substrate production insulates margin from bulk antigen spot market volatility. |
| Direct Government Procurement Capture | Bypassing UNICEF and PAHO pooled mechanisms captures margin in Indonesia and Philippines tenders. |
Research Methodology
Independent corroboration across regulatory filings, national immunization program procurement databases, and manufacturer batch release records underwrites the qualitative findings in this study. Primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and ANVISA, formulary directors at UNICEF and PAHO, and hospital procurement managers in São Paulo and Mumbai combined with secondary validation from WHO prequalification listings, EMA assessment reports, FDA Emergency Use Authorization pathways, and ClinicalTrials.gov entries. Bottom-up segmentation modeling and top-down macroeconomic triangulation cross-validated volume and value estimates.
Historical reference periods anchored the projection horizon through demonstrated CAGR patterns across cell culture platform transitions and regulatory harmonization cycles. The analytical framework modeled segmentation across vaccine type, application timing relative to exposure, end-user institutional tier, and distribution channel accountability structure. CAGRs derived from fitted growth curves incorporating WHO prequalification expansion rates, intradermal protocol adoption trajectories, and national immunization program budget allocation shifts. Industry-specific inputs included fermentation capacity utilization rates and cold-chain infrastructure maturity indices.
Several conditions sit outside the modeled scope, including unforeseen zoonotic reservoir elimination campaigns, breakthrough single-dose recombinant platform approvals, and geopolitical disruption of Indian subcontinent fermentation exports. Forecasts reflect documented assumptions about regulatory harmonization pace and procurement consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Sildenafil Drug Market