
 Yeast-Based Spreads Market | 2026-2036
Yeast-Based Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast-Based Spreads Market Analytics
Household consumption of savory spreads is consolidating as the dominant end-use vertical, displacing traditional sweet spread preferences in urban pantries. Unilever Plc leverages its global distribution network to sustain shelf presence across European and Asia-Pacific retail channels. Bega Cheese anchors its position through deep brand equity in Australian households, while Sanitarium Health & Wellbeing competes on nutrition-focused formulations that target wellness-oriented consumers.
Yeast-based spreads are concentrated pastes derived from autolyzed brewer's yeast or primary-grown yeast, typically fortified with B vitamins and mineral salts, produced through controlled fermentation followed by thermal processing and blending. These products serve as umami-rich flavor enhancers and nutritional supplements in domestic and commercial food preparation. Savory spreads dominate volume throughput due to entrenched consumption habits in Commonwealth markets, while vegan spreads capture the fastest trajectory as plant-based dietary frameworks expand. Organic spreads command premium positioning through certified ingredient sourcing, though supermarket distribution channels still mediate the majority of value realization.
FSANZ governs yeast extract labeling and additive thresholds in Australia, while EFSA standards regulate nutritional claims across European markets, and the FDA oversees import compliance and ingredient safety for US-bound products. Tighter sodium reduction mandates in multiple jurisdictions are forcing reformulation investments that reshape competitive cost structures. Stakeholders must monitor evolving clean-label requirements and alternative protein cross-competition to preserve category relevance.
Market Dynamics
Sodium reduction mandates across Australia, the United Kingdom, and the European Union are forcing wholesale reformulation of legacy yeast-based spread recipes, compressing margin structures while opening avenues for clean-label positioning.
Growth Catalysts
- Vegan dietary frameworks:Plant-based eating patterns in Commonwealth markets are accelerating household adoption of yeast extracts as umami-rich alternatives to animal-derived savory spreads.
- EFSA nutritional claims harmonization:Standardized B-vitamin fortification labeling across European markets is reducing cross-border friction for yeast extract exporters.
- Autolysis process optimization:Advances in controlled thermal processing are yielding cleaner-tasting extracts that broaden palatability beyond traditional consumer bases.
Market Restraints
- Brewer's yeast supply concentration:Dependence on byproduct streams from beer manufacturing in Australia and the United Kingdom creates input volume volatility unrelated to spread demand.
- EFSA additive thresholds:Tightening maximum permitted levels for residual nucleotides in yeast extracts limits formulation flexibility for flavor-intense product lines.
- Nut butter substitution:Almond and cashew spreads are capturing pantry shelf space among wellness-oriented consumers seeking alternative protein sources.
Strategic Opportunities
- United States import compliance pathway:FDA ingredient safety recognition for yeast extracts remains underdeveloped relative to established Commonwealth markets, representing first-mover potential for compliant entrants.
- Direct-to-subscription channels:Specialty food box services are bypassing supermarket gatekeepers to reach diaspora consumers seeking familiar savory flavors.
- EU Green Deal procurement incentives:Public sector foodservice contracts with sustainability criteria favor organic-certified yeast spreads in institutional catering tenders.
Industry Challenges
- Clean-label certification timelines:Organic and non-GMO verification processes for primary-grown yeast strains extend new product launch cycles by 18-24 months.
- Sensory scientist scarcity:Formulation expertise balancing sodium reduction with umami intensity retention concentrates among a small cohort of retired industry specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast-Based Spreads Market |
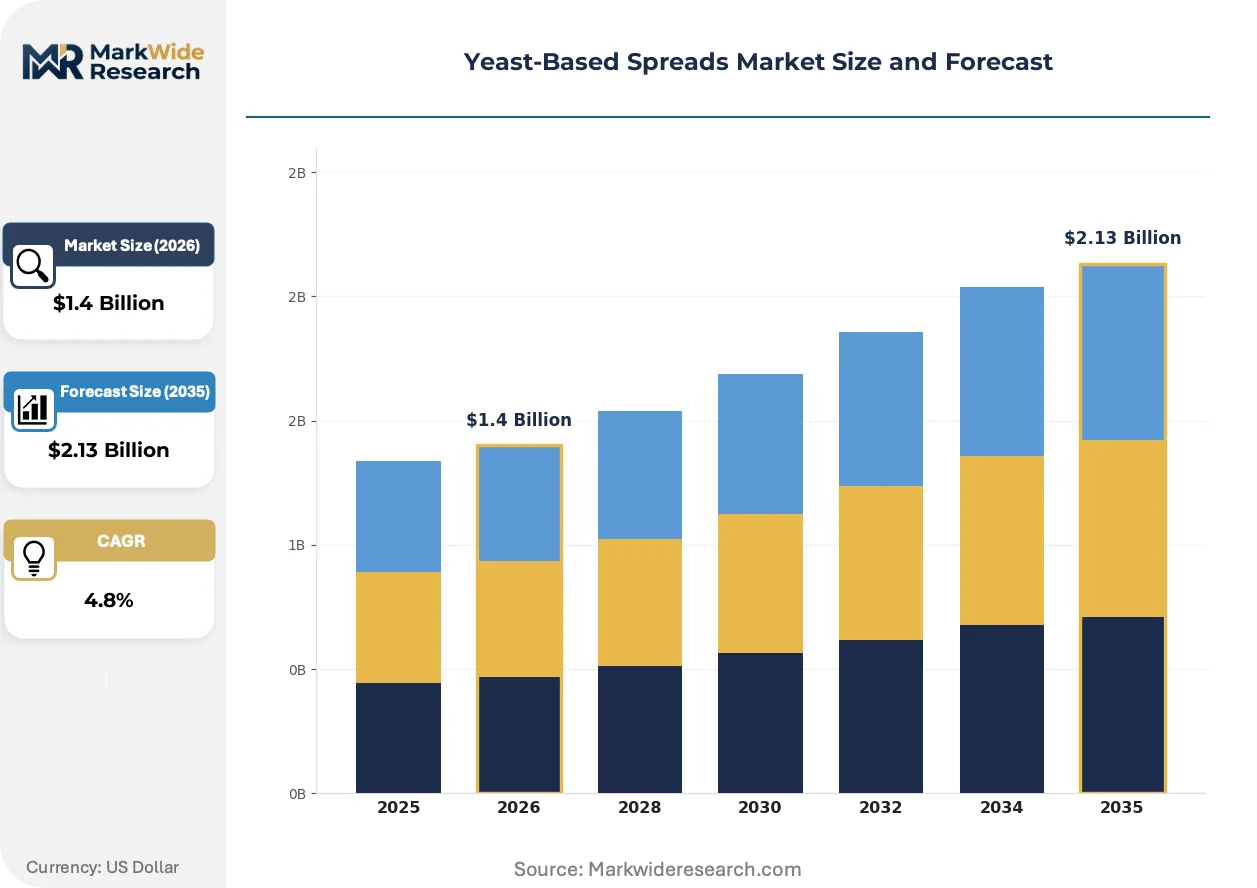
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Spreads, Savory Spreads, Vegan Spreads, Organic Spreads Use Case: Breads, Sandwiches, Dips, Snacks End User: Households, Food Services, Retailers, Manufacturers Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores |
| Companies Covered | Unilever Plc, Bega Cheese, Sanitarium Health & Wellbeing, Mars Foods, All Natural Foods of Stirling, Three Threes Condiments Pty. Ltd., Nature’s Blend, AussieMite, Jardox Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast-Based Spreads Market Evolving Landscape
Reformulation science and distribution channel fragmentation are jointly redefining how yeast-based spreads reach end consumers and what nutritional claims they can credibly advance.
Primary-grown yeast cultivation is overtaking brewer's yeast dependency as the dominant input sourcing strategy. Specialty nutrition manufacturers in Germany and the Netherlands are adopting controlled fermentation infrastructure to secure supply independent of beer production cycles. This vertical input control is overtaking traditional byproduct economics and enabling consistent organic certification.
FSANZ sodium reduction targets for savory spreads are compressing permissible salt content in Australian-manufactured products by 2025 implementation deadlines. Reformulation investments to maintain flavor intensity without sodium reliance are diverting R&D budgets from line extension programs. Premium positioned brands with established clean-label credentials are responding fastest, while value-tier products face technical barriers.
Retail buyer concentration in United Kingdom supermarket chains is compressing supplier negotiation leverage and accelerating own-label yeast spread introductions. Branded manufacturers are responding through direct-to-consumer subscription models and specialty retailer partnerships that bypass central procurement functions. This channel fragmentation is most visible in London and Manchester metropolitan areas where independent food halls are gaining traffic share.
Yeast-Based Spreads Market Segmentation
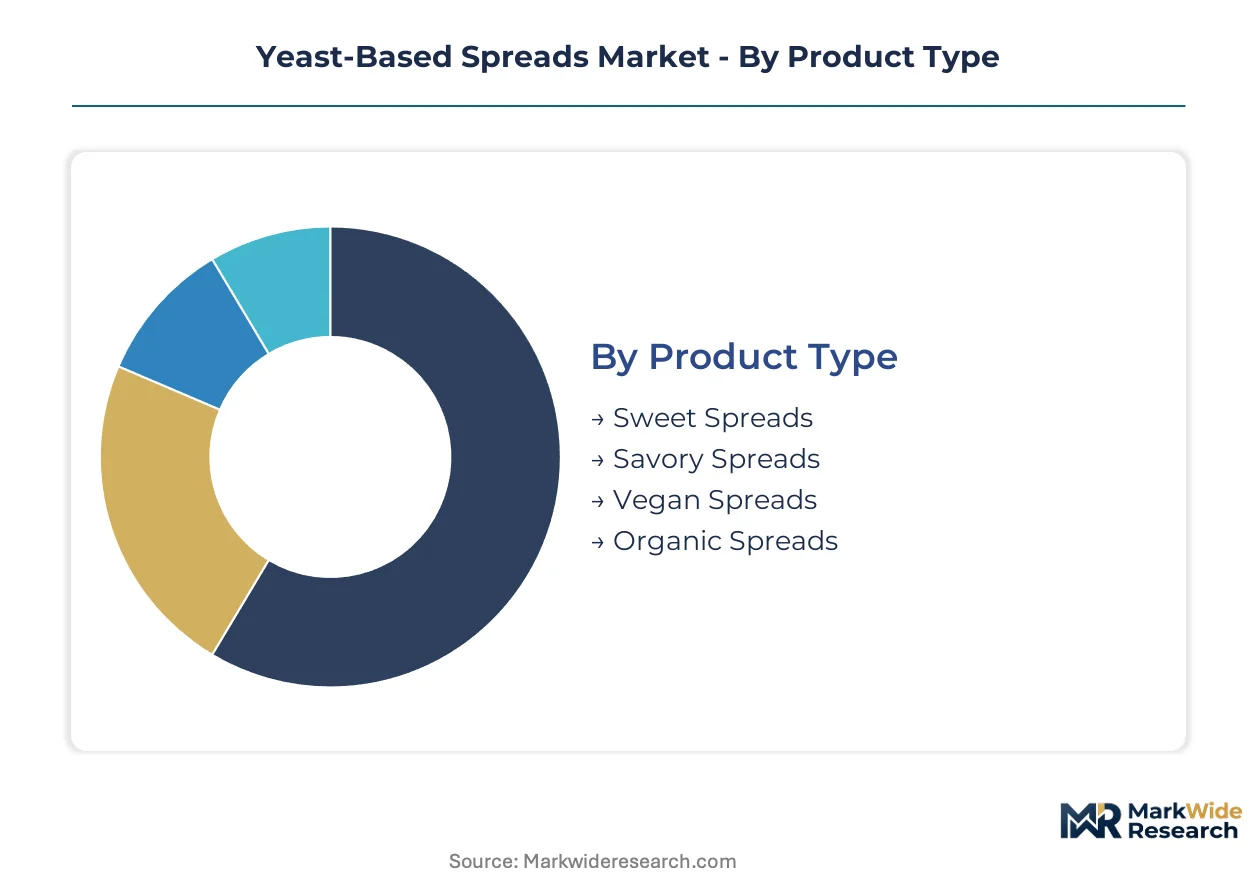
Yeast-based spreads fragment across four distinct axes that reshape procurement priorities and margin capture. Product formulation determines regulatory pathway and clean-label positioning. Distribution channel selection governs price realization and brand control intensity.
Product Type:
Formulation chemistry and ingredient sourcing specifications create divergent compliance burdens and consumer value propositions across product lines.
- Savory Spreads:Autolyzed yeast concentrates fortified with mineral salts and B-vitamin complexes dominate volume throughput in Commonwealth markets. Australian and British households sustain entrenched consumption habits that resist substitution from nut butters or alternative proteins.
- Vegan Spreads:Plant-certified formulations exclude all animal-derived processing aids and rely on primary-grown yeast strains. United Kingdom metropolitan demand is climbing fastest as flexitarian dietary frameworks displace traditional savory preferences.
- Sweet Spreads:Yeast extracts blended with malt extracts or vegetable glycerin for reduced-sugar breakfast applications.
- Organic Spreads:Certified organic primary-grown yeast inputs command 18-24 month verification timelines.
Savory spreads lead on scale; vegan spreads lead on momentum.
Use Case:
Application context determines serving size, frequency, and premiumization potential across consumption occasions.
- Breads:The foundational application where yeast spreads function as both flavor layer and nutritional supplement. Australian breakfast rituals and British tea traditions sustain highest per-capita penetration rates globally.
- Sandwiches:Convenience-oriented portable consumption drives single-serve sachet demand in United Kingdom foodservice channels. Workplace catering contracts specify portion-controlled formats that reshape manufacturing line configurations.
- Dips:Blending applications with cream cheese or vegetable bases for entertaining occasions.
- Snacks:Crackers and rice cake toppings for between-meal consumption.
Bread applications anchor volume; sandwich formats are expanding most quickly.
End User:
Purchasing authority and volume scale create distinct negotiation dynamics and service requirements.
- Households:Individual consumers making pantry replenishment decisions through supermarket or online channels. Brand loyalty and nostalgic preference strongly influence repurchase behavior in Australian and British markets.
- Food Services:Cafes, restaurants, and institutional caterers procuring bulk formats for menu incorporation. United Kingdom contract catering tenders increasingly specify sodium-reduced formulations aligned with public health procurement criteria.
- Retailers:Supermarket chains and independent grocers sourcing for resale with private-label development rights.
- Manufacturers:Industrial food processors using yeast extracts as ingredient inputs for soups, sauces, and savory snacks.
Households dominate absolute demand; food services show steepest expansion trajectory.
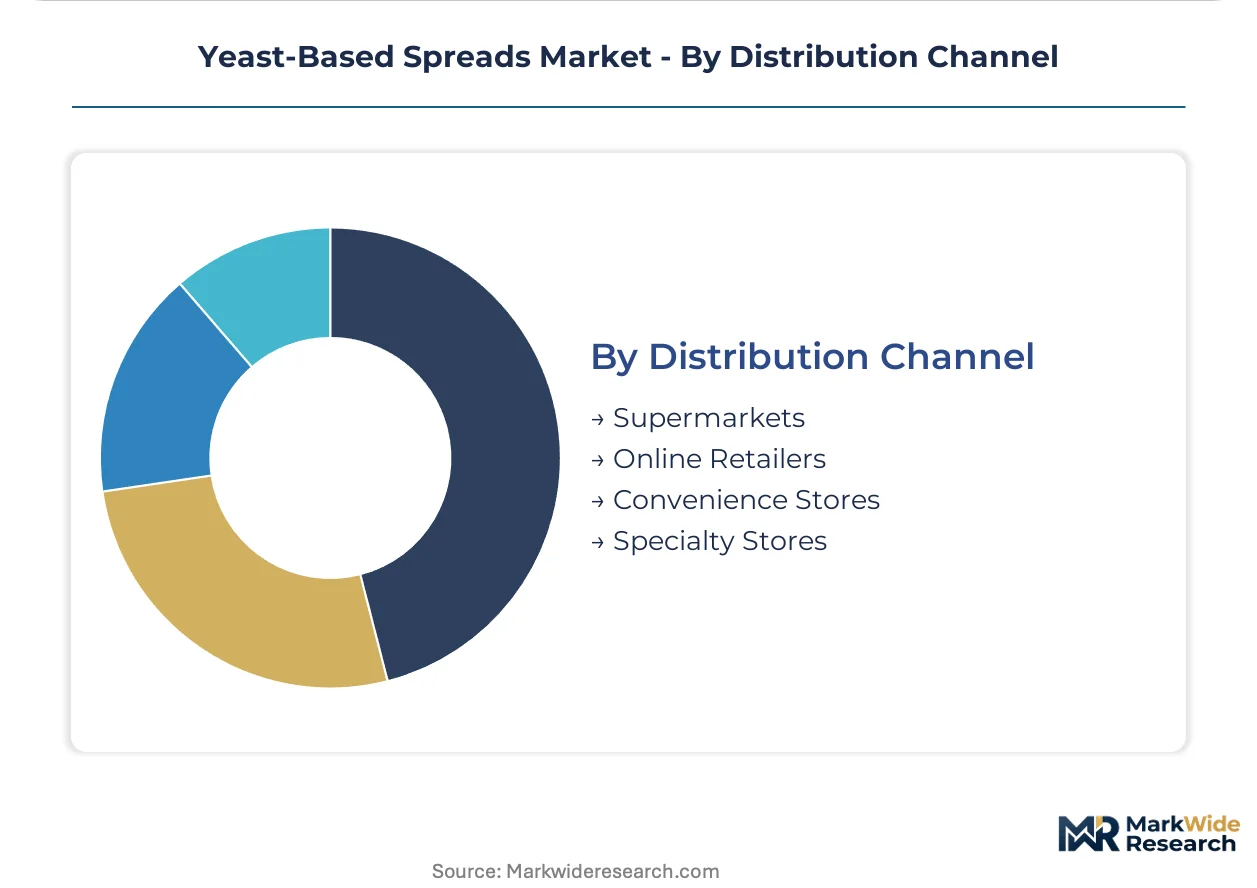
Distribution Channel:
Channel selection mediates price realization, brand narrative control, and consumer data access.
- Supermarkets:Concentrated retail buyer power in United Kingdom chains compresses supplier margins while demanding promotional participation. Australian Woolworths and Coles centralize yeast spread assortment decisions that determine national brand visibility.
- Online Retailers:Direct-to-consumer platforms and marketplace sellers bypass traditional gatekeepers. Diaspora consumers in North America access familiar Commonwealth brands through specialty e-commerce fulfillment.
- Convenience Stores:Impulse-oriented small-format retail for travel and emergency replenishment occasions.
- Specialty Stores:Health food and independent grocers curating organic and clean-label assortments.
Supermarkets retain volume leadership; online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate fermentation capacity toward jurisdictions with streamlined additive-approval pathways and lower sodium-reduction compliance costs.
Australia
Household pantry penetration rates remain highest globally, sustained by breakfast rituals in Sydney and Melbourne metropolitan areas. FSANZ sodium reduction mandates are compressing permissible salt content in manufactured spreads by 2025 deadlines. Queensland-based primary-grown yeast facilities are expanding controlled fermentation infrastructure to bypass brewer's yeast supply volatility.
United Kingdom
Flexitarian dietary shifts in London and Manchester are accelerating vegan-certified spread adoption faster than any Commonwealth market. EFSA harmonized B-vitamin fortification labeling is reducing cross-border friction for exports into continental Europe. Midlands manufacturing clusters are retooling legacy production lines to meet clean-label verification timelines.
Germany
Specialty nutrition manufacturers in Bavaria and North Rhine-Westphalia are pioneering primary-grown yeast cultivation independent of beer production cycles. EU Green Deal procurement criteria are favoring organic-certified spreads in institutional catering tenders. Stuttgart-area R&D facilities are advancing autolysis process optimization for cleaner-tasting extracts.
United States
Diaspora demand from Australian and British expatriates is driving specialty e-commerce channel growth in coastal metropolitan markets. FDA ingredient safety recognition for yeast extracts remains underdeveloped relative to Commonwealth standards, creating first-mover compliance opportunities. Pacific Northwest direct-to-consumer subscription services are bypassing traditional retail gatekeepers.
Netherlands
Controlled fermentation infrastructure investments near Rotterdam are securing supply chains for organic-certified input strains. REACH chemical safety registrations for processing aids are shaping formulation choices for EU-bound exports. Amsterdam-area foodservice distributors are consolidating procurement for sodium-reduced institutional catering contracts.
Yeast-Based Spreads Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with household-facing brands commanding premium shelf positioning while private-label suppliers capture volume through supermarket chain central procurement. Market structure tilts toward consolidated branded leadership in Australia and the United Kingdom, with fragmented specialty producers gaining traction in direct-to-consumer channels. Three archetypes dominate: heritage-brand incumbents leveraging nostalgic loyalty, wellness-positioned nutrition specialists, and private-label manufacturers serving retailer own-brand programs. Competitive moves concentrate on direct-to-subscription channel development and organic certification acquisition to bypass retail buyer concentration.
Within the heritage-brand tier, Unilever Plc and Bega Cheese occupy positions anchored by decades of pantry presence in Commonwealth households. Sanitarium Health & Wellbeing exemplifies the nutrition-specialist archetype, competing on wellness-oriented formulations that target sodium-conscious consumers. These three entities represent the dominant competitive anchors against which smaller specialty producers and private-label alternatives define their market entry strategies.
| Leading Market Players |
|---|
| Unilever Plc |
| Bega Cheese |
| Sanitarium Health & Wellbeing |
| Mars Foods |
| All Natural Foods of Stirling |
| Three Threes Condiments Pty. Ltd. |
| Nature's Blend |
| AussieMite |
| Jardox Ltd. |
| Others |
Value Network & Pricing Analysis
Yeast strain cultivation expertise concentrates in Bavaria and North Rhine-Westphalia, where fermentation technologist wages run 40 percent above Australian benchmarks. This labor-cost differential propagates through three-tier pricing structure across premium, standard, and economy levels, with European organic-certified spreads commanding shelf premiums that Commonwealth manufacturers cannot match without reformulation investments.
Pricing Analysis
Retailer markup layers in United Kingdom supermarket chains absorb 35-45 percent of final shelf price, compressing manufacturer margins and accelerating direct-to-consumer subscription pivots. Price differentiation separates organic-certified from conventional formulations, with certification grade and volume scale as twin drivers. Pricing pressure stems from FSANZ sodium reduction mandates forcing R&D diversion. Foodservice buyers exhibit highest price sensitivity due to tender-based procurement; households show lowest sensitivity where brand nostalgia anchors repurchase behavior.
Supply Chain Analysis
Brewer's yeast supply rests on byproduct streams from beer manufacturing in Australia and the United Kingdom, creating input volume volatility unrelated to spread demand. Raw material dependencies include autolyzed yeast concentrates, B-vitamin fortification complexes, and mineral salt blends. Single-source vulnerability concentrates in Queensland and Midlands brewing clusters where capacity fluctuations ripple through downstream formulation schedules. Distribution runs through supermarket central procurement in Commonwealth markets, with specialty e-commerce gaining share in North American diaspora corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Yeast-based spreads function as a geographic-arbitrage play: FSANZ sodium reduction timelines compress 18-24 months faster than EFSA harmonization cycles, rewarding manufacturers with dual-approval capabilities.
For Market Incumbents: Cement shelf presence through backward integration into primary-grown yeast cultivation, bypassing brewer's yeast supply volatility that threatens formulation consistency. Acquire organic certification capacity in Germany or the Netherlands ahead of EU Green Deal procurement deadlines. Nut butter substitution in wellness-oriented pantries represents the core threat; channel control through direct-to-subscription models offers the primary defensive lever. For New Entrants and Emerging Players: Direct-to-subscription channels offer the lowest barrier to diaspora consumers in North American coastal metros, where FDA recognition gaps create first-mover compliance opportunities. Target vegan-certified spreads in United Kingdom metropolitan flexitarian segments as the most penetrable white space. Specialty food box partnerships provide the specific go-to-market angle to bypass supermarket gatekeeper concentration. For Investors and Strategic Acquirers: Specialty nutrition manufacturers with controlled fermentation infrastructure are the most active acquirer in this space, seeking organic-certified input security. The five-to-ten year viability window favors entities with dual-jurisdiction regulatory approval capabilities. Acquisition target archetype: mid-tier German or Dutch primary-grown yeast facilities with existing EFSA compliance. Watch FSANZ clean-label timeline acceleration as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary-Grown Yeast | Queensland fermentation facilities bypass brewer's yeast supply volatility from Australian brewing cycles. |
| Organic Certification Acquisition | EU Green Deal procurement criteria in Rotterdam and Amsterdam institutional tenders favor certified suppliers. |
| Direct-to-Consumer Subscription Launch | London and Manchester food halls gain traffic share against supermarket central procurement concentration. |
| Sodium-Reduced Reformulation Investment | FSANZ 2025 implementation deadlines force R&D diversion from line extension programs in Australian manufacturing. |
| Dual-Jurisdiction Regulatory Approval | EFSA harmonization combined with FDA recognition gaps creates arbitrage for compliant Commonwealth exporters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation technologists, supermarket category buyers, foodservice procurement directors, and regulatory affairs specialists at FSANZ and EFSA with secondary validation through customs trade records, food standards filings, retail audit databases, and ingredient supplier disclosures. Bottom-up volume triangulation against top-down value estimates anchored forecast integrity.
Segment-weighting approaches distributed value across product type, distribution channel, end-user archetype, and geographic regulatory cluster throughout the forecast period. CAGRs derived from elasticity-adjusted consumption models incorporating sodium reduction mandate compliance costs and organic certification timeline premiums. Forecast inputs included brewer's yeast byproduct availability indices and flexitarian dietary shift penetration rates in Commonwealth metropolitan markets.
The model assumes a particular technology adoption path; alternative pathways for primary-grown yeast cultivation scale-up would alter the outlook. Forecasts reflect assumptions about FSANZ and EFSA timeline adherence, with brewer's yeast supply disruption or nut butter substitution acceleration as specific risk factors that could revise projections. A small set of regulatory deadline adherence, certification backlog resolution, and diaspora channel scaling warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Dong Quai Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Moringa Products Market
Specialty Foods
Maple Syrup Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Foie Gras Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Cat Food Flavors Market